
 Commercial Kitchen Knife Market | 2026-2036
Commercial Kitchen Knife Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Kitchen Knife Market Insights
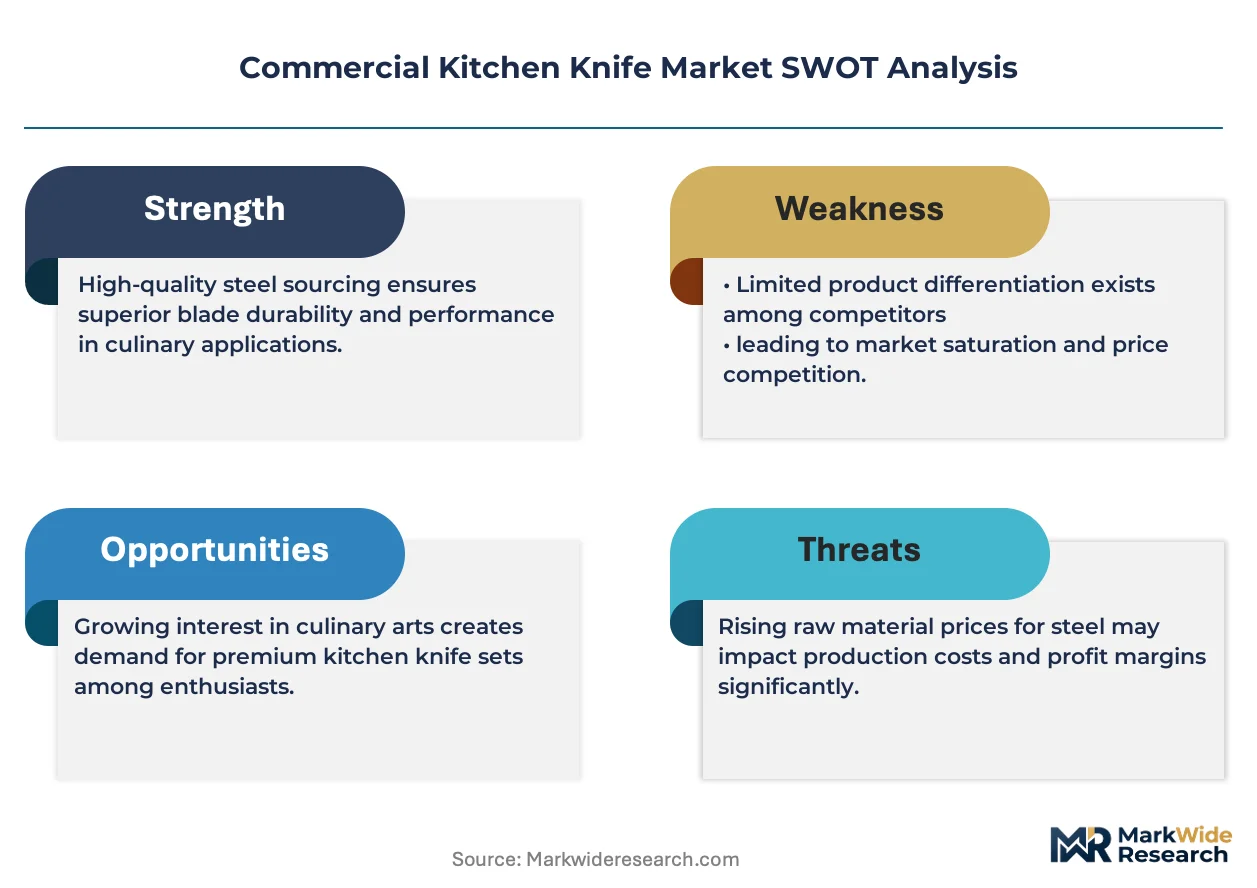
NSF/ANSI Standard 169 for special purpose food equipment and listing is reorganizing which manufacturers qualify for institutional supply contracts in North America. Wüsthof anchors its position through captive forging operations in Solingen, Germany, sustaining full control over blade hardening protocols. Victorinox AG leverages its Swiss Army brand equity to compete across both professional kitchens and culinary school channels, while Kai Corporation specializes in layered Damascus steel construction for premium restaurant accounts in Japan and export markets.
Commercial kitchen knives are precision cutting instruments manufactured from alloyed or layered steels hardened to specific Rockwell C ratings, designed for repetitive food preparation in high-volume foodservice environments. Chef knives dominate volume throughput in restaurant back-of-house operations, while Damascus steel commands the highest margin pools among material segments due to artisan labor intensity and limited batch production. Ceramic blades are displacing steel in specific catering applications where weight reduction and corrosion resistance outweigh edge durability requirements.
FDA food contact substance regulations and NSF International equipment sanitation standards govern blade materials and handle compositions in the United States, while the EU Framework Regulation EC 1935/2004 shapes migration limits for materials contacting food across European commercial kitchens. Japan's Ministry of Economy, Trade and Industry (METI) supports traditional cutlery clusters through regional craft promotion frameworks that preserve artisan forging techniques. Stakeholders must monitor how evolving food safety audits and sustainability disclosure requirements in the EU and North America will reshape supplier qualification timelines and material substitution decisions.
Market Dynamics
NSF International certification tightening across North American institutional foodservice is forcing manufacturers to requalify blade materials and handle compositions, compressing supplier margins while locking out uncertified competitors from hotel and hospital procurement channels.
Growth Catalysts
- Fine-dining expansion:Hotel chains and upscale restaurant groups are standardizing on professional-grade cutlery across properties, creating pull-through demand for forged alloy blades.
- NSF/ANSI Standard 169:Reorganized equipment listing requirements in the United States are disqualifying non-compliant suppliers from institutional contracts.
- Solingen craft heritage:German forging clusters sustain premium positioning through controlled hardening protocols that command price premiums in export markets.
Market Restraints
- Alloy steel cost volatility:Chromium and vanadium price swings compress margin predictability for forged blade manufacturers.
- Artisan labor scarcity:Damascus steel production depends on master forgers concentrated in Seki, Japan, creating batch-size constraints.
- Ceramic substitution threat:Lightweight catering applications are migrating to zirconium dioxide blades where edge durability is secondary.
Strategic Opportunities
- EU sustainability disclosure:CSRD reporting requirements favor suppliers with traceable supply chains and carbon-accounted production.
- Culinary school channel:Vocational training institutions represent underpenetrated volume accounts for entry-professional knife sets.
- Layered steel convergence:Hybrid manufacturing combining traditional folding with precision grinding is opening mid-premium price bands.
Industry Challenges
- Certification timeline compression:NSF requalification cycles are shortening, forcing R&D teams to parallel-track material testing.
- Forge-to-finish integration:Captive heat-treatment capacity requires capital deployment that smaller specialists cannot match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Kitchen Knife Market |
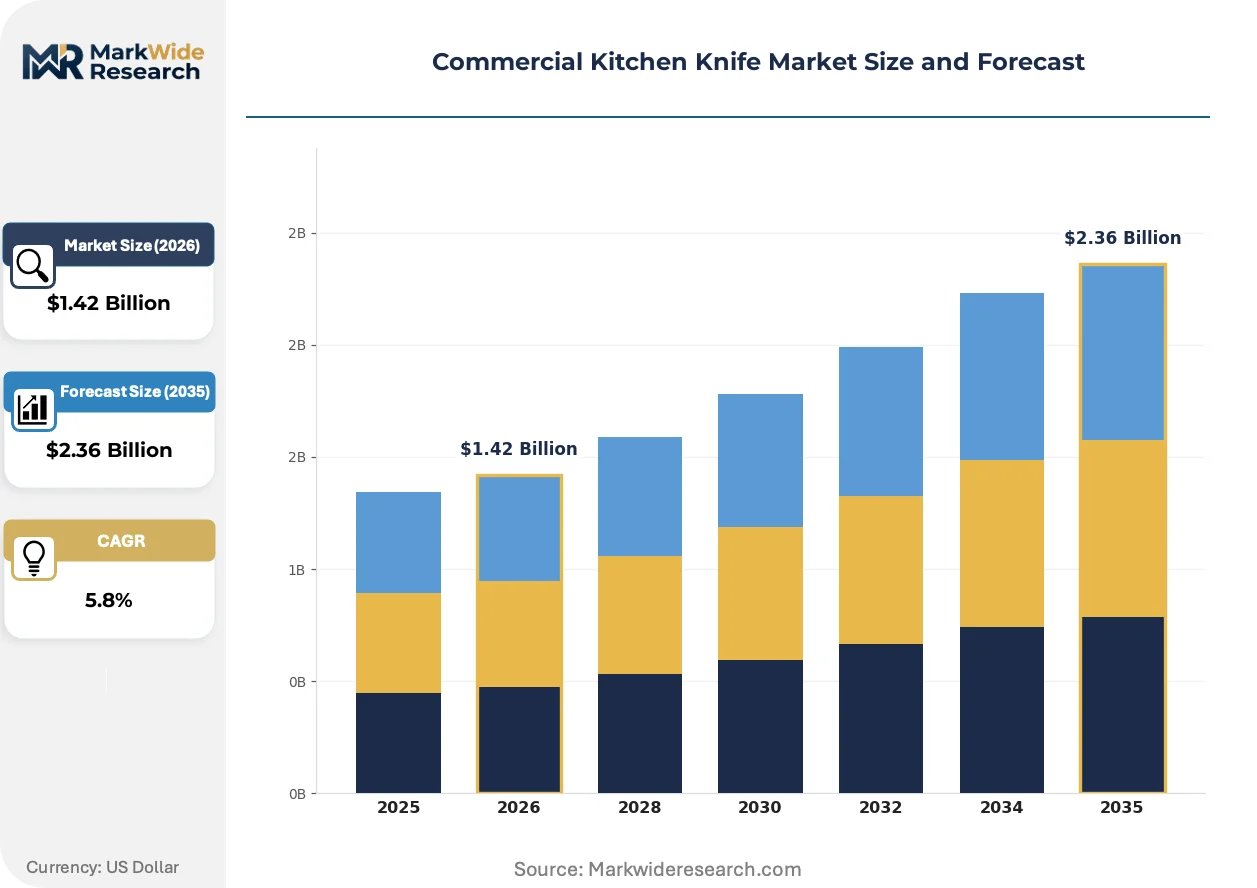
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Knife Type: Chef Knife, Paring Knife, Bread Knife, Santoku Knife Material: Stainless Steel, Carbon Steel, Ceramic, Damascus Steel Application: Restaurants, Catering Services, Home Cooking, Culinary Schools End User: Professional Chefs, Home Cooks, Culinary Institutions, Food Preparers |
| Companies Covered | Groupe SEB, Victorinox AG, Wüsthof, Kai Corporation, Yoshida Metal Industry Co. Ltd., Friedr. Dick GmbH & Co. KG, MAC Knife, Zwilling J. A. Henckels AG, KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Kitchen Knife Market Trends and Innovations
Material science advances and procurement digitization are restructuring how commercial kitchens specify, source, and maintain cutting equipment across institutional and independent operator segments.
High-carbon powder metallurgy steels are supplanting traditional forged alloys in high-volume restaurant environments. Chains with centralized procurement functions are specifying particle metallurgy blades for their superior edge retention and reduced sharpening frequency. This shift is compressing demand for conventional carbon steel in back-of-house operations where labor cost minimization dominates equipment selection.
REACH substance restrictions in the European Union are limiting certain handle polymers and blade coatings in commercial food contact applications. Manufacturers serving EU institutional accounts are reformulating composite handles to meet migration limit requirements under EC 1935/2004. German and French hospital foodservice operators are now requiring full material disclosure documentation as a standard procurement precondition.
Direct sourcing from manufacturer digital platforms is fragmenting traditional distributor relationships in the United States. Independent restaurants and small multi-unit operators are bypassing broadline foodservice distributors to negotiate volume pricing on certified knife sets. This channel shift is most pronounced in metropolitan markets with dense culinary professional networks where peer referral drives specification decisions.
Commercial Kitchen Knife Market Segmentation
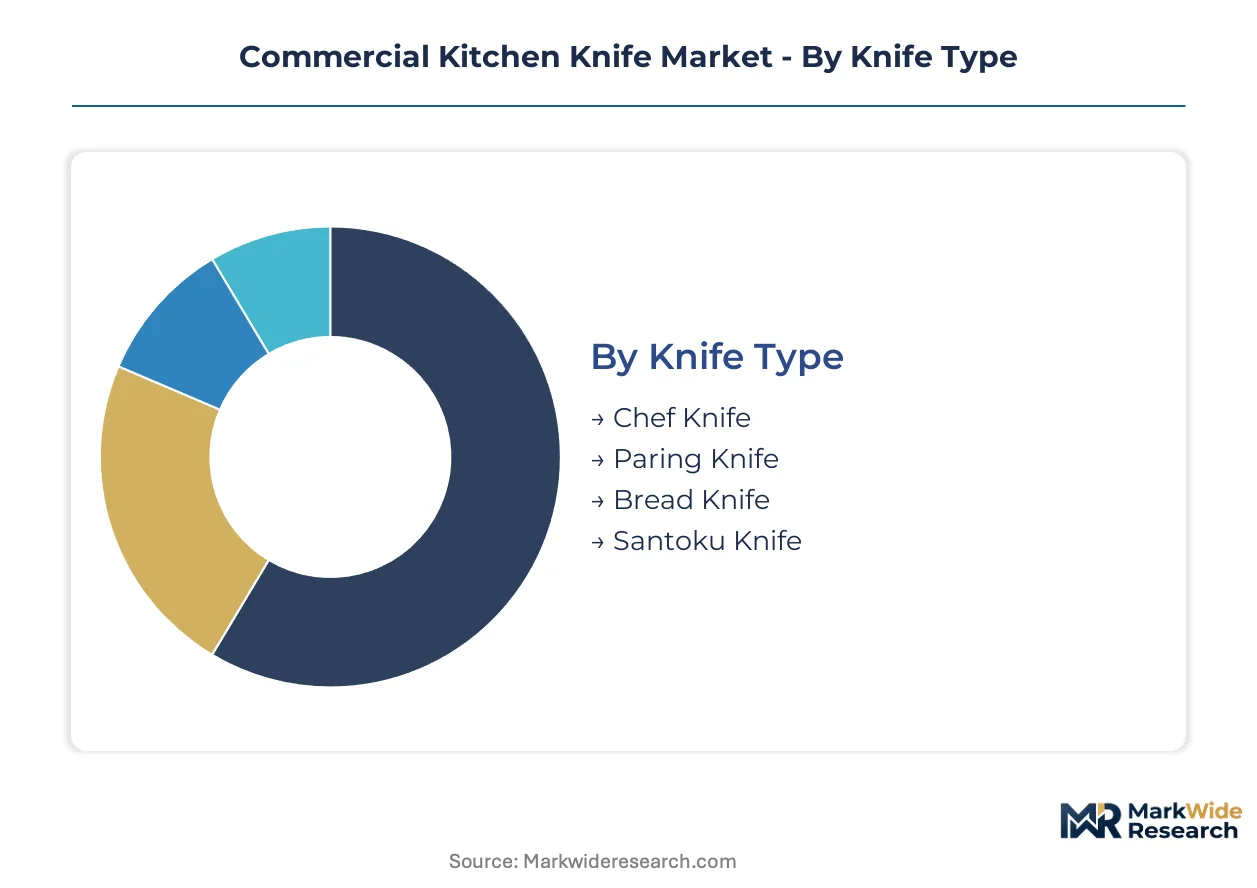
Professional kitchens segment procurement by blade geometry, metallurgy, and operator certification level. Specification decisions cascade from institutional volume buyers to independent restaurants through distributor influence and peer referral networks.
Knife Type:
Ceramic substitution pressure falls most heavily on bread and paring knives where edge durability matters less than weight reduction.
- Chef Knife:The 8-10 inch blade with curved belly dominates back-of-house throughput in full-service restaurants. German and Japanese forging clusters supply hotel chains standardizing across properties.
- Paring Knife:Three-to-four-inch blades for precision tasks face displacement from zirconium dioxide in catering applications. Fine-dining properties still specify forged alloy for hand-feel and balance.
- Bread Knife:Serrated edges with scalloped or pointed profiles cut crust without compression. NSF certification requirements now govern serration geometry for institutional bakery operations.
- Santoku Knife:The sheepsfoot profile with granton edge reduces food adhesion in vegetable prep. Japanese culinary schools drive specification pull-through into North American professional kitchens.
Chef Knife retains volume leadership; Santoku Knife holds the steepest expansion curve.
Material:
Cost tier stratification separates mass-market stainless from artisan Damascus production.
- Stainless Steel:Chromium-alloyed blades resist corrosion in high-moisture kitchen environments. Institutional buyers specify this grade for dishwasher tolerance and reduced maintenance labor.
- Carbon Steel:Higher hardness ratings enable sharper edges but demand active rust prevention. Traditional French brigade kitchens and Japanese izakaya chains specify this for cutting performance.
- Ceramic:Zirconium dioxide blades serve airline catering and remote foodservice where weight reduction outweighs brittleness concerns. Edge chipping limits adoption in high-impact prep stations.
- Damascus Steel:Layered construction with distinctive patterning commands premium positioning through artisan labor intensity. Seki forgers supply limited batches to luxury hotel properties and collector accounts.
Stainless Steel dominates procurement volume; Damascus Steel commands the widest margin spread.
Application:
Customer type concentration shapes specification rigor and replacement frequency.
- Restaurants:Full-service and limited-service operators drive blade throughput with daily sharpening protocols. Independent properties source through direct manufacturer platforms in dense metropolitan markets.
- Catering Services:Mobile and event operators prioritize lightweight equipment for transport efficiency. Ceramic blades gain traction in airline and stadium concession environments.
- Home Cooking:Enthusiast consumers purchase professional-grade cutlery through culinary school referral networks. This channel bridges retail and commercial supply chains.
- Culinary Schools:Vocational institutions represent underpenetrated volume accounts for entry-professional knife sets. Standardized curricula create specification lock-in for graduating cohorts.
Restaurants absorb the highest absolute blade volume; Culinary Schools offer the most concentrated expansion opportunity.
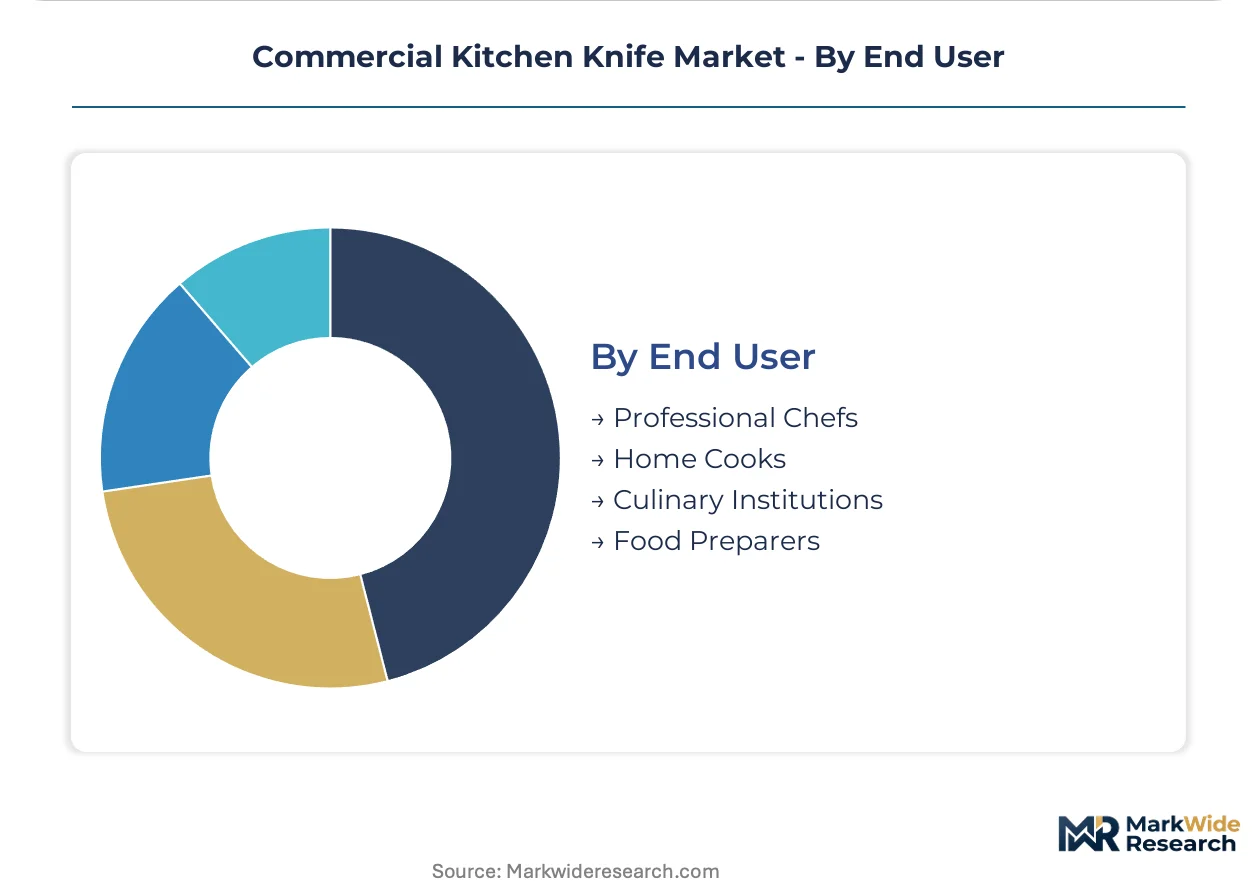
End User:
Skill tier differentiation separates certified professionals from preparatory labor.
- Professional Chefs:Certified operators with formal training specify forged alloy blades by Rockwell hardness and edge geometry. Their procurement decisions influence kitchen-wide equipment standards.
- Home Cooks:Enthusiast segment purchases professional-grade cutlery through peer referral and culinary media. This user class blurs retail-commercial channel boundaries.
- Culinary Institutions:Schools and training programs standardize on NSF-certified sets for student cohorts. Bulk procurement contracts lock suppliers into multi-year relationships.
- Food Preparers:Line cooks and prep staff operate equipment selected by executive leadership. Their usage patterns drive replacement demand and sharpening service contracts.
Professional Chefs anchor premium positioning; Food Preparers generate the highest replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NSF International certification requirements and METI craft promotion frameworks are reorganizing procurement channels across the United States, Germany, and Japan. These regulatory and industrial policy drivers concentrate demand in established forging clusters while compressing margins for non-compliant suppliers.
United States
Fine-dining restaurant groups and hotel chains are standardizing forged alloy specifications across multi-unit properties. FDA food contact substance regulations govern blade materials and handle compositions in institutional foodservice. Solingen-origin imports command price premiums in metropolitan markets with dense culinary professional networks.
Germany
Captive forging operations in Solingen sustain full control over blade hardening protocols for export markets. REACH substance restrictions limit certain handle polymers in commercial food contact applications. The Wüsthof facility exemplifies integrated heat-treatment capacity that smaller specialists cannot match.
Japan
Traditional cutlery clusters in Seki preserve artisan forging techniques through METI regional craft promotion frameworks. Damascus steel production depends on master forgers creating batch-size constraints for luxury hotel accounts. Kai Corporation specializes in layered steel construction for premium restaurant channels.
France
Hospital foodservice operators now require full material disclosure documentation as standard procurement precondition. EU Framework Regulation EC 1935/2004 shapes migration limits for materials contacting food across commercial kitchens. Traditional French brigade kitchens specify carbon steel for cutting performance despite active rust prevention requirements.
Switzerland
Victorinox AG leverages Swiss Army brand equity to compete across professional kitchens and culinary school channels. Swissmedic standards for medical-adjacent foodservice equipment create additional certification layers for institutional suppliers. The company anchors mid-premium positioning through vocational training institution relationships.
Commercial Kitchen Knife Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and price positioning. The vendor base clusters around three structural tiers: integrated forging houses with captive heat-treatment capacity, brand-licensing operators sourcing from contract manufacturers, and regional artisan workshops serving collector accounts. Strategic differentiation concentrates on NSF/ANSI Standard 169 qualification status and forge-to-finish integration depth. M&A activity targets culinary school distribution networks while capacity expansion focuses on powder metallurgy blade production.
Within the integrated forging tier, Wüsthof and Zwilling J. A. Henckels AG represent German-origin manufacturers with Solingen-based operations. Victorinox AG occupies a distinct position leveraging Swiss brand equity across institutional and educational channels. Among Japanese specialists, Kai Corporation exemplifies the layered steel construction archetype serving premium export markets. These three anchors illustrate how geographic craft heritage translates into procurement channel access.
| Leading Market Players |
|---|
| Groupe SEB |
| Victorinox AG |
| Wüsthof |
| Kai Corporation |
| Yoshida Metal Industry Co. Ltd. |
| Friedr. Dick GmbH & Co. KG |
| MAC Knife |
| Zwilling J. A. Henckels AG |
| KYOCERA Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive heat-treatment capacity in Solingen and Seki anchors price floors by locking out smaller competitors lacking forge-to-finish integration. Scale economies at Wüsthof and Zwilling compress unit costs while NSF certification requirements create tiered entry barriers that stratify pricing power across institutional and independent buyer segments.
Pricing Analysis
Certification level (NSF/ANSI Standard 169) creates the primary spread between qualified institutional suppliers and uncertified competitors. Three-tier pricing structure across premium forged alloy, mid-grade stainless, and economy ceramic separates hotel chains from independent restaurants from catering operators. Pricing pressure stems from alloy steel cost volatility as chromium and vanadium price swings compress margin predictability. Independent restaurants exhibit highest price sensitivity due to direct manufacturer platform sourcing, while luxury hotel properties show lowest sensitivity given artisan Damascus specification requirements.
Supply Chain Analysis
Master forger scarcity in Seki constrains batch sizes for layered Damascus production destined for luxury hospitality accounts. Supply concentrates in Germany, Japan, and the United States where craft heritage and regulatory density sustain premium positioning. Raw material dependencies include chromium-alloyed steel stock, zirconium dioxide ceramic feedstock, and high-carbon powder metallurgy inputs. Single-source vulnerability runs through Seki artisan clusters where aging master forgers face limited apprentice pipeline. Distribution runs through broadline foodservice distributors for institutional accounts and direct manufacturer platforms for independent metropolitan operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized procurement functions at hotel chains and culinary institutions, fragmenting traditional distributor relationships and compressing supplier margins through volume concentration.
For Market Incumbents: Shield market position by deepening captive forging capacity in Solingen or Seki to control hardening protocols and lock out contract manufacturers. Prioritize NSF requalification investment to maintain institutional channel access as certification cycles compress. Defend against ceramic substitution by emphasizing edge retention metrics in high-volume restaurant environments where labor cost minimization dominates equipment selection.
For New Entrants and Emerging Players: NSF fast-track certification programs offer the most penetrable entry vector for securing initial institutional contracts. Target culinary school channels where standardized curricula create specification lock-in for graduating cohorts and multi-year bulk procurement relationships. Pursue hybrid manufacturing approaches combining traditional folding with precision grinding to open mid-premium price bands between artisan Damascus and mass stainless production.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sharpening service contracts and replacement blade programs tied to initial knife set sales. Long-term viability favors integrated forging houses with heat-treatment capacity over brand-licensing operators dependent on contract manufacturers. Monitor culinary school distribution network acquisitions as inflection indicators for specification pull-through potential into professional kitchen channels.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Fast-Track | Accelerates institutional contract eligibility under tightening ANSI Standard 169 requirements. |
| Culinary School Distribution Partnership | Locks in specification pull-through from graduating cohorts entering professional kitchens. |
| Powder Metallurgy Capacity Expansion | Captures chain restaurant demand for superior edge retention and reduced sharpening frequency. |
| Direct Manufacturer Platform Launch | Bypasses broadline distributors to capture independent restaurant volume in dense metropolitan markets. |
| Hybrid Manufacturing Integration | Combines traditional folding with precision grinding to open mid-premium price positioning. |
Research Methodology
A spread of perspectives from executive chefs, institutional procurement officers, culinary school administrators, and forged blade manufacturers converged on the working assumptions underlying demand forecasts. Primary interviews with foodservice equipment distributors and NSF certification specialists were cross-referenced against secondary validation from FDA food contact substance filings, EU Framework Regulation EC 1935/2004 migration limit documentation, and METI regional craft promotion frameworks. Bottom-up triangulation across knife type, material grade, and application segments was reconciled with top-down value chain analysis.
Segmentation dimensions modeled include blade geometry category, metallurgy tier, operator certification level, and geographic regulatory cluster across the projection horizon. CAGRs were derived from volume-throughput analysis in restaurant back-of-house operations and replacement frequency patterns by end-user skill tier. Industry-specific forecast inputs incorporated alloy steel price volatility indices and artisan labor availability metrics from Seki forging clusters.
Decision-makers should treat outputs as directional under assumptions of stable NSF certification timelines and sustained fine-dining expansion; material deviation in regulatory requalification cycles or ceramic substitution rates would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance restrictions and CSRD sustainability disclosure requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Ice Maker Market