
 Protein Packed Foods Market | 2026-2036
Protein Packed Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Packed Foods Market Analytics
FDA protein labeling substantiation rules is repositioning the cost-of-entry calculus for new entrants, forcing reformulation investments and third-party testing commitments. Abbott Laboratories leverages its clinical nutrition heritage to sustain premium positioning in medical and sports channels. Nestle SA anchors its portfolio through deep retail distribution and mainstream brand recognition. PepsiCo competes via snack-format innovation that bridges indulgence and functional nutrition.
Protein packed foods are formulated products delivering elevated amino acid density per serving, typically achieving twenty grams or more through concentrated dairy, plant, or animal isolates, and are manufactured via extrusion, cold-pressing, or spray-drying to preserve bioavailability for muscle protein synthesis and satiety applications. Protein powder retains the largest revenue pool due to gym-channel loyalty and bulk purchasing economics, while ready-to-eat meals represent the fastest-growing format as refrigerated supply chains expand and time-compressed consumers prioritize convenience over preparation. Pea protein within ingredient source segmentation is gaining formulation share as allergen-free positioning and sustainability narratives displace soy in clean-label portfolios.
FDA nutrition labeling requirements, USDA organic certification standards, and FTC advertising substantiation guidelines collectively govern protein content claims, manufacturing sanitation, and marketing representations, with compliance costs rising as enforcement actions against inflated protein disclosures intensify. The EU Green Deal's farm-to-fork sustainability targets and EFSA novel food authorizations for alternative proteins are reshaping European import and formulation strategies. Stakeholders must monitor evolving regulatory divergence between jurisdictions to avoid stranded inventory and reformulation cycles that erode margin.
Market Dynamics
FDA protein labeling substantiation requirements are compressing formulation cycles and elevating third-party testing costs, forcing manufacturers to revalidate amino acid density claims or risk enforcement action that strands inventory.
Growth Catalysts
- Fitness culture maturation:Athletes and recreational lifters in the United States drive repeat purchase velocity through gym-channel loyalty and subscription replenishment models.
- EU Green Deal farm-to-fork targets:Sustainability-aligned procurement mandates from European retailers accelerate plant-protein formulation investments and clean-label repositioning.
- Extrusion technology advances:High-moisture extrusion systems improve meat-analogue texture fidelity, expanding ready-to-eat meal adoption among time-compressed consumers.
Market Restraints
- Pea protein input volatility:Concentrated sourcing from Canadian and French growers exposes margins to crop yield fluctuations and rail logistics bottlenecks.
- Allergen cross-contamination liability:Shared dairy-soy processing infrastructure creates FDA recall exposure that limits contract manufacturing options for emerging brands.
- Technical bioavailability ceilings:Plant-protein digestibility scores lag whey isolates, constraining medical nutrition applications where PDCAAS thresholds govern reimbursement.
Strategic Opportunities
- India functional food underpenetration:Rising disposable incomes and FSSAI regulatory clarity create first-mover advantage for shelf-stable protein formats in tier-two cities.
- Direct-to-consumer refrigerated delivery:Cold-chain logistics startups enable ready-to-eat meal subscription models that bypass conventional retail slotting fees.
- USDA BioPreferred procurement mandates:Federal institutional purchasing preferences for bio-based ingredients open volume contracts for sustainable protein isolates.
Industry Challenges
- Food technologist talent scarcity:Formulation chemists with dual expertise in protein chemistry and sensory science command premium compensation that strains R&D budgets.
- Novel food EFSA authorization timelines:Alternative protein ingredients face 18-24 month safety assessment queues that delay European market entry and consume regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Packed Foods Market |
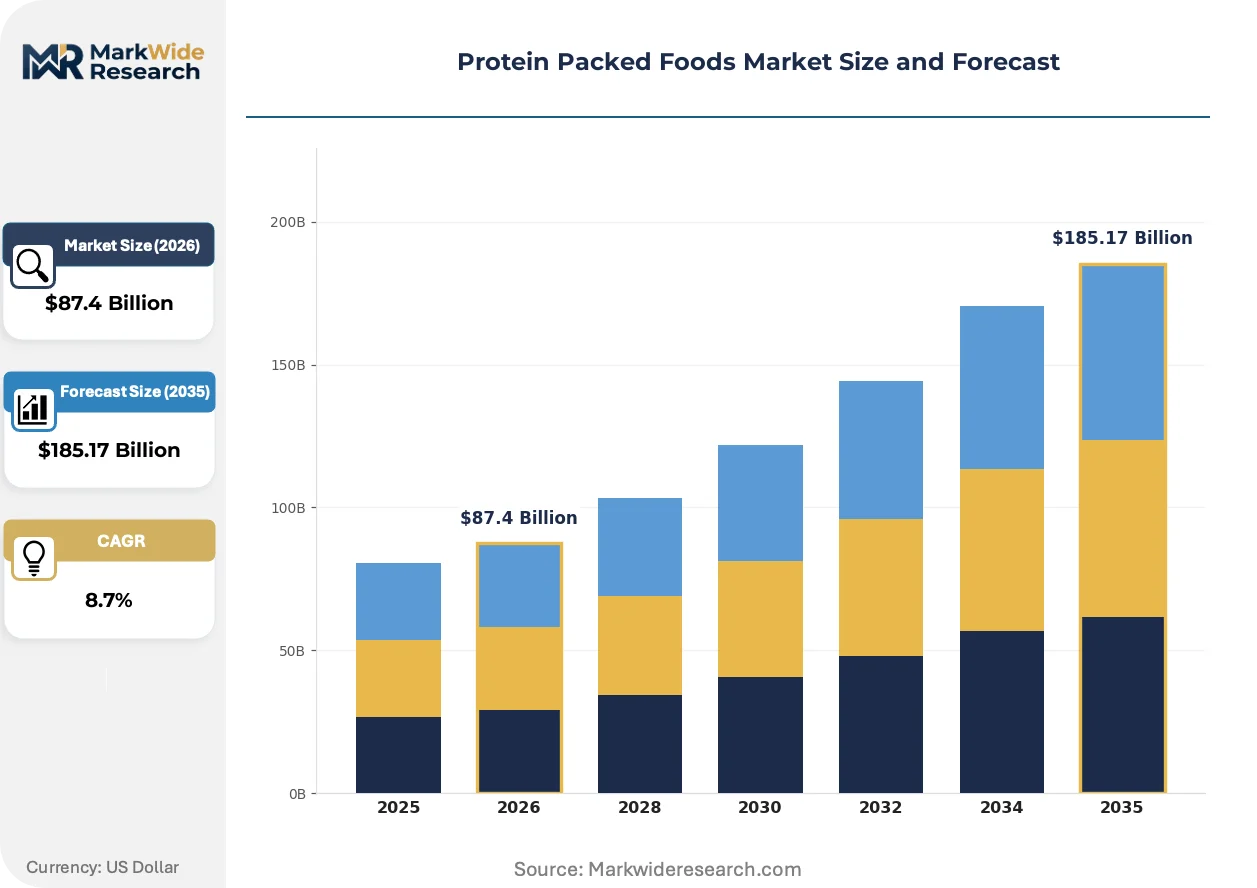
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Protein Powder, Ready-to-Eat Meals, Protein Snacks Ingredient Source: Whey, Casein, Soy, Pea Formulation: High Protein, Low Carb, Gluten-Free, Vegan Packaging Type: Bags, Tubs, Pouches, Boxes |
| Companies Covered | Abbott Laboratories, Chobani Global Holdings LLC, Danone SA, General Mills Inc, Nestle SA, PepsiCo Inc, Tyson Foods Inc, Hormel Foods Corp, Kellogg Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Packed Foods Market Evolving Landscape
Precision fermentation and cellular agriculture are converging with conventional extrusion methods, blurring boundaries between biotechnology and food manufacturing while rewriting protein sourcing economics.
Precision fermentation-derived whey proteins are converging with traditional dairy supply chains as Perfect Day and competitors achieve cost parity with commodity isolates. Sports nutrition brands in the United States and Germany are reformulating powder SKUs to incorporate these ingredients, compressing the premium positioning window for conventional suppliers.
EFSA novel food authorizations for alternative proteins are lengthening pre-market approval timelines, forcing European importers to maintain dual formulation inventories. Manufacturers serving Germany, France, and the Netherlands are prioritizing ingredients with existing safety dossiers to avoid stranded batch risk.
Time-compressed professionals are consolidating protein intake occasions into single ready-to-eat meals rather than discrete shakes and bars. This behavior shift concentrates demand within refrigerated retail and direct-to-subscription channels, most visible in United States metropolitan markets where cold-chain infrastructure supports same-day delivery promises.
Protein Packed Foods Market Segmentation
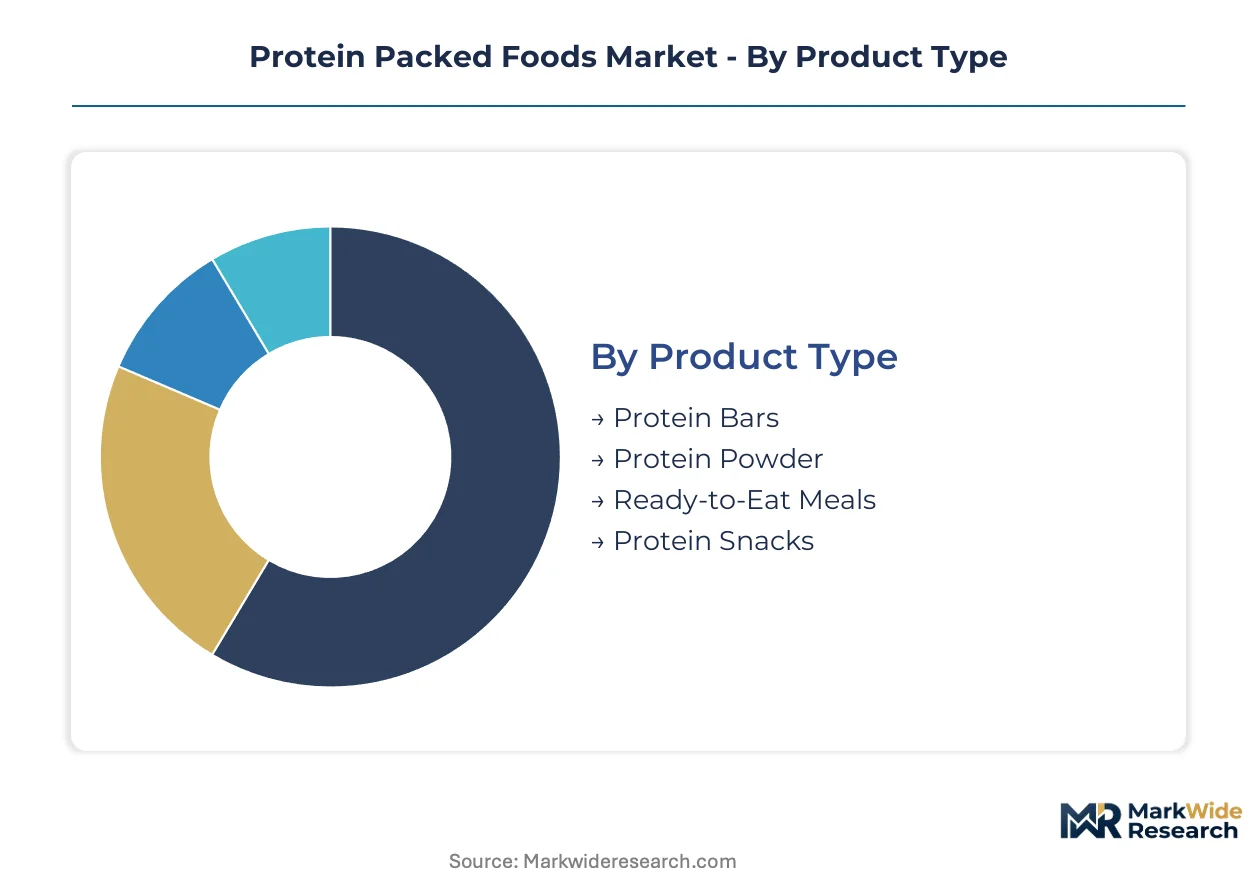
Protein packed foods demand fragments across consumption occasions, ingredient provenance, and dietary compliance requirements. Manufacturers must align portfolio architecture with distinct technical specifications and channel economics that vary dramatically by segment.
Product Type:
Standalone formats dominate gym-channel replenishment cycles, while embedded meal solutions integrate protein delivery into complete nutrition occasions.
- Protein Powder:Concentrated isolates and concentrates deliver 20-30g amino acid density per serving through spray-dried or instantized processing. Gym-channel loyalty in the United States sustains bulk purchasing economics and subscription replenishment velocity. FDA labeling substantiation requirements compress margin as third-party testing costs escalate.
- Ready-to-Eat Meals:Refrigerated protein-dense complete meals leverage high-moisture extrusion and sous-vide thermal processing to preserve texture. Metropolitan cold-chain expansion in the United States enables same-day delivery promises that bypass conventional retail slotting fees. Time-compressed professionals consolidate intake occasions into single convenience-driven purchases.
- Protein Bars:Cold-pressed or extruded formats balance shelf stability with chew texture through hydrocolloid binding systems.
- Protein Snacks:Puffed, baked, or fried formats bridge indulgence positioning with functional nutrition claims.
Volume placements concentrate in Protein Powder; the faster expansion belongs to Ready-to-Eat Meals.
Ingredient Source:
Cost tiers separate commodity dairy isolates from premium-positioned plant and specialty animal proteins with differentiated sustainability narratives.
- Whey:Acid and sweet whey isolates achieve PDCAAS scores of 1.0 with rapid leucine kinetics optimized for muscle protein synthesis. Sports nutrition applications in Germany and the United States demand batch-level amino acid profiling. Precision fermentation alternatives from Perfect Day and competitors compress premium positioning windows.
- Pea:Yellow split pea isolates deliver allergen-free positioning with carbon footprint advantages over dairy. European retailers under EU Green Deal procurement mandates accelerate clean-label reformulation away from soy. Canadian and French concentrated sourcing exposes margins to crop yield volatility.
- Casein:Micellar and calcium caseinates provide sustained amino acid release through coagulated gastric emptying kinetics.
- Soy:Defatted soy flour and isolate maintain cost leadership despite clean-label displacement pressures.
Volume placements concentrate in Whey; Pea is climbing the fastest among alternative sources.
Formulation:
Application requirements dictate whether protein density serves as the primary claim or coexists with secondary dietary compliance positioning.
- High Protein:Formulations achieving 20g+ per serving through isolate concentration or extrusion density enhancement. Medical nutrition channels in the United States require PDCAAS threshold documentation for reimbursement eligibility. FDA substantiation rules elevate third-party amino acid testing costs.
- Vegan:Plant-protein combinations address leucine threshold limitations through pea-rice or pea-fava blending strategies. EFSA novel food queues delay European market entry for emerging alternative proteins. Sustainability-aligned consumers in Germany and Netherlands pay formulation premiums.
- Low Carb:Ketogenic-compliant formats replace maltodextrin carriers with fiber-based bulking agents.
- Gluten-Free:Certification requires dedicated extrusion lines and ELISA testing protocols to prevent cross-contamination liability.
Volume placements concentrate in High Protein; Vegan formulations are gaining share fastest.
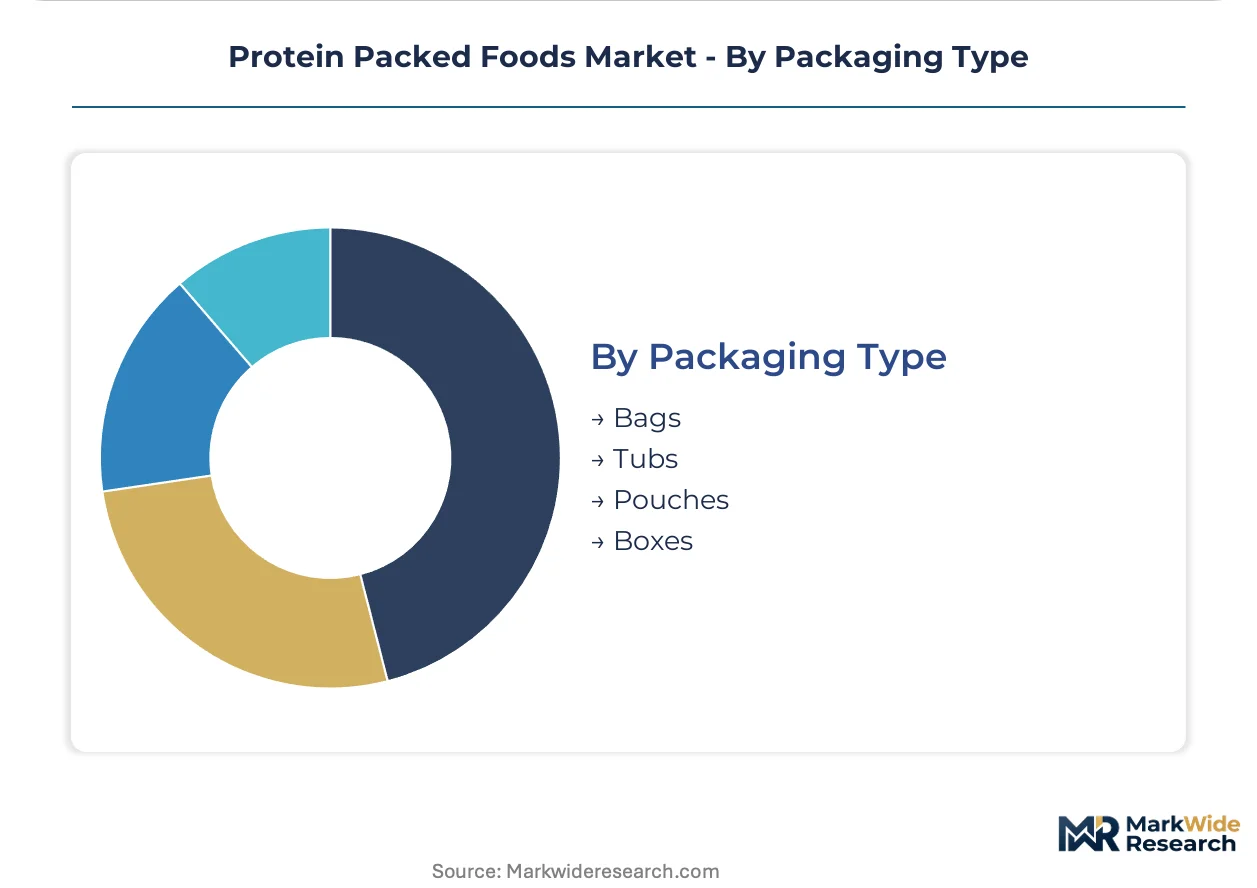
Packaging Type:
Customer type and purchase occasion determine whether bulk economy or single-serve convenience drives format selection.
- Tubs:Rigid polyethylene or polypropylene containers protect powder integrity through moisture-barrier closures and desiccant integration. Home-use replenishment in the United States favors 2-5lb economy sizes with scoop nesting features. E-commerce shipping requirements drive wall-thickness specifications.
- Pouches:Flexible multilayer structures with resealable zippers and degassing valves enable single-serve portability. Direct-to-consumer subscription models in metropolitan United States markets reduce per-unit shipping cube. Stand-up formats command retail shelf presence.
- Bags:Gusseted polyethylene formats serve foodservice and bulk ingredient channels with tear-notch dispensing.
- Boxes:Paperboard secondary packaging organizes multi-unit retail displays and subscription assortment curation.
Volume placements concentrate in Tubs; Pouches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones and biotechnology corridors concentrate protein manufacturing capacity. Special economic zones in Singapore and Shenzhen offer tax holidays that attract precision fermentation startups. Regional demand patterns diverge sharply between gym-channel powder markets and refrigerated meal adoption.
United States
Fitness culture and sports nutrition retail infrastructure sustain protein powder volume leadership. FDA nutrition labeling substantiation requirements force manufacturers to maintain third-party amino acid testing protocols. Metropolitan cold-chain expansion in New York and Los Angeles enables same-day delivery models for ready-to-eat meals.
Germany
Sustainability-aligned consumers accelerate plant-protein adoption through retail procurement mandates. EFSA novel food authorization queues delay market entry for precision fermentation ingredients. The Cologne-Düsseldorf corridor hosts formulation R&D clusters serving Central European distribution networks.
China
Rising middle-class protein consumption drives functional food category expansion. SAMR food safety registration requirements govern imported protein isolate labeling and claims. Yangtze River Delta manufacturing hubs concentrate extrusion equipment capacity for meat-analogue production.
India
Tier-two city disposable income growth creates first-mover opportunity for shelf-stable formats. FSSAI regulatory clarity on protein content claims reduces market entry uncertainty for foreign brands. Maharashtra and Gujarat host contract manufacturing infrastructure for domestic and export markets.
Brazil
Soy protein isolate production leverages agricultural commodity advantages for cost-competitive supply. ANVISA nutrition labeling requirements align with Mercosur standards for regional export eligibility. São Paulo state concentrates food processing capacity serving Latin American distribution channels.
Protein Packed Foods Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base stratifies between multinational nutrition portfolios and emerging biotechnology-enabled challengers. Three archetypes dominate: clinical nutrition heritage players, snack-format innovators, and precision fermentation disruptors. Capacity expansion and strategic partnerships represent the primary competitive moves as firms secure alternative protein supply agreements.
Within the clinical nutrition tier, Abbott Laboratories occupies a position exemplifying heritage-based premium positioning. Nestle SA and PepsiCo anchor the mass-market and snack-format vectors respectively, representing divergent approaches to protein delivery architecture. These three entities collectively illustrate how scale, brand equity, and channel access determine competitive posture.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Chobani Global Holdings LLC |
| Danone SA |
| General Mills Inc |
| Nestle SA |
| PepsiCo Inc |
| Tyson Foods Inc |
| Hormel Foods Corp |
| Kellogg Co. |
| Others |
Value Network & Pricing Analysis
EU Green Deal farm-to-fork sustainability targets gate qualified supply and premium-tier pricing access, as retailers demand carbon-footprint documentation that only vertically integrated or certified-clean-label suppliers can satisfy. Buyers lacking ESG-compliant sourcing credentials face exclusion from procurement shortlists, compressing their pricing power into commodity tiers.
Pricing Analysis
Short lead-time premiums reward suppliers holding finished-goods inventory near metropolitan cold-chain hubs, while spot-market powder lots trade at discounts reflecting amino acid retest requirements. Three-tier pricing structure across premium, standard, and economy levels separates precision-fermentation whey from commodity isolates from blended plant concentrates. Price differentiation hinges on third-party PDCAAS certification and FDA substantiation documentation. Cost compression in economy-tier powder is intensifying because Canadian pea protein harvest volatility forces spot purchasing. Subscription-model fitness enthusiasts show lowest price sensitivity; foodservice bulk buyers exhibit highest.
Supply Chain Analysis
Pea protein isolate supply rests on Canadian prairie growers and French Rhône Valley processors, with whey concentrate production anchored in Wisconsin and New Zealand dairy cooperatives. Raw material flows draw from yellow split peas, fluid milk, and precision-fermentation bioreactor output. Single-source vulnerability concentrates in Canadian rail corridors connecting prairie elevators to Vancouver port terminals. Distribution runs through gym-channel direct replenishment, refrigerated DTC subscription platforms, and mass retail shelf-stable placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA protein labeling substantiation requirements erect a barrier-to-entry moat that rewards compliant incumbents with enforcement-protected shelf space while stranding underinvested challengers with reformulation costs.
For Market Incumbents: Hedge against precision-fermentation displacement by securing exclusive offtake agreements with Perfect Day and competitors before cost parity erodes premium positioning. Acquire Canadian pea protein processing capacity to capture margin from crop yield volatility. Vertical integration into third-party amino acid testing laboratories defends against FDA enforcement exposure that strands non-compliant inventory. For New Entrants and Emerging Players: Time-compressed professionals in United States metropolitan markets represent an underserved buyer archetype demanding ready-to-eat meal subscriptions bypassing retail slotting fees. Target tier-two Indian cities with shelf-stable protein formats ahead of FSSAI regulatory clarity attracting multinational entrants. Lead with direct-to-consumer refrigerated delivery partnerships that conventional brands cannot replicate without channel conflict. For Investors and Strategic Acquirers: EFSA novel food authorization queue lengthening is the leading indicator that European market entry timelines will favor incumbents with existing safety dossiers over biotechnology challengers. Five-to-ten year viability concentrates in formulation houses with dual protein chemistry and sensory science capabilities. Watch for FDA warning letter issuance against inflated protein claims as the signal that enforcement normalization will accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Supply Agreement | Perfect Day partnerships secure cost-competitive whey alternatives before commodity parity erodes margins. |
| Third-Party Testing Laboratory Acquisition | FDA substantiation rules elevate in-house amino acid verification into a competitive moat. |
| Direct-to-Consumer Cold-Chain Launch | Same-day refrigerated delivery bypasses retail slotting fees that burden conventional distribution. |
| Canadian Pea Protein Processing Expansion | Concentrated prairie sourcing exposes margins to rail logistics bottlenecks without captive capacity. |
| EFSA Novel Food Dossier Investment | Existing safety approvals accelerate European market entry ahead of 18-24 month authorization queues. |
Research Methodology
Multi-period observation of gym-channel subscription velocity, refrigerated retail SKU counts, and precision-fermentation cost curves anchored the trend analysis, supplemented by interviews with sports nutrition brand managers, FDA regulatory affairs consultants, cold-chain logistics operators, and plant-protein procurement leads at European retailers. Secondary validation drew from FDA warning letter databases, EFSA novel food submission logs, USDA organic certification records, and customs trade data for pea protein isolate imports. Bottom-up SKU-level revenue modeling triangulated against top-down category expenditure estimates from household panel data.
Segment-weighting across product type, ingredient source, formulation compliance, and packaging format shaped the analytical framework over the projection horizon. CAGRs were derived from category velocity trends and penetration ceiling analysis. Modeled inputs included PDCAAS threshold documentation rates for medical nutrition reimbursement eligibility, metropolitan cold-chain density indices, and EU Green Deal procurement mandate adoption curves among German and Dutch retailers.
Revisions become necessary when FDA enforcement actions against protein content claims accelerate, precision-fermentation production costs fall below commodity whey benchmarks, or Canadian pea protein harvest failures trigger sustained input price spikes. Forecasts reflect documented assumptions about regulatory stability and consumer occasion consolidation behavior. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Ready Meals Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Morning Goods Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
North America Pasta Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Tortilla Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
United Kingdom Food Spreads Market