
 Fin Fish Market | 2026-2036
Fin Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Fin Fish Market Intelligence
Recirculating aquaculture system technology is reshaping how fin fish are produced at scale, enabling land-based farming that isolates biomass from marine ecosystems. Mowi ASA leverages its integrated feed-to-fork model across Norwegian and Scottish waters to sustain volume leadership in Atlantic salmon. Thai Union Group anchors its position through diversified species portfolios spanning tuna value chains in the Indian and Pacific Oceans. Cooke Aquaculture competes via family-owned vertical integration across Atlantic Canada and Maine, controlling hatchery, sea farm, and processing assets.
Fin fish encompasses teleost species raised or harvested for human consumption, with flesh characterized by myotome muscle structure, protein content typically exceeding eighteen percent, and lipid profiles varying by species and diet. The primary commercial purpose spans direct retail sale, food service preparation, and further processing into value-added products such as fillets, portions, and ready meals. Salmon dominates value generation within the product type dimension due to premium pricing and established brand recognition, while frozen processing methods lead volume throughput by extending shelf life and enabling intercontinental trade. E-commerce distribution channels within the wholesale and retail segments are capturing faster growth as cold-chain logistics improve direct-to-consumer reach for fresh and smoked product lines.
The EU's Common Fisheries Policy and Marine Stewardship Council certification requirements shape market access for wild-caught species across European retail channels. Norway's national seafood regulator and Chile's fisheries oversight body enforce area management rules that constrain production expansion in the two dominant Atlantic salmon jurisdictions. The US Food and Drug Administration and NOAA Fisheries administer import monitoring and hazard analysis protocols that filter which overseas suppliers reach American buyers. Stakeholders must track how land-based aquaculture permitting timelines and energy cost structures determine whether recirculating systems achieve cost parity with conventional sea-cage production.
Market Dynamics
Recirculating aquaculture system (RAS) technology is collapsing the geographic constraints that once tied Atlantic salmon production to Norwegian fjords and Chilean sea lochs, redistributing biomass toward land-based facilities in the US Midwest and continental Europe.
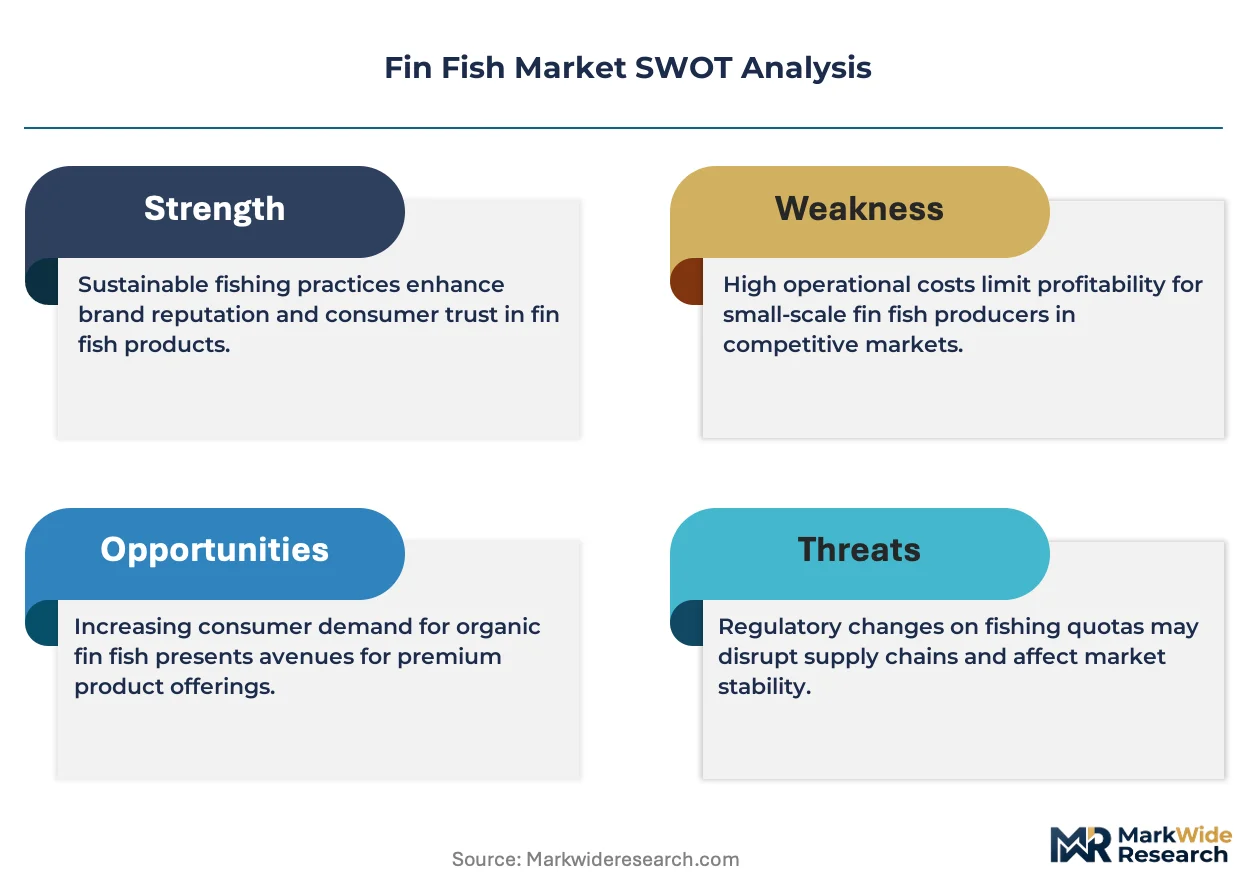
Growth Catalysts
- EU Common Fisheries Policy reform:Tightening wild cod catch quotas redirect food service procurement toward farmed alternatives, expanding contract volumes for RAS operators.
- Marine Stewardship Council certification:Retail chains across Germany and the UK now mandate chain-of-custody documentation, filtering shelf access toward traceable farmed supply.
- Chilled logistics infrastructure:Direct-to-consumer cold-chain networks enable fresh fillet delivery within 24 hours, unlocking urban markets previously served only by frozen product.
Market Restraints
- Smolt supply concentration:Norwegian and Chilean hatcheries control Atlantic salmon juvenile distribution, constraining independent RAS facility stocking schedules.
- Energy cost structure:Land-based recirculating systems require continuous pumping and temperature control, exposing operators to electricity price volatility in European markets.
- Permitting timeline friction:US state-level aquaculture licensing processes extend 18-36 months, delaying facility commissioning relative to conventional sea-cage expansion.
Strategic Opportunities
- US heartland production:Indiana and Ohio offer depleted industrial sites with rail access and wastewater infrastructure suitable for large-scale RAS conversion.
- Carbon accounting integration:EU Green Deal disclosure requirements create premium positioning for operations with verified low-emission feed and energy sourcing.
- Cell-cultured hybridization:Convergence of precision fermentation and traditional aquaculture opens blended product categories combining farmed structure with cultivated lipid profiles.
Industry Challenges
- RAS engineering talent scarcity:Water chemistry specialists and biofilter operators command premium wages, constraining facility staffing at scale.
- Biosecurity protocol complexity:Land-based systems require continuous pathogen monitoring and barrier maintenance, elevating operational overhead versus open-water alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fin Fish Market |
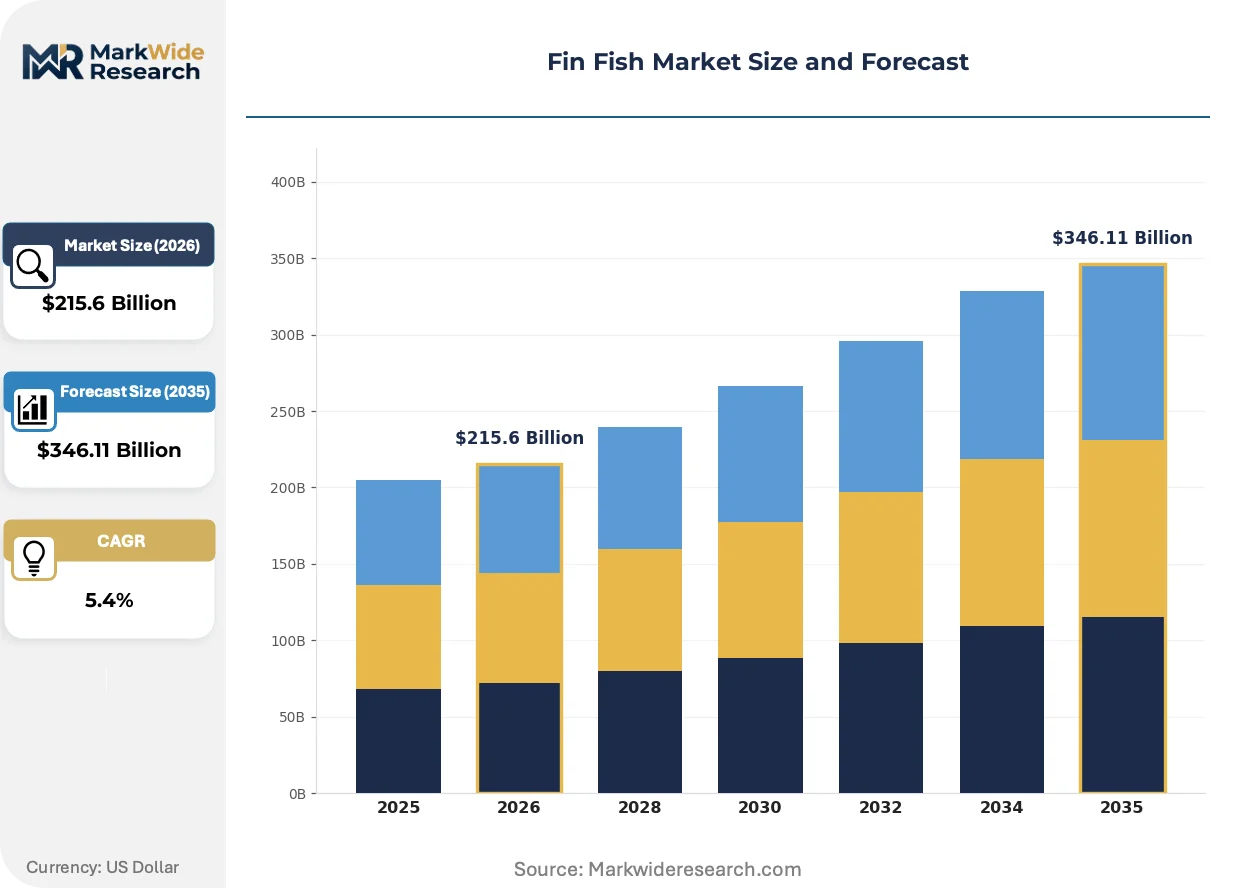
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $346.11 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmon, Tuna, Trout, Cod Distribution Channel: Retail, Wholesale, E-commerce, Food Service Processing Method: Fresh, Frozen, Smoked, Canned Sustainability Certification: MSC, ASC, BAP, Organic |
| Companies Covered | Thai Union Group, Lerøy Seafood Group ASA, Mowi ASA, Maruha Nichiro Corporation, Grieg Seafood ASA, Cermaq Group AS, Cooke Aquaculture, Nissui Corporation, Bakkafrost, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fin Fish Market Strategic Shifts & Innovations
Biomass production is decoupling from coastal geography through engineered closed-loop systems, while regulatory pressure on wild harvests accelerates investment in controlled-environment alternatives.
Single-pass recirculating aquaculture system designs are collapsing the capital cost differential that previously favored sea-cage operations. Food service distributors in the Netherlands and Belgium are commissioning dedicated RAS supply contracts to secure year-round volume consistency. The technology is collapsing seasonal price volatility by enabling harvest scheduling independent of natural photoperiod and temperature cycles.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in industrial refrigeration, forcing processing facilities to retrofit ammonia-based or transcritical CO2 cooling systems. Norwegian exporters face retrofit deadlines that compress capital deployment timelines through 2027. Smoked salmon processors in Poland and Denmark are accelerating equipment replacement to maintain CE-marked market access.
Direct sourcing platforms are disintermediating traditional wholesale auction structures for fresh product. Restaurant groups in London and Paris now contract directly with Scottish and Faroese farms, bypassing Billingsgate and Rungis intermediaries. This pattern is most visible in the premium sashimi-grade segment, where provenance documentation and harvest-to-delivery speed override traditional volume aggregation economics.
Fin Fish Market Segmentation
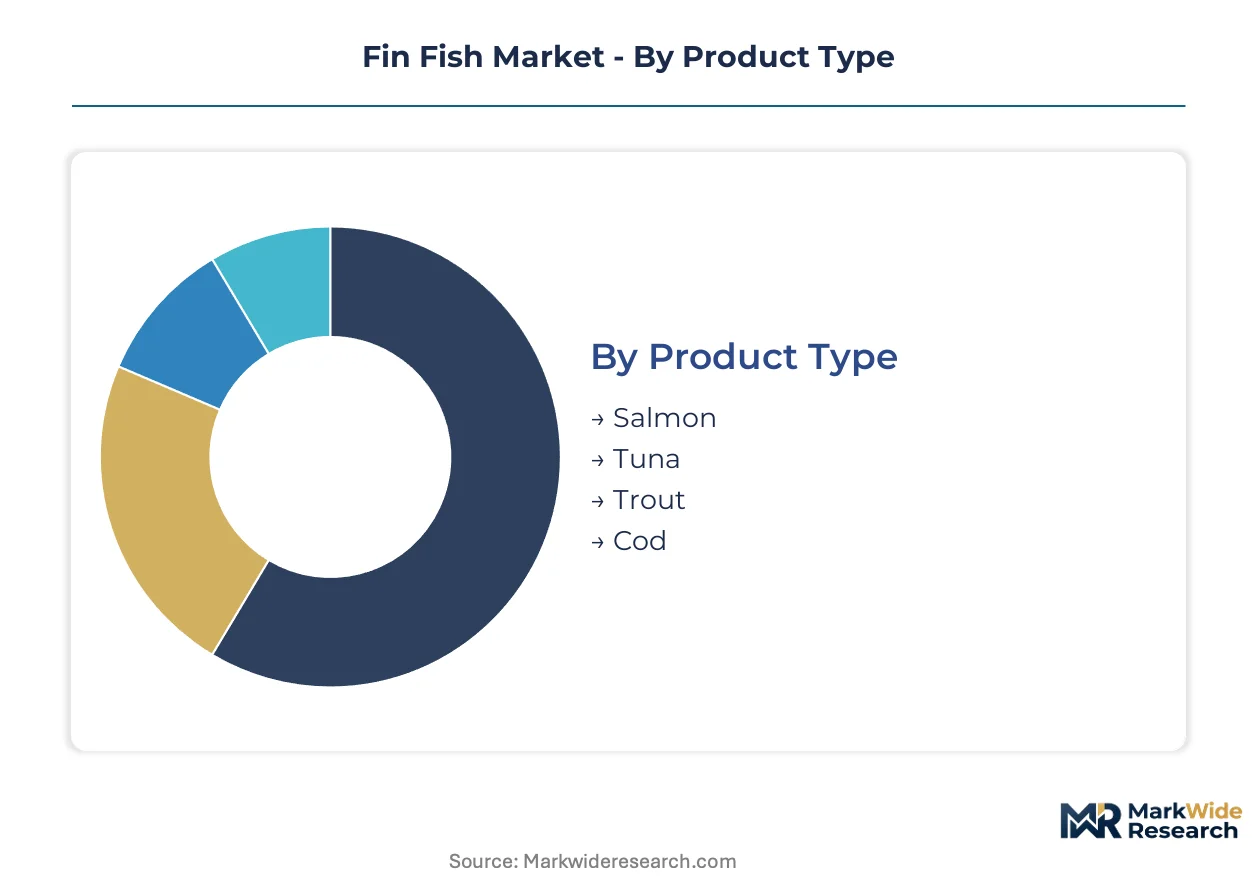
Fin fish segmentation reveals how supply chain configuration and end-use requirements fragment commercial flows across species, channels, and processing formats. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
After-sales intensity in fin fish concentrates on cold-chain maintenance and traceability documentation, with premium species demanding sustained supplier engagement.
- Salmon:Atlantic and Pacific salmon varieties deliver myotome muscle structure with protein content exceeding eighteen percent and omega-3 lipid profiles shaped by feed composition. Norwegian and Chilean farms dominate supply, with RAS technology now penetrating the US Midwest to reduce geographic concentration risk.
- Tuna:Scombridae species including skipjack, yellowfin, and bluefin support sashimi-grade markets and canned commodity segments. Thai Union Group and other processors in the Indian and Pacific Oceans manage vertically integrated tuna value chains from purse-seine capture to retail-ready pouches.
- Trout:Freshwater salmonid production centers on raceway and pond systems across Idaho, North Carolina, and European mountain regions.
- Cod:Gadus morhua and related species face tightening EU Common Fisheries Policy quotas on wild stocks, accelerating substitution toward farmed alternatives and Alaskan pollock.
By volume, cod historically led wild-caught landings. By growth pace, salmon is expanding most quickly through aquaculture volume gains.
Distribution Channel:
Channel selection determines working capital intensity and margin capture, with direct formats compressing intermediary layers.
- Retail:Supermarket chains across Germany and the UK now mandate Marine Stewardship Council chain-of-custody documentation, filtering shelf access toward traceable farmed supply with verified provenance systems.
- Food Service:Restaurant groups in London and Paris contract directly with Scottish and Faroese farms, bypassing traditional wholesale auction structures for premium sashimi-grade segments where harvest-to-delivery speed overrides volume aggregation economics.
- Wholesale:Billingsgate and Rungis intermediaries retain dominance in frozen commodity flows and institutional procurement.
- E-commerce:Direct-to-consumer cold-chain networks enable fresh fillet delivery within 24 hours, unlocking urban markets previously served only by frozen product.
By volume, wholesale channels handle the greatest tonnage. By growth pace, e-commerce is gaining share fastest through improved last-mile refrigeration infrastructure.
Processing Method:
Processing format dictates shelf-life extension, geographic reach, and capital equipment requirements across the value chain.
- Frozen:Blast-freezing and plate-freezing systems extend shelf life to 12-24 months, enabling intercontinental trade from Norwegian and Chilean production zones to Asian and North American markets.
- Fresh:Ice-packed or modified-atmosphere packaged fillets command price premiums in retail and food service segments, requiring continuous temperature control from harvest through consumption.
- Smoked:Traditional and cold-smoking techniques applied to salmon generate value-added products with extended refrigerated shelf life.
- Canned:Retort processing of tuna and salmon creates ambient-stable products for emergency stockpiling and price-sensitive consumption.
By volume, frozen processing leads throughput. By growth pace, fresh formats show steepest expansion trajectory through improved logistics reliability.
Sustainability Certification:
Certification schemes function as market access filters, with retail procurement policies increasingly mandating third-party verification.
- MSC:The Marine Stewardship Council's wild-capture standard governs access to European retail chains, with chain-of-custody documentation now required across German and UK supermarket procurement policies.
- ASC:The Aquaculture Stewardship Council's farmed seafood standard addresses feed sourcing, water quality, and social compliance in salmon and shrimp production.
- BAP:The Global Aquaculture Alliance's Best Aquaculture Practices program covers hatchery, farm, feed mill, and processing plant standards.
- Organic:EU organic aquaculture regulations and USDA National Organic Program standards constrain feed inputs and stocking densities, limiting supply volume and sustaining price premiums.
By volume, conventional uncertified product still dominates. By growth pace, ASC-certified farmed salmon is climbing the fastest through retail procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service distributors in Germany and the UK anchor premium procurement volumes, while RAS technology deployment in the US Midwest and Nordic processing clusters reshape supply geography.
Norway
Atlantic salmon smolt production concentrates along coastal fjord systems, with the national seafood regulator enforcing strict area management rules that constrain expansion. The country's feed-to-fork integrated operators dominate value chain control. Bergen and Stavanger host processing and export infrastructure serving European retail chains.
United States
Restaurant groups in Chicago and New York Metro drive demand for fresh fillet consistency, bypassing traditional wholesale intermediaries through direct farm contracts. FDA and NOAA Fisheries administer import monitoring protocols that filter overseas supplier access. Indiana and Ohio industrial sites with rail access attract RAS facility conversion investment.
Chile
Seafood processors in the Los Lagos and Aysén regions manage vertically integrated Atlantic salmon operations from hatchery through export. The national fisheries oversight body enforces production area restrictions that limit biomass growth. Puerto Montt anchors cold-chain logistics for Asian and North American frozen shipments.
United Kingdom
Scottish salmon farms supply premium sashimi-grade segments to London restaurant groups demanding harvest-to-delivery speed under 24 hours. Marine Stewardship Council chain-of-custody requirements now govern supermarket procurement policies. Shetland and Orkney waters host high-density sea-cage clusters facing biosecurity pressure.
Japan
Sashimi-grade tuna and salmon consumption in Tokyo and Osaka metropolitan areas sustains import dependence on Norwegian and Chilean farmed supply. METI standards govern cold-chain integrity for fresh product distribution. Tsukiji successor market infrastructure in Toyosu handles volume aggregation for domestic wholesale channels.
Fin Fish Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation characterizes Atlantic salmon supply, where feed-to-fork integration dominates value capture. Three archetypes prevail: vertically integrated Norwegian-Chilean giants, diversified Asia-Pacific tuna processors, and emerging RAS pure-plays in North America. Capacity expansion through land-based facility commissioning and backward integration into hatchery assets represent the dominant competitive vectors.
Within the integrated salmon tier, Mowi ASA and Lerøy Seafood Group ASA exemplify Nordic feed-to-fork control spanning Norwegian and Scottish waters. Thai Union Group anchors the diversified species archetype through Indian and Pacific Ocean tuna value chains. Cooke Aquaculture occupies a family-owned vertical integration position across Atlantic Canada and Maine hatchery, sea farm, and processing assets.
| Leading Market Players |
|---|
| Thai Union Group |
| Lerøy Seafood Group ASA |
| Mowi ASA |
| Maruha Nichiro Corporation |
| Grieg Seafood ASA |
| Cermaq Group AS |
| Cooke Aquaculture |
| Nissui Corporation |
| Bakkafrost |
| Others |
Cost & Logistics Intelligence
Smolt supply concentration between Norwegian and Chilean hatcheries determines both the spread between premium fresh and frozen commodity tiers and the geographic shape of Atlantic salmon distribution networks. This single-source dependency for juvenile stock creates pricing power asymmetries that cascade through contract structures and procurement scheduling.
Pricing Analysis
Cost-plus contracts indexed to Norwegian salmon spot prices dominate long-term food service procurement agreements between RAS operators and North American restaurant groups. Three-tier pricing structure across premium sashimi-grade, standard fresh fillet, and frozen commodity levels reflects certification status and harvest-to-delivery speed. Pricing pressure stems from energy cost volatility in European RAS facilities competing against conventional sea-cage production. Quick-service restaurant chains exhibit highest price sensitivity, while premium sushi operators absorb premiums for documented provenance.
Supply Chain Analysis
Tariff exposure between Chile and Asian export markets dominates supply chain risk assessment for frozen Atlantic salmon shipments. Production concentrates in Norway, Chile, and emerging US Midwest RAS facilities. Feed formulation draws from Peruvian fishmeal, Brazilian soy, and Norwegian marine oils. Distribution runs through dedicated cold-chain logistics from Puerto Montt and Bergen to processing hubs in Poland and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fin fish markets reward service-attach revenue streams, with traceability documentation and cold-chain monitoring subscriptions expanding faster than base commodity volume. Certification management and direct-to-consumer logistics represent the fastest-growing recurring-revenue layers.
For Market Incumbents: Build captive smolt supply moats through hatchery asset acquisition in Scotland and Atlantic Canada to insulate stocking schedules from Norwegian-Chilean concentration. Deepen backward integration into feed milling to capture margin from Peruvian fishmeal and Brazilian soy inputs. Defend against RAS pure-plays by securing premium retail shelf space through ASC certification investment ahead of procurement mandate deadlines. For New Entrants and Emerging Players: Pursue white-space RAS development in Indiana and Ohio industrial sites with rail access and existing wastewater infrastructure. Target the US heartland food service segment where harvest-to-delivery speed under 24 hours commands premium positioning unavailable to frozen imports. Establish direct sourcing platforms that disintermediate traditional wholesale auction structures for restaurant group contracts. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors land-based aquaculture pure-plays with permitted sites and operational RAS engineering teams. Long-term viability over the next decade hinges on energy cost structure optimization and smolt supply security. Watch for permitting timeline acceleration in US state-level aquaculture licensing as the inflection signal for scaled capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| RAS Facility Commissioning | Land-based production in Ohio and Indiana collapses geographic dependency on Norwegian fjords. |
| Smolt Supply Agreement | Captive juvenile distribution secures stocking schedules independent of Chilean hatchery concentration. |
| ASC Certification Investment | Retail procurement mandates in Germany and UK filter shelf access toward verified farmed supply. |
| Direct-to-Consumer Cold-Chain Buildout | Last-mile refrigeration infrastructure unlocks urban markets previously served only by frozen product. |
| Feed Mill Backward Integration | In-house production of formulated diets captures margin from Peruvian fishmeal and Brazilian soy volatility. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU Common Fisheries Policy documents, Norwegian seafood regulator area management filings, and Chilean fisheries oversight production data. Primary interviews engaged RAS facility operators, food service procurement directors, cold-chain logistics managers, and marine feed formulation specialists. Secondary validation drew from customs trade records, ASC certification registries, and energy cost disclosures across European processing clusters. Bottom-up facility capacity estimates triangulate against top-down trade flow analysis.
Forecast inputs incorporate species segmentation by salmon, tuna, trout, and cod; processing method differentiation across frozen, fresh, smoked, and canned formats; and distribution channel dynamics spanning retail, food service, wholesale, and e-commerce. CAGRs derive from production volume trajectories, regulatory constraint modeling, and technology adoption curves for recirculating aquaculture systems. Feed cost indices and energy price volatility scenarios inform margin pressure sensitivity across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by RAS pure-plays or accelerated EU quota tightening would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Protein Hydrolysate Market
Seafood
Food Clamshells Market
Seafood
Latin America Salmon Market
Seafood
Seafood Processing Market
Seafood
Crayfish Market
Seafood
China Crustaceans Market
Seafood
Lobster Market
Seafood
Global Shrimp Market
Seafood
Smoked Whiting Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Global White Shrimp Market
Seafood
Wild Pollock Market
Seafood
Canned Tuna Market
Seafood
Octopus Market
Seafood
Sea Bass Market
Seafood
Middle East Seafood Market