
 Wild Pollock Market | 2026-2036
Wild Pollock Market Size, Share, and Industry Trends Forecast 2026-2036
Wild Pollock Market Analysis
Premium fillet pricing is decoupling from commodity surimi values as supply chain investments diverge. Norebo Holding anchors Russian Far East production with fleet modernization and direct quota access. Trident Seafoods sustains Alaska dominance through shore-based processing infrastructure and retail brand strength. American Seafoods Group differentiates with at-sea processing vessels that reduce dock-to-freezer time.
Wild pollock denotes Gadus chalcogrammus, a white-fleshed demersal fish harvested primarily in the North Pacific at depths of 100-400 meters, processed into fillets, surimi, roe, or whole-round products for human and pet consumption. Fillet segments command margin pools in retail and food service channels where portion-controlled, IQF products meet specification buyers. Surimi occupies the highest volume tier but faces margin compression from alternative whitefish substitutes. Frozen foods applications lead absolute demand while pet food represents the fastest-growing outlet as premiumization extends to animal nutrition.
NOAA Fisheries enforces total allowable catch limits under the Magnuson-Stevens Fishery Conservation Act, directly constraining Alaskan landings and supporting quota value appreciation. Russia's Federal Agency for Fisheries administers catch allocation that shapes competitive access for Norebo Holding and Russian Fishery Company. South Korea's MFDS import inspection protocols and the EU's IUU Regulation create layered compliance thresholds for market entry. Stakeholders must monitor quota negotiations between Russia and coastal states, as bilateral agreements determine raw material flows that cascade through surimi, fillet, and roe pricing tiers.
Market Dynamics
Marine Stewardship Council certification requirements and the US Magnuson-Stevens Act traceability mandates are compressing unverified supply sources while elevating quota-backed Alaskan and Russian Far East landings into premium tier positioning.
Growth Catalysts
- Surimi demand from Asian processed seafood manufacturers:South Korean and Japanese food processors are expanding pollock surimi procurement for crab analog and fish cake production, pulling volume through Busan and Yokohama port clusters.
- Pet food premiumization:North American pet food formulators are substituting pollock for whitefish meal in grain-free and limited-ingredient diets, creating specification-grade demand for deboned mince and hydrolysates.
- Magnuson-Stevens Act quota stability:The US federal catch limit framework provides predictable supply ceilings that support long-term processor investment in shore-based filleting and freezing infrastructure.
Market Restraints
- Fuel cost volatility:At-sea processing vessels and distant-water trawlers face margin compression from marine diesel price swings that directly impact fishing economics in the Bering Sea and Sea of Okhotsk.
- Russian quota concentration:Federal Agency for Fisheries allocation decisions concentrate competitive access among a narrow set of quota holders, limiting new entrant participation in raw material sourcing.
- Alternative whitefish substitution:Pangasius and tilapia fillets compete for food service and retail shelf space, particularly in European and North American value-tier positioning.
Strategic Opportunities
- EU IUU Regulation compliance premium:Verified catch documentation and blockchain traceability investments unlock preferential access to European retail and food service buyers under the Illegal, Unreported and Unregulated fishing framework.
- Direct-to-retail frozen fillet branding:Bypassing traditional surimi intermediary channels allows Alaska-based processors to capture margin pools in US and Canadian supermarket private label and branded IQF segments.
- Roe value extraction:Japanese and Korean seasonal demand for salted pollock roe supports specialized processing investments that diversify revenue beyond commodity fillet and surimi grades.
Industry Challenges
- Skilled freezer vessel operator scarcity:Recruitment and retention of qualified deck officers and processing line supervisors limits fleet utilization rates during peak Bering Sea harvest windows.
- Marine Stewardship Council audit timelines:Certification renewal cycles and chain-of-custody documentation requirements create compliance bottlenecks for multi-source processors.
- Legacy dock infrastructure constraints:Alaska coastal communities lack sufficient cold storage and vessel offloading capacity to match at-sea processing throughput during high-volume fishing periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wild Pollock Market |
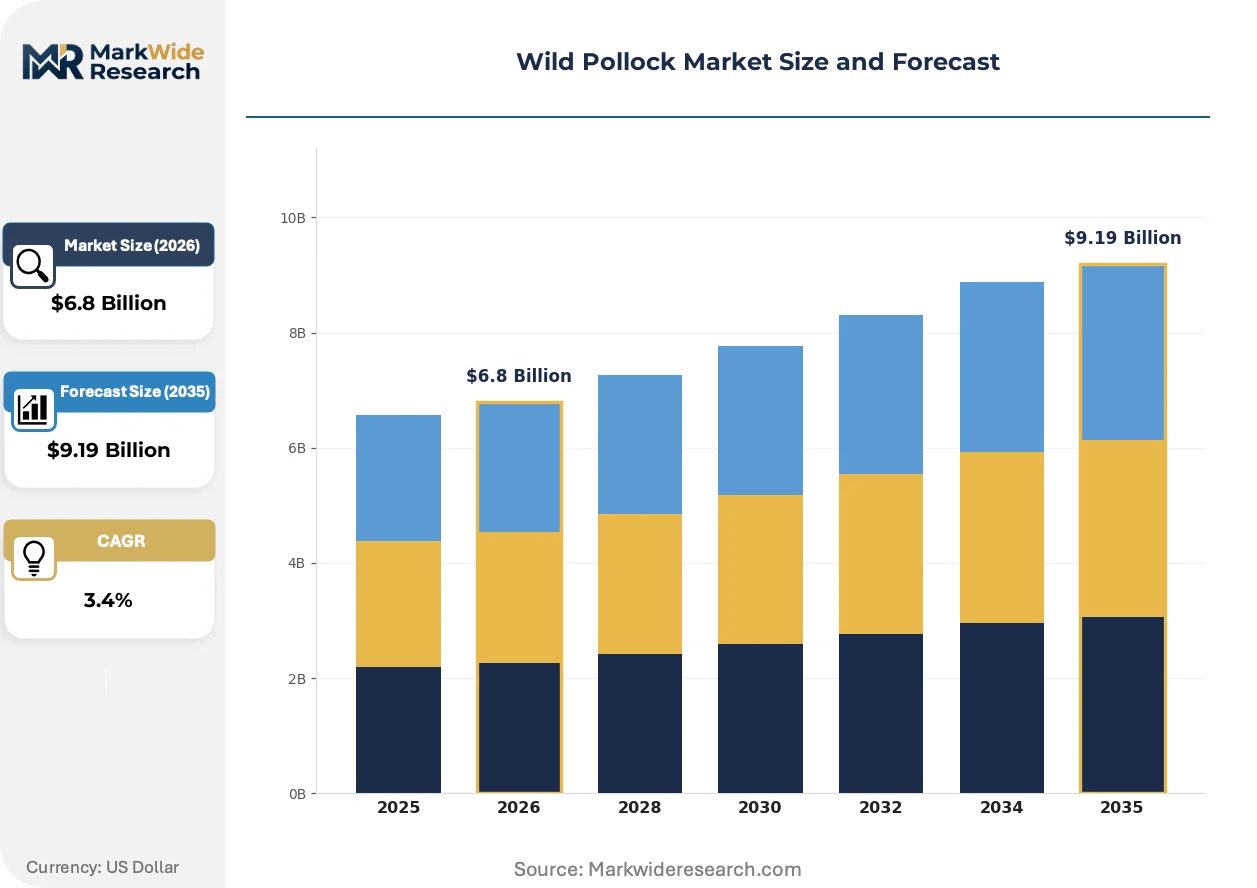
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillet, Surimi, Roe, Whole End User: Food Service, Retail, Exporters, Processors Distribution Channel: Direct Sales, Wholesalers, Online, Distributors Application: Frozen Foods, Snacks, Pet Food, Sauces |
| Companies Covered | Norebo Holding, Russian Fishery Company, Trident Seafoods, American Seafoods Group, Eastern Fish Company, Glacier Fish Company LLC, Alaska Seafood Company, Maruha Nichiro Corporation, Nissui Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wild Pollock Market Emerging Trajectories
Processing technology and traceability systems are fragmenting traditional supply chain hierarchies, enabling new competitive entry points while regulatory frameworks harden sourcing verification requirements.
Blockchain-enabled catch documentation is decentralizing provenance verification away from centralized certifier control. Japanese supermarket chains and European retail consortiums are piloting distributed ledger systems that bypass traditional Marine Stewardship Council paper-based chain-of-custody. This architecture compresses audit costs for multi-vessel fleets while opening market access to smaller quota holders previously excluded by documentation burden.
The EU IUU Regulation's enhanced import control requirements are reshaping documentation standards for Russian and Alaskan origin product. Customs authorities now demand satellite vessel monitoring system data and port state control certificates prior to release, creating compliance infrastructure investments that favor integrated harvester-processors over trader intermediaries. South Korean re-export hubs face particular scrutiny as transshipment documentation gaps trigger detention and rejection.
Specification buying by North American pet food manufacturers is rotating demand toward single-source, species-verified mince and meal products. Contract terms now require DNA authentication and allergen segregation protocols that displace commodity-grade mixed whitefish purchases. This pattern concentrates procurement relationships with Alaska shore plants capable of lot-level traceability, marginalizing traditional surimi-channel material flows.
Wild Pollock Market Segmentation
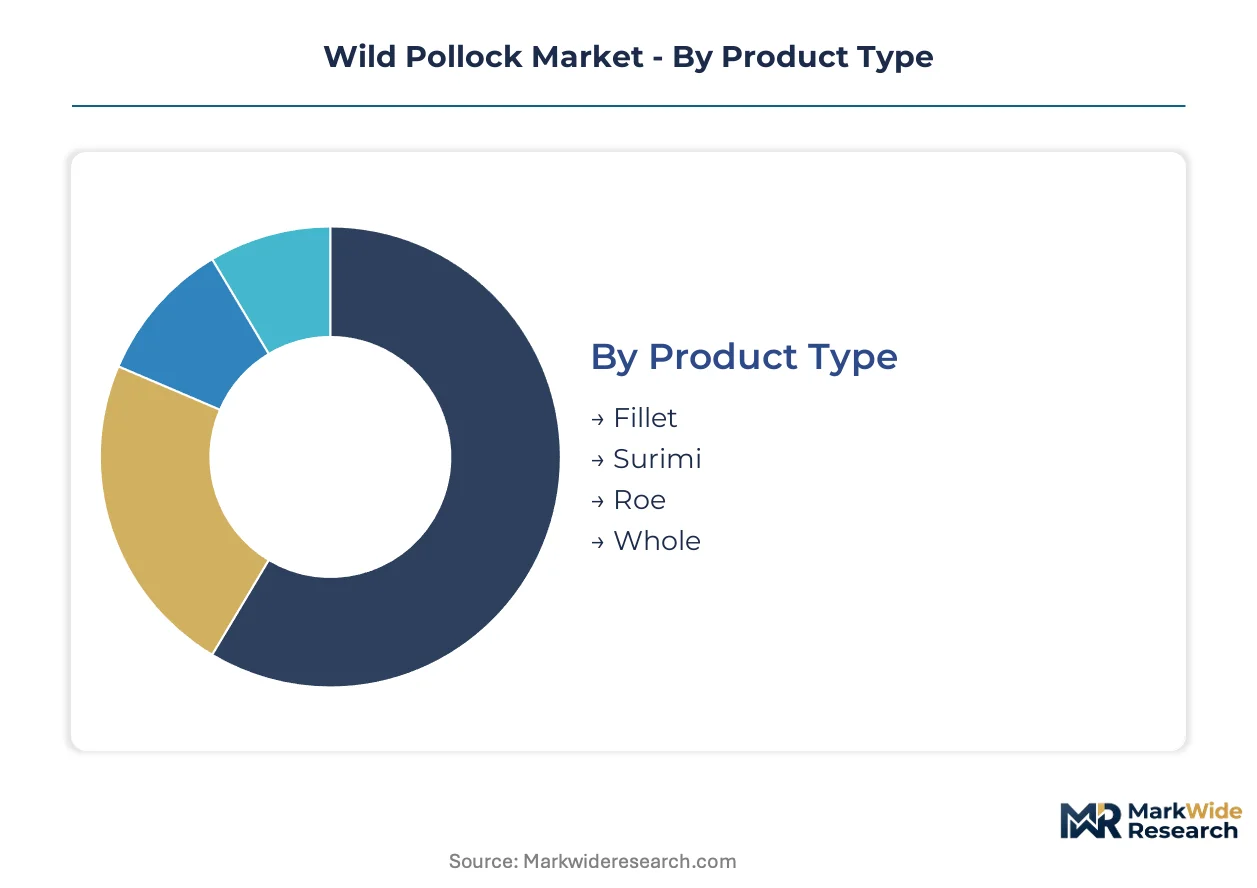
Wild pollock segmentation reveals divergent margin architectures across processing tiers. Product form determines capital intensity and customer access, while end-user concentration shapes procurement specifications and certification requirements.
Product Type:
Fillet and surimi split the volume-premium dynamic, with roe occupying a specialized value tier.
- Fillet:Boneless, skinless portions processed into IQF blocks or shatterpack configurations for retail and food service specification buyers. Alaska shore plants and Russian Far East processors concentrate supply for US and EU supermarket chains where MSC certification commands shelf placement.
- Surimi:Minced, washed, and stabilized fish paste forming the raw material for crab analogs, fish cakes, and kamaboko production. South Korean and Japanese processors pull volume through Busan and Yokohama port clusters, though margin compression from alternative whitefish substitutes limits pricing power.
- Roe:Salted pollock roe (tarako/mentaiko) serves seasonal Japanese and Korean demand with specialized processing investments.
- Whole:Round, unprocessed fish for secondary processing or regional consumption in Russian domestic markets.
Mature deployment sits with surimi. Newer deployment is concentrated in fillet value-added formats.
End User:
Customer type determines traceability burden and contract structure, from spot market exporters to specification-locked retail chains.
- Food Service:Restaurant chains, institutional caterers, and QSR operators purchasing portion-controlled, consistently sized fillets. US and EU buyers under EU IUU Regulation and Magnuson-Stevens Act documentation requirements favor Alaska-origin supply with verifiable chain-of-custody.
- Retail:Supermarket private label and branded IQF segments where MSC certification and blockchain traceability investments unlock shelf access. North American retailers specification-buy for single-source, species-verified products.
- Exporters:Intermediary traders managing cross-border flows from Russian Far East and Alaska to Asian processing hubs, facing layered compliance at South Korean MFDS inspection protocols.
- Processors:Surimi manufacturers and secondary processors converting raw material into crab analog, fish cake, or pet food ingredients.
Contract stability concentrates with retail. Spot market volatility clusters with exporters.
Distribution Channel:
Channel selection reflects customer scale and cold chain infrastructure requirements.
- Direct Sales:Large-volume contracts between integrated harvester-processors and retail chains or food service distributors, bypassing intermediary margins.
- Wholesalers:Traditional seafood merchants aggregating mixed-origin supply for smaller retail and food service accounts.
- Online:Direct-to-consumer frozen fillet sales emerging in North American markets, constrained by last-mile cold chain reliability.
- Distributors:Specialized seafood distributors managing inventory, logistics, and credit terms for mid-scale food service accounts.
Scale economies favor direct sales. Market access expansion runs through distributors.
Application:
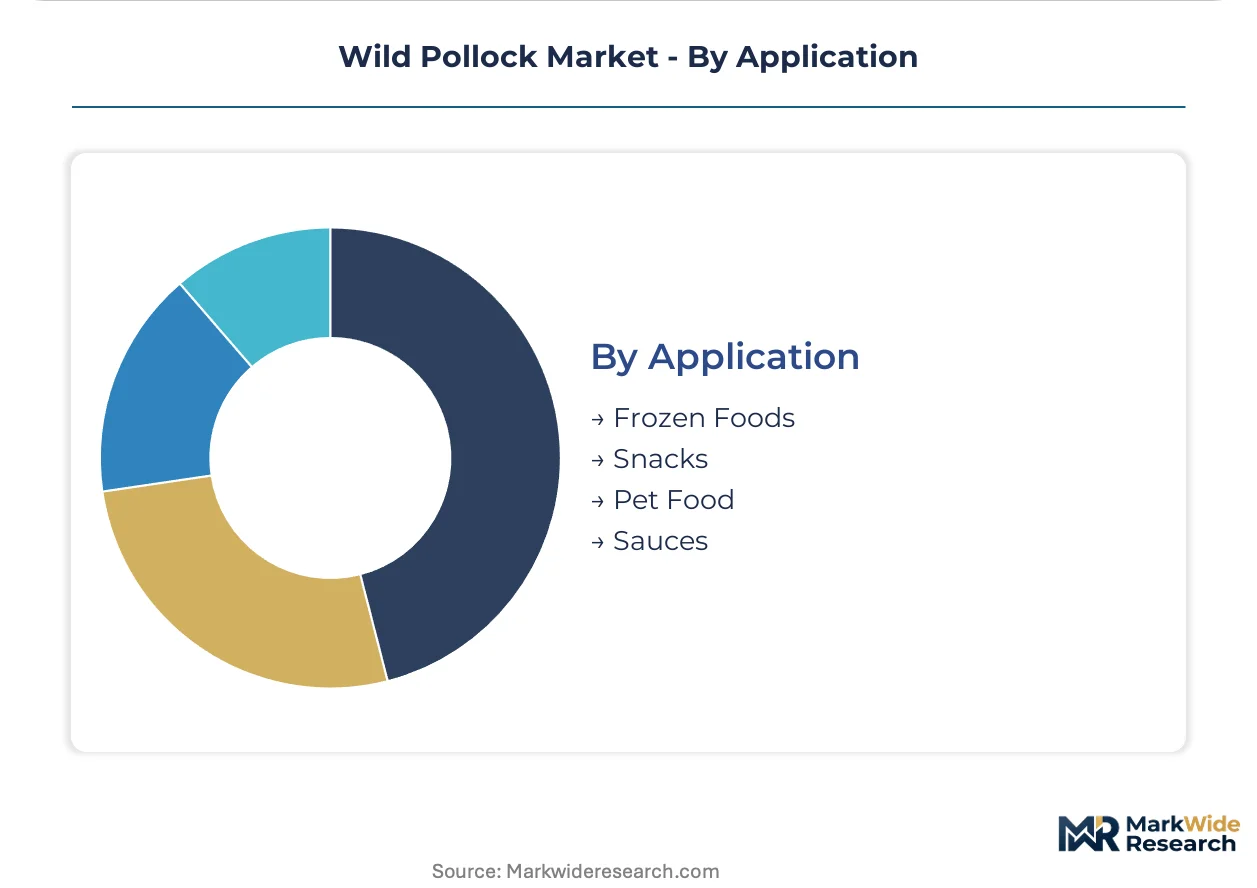
End-use application segments by processing complexity and margin capture potential.
- Frozen Foods:Breaded, battered, or plain frozen fillets and portions for retail and food service, representing the highest absolute demand tier.
- Snacks:Dried, seasoned, or extruded pollock-based products for Asian convenience markets.
- Pet Food:Deboned mince, hydrolysates, and meals for premium grain-free and limited-ingredient diets, climbing the fastest as North American pet food manufacturers specification-buy for DNA-authenticated, allergen-segregated supply.
- Sauces:Fish sauce and fermented products utilizing lower-grade material or bycatch fractions.
Volume concentration remains with frozen foods. Steepest expansion trajectory sits with pet food.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Busan anchors trans-Pacific pollock flows as South Korean processors intermediate between Russian Far East harvesters and Japanese surimi manufacturers. The port cluster handles volume consolidation for crab analog and fish cake production lines.
United States
Alaska's Bering Sea fishery supplies specification-grade fillets for North American retail chains. NOAA Fisheries enforces Magnuson-Stevens Act catch limits that constrain landings and support quota value appreciation. Seattle-based processors operate shore plants in Dutch Harbor and Kodiak for IQF production.
Russia
The Sea of Okhotsk fleet delivers raw material to Nakhodka and Vladivostok processing hubs. The Federal Agency for Fisheries administers quota allocation that shapes competitive access among integrated harvester-processors. Murmansk-based operations extend seasonal production through ice-class vessel deployment.
Japan
Seasonal demand for salted pollock roe drives procurement from Russian and Alaskan sources. The Ministry of Agriculture, Forestry and Fisheries monitors import flows for food safety compliance. Yokohama processors specialize in tarako and mentaiko preparation for domestic distribution.
South Korea
Busan and Incheon port clusters concentrate surimi manufacturing for re-export to Southeast Asian markets. The Ministry of Food and Drug Safety enforces import inspection protocols that create compliance thresholds for Russian-origin product. Daegu-based food processors expand crab analog capacity using Russian Far East raw material.
Wild Pollock Market Vendor Landscape
Capital-heavy at-sea processors compete with asset-light shore-based operators for quota-backed raw material access. The vendor base concentrates among integrated harvester-processors with direct federal quota allocations in both Alaskan and Russian jurisdictions. Three archetypes dominate: distant-water trawler operators with onboard freezing, shore-based fillet specialists with retail brand strength, and Asian trading houses controlling surimi intermediary channels. Competitive moves center on fleet modernization programs and blockchain traceability investments that unlock EU IUU Regulation compliance premiums.
Within the integrated Russian Far East tier, Norebo Holding and Russian Fishery Company occupy positions defined by federal quota access and fleet scale. Trident Seafoods anchors Alaskan representation through shore-based infrastructure concentration. These three exemplify the divergence between at-sea processing economics and land-based fillet specialization.
| Leading Market Players |
|---|
| Norebo Holding |
| Russian Fishery Company |
| Trident Seafoods |
| American Seafoods Group |
| Eastern Fish Company |
| Glacier Fish Company LLC |
| Alaska Seafood Company |
| Maruha Nichiro Corporation |
| Nissui Corporation |
| Others |
Supply Flow & Price Mechanics
Qualified freezer vessel operators concentrated in Alaska and the Russian Far East command wage premiums that compress margins for at-sea processors while amplifying spreads between shore-based fillet tiers and commodity surimi grades. These labor-cost differentials widen the pricing gap between MSC-certified premium fillets and unverified whole-round supply, redirecting procurement investments toward Dutch Harbor and Kodiak infrastructure.
Pricing Analysis
Yield-based pricing anchors fillet valuations to recovery rates from headed-and-gutted raw material, with MSC certification and blockchain traceability commanding shelf placement premiums in EU and North American retail. Price differentiation separates quota-backed Alaskan landings under Magnuson-Stevens Act limits from Russian Far East supply facing EU IUU Regulation documentation burdens. Cost compression in surimi channels is intensifying because pangasius and tilapia substitutes expand in Asian processed seafood manufacturing. Food service buyers show highest price sensitivity to fuel cost pass-throughs, while pet food formulators specification-buying DNA-authenticated mince exhibit lowest sensitivity.
Supply Chain Analysis
Workforce availability constraints in Alaska coastal communities and Russian Far East port hubs limit cold storage and vessel offloading capacity during peak Bering Sea harvest windows. Supply concentrates in the United States, Russia, and South Korea, with raw material flows drawing from federal quota allocations, distant-water trawler fleets, and Busan re-export consolidation. Single-source vulnerability sits with South Korean intermediary processors managing Russian-origin surimi transshipments under heightened MFDS inspection protocols. Distribution runs through direct sales contracts between integrated harvester-processors and retail chains, bypassing traditional seafood merchant margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wild pollock market sits in a traceability-technology transition phase, with blockchain-enabled catch documentation displacing paper-based Marine Stewardship Council chain-of-custody systems. This shift favors integrated operators capable of satellite vessel monitoring system data integration and lot-level DNA authentication.
For Market Incumbents: Hedge against alternative whitefish substitution by deepening shore-based fillet specialization in Dutch Harbor and Kodiak, capturing pet food premiumization demand through in-house hydrolysate production. Defensive consolidation should prioritize backward integration into roe processing for Japanese and Korean seasonal demand, while MSC certification renewal investments protect EU retail shelf access against IUU Regulation compliance gaps.
For New Entrants and Emerging Players: Blockchain traceability platforms offer a technology-first wedge to bypass traditional intermediary channels, enabling direct quota holder-to-retailer contracting previously blocked by documentation burden. White-space targets include EU food service distributors seeking verified Alaskan-origin supply and North American pet food manufacturers requiring allergen-segregated, species-verified mince. Go-to-market positioning should emphasize port-state control certificate integration and DNA authentication protocols.
For Investors and Strategic Acquirers: The window for entry favors integrated harvester-processors with direct federal quota access and at-sea processing vessel fleets. Long-term viability hinges on regulatory compliance infrastructure rather than spot market trading relationships. Acquisition targets should demonstrate EU IUU Regulation documentation readiness and blockchain traceability deployment. The signal to watch is bilateral quota negotiation outcomes between Russia and coastal states, which cascade through surimi, fillet, and roe pricing tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Decentralized ledger systems bypass MSC paper-based chain-of-custody, reducing audit costs for multi-vessel fleets. |
| Shore-Based Fillet Specialization | Alaska plants capture margin pools in IQF retail segments through portion-controlled, specification-grade production. |
| Roe Processing Investment | Seasonal Japanese and Korean demand for tarako and mentaiko diversifies revenue beyond commodity grades. |
| Pet Food Channel Development | DNA-authenticated, allergen-segregated mince supply locks in premium grain-free diet formulation contracts. |
| Fleet Modernization Program | Ice-class vessel deployment extends seasonal production windows in the Sea of Okhotsk and Bering Sea. |
Methodological Framework
Document review covered NOAA Fisheries catch statistics, Russian Federal Agency for Fisheries quota allocations, EU IUU Regulation implementation guidance, and Marine Stewardship Council certification databases, complemented by interviews with Alaska shore plant operations managers, South Korean surimi processors, Japanese roe importers, and North American pet food procurement directors. Secondary validation drew from customs trade data, SEC filings of publicly traded seafood processors, and Busan port authority transshipment records. Bottom-up volume modeling triangulated against top-down quota limit assessments.
Segment-level projections across product type, end user, and application dimensions anchored the analytical framework, with CAGRs derived from quota trajectory modeling and substitution elasticity estimates for pangasius and tilapia. Forecast inputs incorporated Magnuson-Stevens Act catch limit stability assumptions, Russian federal quota concentration trends, and pet food premiumization adoption curves throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under bilateral Russia-coastal state quota renegotiation, marine diesel price volatility, and EU IUU Regulation enforcement intensity shifts. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Krill Meal Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
China Crustaceans Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Oyster Meal Market
Seafood
United States Plant-Based Seafood Market
Seafood
Japan Lobster Market
Seafood
Mussel Extract Market
Seafood
Fish Meal Market
Seafood
North America Seafood Market
Seafood
Carp Market
Seafood
Fish Nutrition Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Mussel Oil Market
Seafood
COD Market