
 Global Commercial Fishing Market | 2026-2036
Global Commercial Fishing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Fishing Market Analysis
Onshore processing value-added is reconfiguring margin distribution across the Global Commercial Fishing Market. Trident Seafoods leverages integrated shoreside plants in Alaska to capture margin that vessels alone cannot secure. Maruha Nichiro Corporation anchors its position through deep freezer networks spanning Japanese ports and Southeast Asian hubs. Thai Union Group competes via species diversification and shelf-stable product lines that reduce spoilage risk.
Commercial fishing denotes the capture of wild fish, crustaceans, and mollusks using mechanized vessels and gear such as trawl nets with mesh sizes regulated by target species, operating across coastal and high-seas zones for human consumption and industrial processing. The fish segment dominates landed volume and underpins most processing infrastructure, while crustaceans command premium pricing in restaurant and retail channels. Trawling remains the most deployed method for demersal species but faces gear-selectivity mandates, whereas purse-seining leads in pelagic tuna volumes where Fish Aggregating Device regulations are tightening.
The EU IUU Regulation, NOAA fisheries enforcement protocols, and the FAO Port State Measures Agreement collectively mandate catch documentation and vessel monitoring systems that raise compliance costs for smaller operators. Japan's METI fisheries certification and South Korea's MFDS import inspection standards further shape market access conditions for exporters. Stakeholders must weigh capital allocation between fleet modernization and processing automation as regulatory thresholds for traceability and sustainability certification continue to harden.
Market Dynamics
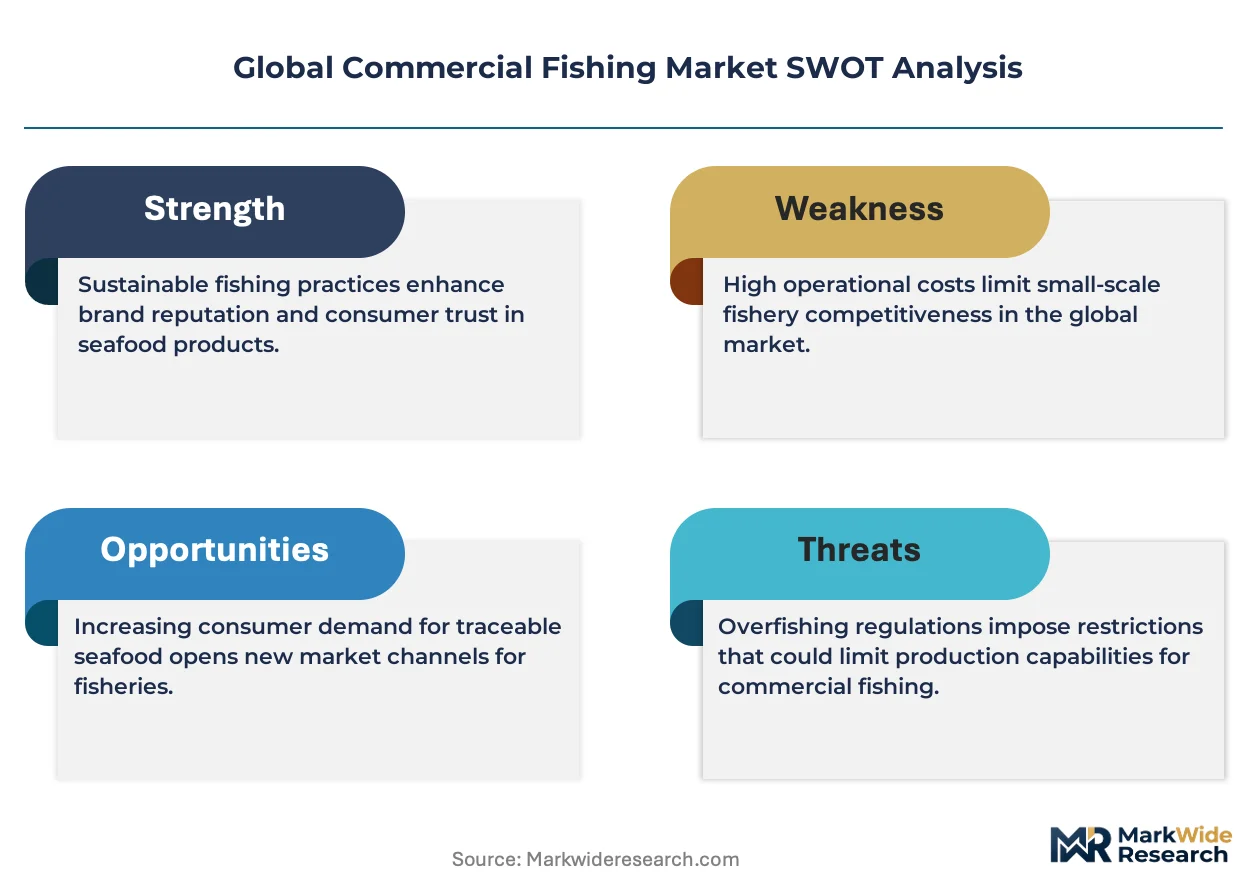
Traceability mandates from the EU IUU Regulation and FAO Port State Measures Agreement are compressing operating margins for vessel operators while rewarding integrated processors with shoreside certification infrastructure.
Growth Catalysts
- Cold-chain maturation:Refrigerated logistics networks across Southeast Asian port clusters now enable frozen seafood exports to reach retail chains in inland Chinese provinces previously inaccessible to fresh supply.
- EU IUU Regulation:Mandatory catch documentation schemes create competitive separation between compliant operators and gray-market suppliers, consolidating volume toward certified fleets.
- Surimi processing automation:Mechanized deboning and washing lines in Alaskan and Thai plants expand output of value-added minced fish products for foodservice manufacturers.
Market Restraints
- Fuel cost volatility:Diesel and marine gasoil price swings constitute the largest variable cost component for distant-water fleets operating in high-seas tuna grounds.
- Indonesian supply concentration:Archipelagic landing volumes depend on small-scale purse-seine and lift-net operators vulnerable to seasonal closures and gear restrictions.
- Gear-selectivity mandates:Trawl mesh regulations for demersal species reduce per-trip harvest efficiency while requiring capital outlays for net replacement.
Strategic Opportunities
- Vietnamese processing zones:Underdeveloped squid and cuttlefish value-addition capacity presents white space for operators with Japanese METI certification and EU-approved HACCP systems.
- Blockchain traceability:Distributed ledger systems converging with vessel monitoring data enable real-time provenance verification for premium retail channels in South Korea and Japan.
- Direct-to-foodservice channels:Bypassing traditional auction markets through contracted supply agreements with hotel and restaurant chains in Singapore and Hong Kong.
Industry Challenges
- Electronic monitoring installation:Onboard camera and sensor deployment for NOAA fisheries enforcement creates integration friction with legacy vessel electrical systems and crew workflow patterns.
- MSC certification timelines:Fishery assessment and chain-of-custody audit processes for Marine Stewardship Council standards extend 18-24 months, delaying market access for reforming operations.
- Refrigeration technician scarcity:Specialized skills for ammonia-based freezing plant maintenance concentrate in aging workforces across Japanese and Norwegian processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Fishing Market |
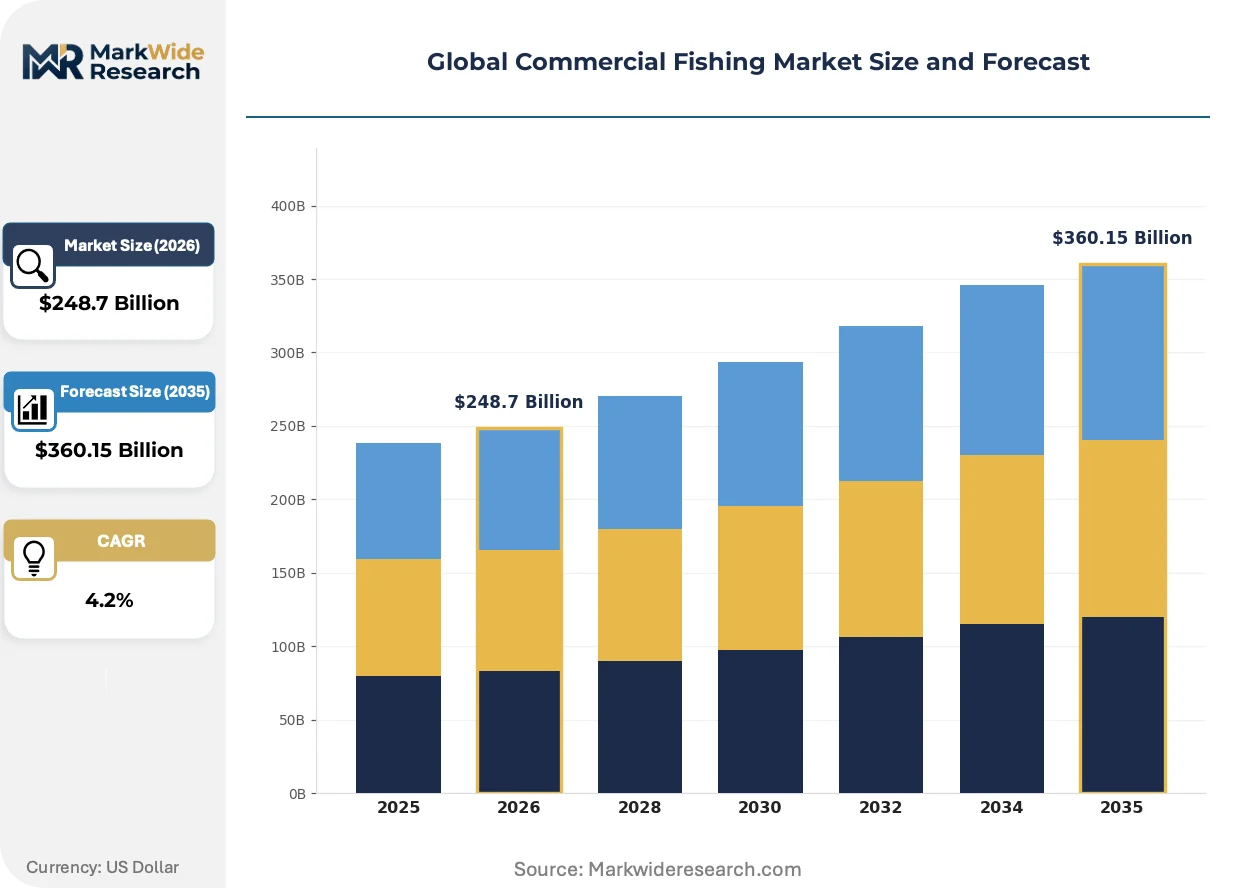
| Market Size in 2026 | $248.7 Billion |
| Market Size in 2035 | $360.15 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Crustaceans, Mollusks, Others Fishing Method: Trawling, Longlining, Purse-seining, Gillnetting End User: Restaurants, Retailers, Fish Processing, Exporters Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distribution Centers |
| Companies Covered | Thai Union Group, Oceana Group, Trident Seafoods, Ocean Beauty Seafoods, Peter Pan Seafoods, Maruha Nichiro Corporation, Mowi, Dongwon Industries, Nippon Suisan Kaisha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Fishing Market Emerging Trajectories
Digital infrastructure is compressing information asymmetries between harvesters and buyers while regulatory technology mandates force capital redeployment from hulls to data systems.
Artificial intelligence-powered species recognition and automated length-measurement systems installed on processing lines are digitizing quality grading that previously required manual inspection. Japanese surimi manufacturers and Norwegian whitefish processors deploy these systems to reduce labor dependency and standardize output consistency. The technology is digitizing margin capture by enabling real-time sorting that matches product specifications to contract premiums without secondary handling.
The EU Green Deal's Farm to Fork Strategy extends sustainability reporting requirements to seafood supply chains, mandating carbon footprint disclosure for imported products. This regulatory layer compounds existing IUU documentation burdens, forcing non-EU exporters to adopt environmental management systems. Pelagic processors in Thailand and Ecuador face the steepest compliance ramps as their mackerel and sardine volumes feed European canning operations.
Consolidation among Asian retail conglomerates is compressing supplier lists toward vertically integrated operators with captive cold storage and multi-species portfolios. Supermarket chains in South Korea and Indonesia now contract directly with processing groups rather than trading houses, shifting price discovery from auction floors to bilateral negotiations. This concentration is most visible in Jakarta and Seoul metropolitan procurement offices where shelf-space allocation favors suppliers with year-round volume guarantees.
Global Commercial Fishing Market Segmentation
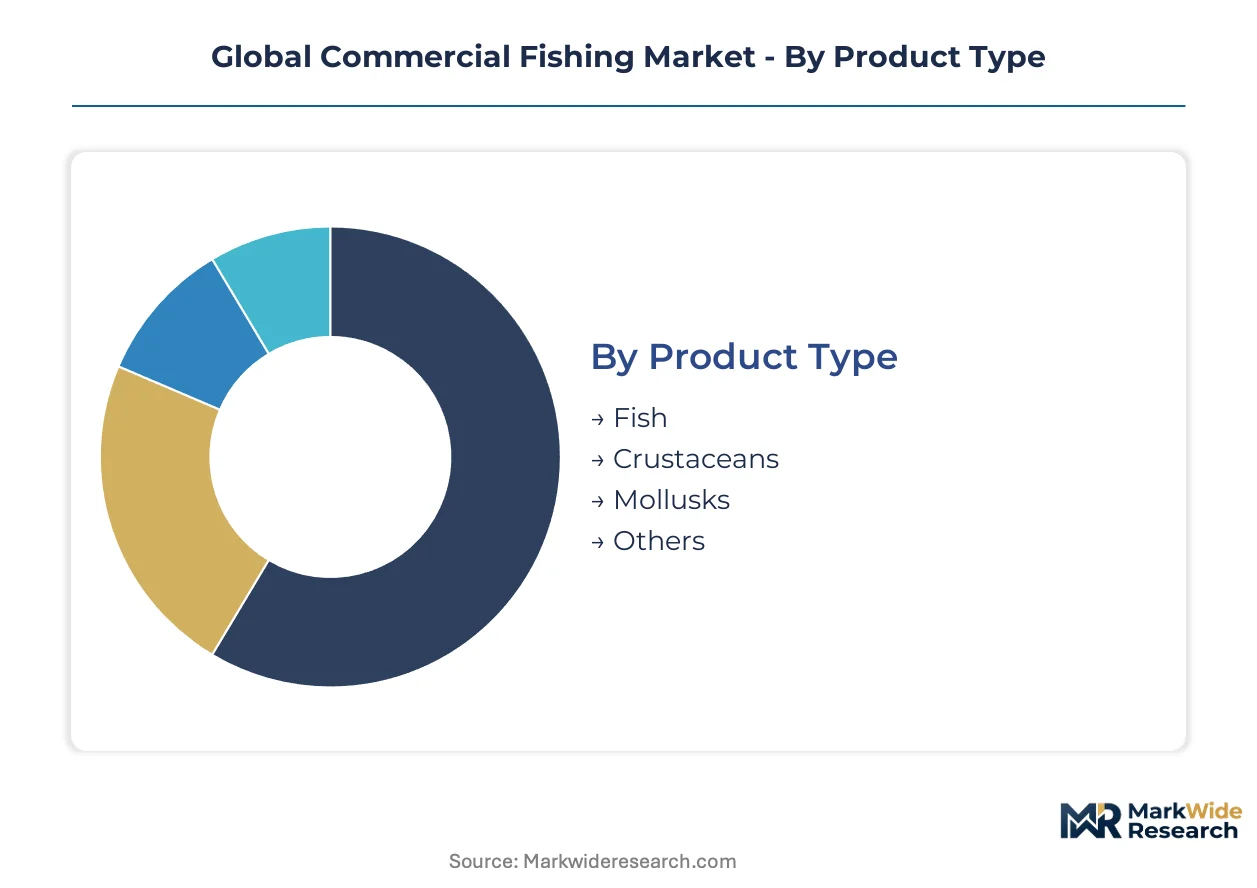
Segmentation in commercial fishing reveals how value migrates from capture to consumption. Product type determines processing infrastructure investment, while fishing method selection locks in regulatory exposure and fuel economics. Understanding these divides exposes where margin concentrates and where compliance costs bite hardest.
Product Type:
Mature segments dominate landed tonnage, though emerging categories are capturing premium positioning through certification and traceability.
- Fish:Pelagic and demersal species constitute the bulk of global landings, with whitefish and tuna underpinning surimi and canning infrastructure. Demand concentrates in Japanese and Thai processing hubs where METI and EU-approved HACCP certification gates market access. Trawl and purse-seine fleets supply these volumes, though IUU documentation mandates now favor larger certified operators over artisanal suppliers.
- Crustaceans:Shrimp, crab, and lobster command price multiples over finfish in restaurant and retail channels. Live tank shipping to Hong Kong and Singapore restaurants drives air freight demand, while frozen value chains feed European and South Korean retail through MFDS-inspected cold storage. Temperature control and mortality risk concentrate margin with integrated handlers.
- Mollusks:Squid, cuttlefish, and bivalve harvesting operates through specialized jigging and dredge fleets. Japanese and Spanish processors dominate cephalopod value-addition.
- Others:Seaweed, sea cucumber, and niche invertebrate harvests serve regional specialty markets with limited processing scale.
Fish handles the majority of throughput; crustaceans is the fastest mover on share as premium retail channels expand in South Korea and Indonesia.
Fishing Method:
Capital intensity and regulatory exposure separate methods, with automation and selectivity mandates driving fleet consolidation.
- Trawling:Bottom and midwater trawls harvest demersal species at scale but face mesh-size regulations that reduce per-trip efficiency. EU gear-selectivity mandates and NOAA observer requirements raise compliance costs, pushing smaller Gulf of Mexico and North Sea operators toward consolidation or exit.
- Purse-seining:Surface nets encircling Fish Aggregating Devices dominate global tuna volumes. Western and Central Pacific Fisheries Commission catch limits and IUU documentation requirements concentrate operations among flagged fleets with shoreside certification infrastructure.
- Longlining:Pelagic and demersal line fishing targets high-value swordfish and tuna with lower fuel burn than trawling. Bycatch mitigation rules reshape gear configurations.
- Gillnetting:Passive net deployment captures salmon and coastal species with minimal capital outlay, though marine mammal interaction restrictions constrain deployment zones.
Purse-seining handles the majority of throughput; longlining is expanding most quickly as fuel efficiency and species targeting improve vessel economics.
End User:
Channel concentration is compressing price discovery from auction floors toward bilateral contracting with integrated suppliers.
- Restaurants:Live and fresh supply chains serving Hong Kong, Singapore, and Tokyo establishments demand just-in-time logistics with mortality guarantees. Direct vessel-to-restaurant relationships bypass traditional wholesale layers.
- Retailers:South Korean and Indonesian supermarket chains now contract directly with processing groups rather than trading houses, favoring suppliers with year-round volume and MSC certification.
- Fish Processing:Surimi, canning, and fillet plants in Thailand, Ecuador, and Alaska convert raw material into value-added products for foodservice manufacturers.
- Exporters:Re-export hubs in Vietnam and the Philippines handle species transshipment to EU and Japanese markets under tightening traceability rules.
Restaurants handle the majority of throughput; retailers is climbing the fastest as Asian conglomerates consolidate procurement.
Distribution Channel:
Cold-chain maturation is shifting volume from traditional wholesale toward direct and digital channels.
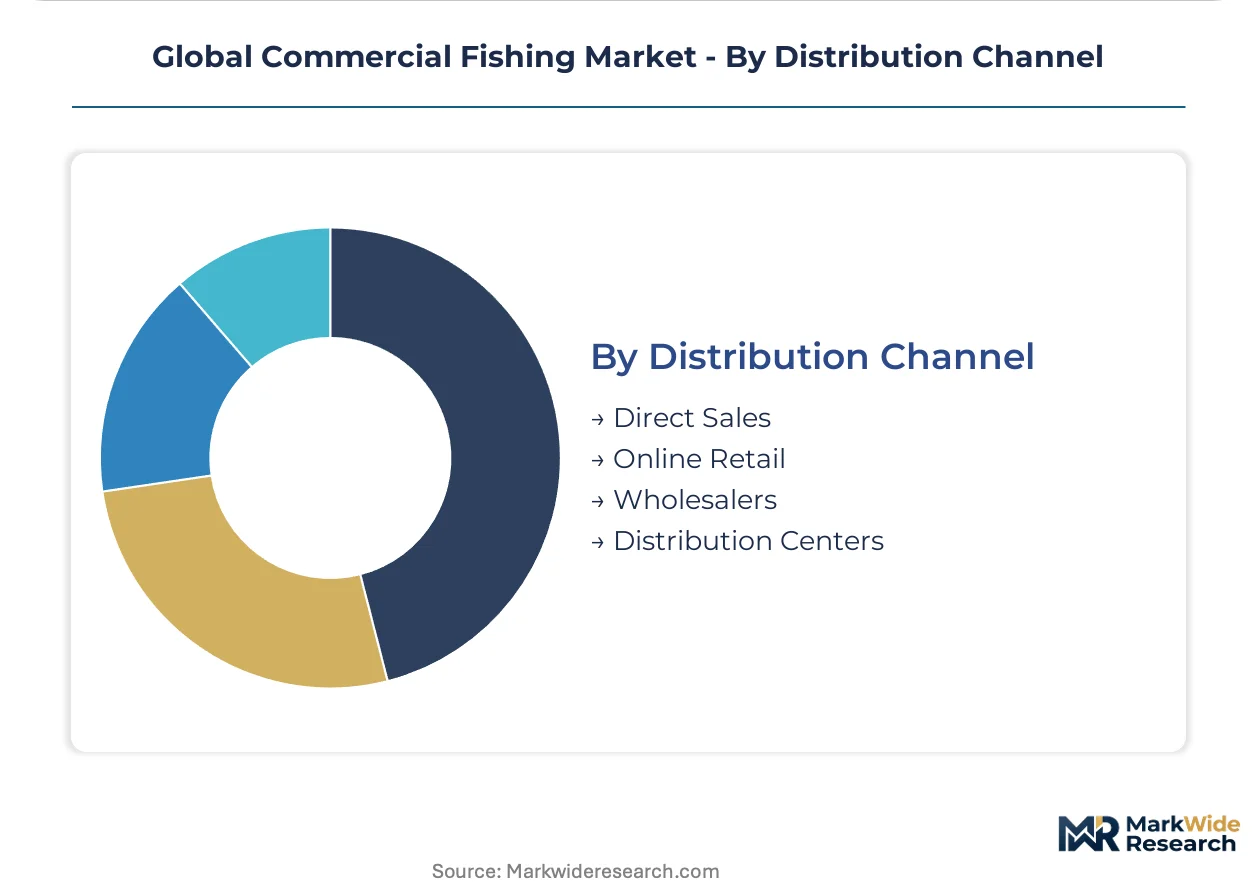
- Direct Sales:Contracted supply agreements between Alaskan catcher-processors and Japanese importers eliminate auction markups. Vessel operators with shoreside plants capture margin that secondary handling once absorbed.
- Online Retail:E-commerce platforms in Chinese inland provinces now reach consumers previously inaccessible to fresh supply, though frozen logistics dominate actual transaction volumes.
- Wholesalers:Tsukiji successor markets and Busan auction floors remain price discovery venues for spot transactions, though their share is eroding.
- Distribution Centers:Refrigerated port clusters in Jakarta, Bangkok, and Ho Chi Minh City consolidate multi-species inventory for regional redistribution.
Wholesalers handles the majority of throughput; direct sales is gaining share fastest as integrated operators bypass traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian buyers show the highest price elasticity for frozen commodity grades, while Japanese procurement offices pay premiums for live crustacean supply with mortality guarantees.
Indonesia
Small-scale purse-seine operators in the archipelagic waters supply the bulk of regional tuna landings, though seasonal closures compress annual availability. The Ministry of Marine Affairs and Fisheries enforces gear restrictions and temporary fishing bans to protect spawning stocks. Processing zones in Bitung and Jakarta consolidate catches for re-export to Thai and Japanese surimi plants.
Japan
Tokyo's Tsukiji successor market and Osaka's wholesale floors anchor premium demand for sashimi-grade tuna and live seafood for restaurant channels. METI fisheries certification requirements gate market access for foreign suppliers, favoring operators with documented chain-of-custody systems. Hokkaido's shoreside plants specialize in crab and scallop value-addition for domestic retail and export.
Thailand
Samut Sakhon province hosts the densest concentration of shrimp peeling and surimi processing facilities serving European and Japanese foodservice manufacturers. EU-approved HACCP systems and IUU documentation compliance separate certified exporters from gray-market competitors. Bangkok's refrigerated port clusters enable frozen container dispatch to South Korean retail chains.
South Korea
Busan's auction floors remain active price discovery venues, though supermarket conglomerates increasingly contract directly with integrated suppliers for year-round volume guarantees. MFDS import inspection standards mandate cold-chain documentation and species verification for all seafood shipments. Incheon's distribution centers consolidate Russian crab and Norwegian whitefish for redistribution to inland provinces.
United States
Alaska's catcher-processor fleet supplies pollock and Pacific cod for global surimi and fillet markets, with shoreside plants in Dutch Harbor and Kodiak capturing margin through integrated operations. NOAA fisheries enforcement protocols require vessel monitoring systems and electronic monitoring installation for quota-managed species. Seattle-based distributors channel Alaskan output to Japanese importers under direct sales agreements that bypass traditional auction markups.
Global Commercial Fishing Market Vendor Landscape
Capability concentration sits with integrated processors owning shoreside certification infrastructure; scale advantage sits with distant-water fleets flagged to major harvesting nations. The competitive structure tiers between vertically integrated operators with captive cold storage and specialized vessel owners dependent on third-party processing. Three archetypes dominate: Alaska-based catcher-processors, Japanese trading house affiliates with freezer networks, and Thai diversified seafood conglomerates. Consolidation pressure operates through fleet acquisitions and processing automation investments rather than brand-building.
Within the integrated processing tier, Trident Seafoods and Maruha Nichiro Corporation exemplify operators capturing margin through shoreside plant ownership and cold-chain control. Thai Union Group occupies a position as a diversified conglomerate competing via species breadth and shelf-stable product portfolios. These three represent distinct strategic positions: North American vertical integration, Japanese freezer-network anchoring, and Southeast Asian diversification.
| Leading Market Players |
|---|
| Thai Union Group |
| Oceana Group |
| Trident Seafoods |
| Ocean Beauty Seafoods |
| Peter Pan Seafoods |
| Maruha Nichiro Corporation |
| Mowi |
| Dongwon Industries |
| Nippon Suisan Kaisha |
| Others |
Supply Flow & Price Mechanics
IUU documentation mandates from the EU Regulation and FAO Port State Measures Agreement compress operating margins for non-compliant operators while widening price spreads between certified and gray-market supply tiers. This regulatory chokepoint forces capital redeployment from fleet expansion to traceability infrastructure, reshaping both procurement premiums and supply chain configuration toward integrated processors with shoreside certification.
Pricing Analysis
After-sales service contracts for cold-chain maintenance and mortality guarantees drive lifetime value in crustacean supply chains serving Hong Kong and Singapore restaurants. Three-tier pricing structure across premium, standard, and economy levels separates MSC-certified sashimi-grade tuna from commodity surimi inputs and unverified gray-market landings. Price differentiation stems from METI certification status and volume scale commitments to Japanese trading houses. Cost compression in commodity frozen segments is intensifying because Indonesian small-scale operators face seasonal closure constraints. Retail conglomerates in South Korea and Indonesia exhibit lowest price sensitivity; inland Chinese distributors through e-commerce platforms show highest elasticity.
Supply Chain Analysis
Upstream feedstock for global surimi and whitefish processing draws from Alaskan pollock, Russian Pacific cod, and Thai tuna purse-seine landings. Ammonia-based freezing systems, specialized refrigeration technicians, and EU-approved HACCP certification capacity constitute critical input dependencies. Single-source vulnerability concentrates in Indonesian archipelagic waters where seasonal closures and gear restrictions disrupt raw material flows. Distribution runs through refrigerated port clusters in Jakarta, Bangkok, and Ho Chi Minh City for regional redistribution to Asian retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Asian retail conglomerates that now contract directly with processing groups rather than trading houses, compressing supplier lists toward vertically integrated operators with captive cold storage.
For Market Incumbents: Insulate margin position through backward integration into shoreside freezing plants and METI certification infrastructure that gates Japanese market access. Threats from electronic monitoring mandates and MSC certification timelines favor operators with capital reserves for compliance technology. Priority levers include vessel monitoring system deployment and surimi processing automation in Alaskan and Thai facilities. For New Entrants and Emerging Players: Pursue Vietnamese squid and cuttlefish value-addition capacity where Japanese METI certification and EU-approved HACCP systems present white space. The most penetrable segment is direct-to-foodservice channels bypassing traditional auction markets in Singapore and Hong Kong. Go-to-market angle centers on blockchain traceability systems converging with vessel monitoring data for premium retail channels in South Korea. For Investors and Strategic Acquirers: EU Green Deal carbon footprint disclosure requirements reshape the acquisition landscape toward processors with environmental management systems already deployed. Long-term viability over the next decade hinges on traceability infrastructure ownership rather than fleet scale alone. Acquisition target archetype: integrated catcher-processors with shoreside plants and multi-species portfolios. Signal to watch is consolidation velocity among Indonesian small-scale operators facing IUU compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Shoreside Processing Automation | Mechanized deboning lines in Alaskan plants capture margin that secondary handling once absorbed. |
| Blockchain Traceability Deployment | Distributed ledger systems enable real-time provenance verification for South Korean premium retail channels. |
| Cold-Chain Infrastructure Expansion | Refrigerated port clusters in Ho Chi Minh City reach inland Chinese provinces previously inaccessible. |
| MSC Certification Investment | Chain-of-custody audits gate market access for reforming operations seeking European retail placement. |
| Direct Sales Agreement Structuring | Contracted supply between Alaskan catcher-processors and Japanese importers eliminates auction markups. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with vessel operators, processing plant managers, cold-chain logistics coordinators, and retail procurement directors; and secondary validation through customs trade records, FAO capture statistics, EU IUU Regulation compliance databases, and NOAA fisheries enforcement protocols. Bottom-up triangulation across landing volumes by species and method converged with top-down market sizing through processing capacity and trade flow analysis.
Forecast inputs considered product type segmentation across fish, crustaceans, and mollusks; fishing method differentiation between trawling, purse-seining, and longlining; and end-user channel concentration across restaurants, retail, and processing. CAGRs were derived through regression analysis against historical landing trends and regulatory implementation timelines. Industry-specific inputs included fuel cost volatility patterns and electronic monitoring adoption curves across quota-managed fisheries.
Sensitivities concentrate around Indonesian seasonal closure enforcement, EU Green Deal carbon disclosure implementation, and ammonia refrigeration technician availability in Japanese and Norwegian hubs. Cross-checking against FAO capture statistics and national fisheries landing reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Canned Anchovy Market
Seafood
Global Smoked Fish Market
Seafood
Sea Biscuits Market
Seafood
Octopus Market
Seafood
Salmon Market
Seafood
Canned Fishery Product Market
Seafood
Carp Market
Seafood
Toothfish Market
Seafood
Cod Fish Market
Seafood
Tinned Fish Market
Seafood
Striped Bass Market
Seafood
Organic Shrimp Market
Seafood
Fish Processing Market
Seafood
Crayfish Market
Seafood
Seafood Processing Market
Seafood
Middle East Seafood Market