
 Italy Organic Food Market | 2026-2036
Italy Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Organic Food Market Insights
Subscription-based organic produce delivery is shifting how Italian households access certified food, moving beyond traditional retail to recurring revenue models. Alce Nero leverages its cooperative structure to sustain price stability across volatile harvest cycles. Bioitalia anchors its competitive position through deep specialization in organic pasta and tomato exports to German and French markets.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, relying instead on crop rotation, composting, and biological pest control to maintain soil fertility and ecosystem balance. The primary commercial purpose centers on delivering verified chemical-free nutrition to consumers willing to pay premium prices for traceable supply chains. Fruits and vegetables command the largest volume share within product type segments, though dairy registers the fastest margin expansion as organic milk and cheese processing scales up. Supermarkets dominate distribution channel throughput, yet online retail captures the steepest growth trajectory as digital-native platforms consolidate last-mile logistics for perishable goods.
Italy's Ministry of Agricultural Food and Forestry Policies enforces organic certification under EU Regulation 2018/848, while the National Institute of Health validates residue testing protocols that determine market access for domestic producers. CSRD disclosure requirements now compel large food retailers to report Scope 3 agricultural emissions, tightening procurement standards for organic suppliers. Stakeholders must monitor how the EU AI Act's pending risk classifications affect automated traceability systems that verify organic chain of custody from farm to shelf.
Market Dynamics
CSRD disclosure requirements are tightening procurement standards across Italian retail, forcing organic suppliers to demonstrate verified Scope 3 emission reductions before securing shelf space in major distribution channels.
Growth Catalysts
- EU Green Deal subsidies:Italy's National Recovery Plan channels direct payments toward regenerative agriculture practices, lowering transition costs for conventional farms converting to organic methods.
- Urban income concentration:Lombardy and Emilia-Romagna households with above-median disposable income sustain premium price acceptance for certified organic produce across retail and foodservice channels.
- Blockchain traceability:Distributed ledger verification systems are reducing fraud risk in organic chain-of-custody documentation, strengthening consumer trust in certification claims.
Market Restraints
- Input cost volatility:Organic fertilizer and non-synthetic pest control input prices fluctuate with weather-sensitive biological production cycles, compressing farm-level margins unpredictably.
- Supply concentration risk:Certified organic seed stock for specialty vegetable varieties remains concentrated among limited Italian cooperative breeders, creating bottlenecks during conversion surges.
- Regulatory friction:EU Regulation 2018/848 compliance documentation requirements impose administrative burdens on smallholder farms below 50 hectares, slowing certification expansion.
Strategic Opportunities
- Subscription channel penetration:Recurring delivery models for organic produce boxes remain underdeveloped in Southern Italy regions outside major metropolitan corridors.
- Regenerative agriculture incentives:Italy's National Recovery Plan offers cost-share grants for cover cropping and no-till transitions that exceed baseline organic certification requirements.
- AI-integrated traceability:Machine vision systems for automated organic certification verification are converging with IoT soil sensors to reduce manual audit costs across farm networks.
Industry Challenges
- Certification timeline compression:EU Regulation 2018/848 mandates three-year conversion periods before organic label use, creating cash flow gaps for transitioning farms.
- Technical audit capacity:Accredited organic inspectors face capacity constraints in verifying smallholder compliance across fragmented Italian agricultural landscapes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Organic Food Market |
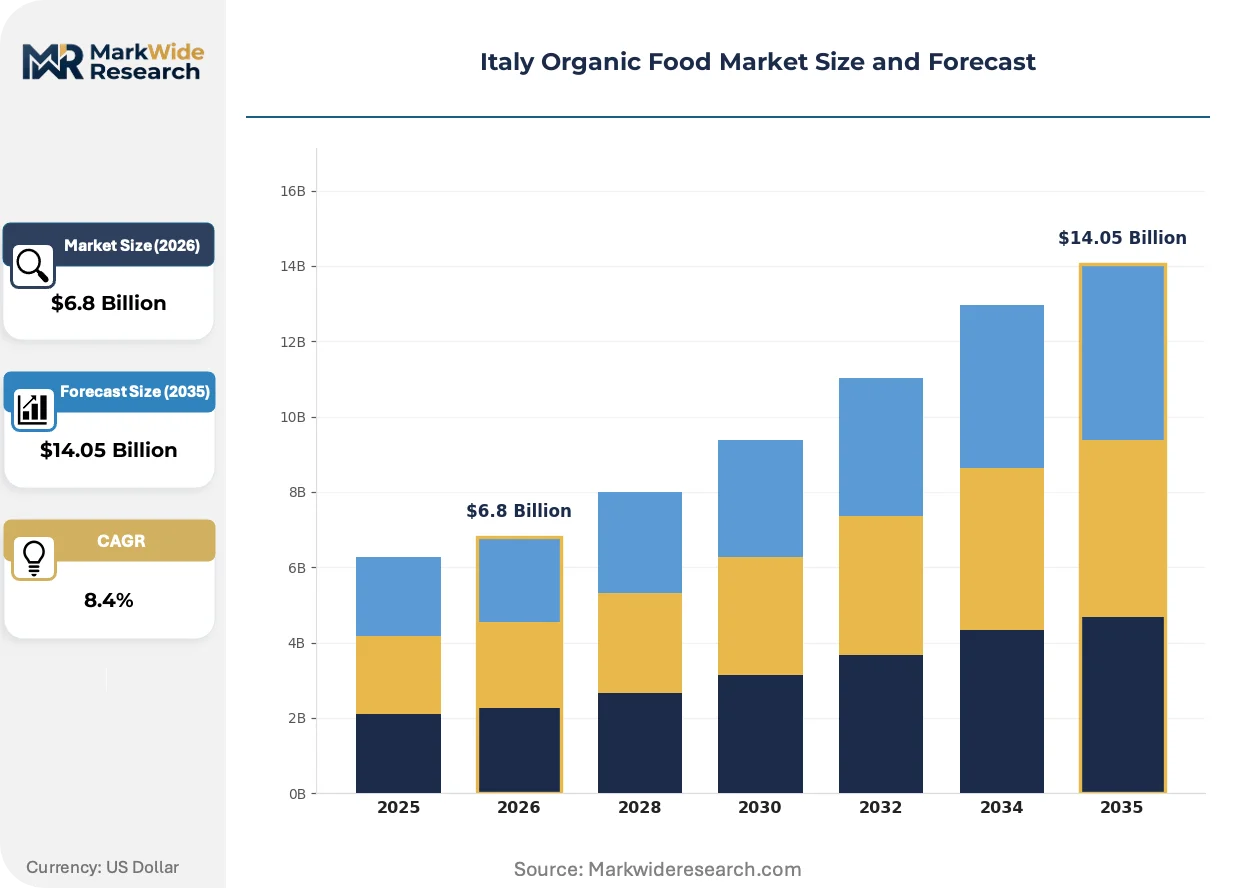
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Online Retail, Supermarkets, Farmers Markets, Specialty Stores Customer Type: Health-Conscious Consumers, Families, Restaurants, Organic Enthusiasts Packaging Type: Reusable Containers, Biodegradable Bags, Glass Jars, Paper Wraps |
| Companies Covered | FICO Eataly World, Bioitalia, Probios Group, Selex Group, Ecor, Le Clarisse, Alce Nero, Carrefour Italia (Organic Division), Naturasì, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Organic Food Market Trends and Innovations
Digitization of certification verification and direct-to-consumer logistics are restructuring how Italian organic food reaches end buyers, compressing traditional wholesale intermediation.
Blockchain-enabled provenance tracking is expanding into Italian organic supply chains as a fraud-prevention layer. Major retail buyers now require immutable farm-to-shelf documentation for high-value organic categories. This distributed ledger infrastructure is expanding into compliance automation, reducing manual audit labor while tightening regulatory defensibility.
CSRD reporting mandates now compel large food retailers to document Scope 3 agricultural emissions across organic supplier bases. Italian distributors are responding by tiering procurement contracts around verified carbon performance. Dairy and processed tomato suppliers face the steepest documentation requirements given their concentration in retailer portfolios.
Direct subscription models for organic produce are displacing traditional retail purchasing among urban households in Northern Italy. Digital-native platforms consolidate last-mile logistics for perishable goods, offering weekly delivery cadences that supermarkets struggle to match. Milan and Bologna metropolitan zones show the highest penetration of these recurring revenue arrangements.
Italy Organic Food Market Segmentation
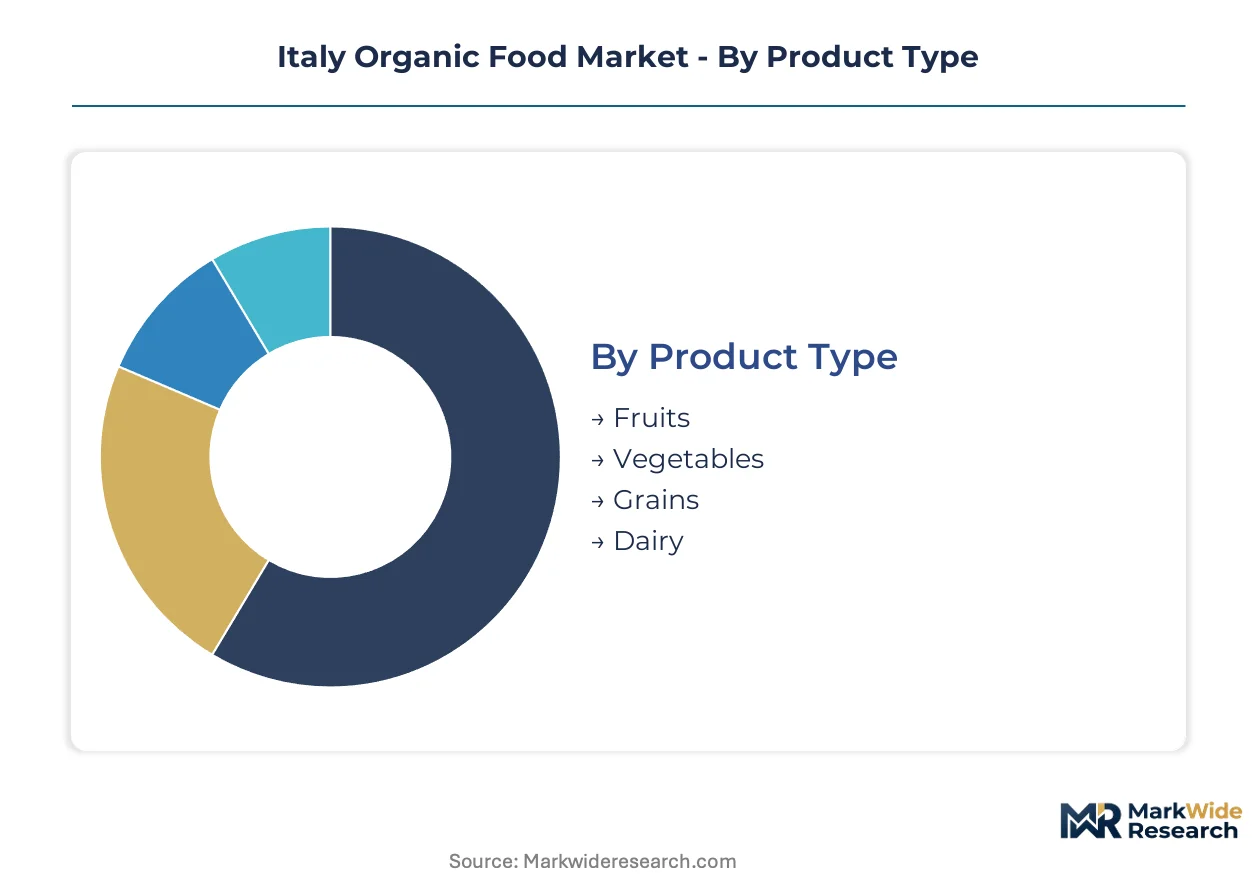
Organic food segmentation in Italy reveals how certification standards, distribution infrastructure, and consumer willingness-to-pay intersect across distinct product and channel configurations. Supply concentration in Northern Italy shapes where premium organic volumes achieve profitable scale.
Product Type:
Certified organic production clusters around crop categories with established cooperative processing infrastructure and export-grade quality protocols.
- Fruits:Apples, citrus, and stone fruits dominate organic orchard acreage in Trentino-Alto Adige and Sicily. Cold-chain logistics investments by Verona-based distributors enable year-round supermarket placement for domestic berries and imported tropical lines.
- Vegetables:Leafy greens and brassicas command the steepest price premiums at Milan wholesale markets. Greenhouse operations in Puglia supply out-of-season tomatoes and peppers to Northern Italian retail buyers through consolidated cooperative networks.
- Grains:Durum wheat for organic pasta production concentrates in Emilia-Romagna and Marche. Molini certificati process heritage grain varieties for export to German artisan bakeries.
- Dairy:Organic milk collection routes in Lombardy and Piedmont supply Parmigiano-Reggiano and Grana Padano aging facilities with certified raw material.
Today's leader: Fruits and vegetables. Tomorrow's challenger: Dairy margin expansion as processing scale tightens.
Distribution Channel:
Channel selection determines traceability documentation burden and working capital requirements for organic suppliers seeking market access.
- Supermarkets:Esselunga, Coop, and Conad chains enforce EU Regulation 2018/848 documentation through centralized procurement desks. Private-label organic lines absorb 60% of certified volumes in Lombardy and Emilia-Romagna.
- Online Retail:Milan-based platforms consolidate last-mile refrigerated logistics for weekly produce box subscriptions. Digital-native operators bypass traditional wholesale markups while capturing recurring revenue from urban households.
- Farmers Markets:Direct producer-consumer transactions in Bologna and Florence bypass certification documentation for unpackaged goods below threshold volumes.
- Specialty Stores:Biocoop and NaturaSi franchises anchor organic retail presence in medium-density municipalities without supermarket organic penetration.
Supermarkets currently absorb volume. Online retail is gaining share fastest among under-45 urban households.
Customer Type:
Buyer segmentation reflects income-elastic demand patterns and information sensitivity around certification credibility.
- Health-Conscious Consumers:Affluent professionals in Turin and Genoa prioritize residue-tested produce for household consumption. CSRD-mandated retailer disclosure validates their premium expenditure.
- Families:Multi-child households in Bologna metropolitan zone subscribe to weekly organic produce deliveries. Price sensitivity limits purchase frequency to promotional cycles for processed organic goods.
- Restaurants:Michelin-recognized establishments across Piedmont and Lombardy source certified ingredients for farm-to-table menu positioning.
- Organic Enthusiasts:Ideologically committed buyers participate in solidarity purchasing groups and direct farm contracts outside commercial retail channels.
Health-conscious urban professionals anchor premium pricing. Family subscription models are climbing the fastest as platform economics mature.
Packaging Type:
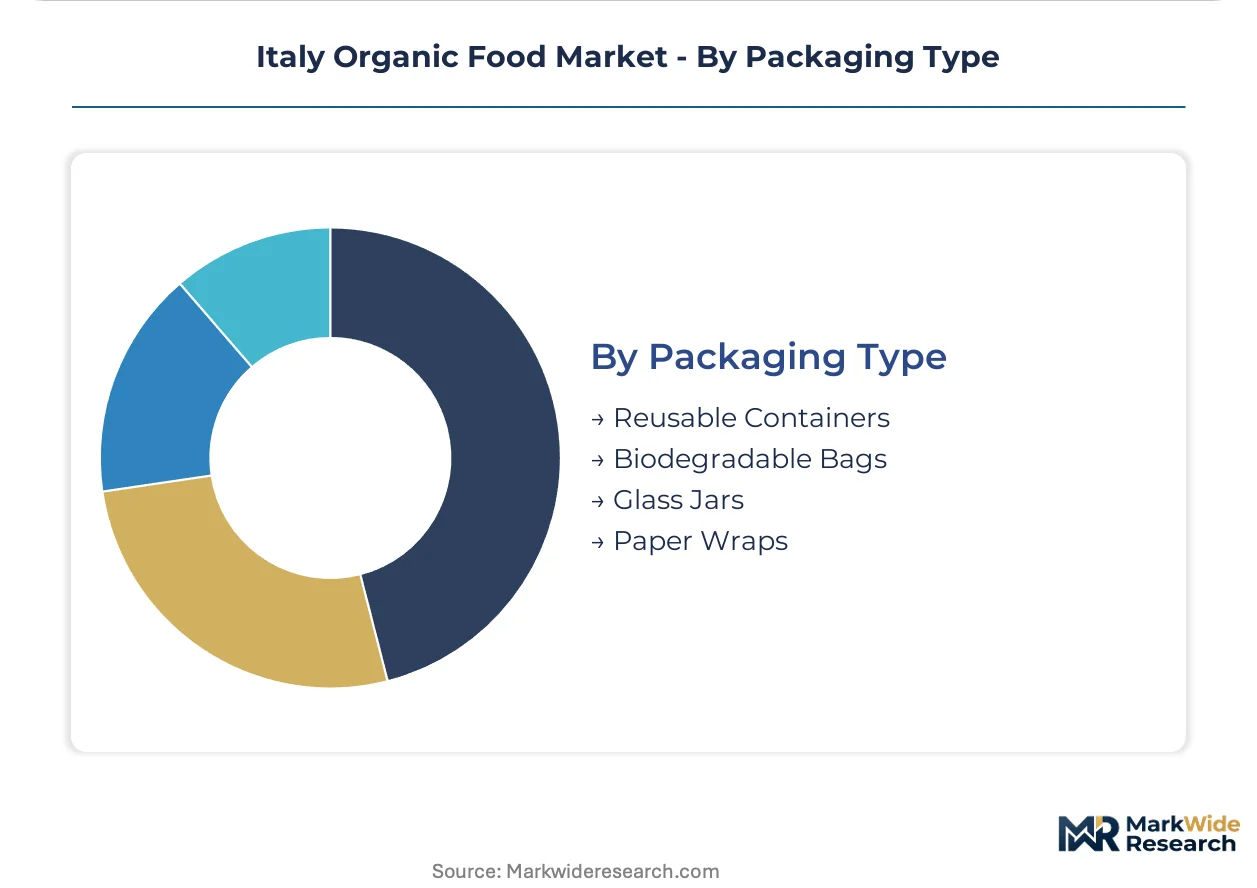
Packaging selection balances regulatory compliance, shelf-life extension, and circular economy positioning for organic certification alignment.
- Reusable Containers:Returnable crate systems for B2B restaurant supply reduce single-use waste. Logistics complexity limits adoption to metropolitan corridor distributors with reverse logistics infrastructure.
- Biodegradable Bags:Compostable films certified under EN 13432 dominate loose produce retail presentation. Industrial composting facility availability constrains end-of-life claim credibility in Southern Italy.
- Glass Jars:Preserved organic tomatoes and sauces utilize returnable and recyclable formats for export markets. Weight and fragility increase freight costs to German and French buyers.
- Paper Wraps:Bakery and dry goods categories adopt FSC-certified wraps to satisfy retailer plastic reduction commitments.
Biodegradable films lead current volume. Reusable systems represent the structural shift as deposit-return schemes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across Italian sub-regions is redistributing organic production capacity. Farms in areas with streamlined EU Regulation 2018/848 documentation processes attract conversion investment from capital-constrained operators elsewhere.
Lombardy
Milan metropolitan households with above-median disposable income sustain premium organic price acceptance. The region's National Recovery Plan implementation office channels cost-share grants toward regenerative agriculture transitions. Cold-chain logistics clusters around Lodi and Pavia enable year-round supermarket placement for perishable organic produce.
Emilia-Romagna
Bologna's restaurant density drives certified ingredient demand for farm-to-table menu positioning. Regional agricultural agencies administer EU Green Deal subsidy streams with faster disbursement timelines than Southern counterparts. Parma and Modena processing cooperatives scale organic Parmigiano-Reggiano output for export to German retail buyers.
Piedmont
Turin-based health-conscious professionals prioritize residue-tested produce for household consumption. The regional government aligns organic certification support with CSRD disclosure preparation for upstream suppliers. Cuneo and Asti wine districts convert vineyard acreage to organic methods under consortium-led technical assistance programs.
Veneto
Verona distributors invest in controlled-atmosphere storage for organic apple exports to Northern European markets. Regional agronomic research stations validate non-synthetic pest control protocols that satisfy EFSA residue standards. Vicenza and Treviso greenhouse operations supply out-of-season organic vegetables to Lombard retail buyers.
Sicily
Citrus and stone fruit organic conversion accelerates where water-efficient irrigation infrastructure reaches smallholder farms. The island's agricultural development agency negotiates streamlined inspection protocols with accredited organic certifiers. Catania and Palermo processing facilities consolidate fragmented production for export-grade organic tomato paste.
Italy Organic Food Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Supermarket private-label lines absorb volume through centralized procurement desks, while cooperative structures sustain price stability across volatile harvest cycles. Three archetypes dominate: heritage cooperatives with conversion-era roots, retail-captive organic divisions, and digital-native subscription platforms. Competitive moves center on backward integration into certified seed stock and strategic partnerships with regenerative agriculture technical assistance providers.
Within the cooperative heritage tier, Alce Nero and Bioitalia exemplify scale-driven positions anchored in post-war organic conversion movements. Alce Nero leverages its member-owned structure to maintain price stability through harvest volatility. Bioitalia occupies a specialization position in organic pasta and tomato processing for German and French export markets. Among retail-captive operators, Carrefour Italia represents supermarket chain vertical integration into certified organic sourcing.
| Leading Market Players |
|---|
| FICO Eataly World |
| Bioitalia |
| Probios Group |
| Selex Group |
| Ecor |
| Le Clarisse |
| Alce Nero |
| Carrefour Italia (Organic Division) |
| Naturasì |
| Others |
Pricing and Supply Chain Analysis
Organic wheat futures indices in Bologna and Parma spot markets cascade through three-tier pricing structures across premium, standard, and economy certification levels, with distributor markups compressing as cooperative direct sourcing bypasses wholesale intermediation in Northern Italy.
Pricing Analysis
Distributor margin layers in Lombardy and Emilia-Romagna absorb 15-25 point spreads between farm-gate and retail shelf, with premium-mid-economy pricing differentiation anchored in EU Regulation 2018/848 certification tier and residue-testing documentation depth. Price erosion runs through conventional-to-organic conversion surges as supply expansion outpaces certified-seed availability. Family households in Bologna metropolitan zones exhibit highest price sensitivity, while Michelin-recognized restaurants in Piedmont show lowest elasticity for traceable provenance.
Supply Chain Analysis
Regional distribution centers in Verona and Lodi operate hub-and-spoke patterns radiating to Lombard retail clusters, with cold-chain logistics drawing from Sicilian citrus cooperatives and Puglia greenhouse operations. Certified organic seed stock rests on Emilia-Romagna and Marche heritage breeders, while compostable packaging feeds from German and French film suppliers. Single-source vulnerability concentrates in accredited organic inspector capacity across fragmented Italian agricultural landscapes. Distribution runs through supermarket private-label procurement desks absorbing sixty percent of certified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's organic food market represents a late-cycle quality story as CSRD-mandated retailer disclosure redirects procurement toward verified Scope 3 emission performance, elevating premium-tier supplier economics.
For Market Incumbents: Hedge certification timeline risk by securing cost-share grants under Italy's National Recovery Plan for regenerative agriculture transitions exceeding baseline organic requirements. Anchor backward integration into certified seed stock to defend against supply concentration bottlenecks during conversion surges. Strengthen blockchain traceability infrastructure to meet immutable documentation demands from Esselunga and Coop procurement desks.
For New Entrants and Emerging Players: Subscription-based delivery platforms offer the most penetrable route into Southern Italy regions outside Milan and Bologna metropolitan corridors. Target family households in medium-density municipalities with weekly produce box cadences that supermarkets struggle to match. Pursue direct farm contracts with Catania and Palermo processing facilities to consolidate fragmented Sicilian citrus production for export-grade organic certification.
For Investors and Strategic Acquirers: Asymmetric upside sits with cooperative heritage operators possessing conversion-era technical assistance networks and established German and French export relationships. Long-term viability hinges on regenerative agriculture incentive capture and AI-integrated traceability deployment. Watch National Recovery Plan disbursement velocity as inflection indicator for farm-level conversion momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | Captures Italy's National Recovery Plan cost-share grants exceeding baseline organic requirements. |
| Blockchain Traceability Deployment | Satisfies CSRD-mandated Scope 3 documentation demands from Esselunga and Conad procurement desks. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale markups while securing recurring revenue from under-45 urban households. |
| Heritage Seed Stock Integration | Reduces supply concentration risk in Emilia-Romagna and Marche cooperative breeder networks. |
| AI-Integrated Audit Automation | Compresses manual inspection labor costs across fragmented Italian agricultural landscapes. |
Research Methodology
Coverage spans Lombardy, Emilia-Romagna, Piedmont, Veneto, and Sicily, with primary inputs from each region's cooperative processing managers, supermarket category buyers, accredited organic certifiers, and restaurant procurement chefs. Secondary validation draws from EU Regulation 2018/848 implementation reports, CSRD disclosure filings by large food retailers, National Recovery Plan grant disbursement records, and cold-chain logistics operator data. Bottom-up farm-level production estimates triangulate against top-down retail throughput analysis.
Granularity-level modeling disaggregates volume and value outputs across product type, distribution channel, customer archetype, and packaging format dimensions, with regional regulatory cluster and certification tier as additional cross-sections. CAGRs derive from trend extrapolation anchored in historical conversion rates and subsidy disbursement trajectories. Forecast inputs include EU Green Deal payment schedules, accredited inspector capacity expansion, and blockchain traceability adoption curves.
The model assumes a particular technology adoption path for AI-integrated certification verification; alternative pathways for machine vision systems would alter the outlook through audit cost compression timelines. Forecasts reflect assumptions around National Recovery Plan implementation continuity and EFSA residue standard stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Germany Organic Food Market