
 Asia Pacific Canned Seafood Market | 2026-2036
Asia Pacific Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Canned Seafood Market Outlook
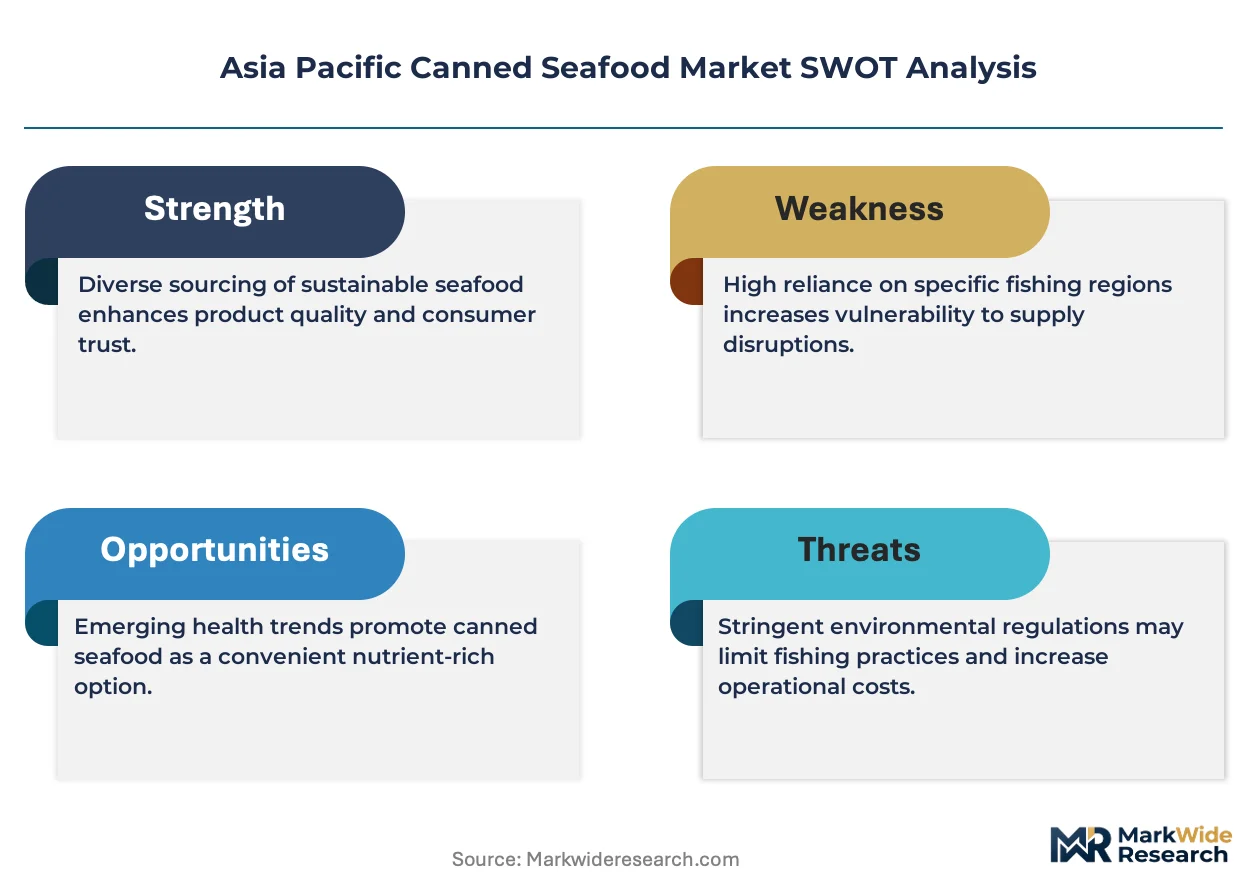
Skilled fish processing labor availability is collapsing across Southeast Asian cannery zones, forcing automation investments and wage restructuring that reshape cost curves for producers. Thai Union Group leverages its integrated cold-chain infrastructure to sustain raw material access across Thai and Indonesian waters. Century Pacific Food anchors Philippine domestic supply through branded retail dominance while competing aggressively in Middle East export channels. Dongwon Industries dominates Korean shelf-stable tuna through vertical control of distant-water fleets and domestic canning capacity.
Asia Pacific canned seafood comprises thermally processed fish products sealed in hermetic containers, typically achieving commercial sterility through retort treatment at 116-121 degrees Celsius to eliminate Clostridium botulinum risk and enable ambient storage up to five years. Tuna leads product type volume due to established consumer preference and global commodity flow integration, while sardines and mackerel segments retain stronger price elasticity among lower-income demographics across Indonesia and the Philippines. Supermarkets and convenience stores control primary distribution channel throughput, though online retail is gaining fastest in South Korean and Japanese urban markets where refrigerated last-mile infrastructure supports subscription pantry replenishment models.
Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards that restrict histamine levels and mandate bilingual labeling for imported canned fish, directly conditioning market access for Thai and Philippine exporters. China's National Health Commission and GB standards govern retort pouch safety and heavy metal limits, while Australia's Food Standards Code and New Zealand's MPI requirements create additional compliance layers for Pacific Rim trade flows. Stakeholders must monitor evolving Extended Producer Responsibility frameworks for metal can recycling and shifting mercury testing protocols that could alter species sourcing strategies and supplier qualification criteria.
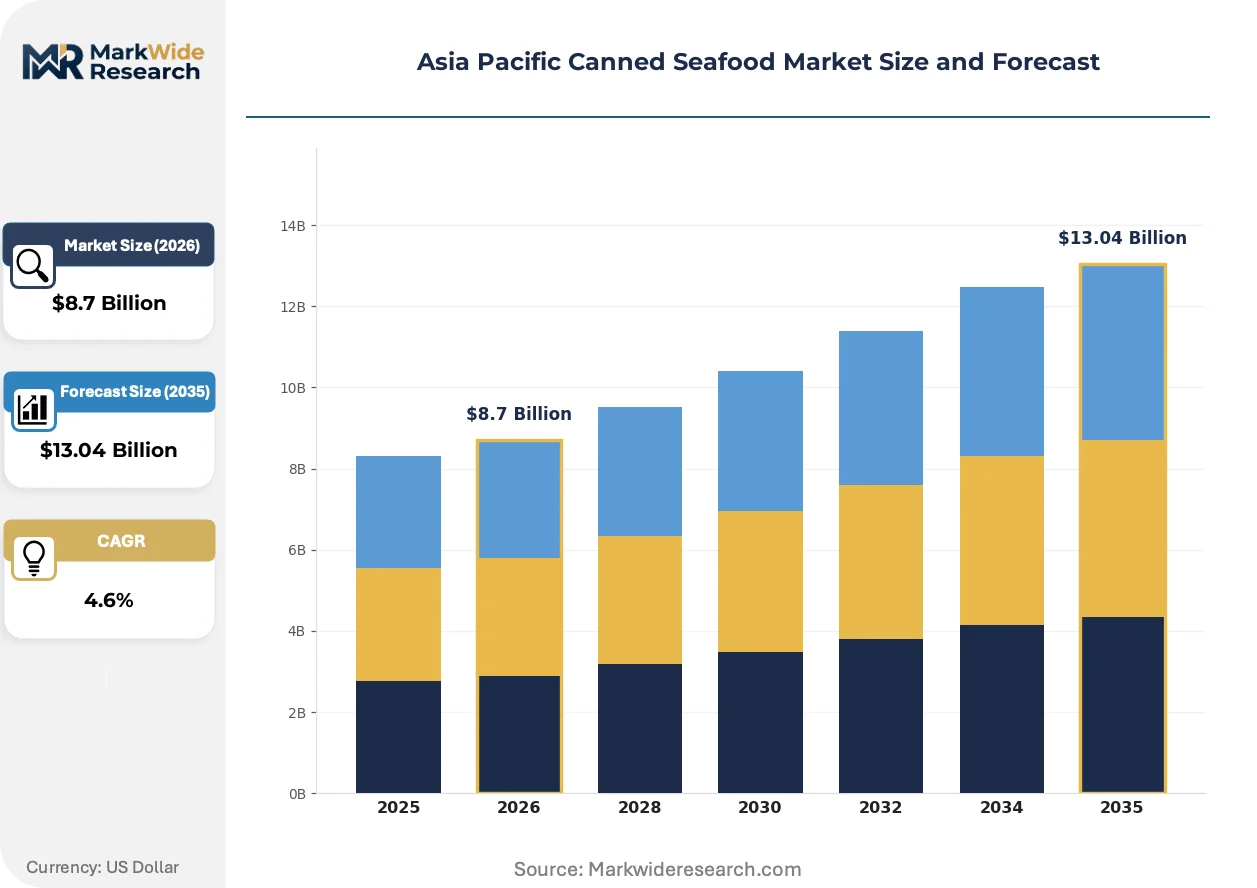
Market Dynamics
Skilled fish processing labor availability is collapsing across Southeast Asian cannery zones, forcing automation investments and wage restructuring that reshape cost curves for producers across Thailand, the Philippines, and Indonesia.
Growth Catalysts
- Japan's Food Sanitation Act Revisions:Tightening additive and labeling standards for shelf-stable fish products create compliance-driven quality upgrades that premiumize import flows from Thai and Philippine exporters.
- Urban Household Protein Demand:Ready-to-eat protein demand from dual-income households across Seoul, Tokyo, and Singapore accelerates uptake of ambient-storage tuna and mackerel as pantry staples.
- Retort Pouch Technology:Flexible packaging formats with reduced metal content and faster thermal processing cycles gain traction among Southeast Asian processors serving convenience-oriented retail channels.
Market Restraints
- Wild Catch Input Volatility:Skipjack and yellowfin tuna price swings tied to Western and Central Pacific Fisheries Commission quota negotiations compress margin predictability for Thai and Indonesian canneries.
- Mercury Testing Protocol Stringency:Australia's Food Standards Code and New Zealand's MPI requirements impose species-specific maximum levels that restrict sourcing from certain Indian Ocean fishing grounds.
- Aluminum Can Sheet Concentration:Regional supply of food-grade tinplate and aluminum coil concentrates among a limited set of East Asian metal rollers, creating input cost pass-through vulnerability.
Strategic Opportunities
- Vietnam Processing Zone Expansion:Underdeveloped canning infrastructure along Vietnam's central coast presents greenfield investment potential for exporters seeking tariff-advantaged access to ASEAN and EU markets.
- Extended Producer Responsibility Frameworks:Emerging metal can recycling mandates across South Korea and Japan create first-mover advantages for producers with closed-loop packaging partnerships.
- Subscription Pantry Replenishment:South Korean and Japanese urban markets demonstrate fastest online retail channel growth where refrigerated last-mile infrastructure supports recurring delivery models for multi-pack tuna assortments.
Industry Challenges
- Retort Operator Skill Scarcity:Thermal process validation and botulism risk management expertise is thinning across Philippine and Indonesian cannery workforces, elevating training costs and audit failure rates.
- Dual-Label Compliance Burden:Bilingual Japanese-English packaging requirements for histamine and allergen declarations force SKU proliferation and inventory complexity for Thai exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Canned Seafood Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuna, Salmon, Sardines, Mackerel Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packaging Type: Metal Cans, Glass Jars, Pouches, Tins End User: Households, Restaurants, Food Services, Catering |
| Companies Covered | Thai Union Group, Century Pacific Food, Nippon Suisan Kaisha, Dongwon Industries, Maruha Nichiro Corporation, Tri Marine Group, FCF Co. Ltd., StarKist Co., Bumble Bee Seafoods, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Canned Seafood Market Strategic Shifts
Automation and packaging technology convergence is compressing production batch sizes while regulatory pressure on traceability is forcing digitization of supply chain documentation across the Asia Pacific canned seafood value chain.
Retort pouch technology is miniaturizing traditional canning footprints across Thai and Philippine processing lines. Smaller-footprint flexible retort systems enable batch sizes down to 500-unit runs for private-label convenience store SKUs. This technology is miniaturizing capital requirements for mid-tier processors, allowing regional players to compete for contract manufacturing volumes previously captured by integrated multinationals.
Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards that restrict histamine levels and mandate bilingual labeling for imported canned fish. These requirements directly condition market access for Thai and Philippine exporters, forcing upstream investment in onboard cold-chain documentation and vessel-level traceability systems. Smaller Indonesian processors face exclusion from premium Japanese import channels due to compliance infrastructure gaps.
Subscription pantry replenishment models are displacing traditional supermarket bulk purchasing among Seoul and Tokyo urban households. Younger consumers in South Korea and Japan favor automated monthly delivery of curated tuna and mackerel assortments over in-store stock-up behavior. This channel shift concentrates demand among e-commerce platforms with captive cold-chain logistics, marginalizing traditional wholesale distributors.
Asia Pacific Canned Seafood Market Segmentation
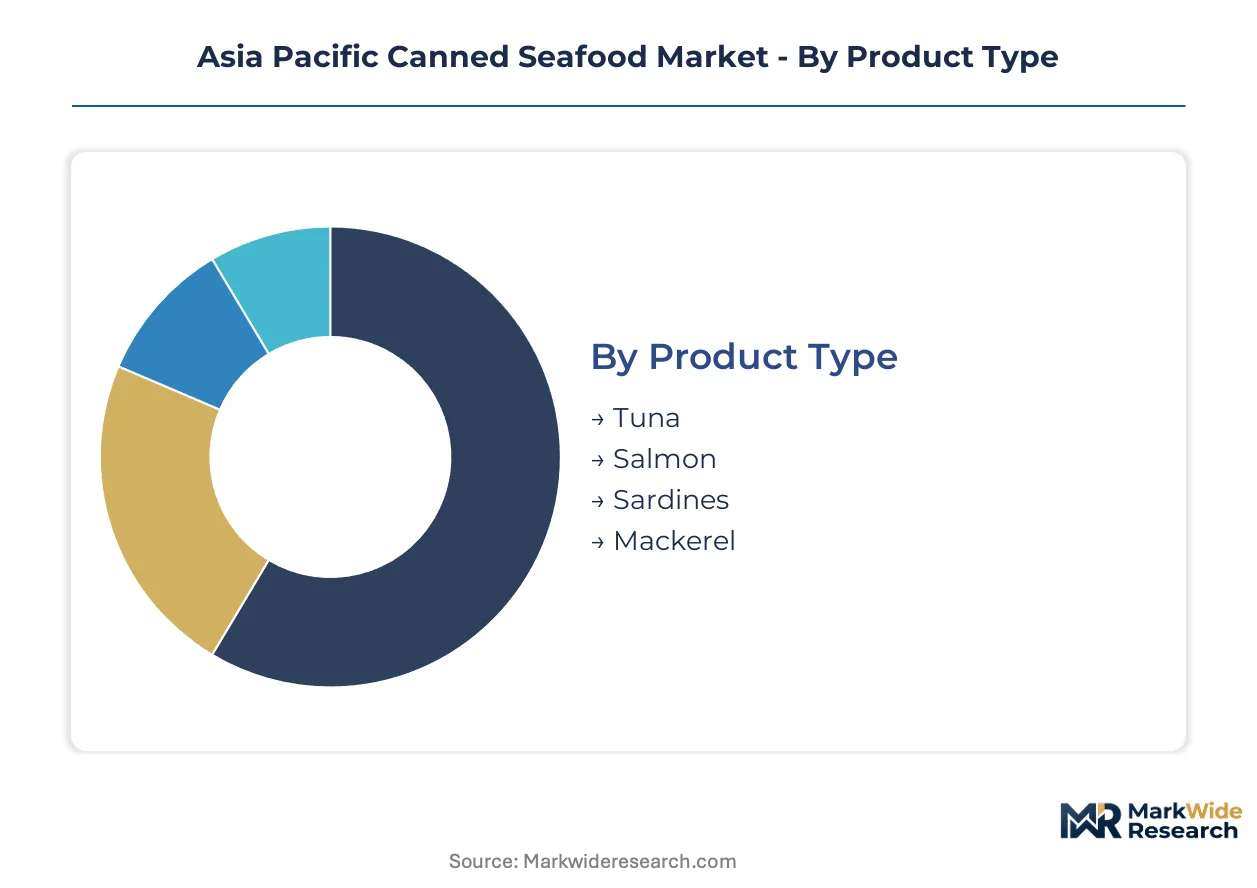
Segmentation in Asia Pacific canned seafood reveals how regulatory pressure and channel infrastructure reshape profit pools across product formats. Understanding these divides exposes where compliance costs concentrate and which packaging technologies unlock new customer access.
Product Type:
Japan's Food Sanitation Act and Australia's Food Standards Code impose species-specific histamine and mercury thresholds that favor processors with integrated cold-chain documentation and distant-water fleet control.
- Tuna:Skipjack and yellowfin varieties dominate volume through established commodity flows and retort processing compatibility. Japanese import channels concentrate demand for premium-grade solid pack, while Southeast Asian households absorb flake and chunk grades at higher price elasticity.
- Sardines:Smaller pelagic species face lower mercury testing barriers under New Zealand MPI protocols, enabling broader Indian Ocean sourcing. Philippine and Indonesian canneries leverage this regulatory advantage for Middle East export volumes where price sensitivity runs highest.
- Mackerel:Higher oil content requires modified thermal processing cycles to achieve commercial sterility without texture degradation.
- Salmon:Farmed Atlantic supply chains from Chilean and Norwegian origins face extended cold-chain requirements and tariff layering across ASEAN markets.
Tuna handles the majority of throughput; sardines are climbing the fastest on share as mercury-compliant sourcing expands.
Distribution Channel:
Channel economics diverge sharply where refrigerated last-mile infrastructure exists versus where ambient storage dominates.
- Supermarkets:Control primary throughput across Tokyo, Seoul, and Singapore through bulk stock-up behavior and private-label placement. Thai Union and Century Pacific anchor shelf space via branded block pricing and promotional calendar coordination.
- Online Retail:Subscription pantry replenishment models concentrate in South Korean and Japanese urban corridors where MFDS-registered cold-chain logistics enable recurring multi-pack delivery. Younger demographics displace traditional wholesale purchasing through automated monthly curation.
- Convenience Stores:Smaller format retail in Taiwan and Hong Kong drives single-serve pouch demand with limited ambient storage.
- Specialty Stores:Premium import channels in Australian metro areas focus on pole-and-line certified and organic-labeled assortments.
Supermarkets retain volume dominance; online retail shows steepest expansion trajectory where logistics infrastructure permits.
Packaging Type:
Material selection directly conditions compliance burden under South Korean and Japanese Extended Producer Responsibility frameworks for metal recovery and recycling documentation.
- Metal Cans:Tinplate and aluminum coil supply concentrates among East Asian rollers, creating input cost pass-through vulnerability. Food-grade specifications under China's GB standards and Japan's JIS requirements mandate precise coating chemistries to prevent sulfur blackening with high-protein species.
- Pouches:Flexible retort formats reduce thermal processing cycles and enable 500-unit batch runs for private-label convenience store SKUs. Thai processors leverage this technology to capture contract manufacturing volumes from integrated multinationals.
- Glass Jars:Premium positioning in Australian specialty retail carries freight cost penalties and breakage risk across archipelagic logistics.
- Tins:Lightweight aluminum variants serve airline and institutional catering channels with reduced shipping weight.
Metal cans absorb the bulk of production volume; pouches gain share fastest as retort technology miniaturizes capital requirements.
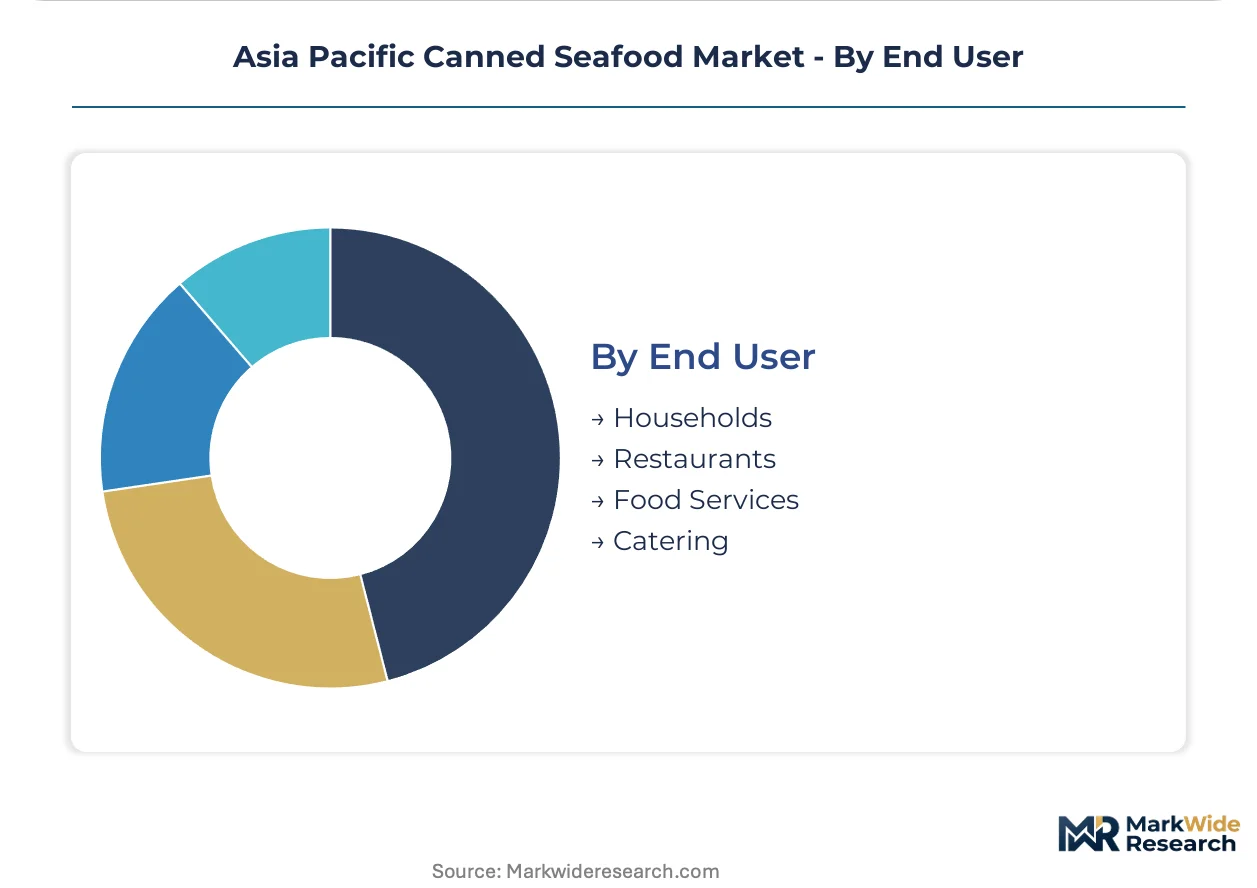
End User:
Demand concentration splits between pantry stock-up behavior in dual-income households and procurement scale in centralized food service operations.
- Households:Urban households across Seoul, Tokyo, and Singapore drive ready-to-eat protein demand as pantry staples. Ambient storage compatibility supports earthquake preparedness purchasing patterns in Japanese markets.
- Restaurants:Japanese izakaya chains and Korean gimbap specialists source institutional-size tuna for menu standardization. Histamine documentation requirements under Food Sanitation Act enforcement condition supplier qualification.
- Food Services:Centralized procurement for school and hospital cafeterias in Thailand and the Philippines prioritizes cost-stable mackerel and sardine grades.
- Catering:Event and airline catering segments in Singapore and Hong Kong demand portion-controlled formats with extended ambient holding capacity.
Households generate the dominant consumption base; restaurants are expanding most quickly as food service procurement professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Health, Labour and Welfare anchors regulatory stringency across the Asia Pacific canned seafood corridor through Food Sanitation Act enforcement. The region's demand concentrates in four distinct national markets with divergent compliance burdens and channel structures.
Japan
Urban households in Tokyo and Osaka drive premium-grade solid-pack tuna demand through subscription pantry replenishment models. The Food Sanitation Act mandates bilingual labeling and strict histamine thresholds that condition import access for Thai and Philippine exporters. Kanto and Kansai industrial zones host specialized cold-chain logistics operators serving e-commerce platforms with MFDS-registered last-mile infrastructure.
Thailand
Bangkok and Samut Sakhon processing zones absorb the bulk of Southeast Asian cannery capacity expansion as export-processing demand accelerates. Thai processors face tightening additive standards under Japanese import protocols that force upstream cold-chain documentation investments. The Eastern Economic Corridor attracts automation equipment suppliers responding to skilled labor scarcity across traditional cannery workforces.
South Korea
Seoul Capital Area households displace traditional supermarket bulk purchasing through automated monthly delivery of curated tuna assortments. The Ministry of Food and Drug Safety enforces retort pouch safety standards and Extended Producer Responsibility frameworks for metal can recycling. Busan-Ulsan logistics clusters support refrigerated last-mile infrastructure enabling subscription channel growth.
Philippines
Century Pacific Food anchors domestic supply through branded retail dominance while competing in Middle East export channels where price sensitivity runs highest. Philippine canneries face retort operator skill scarcity that elevates training costs and audit failure rates under Japanese import compliance. Zamboanga and General Santos City concentrate tuna processing infrastructure with access to domestic fleet supply.
Vietnam
Underdeveloped canning infrastructure along Vietnam's central coast presents greenfield investment potential for exporters seeking tariff-advantaged ASEAN and EU market access. Domestic processors leverage lower mercury testing barriers for sardine grades compared to tuna species. Da Nang and Quy Nhon port zones attract cold-chain infrastructure investment serving contract manufacturing volumes.
Asia Pacific Canned Seafood Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Asia Pacific canned seafood, with concentration highest in Thai and Korean processing zones. The upper tier commands distant-water fleet access and domestic canning capacity that insulates against wild catch input volatility. Mid-tier specialists compete through retort pouch technology adoption and private-label contract manufacturing. Competitive moves concentrate on automation investment to offset labor scarcity and portfolio diversification into premium-grade solid-pack segments.
Within the integrated leader tier, Thai Union Group and Dongwon Industries occupy positions defined by captive supply chain control. Thai Union leverages cold-chain infrastructure across Thai and Indonesian waters, while Dongwon commands Korean shelf-stable tuna through fleet and canning integration. Century Pacific Food exemplifies the domestic-market anchor archetype, securing Philippine retail shelf space while building Middle East export presence. These three entities represent distinct strategic postures: transnational fleet integration, national champion verticalization, and emerging market retail dominance.
| Leading Market Players |
|---|
| Thai Union Group |
| Century Pacific Food |
| Nippon Suisan Kaisha |
| Dongwon Industries |
| Maruha Nichiro Corporation |
| Tri Marine Group |
| FCF Co. Ltd. |
| StarKist Co. |
| Bumble Bee Seafoods |
| Others |
Value Chain & Pricing Dynamics
Japan's Food Sanitation Act gates both supply qualification and price differentiation simultaneously, as histamine documentation requirements and bilingual labeling mandates create compliance tiers that separate premium-grade solid-pack tuna from flake and chunk grades destined for price-sensitive Southeast Asian households. Thai and Philippine exporters face SKU proliferation costs that concentrate pricing power among integrated processors with captive cold-chain infrastructure, while smaller Indonesian operators absorb margin compression from audit failure rates and training investments.
Pricing Analysis
Long-term offtake contracts dominate procurement between Thai canneries and Japanese import distributors, stabilizing input costs against skipjack and yellowfin tuna volatility under Western and Central Pacific Fisheries Commission negotiations. Pricing stratifies across premium, standard, and economy tiers driven by histamine certification grade and distant-water fleet traceability documentation. Cost compression in economy-grade flake tuna is intensifying because Philippine processors compete for Middle East export volumes where price sensitivity runs highest. Supermarket private-label buyers exhibit greatest price elasticity, while subscription pantry replenishment subscribers in Seoul and Tokyo absorb modest premiums for curated assortments.
Supply Chain Analysis
Inventory lead times stretch across archipelagic logistics corridors where refrigerated last-mile infrastructure remains unevenly deployed between Busan-Ulsan clusters and Philippine provincial distribution. Raw material supply concentrates in Thailand, the Philippines, and Indonesia, drawing from skipjack and yellowfin tuna stocks under regional fisheries management. Aluminum coil and food-grade tinplate feed from East Asian metal rollers, creating single-source vulnerability for can sheet specifications under China's GB standards and Japan's JIS requirements. Distribution runs through supermarket wholesale networks anchored by Thai Union and Century Pacific shelf-space control, with online retail gaining share where MFDS-registered cold-chain logistics enable subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as urban household pantry replenishment patterns stabilize following pandemic-era stockpiling distortions, with subscription channel growth in Seoul and Tokyo providing recurring revenue visibility for processors with captive logistics infrastructure.
For Market Incumbents: Fortify position by deepening automation investments across Samut Sakhon and Zamboanga processing zones to offset retort operator skill scarcity, while securing bilingual packaging line capacity to defend Japanese import channel access against emerging Vietnamese competitors. Threat of tariff-advantaged ASEAN sourcing from Da Nang greenfield investments demands proactive supplier qualification and Extended Producer Responsibility framework compliance ahead of South Korean and Japanese recycling mandate enforcement.
For New Entrants and Emerging Players: Subscription pantry replenishment service layers present white-space opportunity where incumbent processors under-serve younger Seoul and Tokyo demographics seeking automated monthly curation. Vietnam's central coast offers most penetrable geography for tariff-advantaged ASEAN and EU market access, with sardine grades benefiting from lower mercury testing barriers compared to tuna species. Go-to-market angle should emphasize retort pouch contract manufacturing for convenience store private-label SKUs, leveraging miniaturized batch-size technology to capture volumes from integrated multinationals.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across retort pouch technology adoption as flexible packaging formats reduce thermal processing cycle investments and enable smaller-footprint production lines. Long-term viability favors processors with backward integration into distant-water fleet control and cold-chain documentation systems spanning Thai and Indonesian waters. Acquisition target archetype: mid-tier Philippine or Vietnamese canneries with latent Japanese import compliance capacity and underutilized retort infrastructure. Signal to watch: Western and Central Pacific Fisheries Commission quota negotiation outcomes affecting skipjack input cost predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Technology Adoption | Flexible packaging formats enable 500-unit batch runs for private-label convenience store SKUs in Taiwan and Hong Kong. |
| Automation Investment in Processing Zones | Robotic filleting and sealing systems offset labor scarcity across Samut Sakhon and General Santos City canneries. |
| Extended Producer Responsibility Compliance | Closed-loop metal can recycling partnerships secure first-mover advantage under South Korean and Japanese mandates. |
| Cold-Chain Documentation Upgrades | Vessel-level traceability systems satisfy Japan's Food Sanitation Act histamine thresholds for premium import access. |
| Subscription Channel Infrastructure Buildout | MFDS-registered last-mile logistics capture recurring Seoul and Tokyo household demand for curated tuna assortments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing cannery operations managers at Thai Union and Century Pacific facilities, Japanese import distributor procurement leads, Seoul-based e-commerce platform logistics directors, and Philippine fisheries regulatory compliance officers. Secondary validation drew from Western and Central Pacific Fisheries Commission quota records, Japan's Ministry of Health Labour and Welfare import inspection data, South Korean MFDS retort pouch safety filings, and ASEAN customs trade statistics. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, packaging format, distribution channel, and end-user concentration, with additional modeling of regulatory compliance tier effects on trade flow patterns. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for urbanization rates and channel shift dynamics. Industry-specific forecast inputs included distant-water fleet catch volume projections and Extended Producer Responsibility framework implementation timelines.
Forecasts assume regulatory continuity in Japan's Food Sanitation Act, South Korea's MFDS standards, and China's GB retort pouch safety regimes; material policy shifts would require re-modeling of import access conditions and compliance cost structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Meal Market
Seafood
Canned Anchovy Market
Seafood
Canned Mackerel Market
Seafood
Middle East Seafood Market
Seafood
South America Canned Seafood Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
Fresh Fish Market
Seafood
Smoked Salmon Market
Seafood
Mussel Oil Market
Seafood
Tuna Market
Seafood
Global Smoked Fish Market
Seafood
Fish Protein Concentrate Market
Seafood
North America Frozen Seafood Market
Seafood
Organic Salmon Market
Seafood
Toothfish Market
Seafood
Surimi Market