
 Middle East Seafood Market | 2026-2036
Middle East Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Seafood Market Outlook
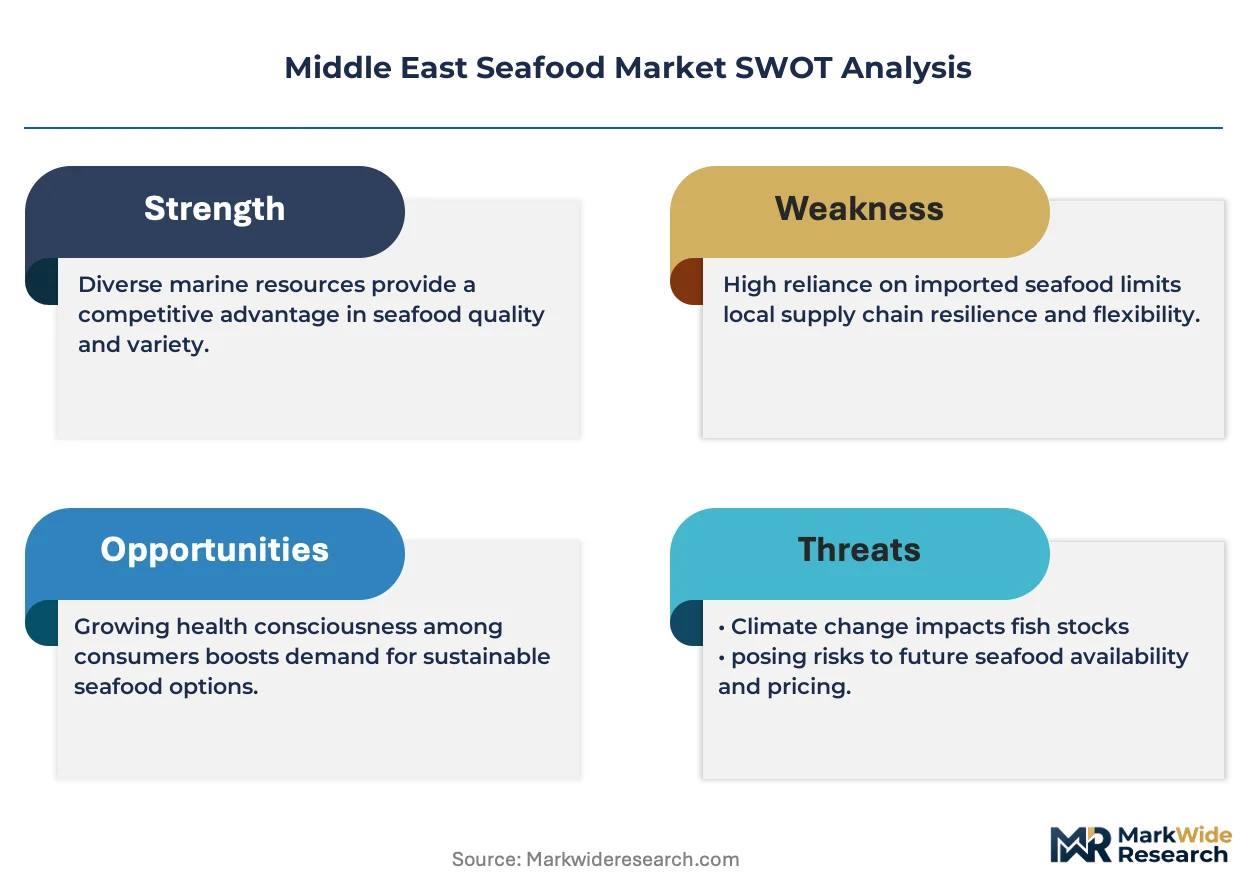
Recirculating aquaculture systems (RAS) technology is narrowing the cost gap between farmed and wild-caught supply across Arabian Peninsula operations. National Aquaculture Group (NAQUA) leverages its integrated hatchery-to-harvest infrastructure along the Red Sea coast to dominate domestic Saudi production. The Deep Seafood Company sustains its position through cold chain control across Gulf distribution corridors. Oman Fisheries Co. SAOG anchors its competitive stance on artisanal fleet access to the Sea of Oman and Indian Ocean waters.
Middle East seafood encompasses finfish, shellfish, and marine invertebrates harvested from marine, brackish, or controlled aquaculture environments, typically processed to moisture specifications below 80 percent for fresh trade or flash-frozen at minus 18 degrees Celsius for shelf stability, serving protein supply needs across hospitality, retail, and institutional channels. The fish segment occupies the largest volume share given per-capita familiarity and processing adaptability, while crustacean demand accelerates fastest among premium hospitality buyers in Dubai and Riyadh. Frozen form leads distribution economics due to Gulf climate constraints and import dependency, though fresh form commands margin concentration in high-turnover urban retail.
Saudi Food and Drug Authority (SFDA) standards govern import safety thresholds and aquaculture veterinary protocols, while UAE Ministry of Climate Change and Environment (MOCCAE) regulations enforce traceability mandates for Emirates-based distributors. These frameworks elevate compliance costs for smaller traders while creating structured pathways for certified producers to secure recurring supply contracts. Stakeholders must monitor how Gulf standardization bodies align halal certification requirements with evolving international sustainability benchmarks.
Market Dynamics
Recirculating aquaculture systems are compressing production costs for land-based finfish operations across the Arabian Peninsula, narrowing the historical premium against wild-caught supply and forcing wholesale price recalibration throughout Gulf distribution networks.
Growth Catalysts
- SFDA aquaculture licensing reforms:Saudi Arabia's streamlined permitting for Red Sea coastal farms is accelerating domestic output of barramundi and sea bream, reducing import dependency for hospitality supply chains.
- Tourism infrastructure multiplication:Hotel and restaurant chains across Dubai and Abu Dhabi are expanding cold storage capacity and menu diversification, pulling premium crustacean and finfish volumes through re-export hubs.
- RAS technology maturation:Closed-loop water treatment systems are cutting mortality rates and feed conversion ratios for indoor farms, enabling year-round production independent of seasonal wild catch fluctuations.
Market Restraints
- Feed input cost volatility:Soybean and fishmeal prices, denominated in US dollars, expose Gulf producers to currency fluctuation risks that compress margin predictability.
- Wild catch supply concentration:Artisanal fleet dependence in Omani and Yemeni waters creates volume instability for processors relying on Indian Ocean landing consistency.
- Halal certification fragmentation:Divergent interpretations between Gulf standardization bodies and international sustainability benchmarks create compliance friction for cross-border traders.
Strategic Opportunities
- Underpenetrated Saudi retail:Jeddah and Riyadh supermarket chains lack dedicated fresh seafood counters, presenting white space for cold chain investors to replicate UAE urban retail density.
- E-commerce direct-to-consumer channels:Flash-frozen subscription models are bypassing traditional wholesale layers, capturing margin from time-constrained households in Kuwait and Qatar.
- MOCCAE traceability mandates:Emirates-based distributors face compulsory blockchain-style documentation requirements, creating first-mover advantage for integrated producers with captive hatchery-to-retail data systems.
Industry Challenges
- RAS engineering talent scarcity:Water chemistry specialists and biofilter technicians command premium wages, constraining expansion timelines for new indoor farm projects.
- SFDA veterinary protocol compliance:Antibiotic residue testing and health certificate documentation create certification bottlenecks that delay harvest-to-market cycles for smaller Saudi operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Seafood Market |
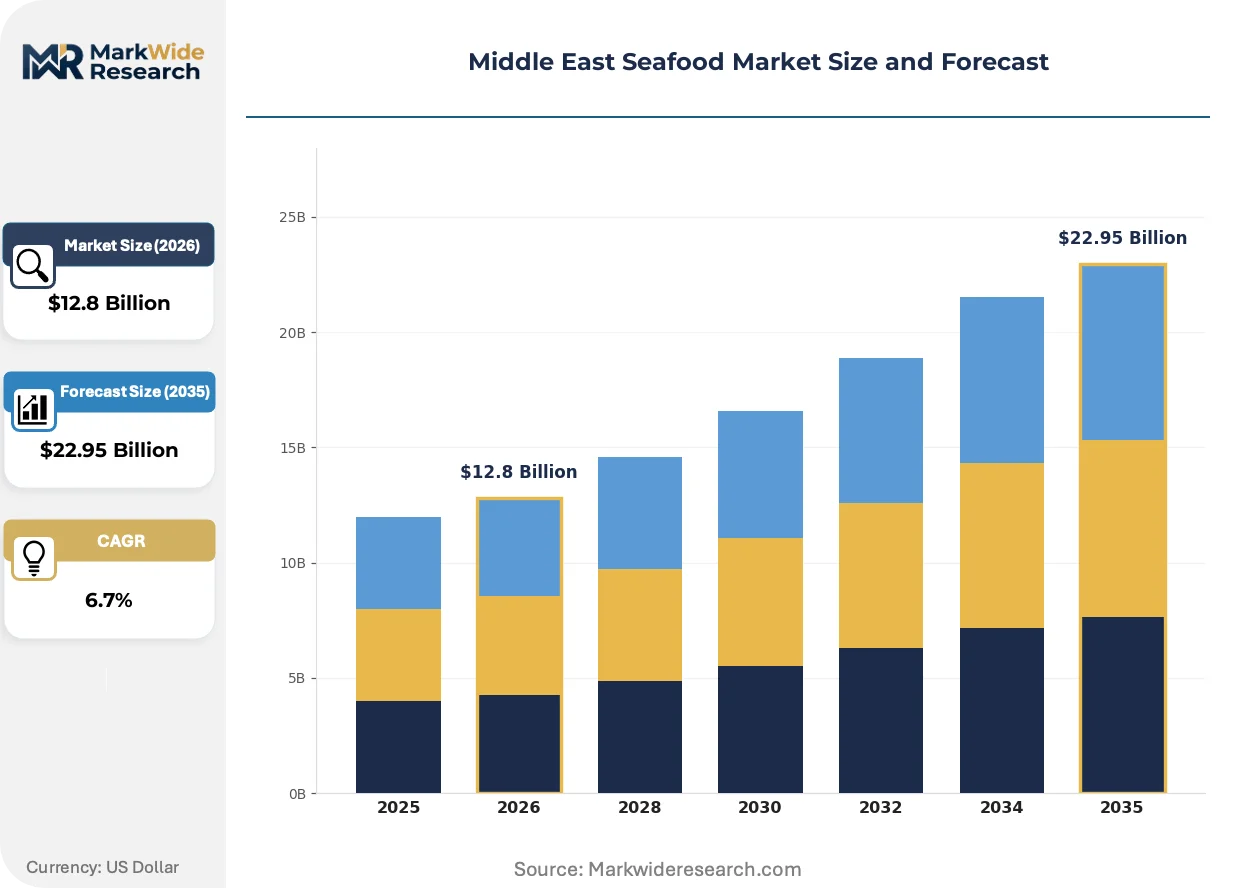
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Crustaceans, Mollusks, Cephalopods Distribution Channel: Retail, Wholesale, E-commerce, Food Service End User: Restaurants, Households, Hotels, Institutions Form: Fresh, Frozen, Dried, Canned |
| Companies Covered | Albatha Group, Sea Pride LLC, National Aquaculture Group (NAQUA), The Deep Seafood Company, National Fishing Company K.S.C., Saudi Fisheries Company, Al Munajem Foods, Enhance Group Holding Company Limited, Oman Fisheries Co. SAOG, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Seafood Market Strategic Shifts
Technology convergence between land-based recirculation and offshore cage systems is compressing the traditional wild-versus-farmed cost structure, while regulatory traceability mandates and shifting hospitality procurement patterns are redrawing competitive boundaries across Gulf supply chains.
Land-based recirculating aquaculture systems are hybridizing with solar-powered desalination infrastructure along Saudi Arabia's Red Sea coast, enabling NAQUA and emerging competitors to cut energy costs per kilogram of harvested biomass. Five-star hotel chains in Dubai are sourcing exclusively from RAS-certified suppliers, creating tiered supplier accreditation that excludes traditional open-water farms from premium contract pools.
MOCCAE traceability regulations now require Emirates-based distributors to maintain electronic records linking each batch to vessel or farm of origin, with inspection protocols enforced at Jebel Ali and Khalifa Port cold storage facilities. Smaller traders lacking integrated ERP systems face exclusion from government and hospitality tenders, consolidating contract access around capitalized operators with compliance infrastructure.
Hospitality procurement teams are consolidating supplier relationships around integrated cold chain operators capable of delivering both fresh and flash-frozen product lines under single contract frameworks. Dubai's cloud kitchen networks and Riyadh's fine-dining clusters are bypassing traditional wholesale fish markets, sourcing directly from processors with in-house logistics arms that guarantee temperature integrity across last-mile delivery.
Middle East Seafood Market Segmentation
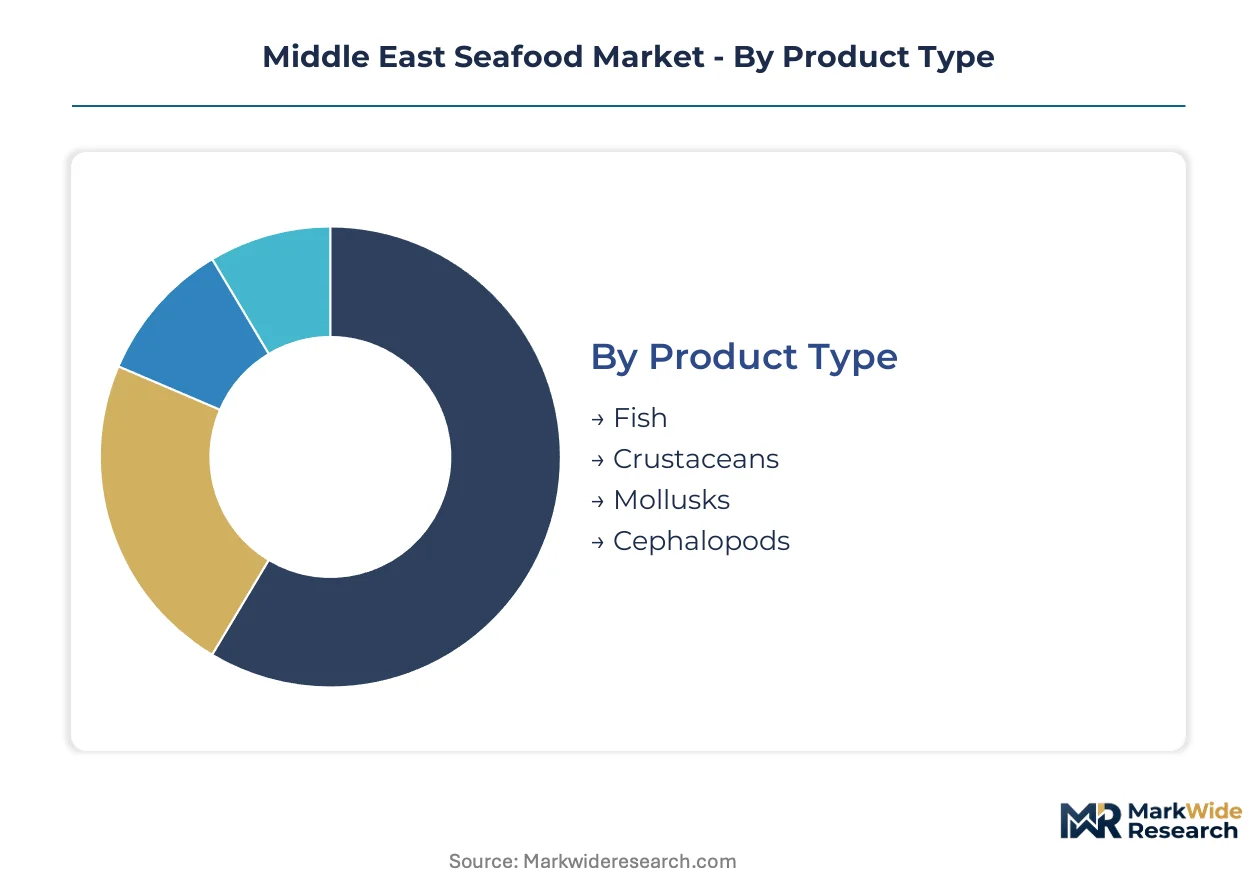
Segmentation in the Middle East seafood market reveals how Gulf climate constraints, import dependency, and hospitality procurement patterns reshape channel economics. Understanding these dimensions exposes where cold chain investment and regulatory compliance create sustainable margin positions.
Product Type:
Volume concentration across protein categories reflects processing adaptability, per-capita familiarity, and premium hospitality demand rotation in Dubai and Riyadh.
- Fish:Barramundi, sea bream, and hammour dominate procurement volumes given established filleting infrastructure and menu integration across UAE hotel chains. Saudi aquaculture licensing reforms under SFDA protocols are accelerating Red Sea farmed output, compressing import dependency for this core category.
- Crustaceans:Shrimp and lobster command the steepest price premiums, with five-star Dubai properties sourcing exclusively from RAS-certified suppliers to satisfy traceability mandates. MOCCAE blockchain-style documentation requirements are consolidating contract access around integrated producers with captive hatchery data systems.
- Mollusks:Oysters and mussels face narrower Gulf acceptance due to traditional preparation preferences, though Abu Dhabi fine-dining clusters are expanding raw bar formats.
- Cephalopods:Squid and octopus supply concentrates through Omani artisanal fleet landings, creating volume instability for processors dependent on Indian Ocean catch consistency.
Fish holds installed capacity. Crustaceans is rotating up the share rankings.
Distribution Channel:
Channel selection in Gulf markets hinges on temperature integrity guarantees and regulatory documentation depth rather than price alone.
- Retail:UAE supermarket chains maintain dedicated fresh seafood counters with live tank displays, while Saudi Jeddah and Riyadh operations remain underpenetrated, presenting white space for cold chain replication. Flash-frozen private label lines are capturing margin from time-constrained households.
- Wholesale:Traditional fish markets in Deira and Manama face bypass pressure as hospitality procurement teams consolidate around integrated operators capable of dual fresh-frozen delivery under single contract frameworks.
- E-commerce:Flash-frozen subscription models in Kuwait and Qatar are eliminating wholesale layers, with last-mile temperature guarantees determining platform survival.
- Food Service:Dubai cloud kitchen networks and Riyadh fine-dining clusters source directly from processors with in-house logistics arms, abandoning conventional market intermediaries.
Wholesale retains transaction volume density. E-commerce is climbing the fastest.
End User:
End-user procurement patterns expose where traceability certification and halal compliance create supplier tiering.
- Restaurants:Menu diversification across Dubai's hospitality sector is pulling premium crustacean and finfish volumes through re-export hubs, with RAS certification now a mandatory tender filter for five-star contracts.
- Households:Frozen form dominates residential purchase given Gulf climate constraints, though fresh counter penetration in UAE urban retail is establishing new consumption occasions.
- Hotels:Cold storage capacity expansion across Abu Dhabi and Doha properties is enabling larger spot purchases and reduced delivery frequency.
- Institutions:Government and corporate catering tenders in Saudi Arabia enforce SFDA antibiotic residue protocols that exclude smaller traders lacking integrated ERP documentation systems.
Restaurants command premium pricing power. Institutions is gaining compliance-driven share.
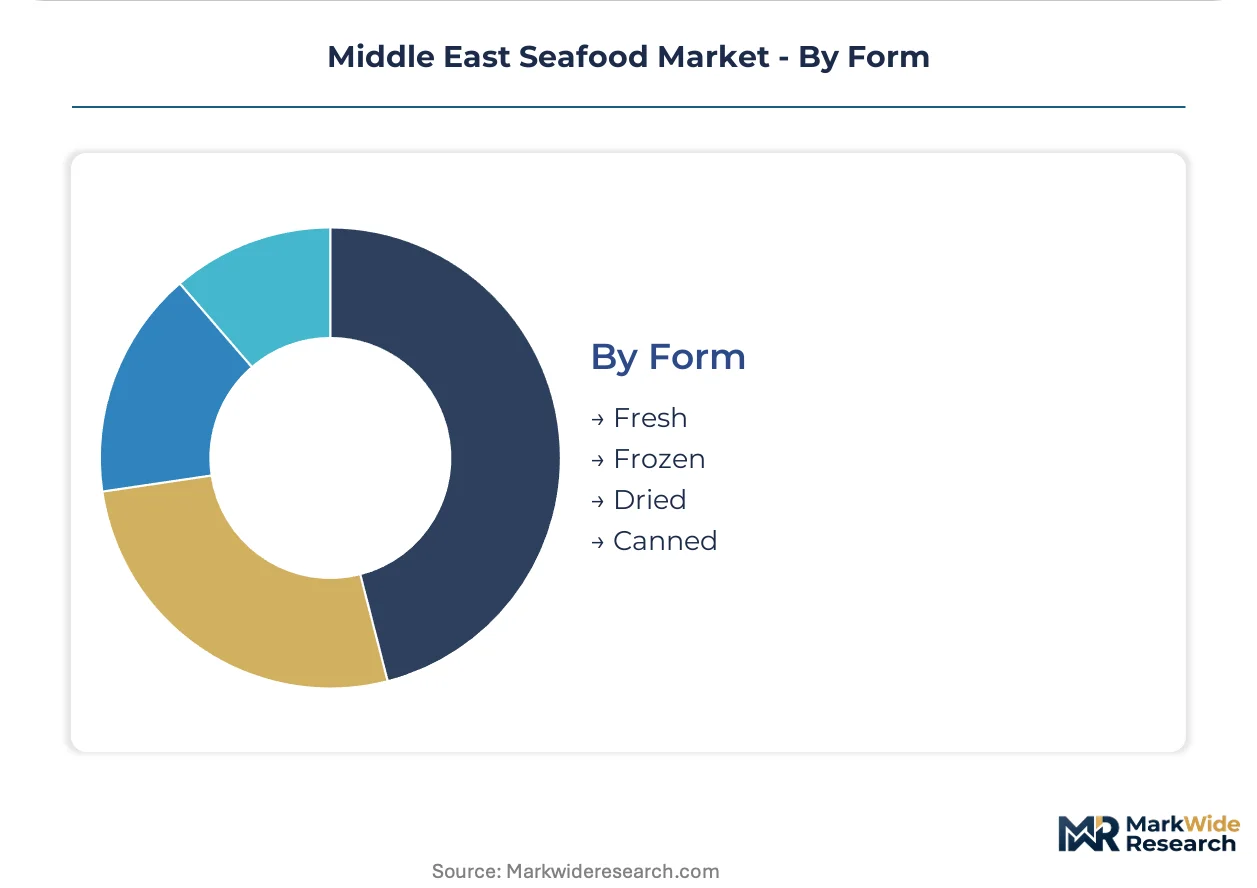
Form:
Form selection reflects climate logistics, shelf stability requirements, and margin capture potential across Gulf distribution economics.
- Fresh:High-turnover urban retail in Dubai and Abu Dhabi commands concentrated margin, with live tank infrastructure and same-day landing protocols creating service differentiation. Temperature excursions above 4 degrees Celsius trigger immediate spoilage liability.
- Frozen:Flash-frozen at minus 18 degrees Celsius, this form leads distribution economics due to import dependency and extended supply chains from Indian Ocean and Atlantic origins. Jebel Ali and Khalifa Port cold storage facilities enforce MOCCAE inspection protocols at entry.
- Dried:Traditional preservation for local species maintains niche demand in Bahrain and eastern Saudi markets, though limited scalability constrains commercial expansion.
- Canned:Shelf-stable tuna and sardine products serve institutional emergency stock requirements and price-sensitive retail segments with minimal cold chain burden.
Frozen maintains volume leadership. Fresh is expanding most quickly in premium urban nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE re-export corridors channel Indian Ocean and Atlantic catch into Saudi and Kuwaiti buyer networks, with Jebel Ali and Khalifa Port cold storage facilities processing the majority of Gulf transshipment volume.
United Arab Emirates
Dubai hospitality procurement and Abu Dhabi five-star hotel expansion pull premium crustacean volumes through re-export hubs. MOCCAE traceability mandates enforce blockchain-style documentation at port entry. Jebel Ali cold storage clusters consolidate distribution for GCC hospitality supply chains.
Saudi Arabia
Red Sea aquaculture licensing reforms accelerate domestic barramundi and sea bream output for Riyadh and Jeddah retail. SFDA veterinary protocols govern antibiotic residue testing and health certificate documentation. Western Region coastal farms near Jeddah integrate RAS infrastructure with solar-powered desalination.
Oman
Artisanal fleet landings from the Sea of Oman and Indian Ocean waters supply squid and octopus to regional processors. The national fisheries regulator enforces sustainable catch quotas for coastal vessels. Muscat-based processing clusters face volume instability from monsoon-season landing fluctuations.
Kuwait
Flash-frozen subscription models capture household demand from time-constrained urban consumers. Import dependency drives cold chain investment for last-mile temperature guarantees. Kuwait City retail networks expand dedicated seafood counter infrastructure.
Qatar
Hospitality procurement for Doha hotel chains concentrates around integrated operators with dual fresh-frozen delivery capability. Food security strategies prioritize supply chain resilience for institutional catering. Lusail development corridors anchor new cold storage capacity.
Middle East Seafood Market Competitive Environment
On the supply side, the industry is tiered between integrated aquaculture operators with captive hatchery infrastructure and import-dependent distributors controlling cold chain corridors. National champions dominate domestic production licensing while regional traders compete on port access and temperature integrity guarantees. Two strategic archetypes prevail: vertically integrated farm-to-retail producers and logistics-heavy re-export specialists. Competitive moves center on RAS technology licensing partnerships and backward integration into hatchery operations.
Among Saudi-based integrated producers, National Aquaculture Group (NAQUA) and Saudi Fisheries Company exemplify the captive infrastructure archetype with Red Sea coastal operations. UAE-focused distributors including The Deep Seafood Company occupy positions emphasizing cold chain control across Gulf corridors. Oman Fisheries Co. SAOG represents the artisanal fleet access model dependent on Indian Ocean landing relationships.
| Leading Market Players |
|---|
| Albatha Group |
| Sea Pride LLC |
| National Aquaculture Group (NAQUA) |
| The Deep Seafood Company |
| National Fishing Company K.S.C. |
| Saudi Fisheries Company |
| Al Munajem Foods |
| Enhance Group Holding Company Limited |
| Oman Fisheries Co. SAOG |
| Others |
Value Chain & Pricing Dynamics
Feed input cost volatility denominated in US dollars compresses margin predictability for Gulf producers while simultaneously widening pricing tier spreads between integrated RAS operators and import-dependent distributors. This currency exposure forces supply chain restructuring toward backward integration into hatchery operations and solar-powered desalination infrastructure to defend position.
Pricing Analysis
The current-generation RAS-certified supplier premium against prior-generation open-water farm supply is reshaping contract structures across Dubai five-star hospitality procurement. Pricing stratifies across premium RAS-certified, standard integrated cold chain, and economy traditional wholesale tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because currency fluctuation erodes landed cost predictability for import-dependent traders. Institutional catering buyers in Saudi Arabia exhibit highest price sensitivity due to SFDA compliance cost pass-through requirements, while premium hospitality buyers in Abu Dhabi show least sensitivity given menu positioning needs.
Supply Chain Analysis
Extended payment terms from hospitality procurement teams are squeezing working capital for smaller traders while supply-chain finance facilities consolidate around capitalized operators with integrated ERP documentation systems. Geographic supply concentration centers on Saudi Arabia for domestic aquaculture output, the UAE for re-export hub consolidation, and Oman for artisanal fleet landings. Raw material dependencies rest on soybean and fishmeal feed inputs, temperature-controlled logistics infrastructure, and desalinated water supply. Single-source vulnerability runs through Indian Ocean wild catch concentration for cephalopod processors. Distribution feeds from Jebel Ali and Khalifa Port cold storage clusters through integrated operator networks capable of dual fresh-frozen delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain as-a-service offerings are expanding faster than farmed biomass production, creating attach opportunities for operators with captive logistics infrastructure. Recurring revenue from temperature integrity guarantees and traceability documentation subscriptions outpaces hardware margins on harvesting equipment.
For Market Incumbents: Harden RAS certification moats by investing in blockchain-style hatchery-to-retail data systems that satisfy MOCCAE mandates and exclude non-compliant competitors from government tenders. Deepen upstream control over solar-powered desalination infrastructure to cut energy costs per kilogram and widen margin advantage against import-dependent distributors facing currency volatility. For New Entrants and Emerging Players: Pursue underpenetrated Saudi retail fresh counter infrastructure in Jeddah and Riyadh supermarket chains, replicating UAE urban density models. Target flash-frozen subscription channels in Kuwait and Qatar where last-mile temperature guarantees eliminate wholesale layers and capture household margin. Lead with direct-to-consumer platform positioning anchored on SFDA-compliant documentation transparency. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated cold chain operators with dual fresh-frozen capability and captive hatchery infrastructure. Long-term viability over a multi-year horizon rests on regulatory compliance depth rather than volume scale alone. Acquisition target archetype: mid-cap Saudi RAS producers with Red Sea coastal licensing and solar desalination integration. The signal to watch is SFDA enforcement intensity on antibiotic residue testing protocols as inflection indicator for competitive exclusion timing.| Strategic Initiative | Industry Significance |
|---|---|
| RAS Technology Licensing Partnership | Accelerates capacity buildout for Red Sea coastal farms seeking SFDA aquaculture permits. |
| Backward Integration into Hatchery Operations | Secures genetic stock control and cuts mortality rates for barramundi and sea bream production. |
| Cold Chain Infrastructure Expansion | Captures re-export hub consolidation at Jebel Ali and Khalifa Port for GCC hospitality supply. |
| Traceability System Deployment | Meets MOCCAE blockchain-style documentation mandates and locks in government tender access. |
| Solar Desalination Integration | Reduces energy cost per kilogram harvested for Saudi Red Sea coastal RAS operations. |
Study Parameters
Initial hypotheses were tested against primary input from aquaculture operations directors, hospitality procurement managers, cold chain logistics specialists, and SFDA regulatory affairs leads and refined through secondary validation. Primary fieldwork drew from hatchery technicians, port cold storage facility managers, and retail category buyers at UAE supermarket chains. Secondary sources included SFDA veterinary protocol filings, MOCCAE traceability regulation texts, customs landing data from Jebel Ali and Khalifa Port, and Red Sea coastal farm licensing records. Bottom-up volume modeling triangulated against top-down hospitality spending analysis across the analysis window.
Demand-supply balance framing anchored the forecast framework, with projected consumption from Dubai and Riyadh hospitality expansion tested against Saudi aquaculture licensing pipeline capacity and Indian Ocean wild catch landing consistency. Segmentation dimensions spanned product type, distribution channel, form, and end-user procurement pattern. CAGRs were derived from iterative reconciliation of production capacity buildout timelines and import dependency reduction targets. Industry-specific inputs incorporated RAS technology maturation curves and feed conversion ratio improvements from closed-loop water treatment systems.
Sensitivities concentrate around currency fluctuation in dollar-denominated feed inputs, SFDA enforcement intensity on antibiotic residue protocols, and monsoon-season landing volatility for Omani artisanal fleet supply. Forecasts reflect documented assumptions on tourism infrastructure multiplication rates and RAS engineering talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Salmon Market
Seafood
Fish Hydrolysate Market
Seafood
Herring Market
Seafood
North America Frozen Seafood Market
Seafood
Fish Protein Market
Seafood
Crayfish Market
Seafood
Edible Seaweed Market
Seafood
Tinned Fish Market
Seafood
Canned Anchovy Market
Seafood
Europe Lobster Market
Seafood
Crustacean Market
Seafood
Caviar Market
Seafood
Fish Meal Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Carp Market