
 Europe Shrimp Market | 2026-2036
Europe Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Shrimp Market Intelligence
Processing-margin pools is narrowing as raw material costs climb and retail price ceilings hold firm. Thai Union Group PCL ADR anchors its European position through integrated supply chains from Southeast Asian aquaculture zones. Nordic Seafood competes via specialized cold-chain distribution across Scandinavian markets. Clearwater Seafoods leverages its Arctic shrimp sourcing to differentiate on premium shellfish positioning.
Shrimp comprise decapod crustaceans of the suborder Pleocyemata, typically harvested at 20-30 grams per individual for commercial trade and processed through IQF freezing or cooked-peeled operations for foodservice and retail distribution. White Shrimp dominates European import volumes due to faster grow-out cycles and consistent fillet yield, while Tiger Shrimp occupies the premium tier in restaurant channels. Frozen form leads distribution through supermarket and fish market channels, though fresh product commands higher per-kilogram margins in Mediterranean coastal cities.
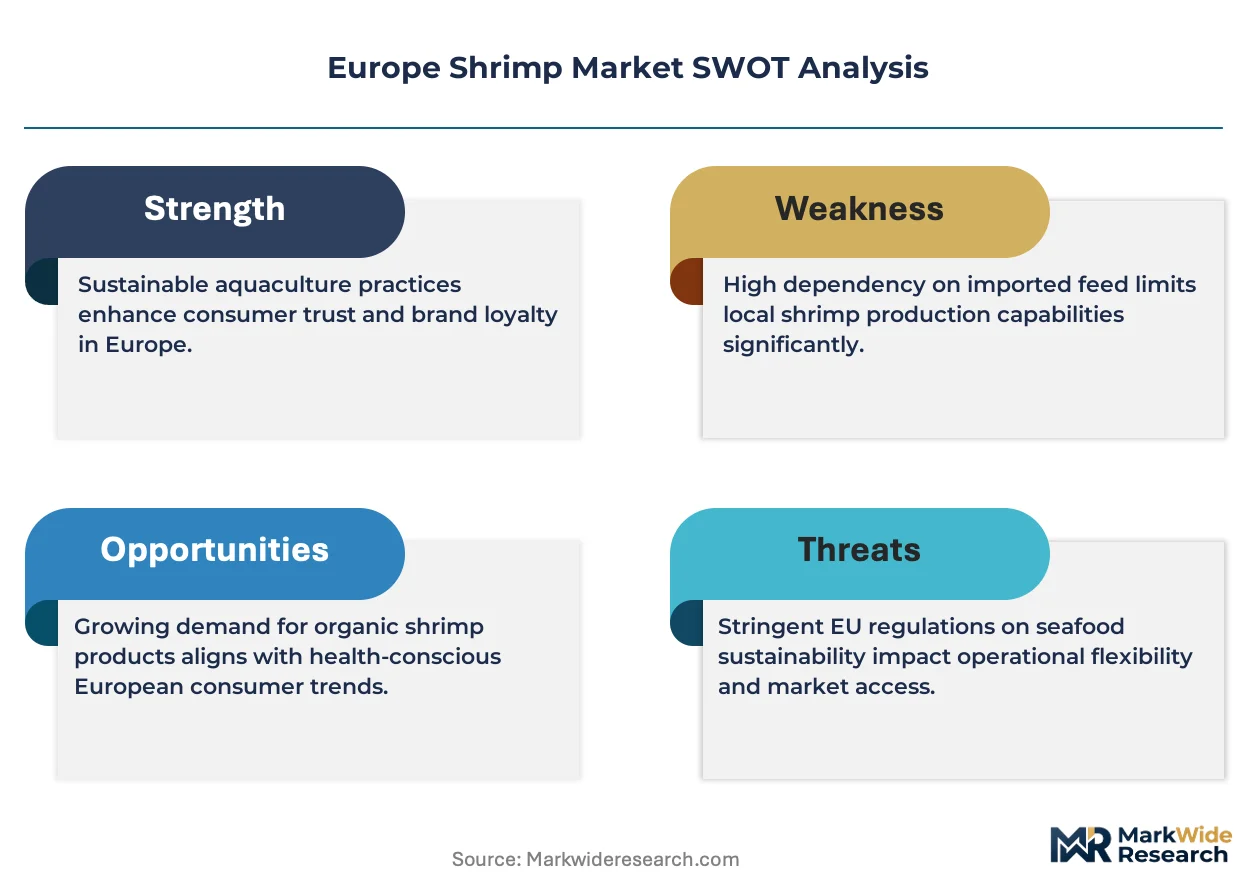
EFSA sets maximum residue limits for veterinary drugs in crustaceans, while EU import regulations under IUU fishing controls and REACH-aligned cold-storage chemical standards shape market access for non-European suppliers. The EU Green Deal's sustainable food system targets are pressuring processors to document supply chain provenance. Stakeholders must monitor how ECHA evolves biocide approvals for aquaculture equipment and whether the EU AI Act extends to automated shrimp grading systems.
Market Dynamics
EU Green Deal mandates are forcing processors to document supply chain provenance while ECHA tightens biocide approvals for aquaculture equipment, reshaping competitive positioning across the European shrimp trade.
Growth Catalysts
- EFSA residue limit enforcement:Stricter antibiotic testing protocols under EU food safety frameworks are filtering out non-compliant suppliers and consolidating market access for certified European distributors.
- Spain and Italy demand concentration:Per capita seafood consumption in these Mediterranean markets anchors import volumes and justifies dedicated cold-chain infrastructure investments.
- IQF freezing technology diffusion:Foodservice operators are expanding shrimp menu placements as individual quick freezing preserves product quality through extended distribution networks.
Market Restraints
- Raw material cost volatility:Southeast Asian aquaculture zone disruptions transmit directly into European processing-margin compression as retail price ceilings hold firm.
- Supply concentration risk:Dependence on Thai and Vietnamese farmed shrimp creates vulnerability to climate events and disease outbreaks in concentrated production regions.
- Substitution threat from plant-based seafood:European alt-protein startups are targeting shellfish analogues with improved texture profiles that compete at mid-market price points.
Strategic Opportunities
- Portuguese market underpenetration:Coastal cities with established fish market culture represent expansion white space for fresh shrimp distribution beyond frozen dominance.
- EU AI Act automation pathway:Automated shrimp grading systems present compliance-aligned investment opportunities as the regulation extends to food processing equipment.
- Direct-to-foodservice channel innovation:Bypassing traditional wholesale layers through specialized cold-chain partnerships captures margin currently absorbed by intermediaries.
Industry Challenges
- Antibiotic residue testing skill gaps:Laboratory capacity for ECHA-mandated crustacean screening is concentrating in Germany and the Netherlands, creating regional bottlenecks.
- REACH-aligned cold-storage capex intensity:Chemical storage standard upgrades require facility reinvestment that squeezes mid-tier processors without integrated supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Shrimp Market |
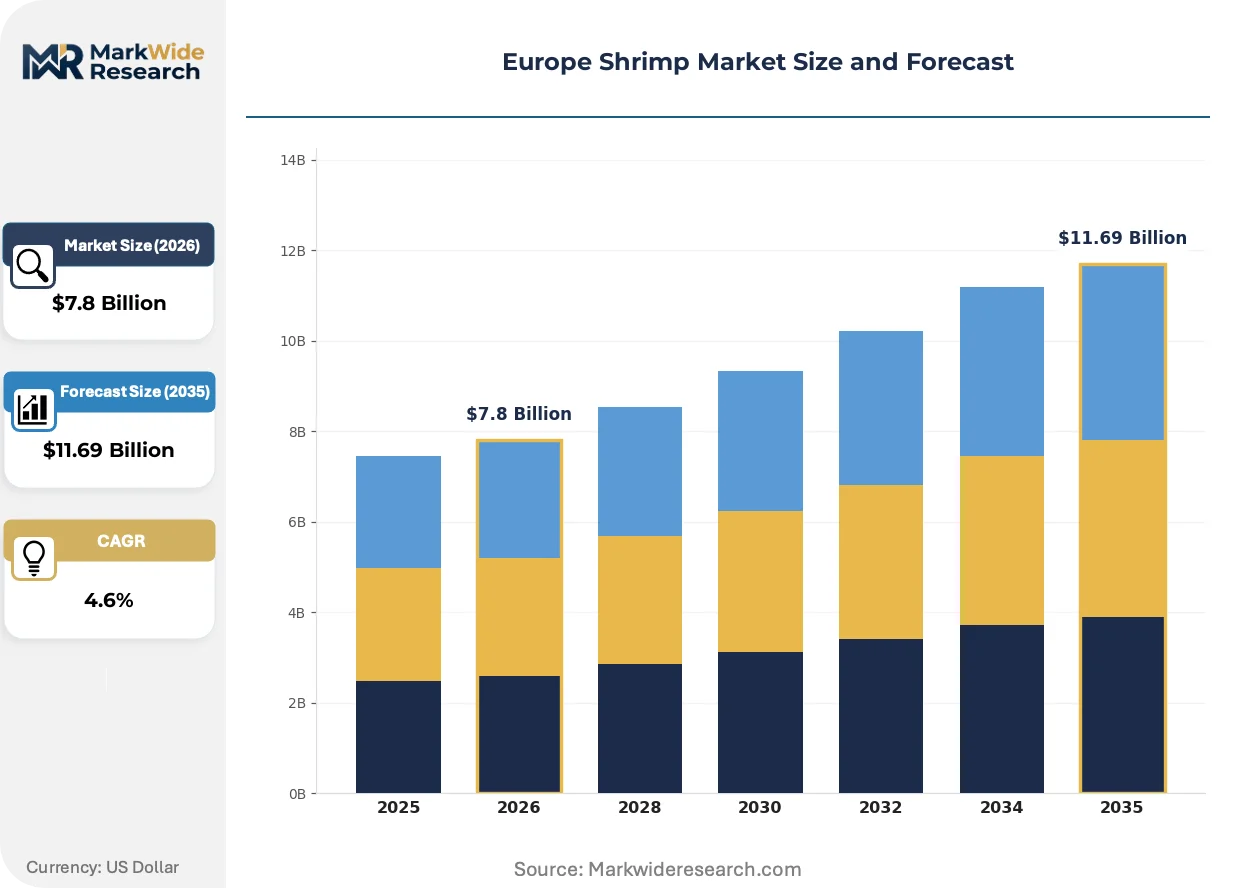
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prawns, Blue Shrimp, White Shrimp, Tiger Shrimp Form: Frozen, Fresh, Dried, Cooked Distribution Channel: Supermarkets, Online Retail, Restaurants, Fish Markets End User: Households, Foodservice, Exporters, Seafood Processors |
| Companies Covered | High Liner Foods, Avanti Feeds, Thai Union Group PCL ADR, Aqua Star, Nordic Seafood, Pescanova, Clearwater Seafoods, Waterbase, Surapon Foods, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Shrimp Market Strategic Shifts & Innovations
Digital traceability platforms and automation are compressing traditional quality assurance timelines while regulatory pressure accelerates sustainable sourcing verification across European shrimp supply chains.
Blockchain-enabled provenance tracking is virtualizing the documentation layer that previously required paper-based chain-of-custody records. Major Spanish retail distributors are piloting these systems for frozen shrimp lots sourced from Southeast Asian aquaculture zones. The technology is virtualizing compliance costs by automating EFSA audit trails and reducing manual verification labor.
EU Green Deal sustainable food system targets are mandating carbon footprint disclosure for imported seafood categories. Processors must now calculate and report transportation and cold-storage emissions to maintain supermarket shelf access. Arctic shrimp suppliers leveraging shorter supply routes are capturing premium positioning in Scandinavian markets.
Foodservice procurement is consolidating toward fewer, larger suppliers capable of delivering certified sustainable volumes at scale. Independent restaurant operators in Italy are forming buying cooperatives to meet minimum volume thresholds for direct import contracts. This concentration is most visible in Barcelona and Milan, where distributor consolidation has accelerated post-pandemic.
Europe Shrimp Market Segmentation
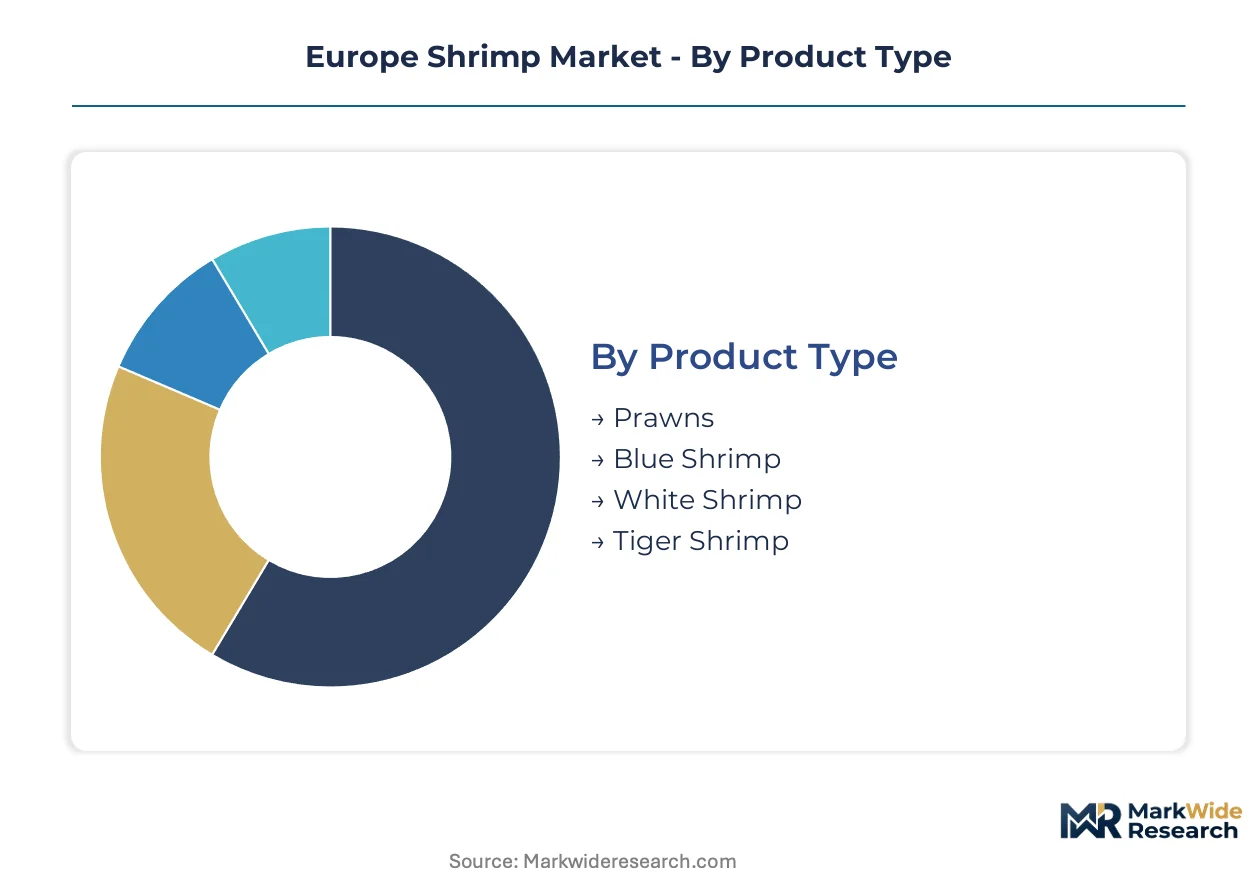
European shrimp procurement patterns diverge sharply across product types and forms, with cold-chain capabilities and regulatory compliance requirements determining viable segment combinations for each buyer category. Distribution channel selection directly constrains which product-form pairings reach specific end-user groups.
Product Type:
After-sales service intensity varies substantially across shrimp categories, with live-holding technical support and traceability documentation demands scaling with product perishability and certification tier.
- White Shrimp:Fast grow-out cycles and consistent fillet yield make this the default choice for high-volume foodservice contracts. Demand concentrates in Spanish and Italian retail and restaurant channels where price-sensitive procurement dominates import volumes.
- Tiger Shrimp:Larger average size and distinctive striping command premium positioning in Mediterranean restaurant channels. Coastal cities in Italy and Spain absorb disproportionate volumes for grilled and plated presentations where visual differentiation justifies higher per-kilogram pricing.
- Prawns:Cold-water species with firmer texture profile serve specialized Nordic and British retail markets requiring extended shelf-life performance.
- Blue Shrimp:Limited European penetration due to restricted aquaculture zone availability and higher production cost base relative to white shrimp alternatives.
White Shrimp holds the largest share; momentum sits with Tiger Shrimp in premium restaurant channels.
Form:
Cost tier stratification separates investment-grade cold-chain infrastructure from ambient-capable alternatives, with margin structures inversely correlated with storage complexity.
- Frozen:IQF technology preserves individual integrity through extended distribution networks, enabling supermarket and fish market penetration across landlocked European regions. This form anchors volume through Thai and Vietnamese supply chains where integrated freezing operations at origin minimize downstream handling costs.
- Fresh:Higher per-kilogram margins concentrate in Mediterranean coastal cities with established wholesale fish market infrastructure. Barcelona, Marseille, and Genoa maintain dedicated fresh shrimp auction halls where daily landed volumes determine spot pricing.
- Cooked:Ready-to-serve preparation reduces foodservice labor costs and supports grab-and-go retail formats in urban convenience store networks.
- Dried:Shelf-stable preservation enables ethnic grocery channel placement with minimal cold-chain dependency, serving diaspora communities in London, Paris, and Berlin.
Frozen commands volume leadership; fresh product is climbing the fastest in margin contribution terms.
Distribution Channel:
Customer type concentration shapes channel viability, with institutional procurement scale requirements filtering out fragmented supply alternatives.
- Supermarkets:Centralized buying desks at Carrefour, Ahold Delhaize, and Mercadona demand certified sustainable volumes with blockchain traceability documentation. EFSA compliance records and EU Green Deal carbon disclosure are mandatory for shelf access.
- Restaurants:Independent operators in Milan and Barcelona are consolidating into buying cooperatives to meet direct import minimums, bypassing traditional wholesale markups.
- Fish Markets:Traditional wholesale halls in Marseille, Genoa, and Hamburg maintain fresh shrimp auction systems where daily landed volumes determine spot pricing for restaurant and retail buyers.
- Online Retail:Home delivery platforms are expanding frozen shrimp SKU ranges as last-mile cold-chain investments mature in metropolitan markets.
Supermarkets hold the largest share; online retail is gaining share fastest among emerging channels.
End User:
Application maturity separates price-elastic household consumption from specification-driven industrial procurement with dedicated technical account management requirements.
- Foodservice:Chain restaurants and institutional caterers specify IQF frozen product with consistent sizing grades for menu cost control. ECHA-mandated residue documentation is non-negotiable for contract eligibility.
- Seafood Processors:Value-added operations in Germany and the Netherlands demand raw material with precise moisture content and defect rate specifications for breaded and sauced product lines.
- Households:Retail purchase decisions prioritize convenience formats and recognizable sustainability certifications over origin-specific attributes.
- Exporters:Re-export operations in Rotterdam and Hamburg require EU-imported product with full traceability documentation for onward shipment to non-European destinations.
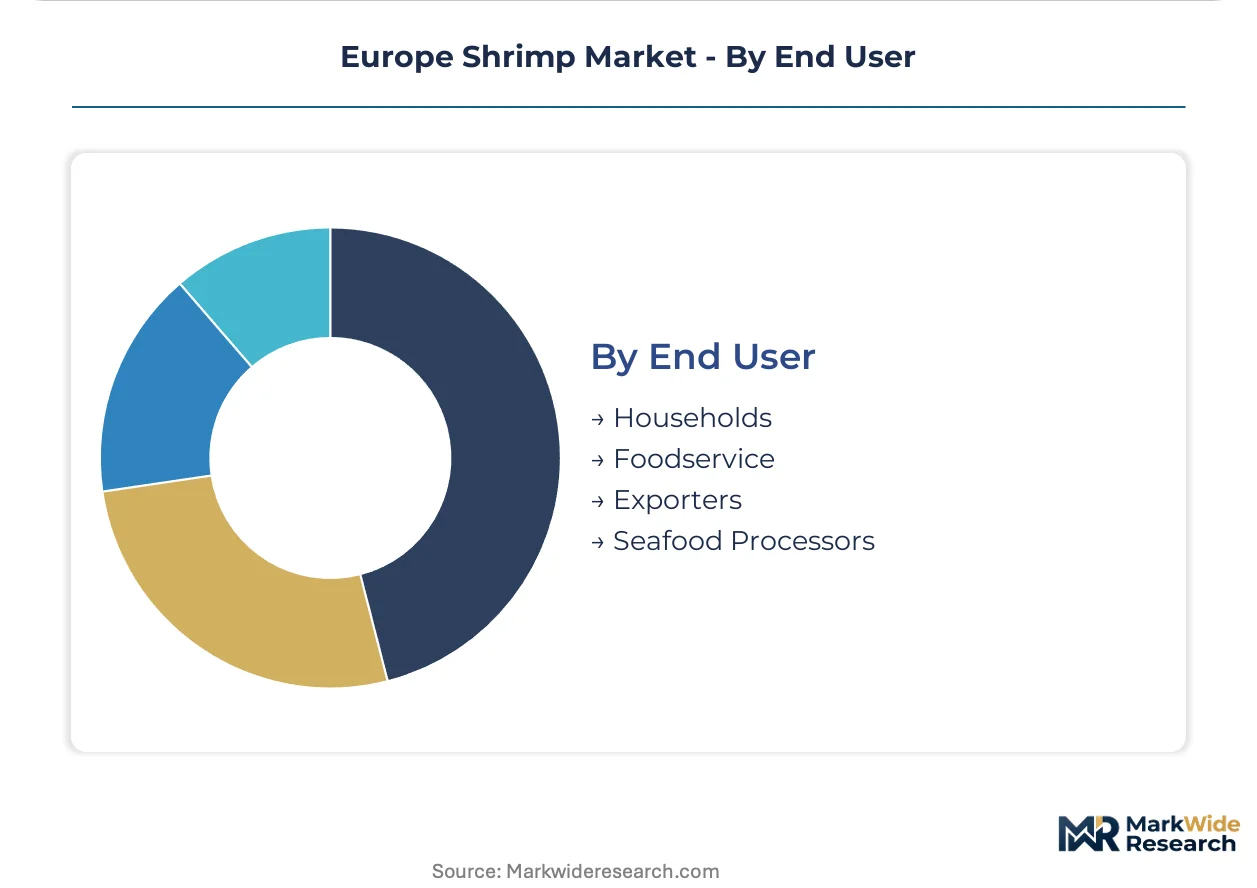
Foodservice holds the largest share; seafood processors show steepest expansion trajectory in value-added input demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish and Italian buyers exhibit the lowest price elasticity in Europe, absorbing premium Tiger Shrimp for restaurant plating, while German and Dutch procurement desks enforce rigid cost ceilings that compress supplier margins.
Spain
Mediterranean per capita seafood consumption sustains the continent's largest shrimp import volumes, with Barcelona's wholesale fish markets commanding fresh product premiums. EFSA residue documentation requirements filter non-compliant Southeast Asian suppliers from Mercadona and Carrefour shelf access. Valencia's processing corridor concentrates IQF freezing operations serving Iberian foodservice chains.
Italy
Milan restaurant cooperatives consolidate procurement to bypass traditional wholesale markups, driving direct import contract growth. REACH-aligned cold-storage chemical standards force facility upgrades among mid-tier distributors in Emilia-Romagna. Genoa maintains dedicated fresh shrimp auction infrastructure where daily landed volumes determine spot pricing for Ligurian seafood retailers.
Germany
Centralized retail buying at Edeka and Rewe demands blockchain traceability and EU Green Deal carbon disclosure for frozen shrimp shelf placement. ECHA-mandated antibiotic testing capacity concentrates in Hamburg and Bremen laboratories, creating regional compliance bottlenecks. The Port of Rotterdam-re-export corridor feeds German value-added processors with traceable raw material.
Netherlands
Rotterdam's cold-storage hub function positions Dutch traders as gatekeepers for onward EU distribution, with full documentation required for re-export to non-European destinations. CSRD sustainability reporting obligations pressure processors to calculate transportation and storage emissions. Urk's seafood processing cluster specializes in breaded and sauced shrimp lines for Northern European retail.
France
Marseille's traditional wholesale halls preserve fresh shrimp auction systems for Provençal restaurant buyers resistant to frozen substitution. ANSM pharmaceutical residue monitoring extends EFSA frameworks to border inspection protocols. The Grand Ouest processing belt in Brittany concentrates cooked-peeled operations for urban convenience store networks in Paris.
Europe Shrimp Market Key Industry Players
Capability concentration sits with integrated aquaculture-to-retail operators; scale advantage sits with diversified seafood conglomerates. Thai Union Group PCL ADR anchors volume leadership through captive Southeast Asian farming operations. Nordic Seafood and Clearwater Seafoods occupy specialized cold-water sourcing niches. Competitive dynamics center on backward integration into aquaculture zones and certification-heavy retail contract capture.
Within the integrated supply chain tier, Thai Union Group PCL ADR represents scale-driven vertical control from farming through European distribution. Nordic Seafood and Clearwater Seafoods exemplify geographic specialization strategies—Arctic and cold-water sourcing for premium positioning in Scandinavian markets. Pescanova occupies a distinct Iberian footprint. These three anchors demonstrate how provenance documentation and cold-chain custody separate viable suppliers from commodity traders.
| Leading Market Players |
|---|
| High Liner Foods |
| Avanti Feeds |
| Thai Union Group PCL ADR |
| Aqua Star |
| Nordic Seafood |
| Pescanova |
| Clearwater Seafoods |
| Waterbase |
| Surapon Foods |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Hamburg reefer corridor anchors cost dynamics for frozen shrimp moving into German retail, with freight rate volatility amplifying margin pressure on mid-tier distributors while Arctic-origin suppliers leverage shorter routes to capture premium positioning in Scandinavian markets. ECHA-mandated cold-storage chemical upgrades add facility-level cost burdens that stratify pricing power between integrated operators and fragmented traders.
Pricing Analysis
After-sales revenue from traceability documentation and residue testing services drives lifetime value for certified distributors serving Edeka and Rewe procurement desks. Three-tier pricing structure across premium, standard, and economy levels separates Arctic wild-catch Tiger Shrimp from Vietnamese farmed White Shrimp and unbranded commodity lots. Cost compression in the standard tier is intensifying because Thai Union's captive farming operations compress competitor margins. German retail buyers enforce the strictest price ceilings, while Milan restaurant cooperatives absorb premium markups for provenance-verified product.
Supply Chain Analysis
Upstream feedstock from Thai and Vietnamese aquaculture zones supplies roughly three-quarters of European frozen shrimp import volumes. Production hinges on juvenile stock from specialized hatcheries, formulated feed from agricultural commodity markets, and veterinary inputs subject to EFSA residue limits. Single-source vulnerability concentrates in the Mekong Delta, where climate disruption and disease outbreaks transmit rapidly into European spot price spikes. Distribution runs through Rotterdam's cold-storage hub for onward re-export and direct German retail supply, with fresh product bypassing this node via Barcelona and Genoa auction halls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail procurement desks at Carrefour, Ahold Delhaize, and Mercadona, with supermarket concentration squeezing supplier margins while fragmenting restaurant cooperatives struggle to match direct import scale thresholds.
For Market Incumbents: Build regulatory compliance moats through EFSA-certified laboratory partnerships in Hamburg and Bremen that mid-tier competitors cannot replicate. Anchor backward integration into Southeast Asian farming operations to defend against raw material cost spikes. Capture channel control via blockchain traceability platforms that automate audit trails for Mercadona shelf access. For New Entrants and Emerging Players: Build out fresh shrimp distribution infrastructure in Portuguese coastal cities where frozen product dominance has left wholesale fish market culture underexploited. Target Barcelona and Marseille auction hall relationships as the most penetrable entry point for Mediterranean restaurant supply. Pursue direct-to-foodservice partnerships that bypass traditional wholesale markups through specialized cold-chain logistics. For Investors and Strategic Acquirers: Cold-water sourcing specialists with Arctic shrimp concessions and established Nordic retail relationships represent the most defensible acquisition archetype for premium segment exposure. Long-term viability rests on provenance documentation capabilities that align with EU Green Deal carbon disclosure mandates. Watch ECHA biocide approval tightening as the inflection signal for aquaculture equipment capex intensity that favors scaled operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Operations | Captive supply from Thai aquaculture zones insulates Thai Union from spot price volatility and EFSA compliance bottlenecks. |
| Blockchain Traceability Deployment | Spanish retail distributors pilot distributed ledger systems to automate EFSA audit trails and reduce manual verification labor. |
| Direct-to-Foodservice Channel Development | Milan restaurant cooperatives consolidate procurement to bypass wholesale markups and capture margin currently absorbed by intermediaries. |
| Arctic Sourcing Premium Positioning | Clearwater Seafoods leverages shorter supply routes and cold-water texture profiles for Scandinavian supermarket shelf differentiation. |
| Automated Grading System Investment | EU AI Act compliance-aligned equipment upgrades present first-mover advantages in labor cost reduction and sizing consistency. |
Research Approach
Initial hypotheses were tested against primary input from aquaculture operations managers, European retail category buyers, cold-chain logistics directors, and EFSA compliance officers, and refined through secondary validation against customs trade records, ECHA regulatory filings, EU import statistics, and seafood processor SEC disclosures. Bottom-up volume modeling from individual country import flows was triangulated against top-down market sizing from aggregated retail scanner data.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, form, distribution channel, and end-user application dimensions. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated ECHA biocide approval timelines and EU Green Deal carbon disclosure implementation phases.
Stress conditions across Southeast Asian climate disruption, EFSA residue limit enforcement intensity, and Rotterdam cold-storage capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against EUMOFA seafood market monitoring data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Canned Fishery Product Market
Seafood
North America Salmon Market
Seafood
Smoked Salmon Market
Seafood
Seafood Takeout Market
Seafood
Crayfish Market
Seafood
Tinned Fish Market
Seafood
Carp Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Fresh Fish Market
Seafood
Herring Market
Seafood
Fish Protein Concentrate Market
Seafood
Surimi by-Product Market
Seafood
Asia-Pacific Seafood Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
Krill Meal Market
Seafood
Japan Lobster Market