
 Groundfish Market | 2026-2036
Groundfish Market Size, Share, and Industry Trends Forecast 2026-2036
Groundfish Market Outlook
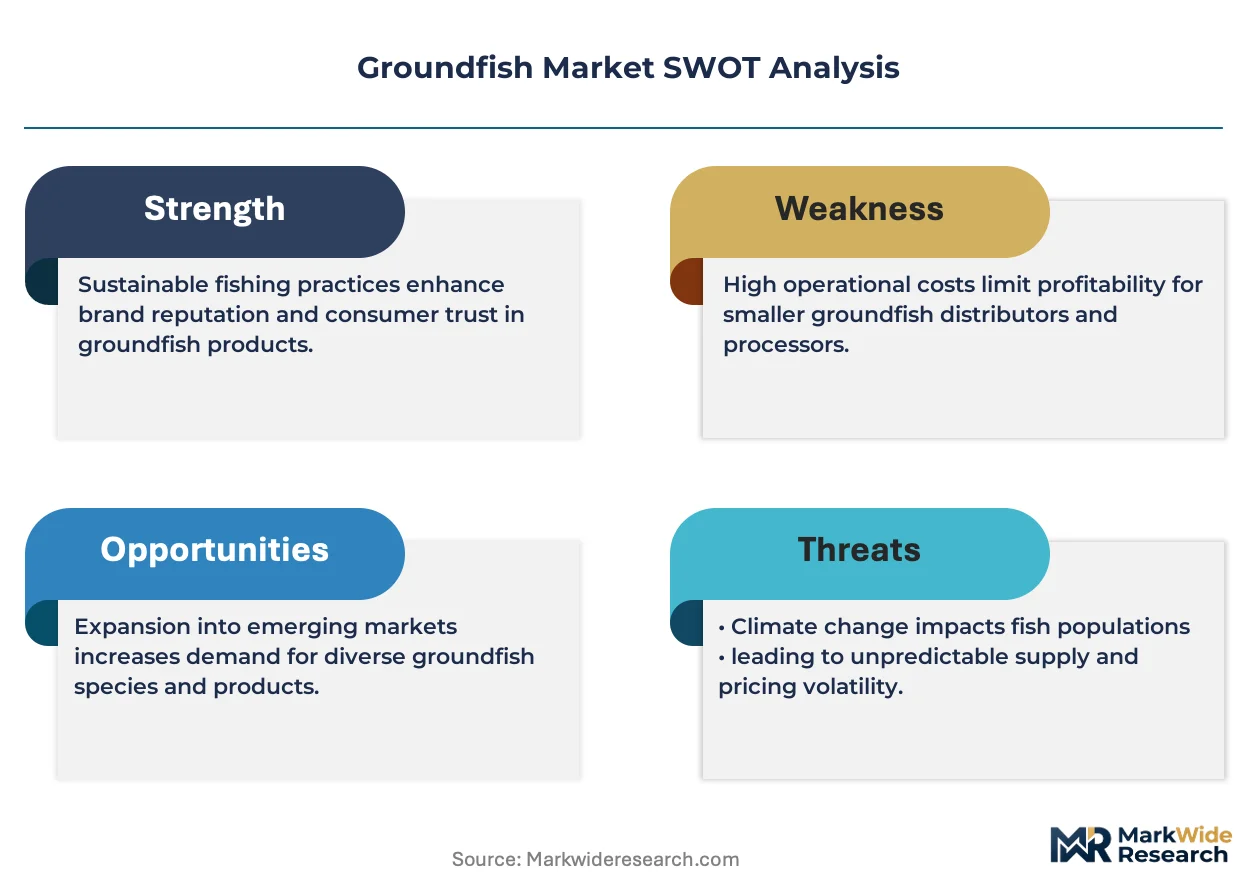
Marine Stewardship Council certification is collapsing as the decisive gate for supplier access to European retail chains. Trident Seafoods Corp. leverages its Alaska-based vertical integration to control pollock and cod supply from harvest through frozen fillet production. Royal Greenland anchors its competitive position through dominance of North Atlantic halibut and Greenland halibut quotas. High Liner Foods Inc. differentiates via specialized value-added breaded and sauced groundfish products for foodservice.
Groundfish comprises demersal fish species inhabiting seabed environments, characterized by white flaky flesh with protein content typically ranging from 15-20% and low fat profiles under 3%, primarily serving human consumption markets as fresh fillets, frozen blocks, or processed preparations. Cod and haddock lead volume throughput in North Atlantic supply chains where mature catch quotas constrain expansion, while flounder and sole attract premium pricing in European white-tablecloth restaurants. Trawling remains the dominant capture method for industrial-scale operations, though longlining gains share in sustainability-differentiated segments commanding higher unit margins.
The EU's Common Fisheries Policy, NOAA Fisheries Magnuson-Stevens Act provisions, and MSC chain-of-custody standards collectively shape allowable catch volumes, seasonal access windows, and market eligibility for groundfish suppliers across the Atlantic basin. Norway's Directorate of Fisheries implements stringent individual transferable quota systems that directly determine which vessels and processors can operate at economically viable scale. Stakeholders must monitor quota negotiation outcomes between coastal states and certification body rulings on stock sustainability to anticipate supply availability and pricing trajectories.
Market Dynamics
Individual transferable quota systems in Norway, Iceland, and the United States are concentrating harvest rights among fewer vessel operators and shoreside processors, fundamentally restructuring competitive access to Atlantic cod and Alaska pollock supply chains.
Growth Catalysts
- EU Green Deal sustainable protein targets:Retail chains across Germany, France, and the Netherlands face binding sustainability commitments that favor MSC-certified groundfish over farmed alternatives, redirecting procurement budgets toward verified wild-catch supply.
- Flash-freezing at sea technology:Onboard processing systems installed on Norwegian and Icelandic trawlers extend product shelf life by 40% versus traditional shore-based freezing, opening distant-water harvest zones to European retail distribution.
- Foodservice rebound in coastal tourism corridors:Restaurant demand in Portugal, Spain, and Italy's Mediterranean ports is recovering pre-pandemic volumes for fresh haddock and sole fillets, tightening spot-market availability during peak summer months.
Market Restraints
- Fuel cost volatility:Diesel prices for distant-water trawlers operating Barents Sea and Bering Sea grounds consume 25-35% of voyage economics, compressing margins when Brent crude exceeds threshold levels.
- Quota concentration in Norwegian processing clusters:Three coastal municipalities control 60% of North Atlantic cod quota rights, creating supply bottlenecks for independent processors lacking vertical integration into harvest.
- Plant-based whitefish analogues:Mycoprotein and legume-based fillet products from Netherlands and UK manufacturers are capturing shelf space in British and Scandinavian retail, pressuring price positioning for commodity frozen blocks.
Strategic Opportunities
- Direct-to-restaurant distribution in Poland and Czech Republic:These Central European markets show 15% annual growth in white-tablecloth seafood consumption with underdeveloped cold-chain infrastructure, rewarding early entrants with specialized logistics.
- Blockchain traceability integration:Combining IoT sensors with distributed ledger systems enables real-time catch documentation from hook to plate, satisfying French hypermarket chains demanding granular provenance data.
- Alaska pollock roe and surimi value extraction:Japanese and South Korean buyers pay premiums for specialized grades currently underutilized by North American processors focused on block production.
Industry Challenges
- MSC certification audit timelines:Stock assessment delays and certificate suspension procedures for Barents Sea cod fisheries create 12-18 month eligibility gaps that freeze supplier access to EU retail contracts.
- Deckhand recruitment in remote processing ports:Norwegian and Alaskan shore plants face chronic labor shortages for filleting and pin-bone removal operations, limiting capacity utilization during peak seasonal landings.
- Legacy ERP integration with catch documentation systems:Mid-sized processors struggle to reconcile decades-old inventory platforms with new EU IUU regulation digital reporting requirements, forcing costly system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Groundfish Market |
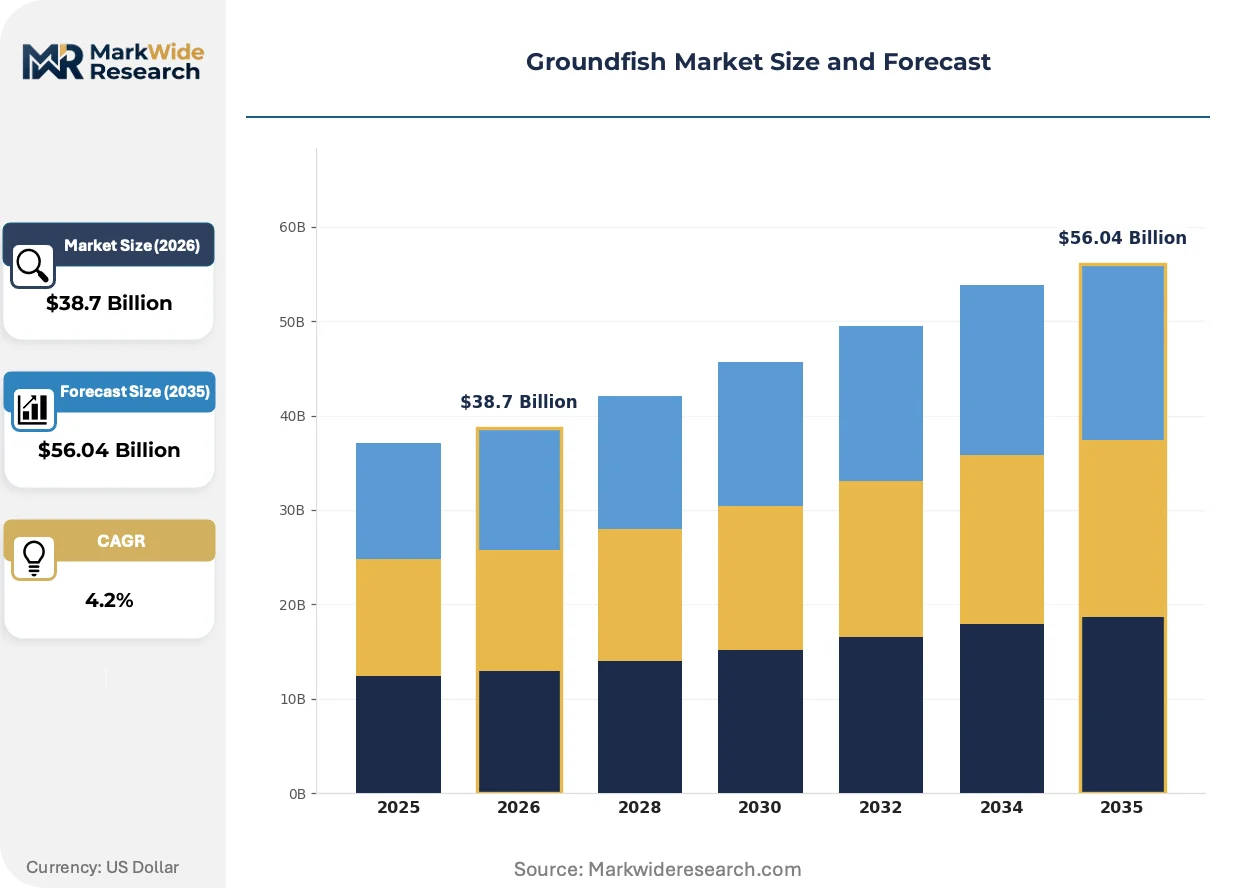
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flounder, Haddock, Cod, Sole Capture Method: Trawling, Longlining, Gillnetting, Purse Seining End User: Restaurants, Retail Chains, Seafood Processors, Institutions Sales Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | American Seafoods Group LLC, Trident Seafoods Corp., High Liner Foods Inc., Mowi ASA, Royal Greenland, Nomad Foods Ltd, Performance Food Group, Nissui Corp., Surapon Foods Public Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Groundfish Market Strategic Shifts
Automation and digital verification systems are compressing labor dependence and documentation latency across groundfish supply chains, while regulatory complexity and buyer sophistication are simultaneously raising barriers to market participation.
Autonomous longline systems equipped with AI-powered species recognition cameras are displacing traditional manned trawling in Iceland's haddock fisheries. These platforms reduce fuel consumption by 30% while improving target-species selectivity. Norwegian cooperatives are deploying the technology fastest, capturing sustainability premiums from German retail buyers who now require automated bycatch documentation.
The EU's Corporate Sustainability Reporting Directive now mandates seafood importers to disclose scope 3 emissions from distant-water fleets supplying their frozen fillet operations. This creates compliance burdens for Spanish and Portuguese traders sourcing from West African processing hubs. Large Nordic retailers are responding by shortening supply chains to Iceland and Norway, where vessel-level fuel data is already digitized.
Chef-driven procurement collectives in London, Copenhagen, and Amsterdam are bypassing traditional wholesale auctions to contract directly with Icelandic and Faroese day-boat operators. These arrangements guarantee specific line-caught freshness grades. The model is compressing working capital cycles for small-scale harvesters while fragmenting volume commitments previously captured by major distributors.
Groundfish Market Segmentation
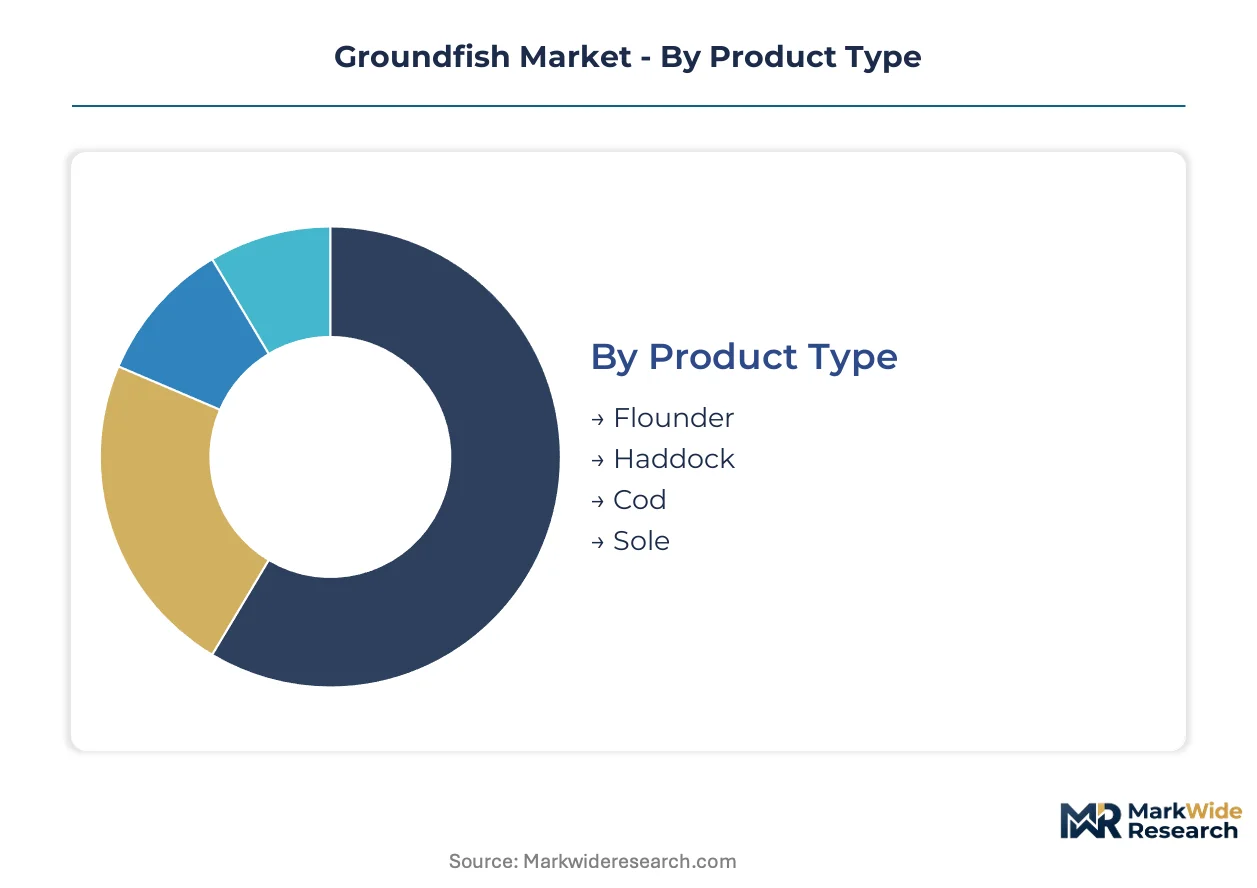
Groundfish market segmentation reveals where value capture diverges from volume flow. Processing economics, quota ownership structures, and certification requirements reshape profitability across each dividing line.
Product Type:
Margin pools concentrate in species facing quota scarcity and premium positioning in foodservice channels.
- Flounder:Flatfish species with delicate texture and low oil content, commanding premium pricing in white-tablecloth establishments across France and Spain. Demand concentrates in Mediterranean port cities where day-boat freshness grades justify menu premiums, though Barents Sea supply constraints limit volume expansion.
- Haddock:Firm white flesh with distinctive flavor profile, dominating British fish-and-chip shops and Scandinavian retail freezer cases. Scottish and Icelandic day-boat landings capture sustainability premiums from UK supermarket chains enforcing MSC chain-of-custody requirements.
- Cod:Standard-setting species for groundfish texture and yield, facing mature catch quotas across the North Atlantic basin. Norwegian and Russian Barents Sea allocations determine global supply availability.
- Sole:Thin, delicate fillets preferred in French and Belgian haute cuisine, with Dover sole landings concentrated in English Channel ports. Channel quota negotiations between UK and EU coastal states directly shape pricing.
Cod holds installed capacity across frozen block production. Haddock is rotating up the share rankings in sustainability-differentiated retail channels.
Capture Method:
Capital intensity and fuel economics separate profitable operations from marginal vessels in each technique category.
- Trawling:Industrial-scale demersal netting with high volume throughput but elevated bycatch ratios. Barents Sea and Bering Sea operations face fuel cost pressures consuming voyage economics when diesel prices spike.
- Longlining:Baited hook systems targeting specific species with minimal habitat disruption, capturing 15-20% price premiums from German and Dutch retail buyers demanding automated bycatch documentation. Icelandic cooperatives deploy AI-powered autonomous systems fastest.
- Gillnetting:Passive netting with lower capital requirements, concentrated in coastal day-boat fleets supplying fresh markets in Portugal and Galicia.
- Purse Seining:Surface encirclement technique rarely applied to demersal species, limited to seasonal aggregations in specific grounds off West Africa.
Trawling holds installed capacity across distant-water factory vessels. Longlining is climbing the fastest in sustainability-premium contract structures.
End User:
Working capital cycles and specification rigor determine processor alignment with each buyer category.
- Restaurants:Chef-driven procurement collectives in London, Copenhagen, and Amsterdam now contract directly with Icelandic day-boat operators, bypassing traditional wholesale auctions. These arrangements demand specific line-caught freshness grades and compress payment cycles.
- Retail Chains:German, French, and Dutch supermarkets enforce binding sustainability commitments under EU Green Deal protein targets, redirecting procurement budgets toward MSC-certified wild-catch supply.
- Seafood Processors:Norwegian and Alaskan shore plants face chronic labor shortages for filleting operations, limiting capacity utilization during peak seasonal landings.
- Institutions:Hospital, school, and military catering contracts prioritize frozen block stability and price predictability over provenance documentation.
Retail chains hold installed capacity across MSC-certified supply contracts. Restaurants are gaining share fastest in direct-to-harbor procurement models.
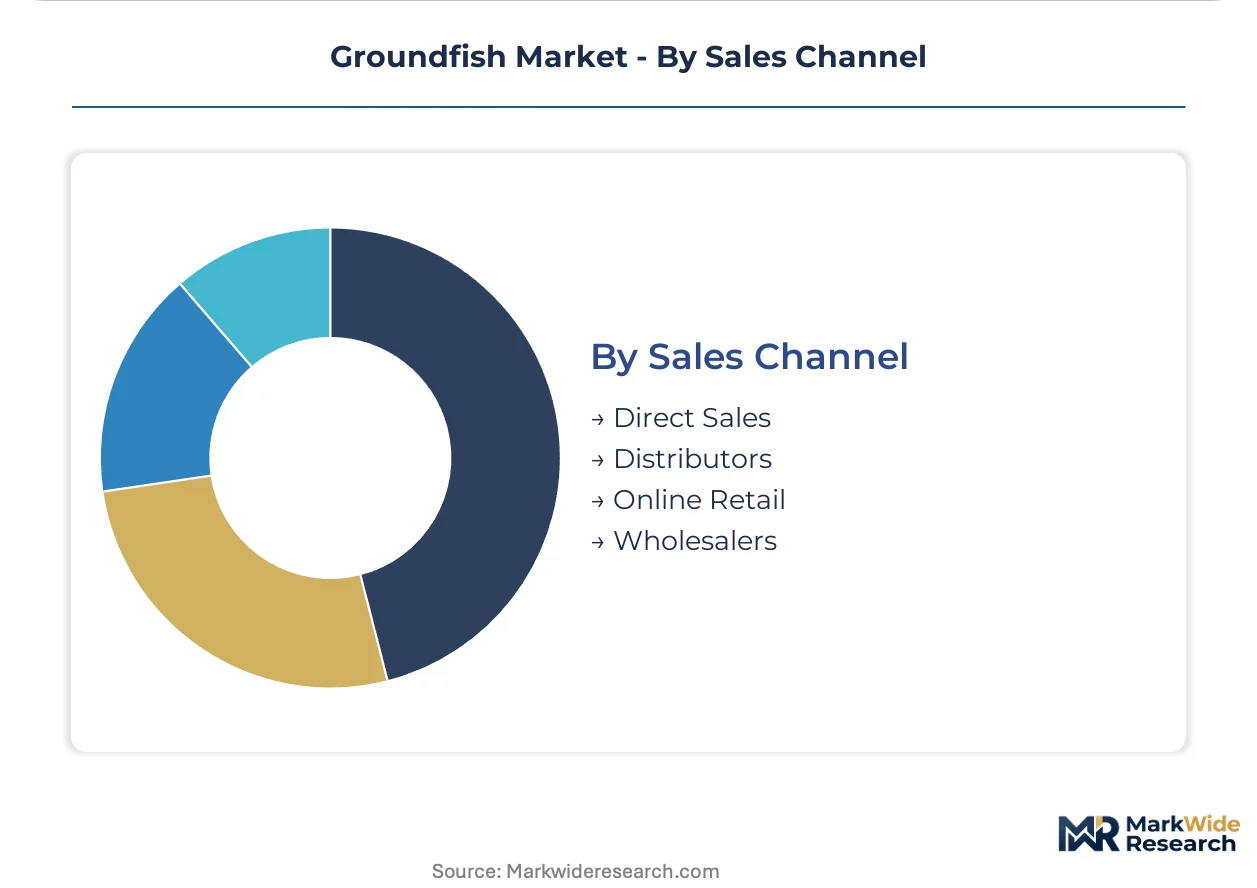
Sales Channel:
Traceability requirements and lot-size economics reshape channel profitability as documentation burdens intensify.
- Direct Sales:Processor-to-buyer arrangements eliminating intermediary margins, concentrated in Norwegian vertical integration models controlling quota through captive vessel fleets.
- Distributors:Temperature-controlled logistics specialists managing last-mile delivery to foodservice accounts, facing margin compression from fuel cost volatility.
- Online Retail:Emerging channel for premium fresh fillet home delivery, constrained by cold-chain infrastructure gaps in Central European markets.
- Wholesalers:Traditional auction-based volume clearing, losing share to direct contracting as buyer sophistication increases.
Distributors hold installed capacity across fragmented foodservice accounts. Direct sales are expanding most quickly in quota-integrated supply structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's sustainable protein targets redirect procurement budgets across member states toward verified wild-catch supply. Norway's Directorate of Fisheries administers individual transferable quotas that determine viable operating scale for Atlantic cod processors. Processing clusters in three Norwegian coastal municipalities control the majority of North Atlantic cod quota rights.
Norway
German and Dutch retail buyers demand automated bycatch documentation from Norwegian suppliers. The Directorate of Fisheries implements stringent individual transferable quota systems. Tromsø and surrounding coastal municipalities concentrate 60% of North Atlantic cod quota rights, creating supply bottlenecks for independent processors.
United States
NOAA Fisheries Magnuson-Stevens Act provisions shape allowable catch volumes and seasonal access windows. The act's conservation mandates constrain expansion in Alaska pollock and Pacific cod fisheries. Dutch Harbor and Kodiak processing clusters face chronic labor shortages for filleting operations during peak seasonal landings.
Iceland
Scottish and UK supermarket chains enforce MSC chain-of-custody requirements that favor Icelandic day-boat landings. The country's fisheries ministry supports autonomous longline system deployment with AI-powered species recognition. Reykjavik-based cooperatives capture sustainability premiums through automated bycatch documentation.
United Kingdom
Chef-driven procurement collectives in London contract directly with day-boat operators for specific line-caught freshness grades. Post-Brexit quota negotiations with EU coastal states directly shape Dover sole pricing and availability. Grimsby and Hull processing ports handle North Sea haddock landings for domestic fish-and-chip shop supply.
Spain
Restaurant demand in Mediterranean ports recovers pre-pandemic volumes for fresh haddock and sole fillets during peak summer months. The country's national fisheries regulator enforces documentation requirements for distant-water fleet operations. Vigo and A Coruña serve as primary processing hubs for West African-sourced groundfish.
Groundfish Market Competitive Environment
Player mix skews toward vertically integrated harvest-to-retail conglomerates controlling quota rights through captive vessel fleets. Three structural tiers operate: scale-driven block producers, sustainability-differentiated premium fillet specialists, and value-added prepared food manufacturers. Dominant competitive moves include backward integration into quota ownership and geographic expansion into underdeveloped Central European cold-chain markets.
Among North American harvest-to-processor conglomerates, American Seafoods Group LLC and Trident Seafoods Corp. exemplify scale-driven archetypes with Alaska-based vertical control. Royal Greenland occupies a position within the premium-tier vector as a quota-integrated North Atlantic halibut specialist. These three represent contrasting strategic postures: volume throughput maximization, sustainability-premium capture, and species-specific quota dominance.
| Leading Market Players |
|---|
| American Seafoods Group LLC |
| Trident Seafoods Corp. |
| High Liner Foods Inc. |
| Mowi ASA |
| Royal Greenland |
| Nomad Foods Ltd |
| Performance Food Group |
| Nissui Corp. |
| Surapon Foods Public Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of cold-storage inventory in Norwegian processing clusters concentrates pricing power among quota-integrated operators while forcing independent buyers into volatile spot markets for Atlantic cod and haddock. This inventory banding directly ties to the EU's IUU regulation compliance timelines, which delay customs clearance for non-digitized catch documentation and compress margins for processors lacking backward integration into vessel fleets.
Pricing Analysis
Certification level creates the primary spread between commodity frozen blocks and premium fresh fillets, with MSC chain-of-custody status commanding 15-20% uplifts from German retail buyers. Three-tier pricing structure separates line-caught day-boat grades from trawler-caught shore-frozen lots and commodity block production, though plant-based whitefish analogues from Netherlands manufacturers are intensifying cost compression in the economy tier. Foodservice institutions exhibit highest price sensitivity due to frozen block standardization, while chef-driven procurement collectives in London and Copenhagen show lowest sensitivity for documented freshness grades.
Supply Chain Analysis
Barents Sea ice-edge transit windows constrain annual harvest volumes and concentrate processing capacity in Tromsø, Murmansk, and Reykjavik coastal municipalities. North Atlantic supply chains draw from diesel-dependent distant-water trawlers, AI-automated longline cooperatives, and Icelandic day-boat fleets, with fuel cost volatility representing the dominant structural risk compressing voyage economics. Distribution runs through temperature-controlled logistics specialists serving fragmented foodservice accounts, though direct processor-to-retail contracting is displacing traditional wholesale auction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Central European cold-chain infrastructure creates entry niches as Polish and Czech restaurant demand outpaces specialized logistics supply. Chef-driven procurement collectives bypassing traditional distributors reward agile operators with freshness-grade documentation capabilities.
For Market Incumbents: Secure captive quota rights through vessel fleet acquisitions or long-term leasing arrangements with Norwegian coastal municipalities, insulating against the 60% supply concentration in three processing clusters. Invest in flash-freezing at sea technology to extend shelf life and access distant-water harvest zones, while automating bycatch documentation to defend MSC certification status against audit suspension risks. For New Entrants and Emerging Players: Lead with blockchain-integrated traceability platforms targeting French hypermarket chains demanding granular provenance data, a segment where legacy ERP systems burden mid-sized processors. Target Poland and Czech Republic white-tablecloth channels through specialized cold-chain partnerships, exploiting 15% annual consumption growth and underdeveloped infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium capture play because EU Green Deal protein targets redirect procurement budgets toward verified wild-catch supply with decade-long regulatory tailwinds. Target quota-integrated processors with digitized catch documentation and established MSC chain-of-custody contracts. Monitor MSC certification audit timelines for Barents Sea cod fisheries as the critical inflection signal, where 12-18 month eligibility gaps freeze supplier access and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Quota Rights Consolidation | Captures supply bottlenecks in Norwegian coastal municipalities controlling North Atlantic cod allocations. |
| Flash-Freezing at Sea Deployment | Extends product shelf life and opens distant-water harvest zones to European retail distribution. |
| Blockchain Traceability Integration | Satisfies French hypermarket chains demanding granular provenance data from hook to plate. |
| Autonomous Longline System Adoption | Reduces fuel consumption by 30% while improving target-species selectivity for sustainability premiums. |
| Central European Cold-Chain Expansion | Captures 15% annual growth in Polish and Czech white-tablecloth seafood consumption. |
Study Parameters
Desk research of customs trade databases, EU Common Fisheries Policy quota registries, and NOAA Fisheries landings statistics preceded structured interviews with Norwegian vessel operators, Alaskan shore plant managers, German retail category buyers, and French foodservice procurement directors. Primary fieldwork validated secondary findings on processing capacity utilization and certification audit timelines, with bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across species, capture method, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions included product type differentiation, quota ownership structures, certification requirements, and channel-specific traceability burdens. CAGRs derived from historical landings trends, quota negotiation outcomes between coastal states, and elasticity estimates for fuel cost pass-through to fillet pricing.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or MSC certification continuity would require recalibration. Forecasts reflect assumptions on quota stability, diesel price bands, and labor availability in remote processing ports. Practitioners should keep alternative scenarios live as Barents Sea stock assessments and Brexit-era Channel quota negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Lobster Market
Seafood
Mussel Oil Market
Seafood
North America Seafood Market
Seafood
Wild Pollock Market
Seafood
Europe Shrimp Market
Seafood
Smoked Whiting Market
Seafood
Frozen Seafood Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Global Shrimp Market
Seafood
Tuna Fish Market
Seafood
Haddock Market
Seafood
Japan Frozen Seafood Market
Seafood
Global White Shrimp Market
Seafood
Alaskan Salmon Market
Seafood
Oyster Meal Market
Seafood
Fresh Fish Market