
 Fish Protein Hydrolysate Market | 2026-2036
Fish Protein Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Protein Hydrolysate Market Analysis
Marine Stewardship Council chain-of-custody certification is unwinding competitive access across European and North American supply chains. Bio-Marine Ingredients Ireland leverages its Irish coastal processing network to dominate regional supply. Scanbio Marine anchors its position through captive fleet partnerships and integrated enzymatic hydrolysis infrastructure. Omega Protein sustains volume leadership via Gulf of Mexico menhaden fisheries and backward integration into rendering operations.
Fish protein hydrolysate denotes a mixture of peptides and free amino acids produced by enzymatic or acid hydrolysis of fish muscle and viscera, typically yielding 70-90% protein content with molecular weight distributions below 10 kDa for bioactive applications. Powdered hydrolysates command premium positioning in nutraceutical formulations where solubility and shelf stability determine formulation economics. Liquid hydrolysates occupy mature volume pools in aquaculture feed applications where cost-per-protein-unit drives procurement decisions. Spray-dried variants represent the fastest-growing format as sports nutrition brands demand clean-label, instantized protein ingredients.
EFSA novel food authorizations and FDA GRAS self-affirmation pathways shape market access timelines for new hydrolysate entrants targeting human consumption. REACH compliance for enzymatic processing aids and EU MDR traceability requirements for marine-sourced ingredients add compliance layers that favor established processors with dedicated regulatory affairs functions. Stakeholders must monitor evolving EPA fisheries management quotas and NMPA import registration requirements as supply security becomes inseparable from sustainability certification credibility.
Market Dynamics
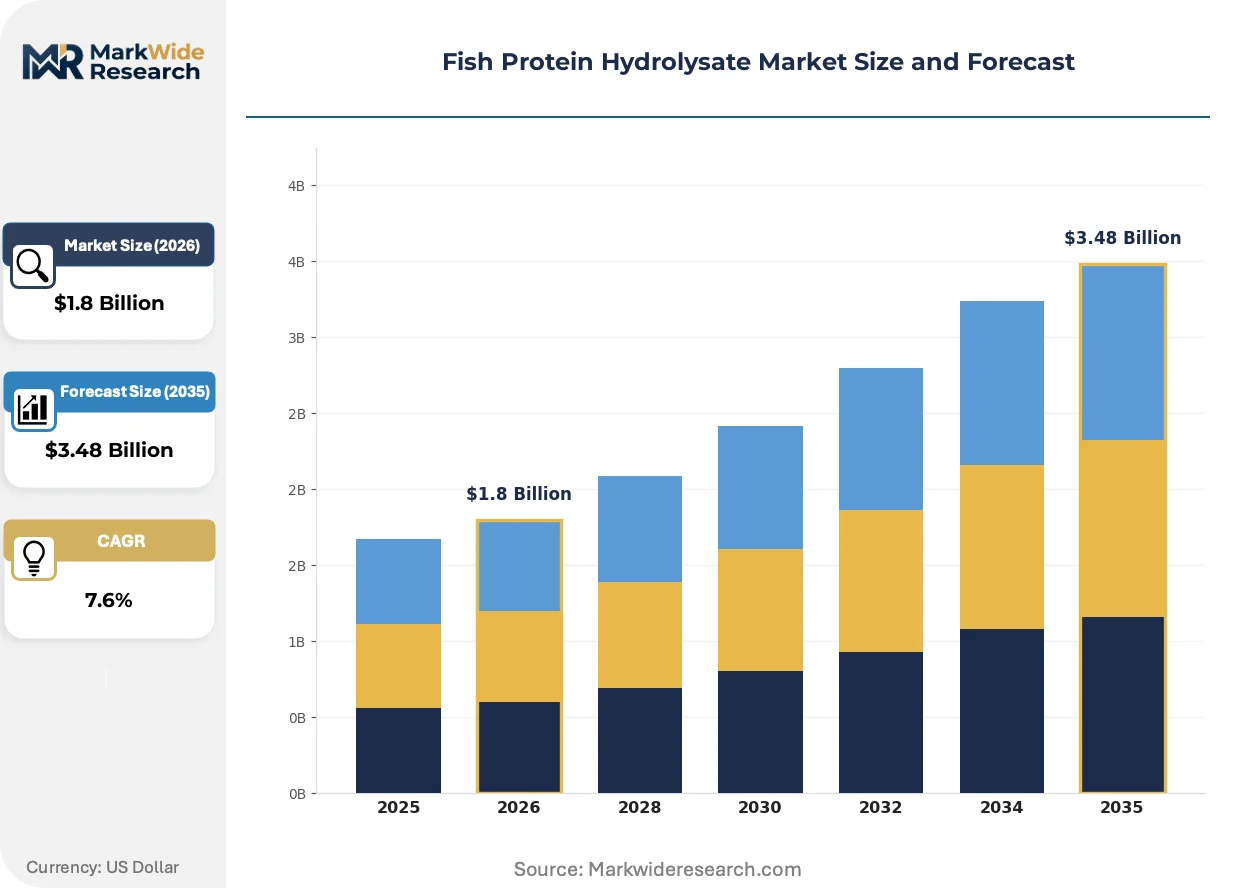
Enzymatic hydrolysis technology maturation is compressing production costs while EU traceability mandates under the Green Deal and F-Gas Regulation are rewriting competitive access rules for marine-derived ingredients.
Growth Catalysts
- Sports nutrition formulation demand:Clean-label instantized protein specifications from nutraceutical brands are pulling spray-dried hydrolysate volumes upward.
- REACH enzymatic processing compliance:Established processors with dedicated regulatory affairs functions are capturing market share from smaller entrants facing authorization delays.
- Norwegian aquaculture processing corridor:Capacity clustering around Bergen and Ålesund is creating supply-side economies of scale for liquid hydrolysate production.
Market Restraints
- Wild catch input volatility:EPA fisheries management quotas for Gulf of Mexico menhaden directly constrain raw material availability for major rendering operations.
- Marine Stewardship Council certification bottleneck:Chain-of-custody audit backlogs are limiting supply chain participation for uncertified processors.
- Acid hydrolysis substitution pressure:Lower-cost acid-catalyzed alternatives threaten enzymatic hydrolysate positioning in cost-sensitive aquaculture feed segments.
Strategic Opportunities
- India dietary supplement penetration:FSSAI novel food pathways remain underutilized by international hydrolysate suppliers relative to protein isolate competitors.
- Dual carbon goal alignment in China:NMPA import registration combined with carbon-neutral processing claims opens positioning for enzymatic versus thermal methods.
- Direct-to-brand nutraceutical supply:Bypassing traditional ingredient distributors via e-procurement platforms is compressing margin extraction by intermediaries.
Industry Challenges
- Peptide characterization expertise scarcity:Bioactive molecular weight fractionation below 10 kDa requires analytical chemistry capabilities in short supply across mid-scale processors.
- Spray-drying capex intensity:Instantized powder production lines demand capital commitments that strain balance sheets absent offtake guarantees from branded customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Protein Hydrolysate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Hydrolysates, Powdered Hydrolysates, Spray-Dried Hydrolysates, Gelled Hydrolysates End User: Food Industry, Animal Feed, Nutraceuticals, Cosmetics Delivery Mode: Online Sales, Direct Sales, Distributors, Retail Outlets Application: Functional Foods, Dietary Supplements, Aquaculture, Sports Nutrition |
| Companies Covered | Bio-Marine Ingredients Ireland, Scanbio Marine, Omega Protein, TC Union, SOPROPECHE, Diana Aqua, Copalis Sea, TripleNine, Hofseth Biocare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Protein Hydrolysate Market Emerging Trajectories
Process intensification and regulatory digitization are converging to reshape how marine proteins move from catch to formulated product, with sustainability verification becoming inseparable from supply security.
Membrane filtration systems for peptide fractionation are miniaturizing. Nutraceutical formulators in North America and Europe are adopting compact skid-mounted units for in-house hydrolysate refinement. This distributed processing model is compressing reliance on centralized spray-drying facilities while enabling batch-specific bioactivity customization.
EU MDR traceability requirements for marine-sourced ingredients are hardening documentation standards. Processors must now maintain electronic records linking individual batches to vessel-level catch documentation. Human consumption applications face the steepest compliance burden, with EFSA novel food authorizations extending timelines for new entrants versus established GRAS-affirmed suppliers.
Ingredient procurement from marine processors is consolidating around long-term offtake agreements with sustainability-linked pricing. Sports nutrition brands are displacing spot-market purchasing with multi-year contracts tied to MSC certification status. This shift is most visible in Nordic supply chains, where captive fleet partnerships now dominate volume allocation decisions.
Fish Protein Hydrolysate Market Segmentation
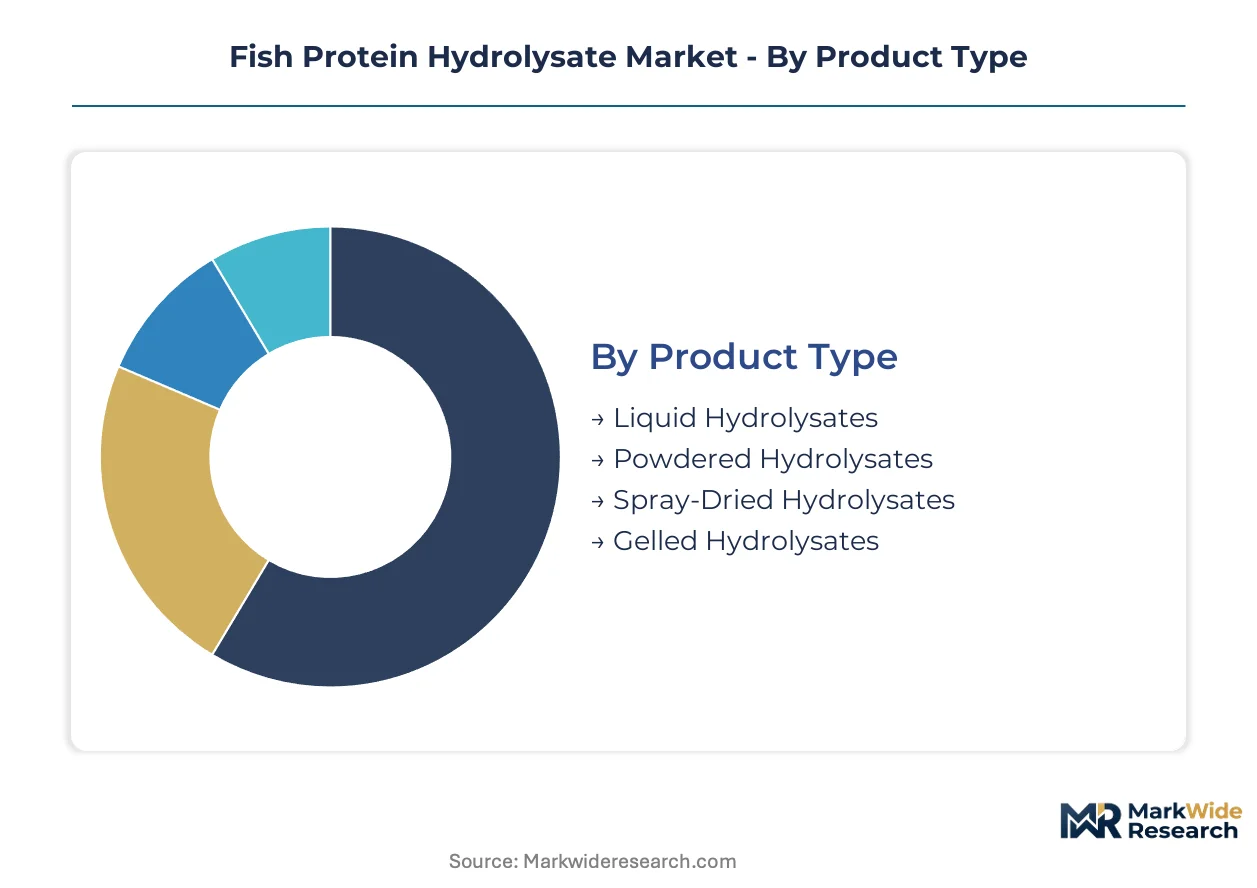
Product format and application specifications dictate procurement economics in the fish protein hydrolysate market. Spray-dried variants command formulation premiums in nutraceuticals while liquid grades compete on cost-per-protein-unit in aquaculture feed. Distribution channel selection directly shapes margin capture for processors serving fragmented end-use segments.
Product Type:
Liquid hydrolysates face the most acute substitution pressure from acid-catalyzed alternatives in cost-sensitive feed applications, while spray-dried formats defend their position through solubility specifications that acid hydrolysis cannot replicate.
- Spray-Dried Hydrolysates:Instantized powder with particle sizes optimized for beverage dispersion and shelf-stable packaging. Sports nutrition brands in the United States and Germany are consolidating procurement around this format to meet clean-label protein claims. EFSA novel food authorization requirements favor established suppliers with documented peptide characterization.
- Powdered Hydrolysates:Standard milled hydrolysate with 70-90% protein content and molecular weight distributions below 10 kDa. Nutraceutical manufacturers in Norway's Bergen-Ålesund processing corridor are expanding spray-drying capacity to serve this specification tier.
- Liquid Hydrolysates:Unconcentrated enzymatic hydrolysate with higher moisture content, dominating aquaculture feed formulations where cost efficiency outweighs handling constraints.
- Gelled Hydrolysates:Thickened variants for specialized cosmetic and topical applications requiring rheological stability.
Spray-dried hydrolysates retain volume leadership; gelled hydrolysates hold the steepest expansion curve.
End User:
Margin structure varies sharply across end-use segments, with nutraceutical applications capturing value through bioactive peptide claims while animal feed competes on commodity protein pricing.
- Nutraceuticals:Dietary supplement and functional food applications requiring documented bioactivity and EFSA novel food or FDA GRAS status. Peptide fractionation below 10 kDa demands analytical chemistry capabilities that constrain supplier participation.
- Animal Feed:Aquaculture and livestock protein supplementation where procurement decisions hinge on cost-per-unit-protein and MSC certification status. Norwegian processors with captive fleet partnerships dominate volume allocation.
- Food Industry:Flavor enhancement and protein fortification in processed foods, facing competition from plant-based hydrolysates.
- Cosmetics:Marine-derived peptides for topical anti-aging formulations, requiring REACH compliance for enzymatic processing aids and batch-level traceability documentation.
Animal feed retains volume leadership; nutraceuticals hold the steepest expansion curve.
Delivery Mode:
Channel selection determines working capital intensity and customer intimacy, with direct sales capturing strategic accounts while distributors fragment margin across smaller end-users.
- Direct Sales:Long-term offtake agreements with branded nutraceutical and sports nutrition companies, often incorporating sustainability-linked pricing tied to MSC certification.
- Distributors:Regional ingredient distributors serving mid-scale food and cosmetic manufacturers with fragmented order patterns.
- Online Sales:E-procurement platforms enabling direct-to-brand supply relationships that compress intermediary margin extraction.
- Retail Outlets:Limited presence for consumer-packaged hydrolysate products, primarily in specialty health food channels.
Direct sales retain volume leadership; online sales hold the steepest expansion curve.
Application:
Application-level specifications create divergent technology requirements, with sports nutrition demanding instantized solubility while aquaculture tolerates higher moisture and viscosity.
- Sports Nutrition:Protein powders and ready-to-drink beverages requiring instantized dispersion, neutral flavor profiles, and bioactive peptide content claims. Brands are displacing spot-market purchasing with multi-year contracts.
- Aquaculture:Feed ingredient applications in Norway's salmon farming industry, where enzymatic hydrolysate competes with fish meal and acid-hydrolyzed alternatives on cost and digestibility metrics.
- Functional Foods:Protein fortification in beverages, bars, and prepared meals, facing formulation challenges around flavor masking and heat stability.
- Dietary Supplements:Capsule and tablet applications requiring standardized peptide profiles and documented bioavailability.
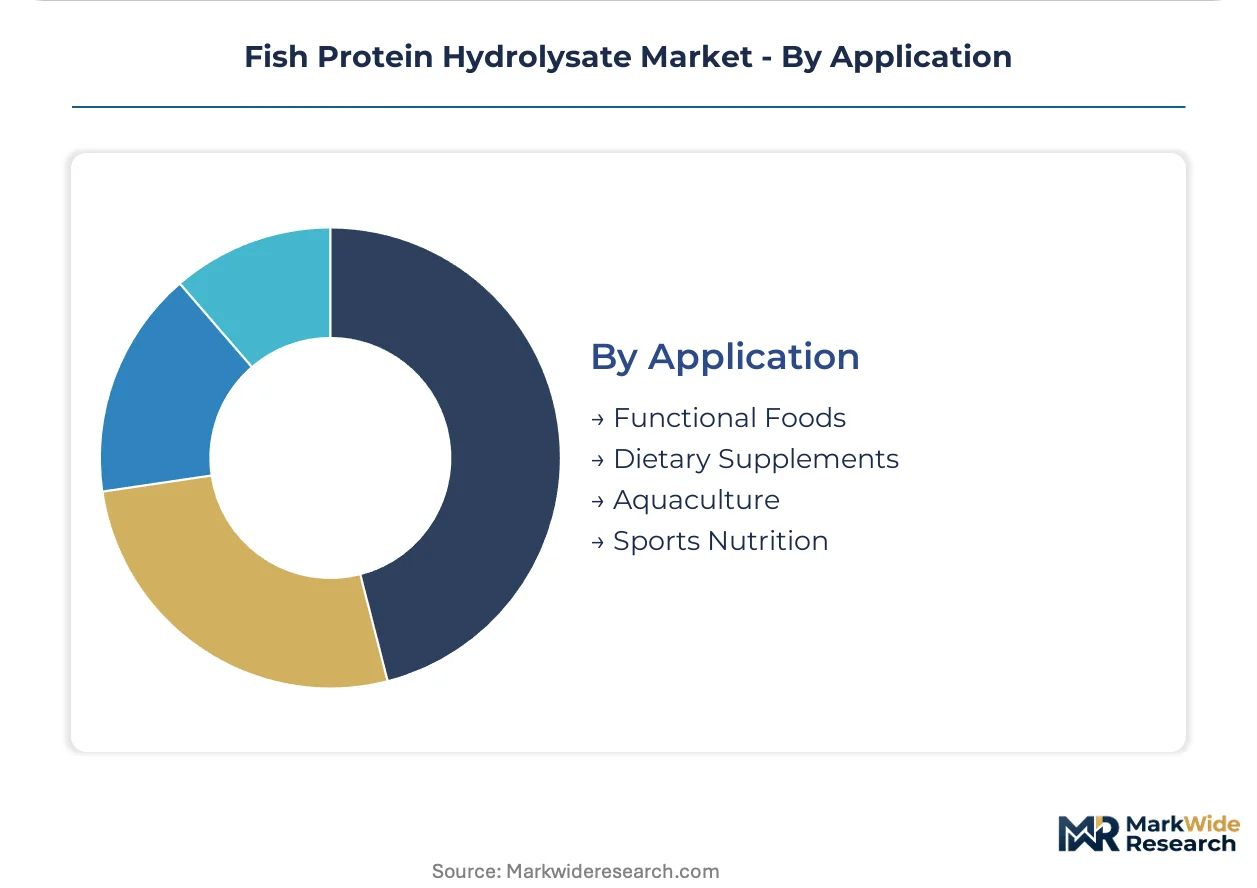
Aquaculture retains volume leadership; sports nutrition holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal traceability mandates and F-Gas Regulation compliance costs are redrawing procurement geography for marine-derived ingredients. Norway's aquaculture processing corridor captures enzymatic hydrolysis scale advantages. Regulatory fragmentation across FDA GRAS and EFSA novel food pathways creates divergent market access timelines.
Norway
Salmon farming operations in Bergen and Ålesund drive liquid hydrolysate consumption for feed applications. The Norwegian Food Safety Authority enforces strict vessel-level documentation under EU MDR traceability requirements. Enzymatic hydrolysis capacity clusters along the western fjord coastline, with processors leveraging captive fleet partnerships to secure raw material supply.
United States
Sports nutrition brands in California and Texas consolidate procurement around spray-dried formats for clean-label protein claims. FDA GRAS self-affirmation provides faster market access than EFSA pathways for human consumption applications. Gulf of Mexico menhaden fisheries anchor rendering operations, though EPA fisheries management quotas constrain input volumes seasonally.
China
NMPA import registration requirements filter international suppliers while domestic aquaculture expansion sustains feed-grade demand. Dual carbon goal alignment favors enzymatic over thermal processing methods for carbon-neutral claims. Yangtze River Delta processors are upgrading peptide fractionation capabilities to serve nutraceutical export markets.
Germany
REACH compliance for enzymatic processing aids elevates regulatory barriers for mid-scale entrants. Sports nutrition formulators in Bavaria and North Rhine-Westphalia source spray-dried hydrolysates for instantized beverage applications. Hamburg's port infrastructure facilitates MSC-certified marine ingredient imports from Nordic suppliers.
India
FSSAI novel food pathways remain underutilized by international hydrolysate suppliers relative to protein isolate competitors. Maharashtra and Gujarat dietary supplement manufacturers represent untapped demand for bioactive peptide formulations. Import tariff structures currently disadvantage finished hydrolysate products versus raw material alternatives.
Fish Protein Hydrolysate Market Vendor Landscape
Player mix skews toward vertically integrated marine processors with captive fleet access and dedicated regulatory affairs functions. Tiered competitive structure separates MSC-certified premium suppliers from uncertified volume players. Two dominant archetypes prevail: Nordic coastal processors with integrated enzymatic infrastructure and Gulf of Mexico rendering operations with backward integration into wild catch. Competitive moves concentrate on long-term offtake agreements with sustainability-linked pricing and spray-drying capacity expansion to capture sports nutrition premiums.
Among Irish coastal processors, Bio-Marine Ingredients Ireland exemplifies the regional supply dominance archetype through its island-wide processing network. Scanbio Marine anchors the captive fleet partnership model, representing integrated infrastructure advantages in Norwegian waters. Omega Protein occupies a position exemplifying Gulf of Mexico volume leadership through menhaden fishery access and in-house rendering operations. These three company structures illustrate how geographic concentration of marine resources translates into procurement leverage across distinct regulatory environments.
| Leading Market Players |
|---|
| Bio-Marine Ingredients Ireland |
| Scanbio Marine |
| Omega Protein |
| TC Union |
| SOPROPECHE |
| Diana Aqua |
| Copalis Sea |
| TripleNine |
| Hofseth Biocare |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with sustainability-linked pricing lock in both raw material access and price visibility for processors serving nutraceutical brands, compressing spot-market exposure while MSC certification status becomes the primary contract term determinant.
Pricing Analysis
Certification level (MSC chain-of-custody versus uncertified) creates the primary spread between premium and standard tiers, with spray-dried formats commanding formulation premiums over liquid grades. Contract-based long-term offtake structures dominate volume allocation, though acid hydrolysis substitution pressure in aquaculture feed segments is compressing margins for enzymatic processors. Aquaculture feed buyers exhibit the highest price sensitivity due to cost-per-protein-unit procurement metrics, while sports nutrition brands prioritize solubility specifications over unit cost.
Supply Chain Analysis
Port congestion at Hamburg and container availability constraints on trans-Atlantic trade lanes elevate inbound logistics costs for European nutraceutical formulators sourcing Nordic marine ingredients. Supply concentrates in Norway, Ireland, and the United States, with raw material dependencies on Gulf of Mexico menhaden fisheries, North Atlantic whitefish processing discards, and Irish coastal pelagic catches. Single-source vulnerability around EPA fisheries management quotas for menhaden represents the dominant structural risk. Distribution runs through direct sales channels for branded nutraceutical accounts and regional distributors serving fragmented cosmetic and food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EFSA novel food authorizations and FDA GRAS self-affirmation creates switching costs that protect incumbent positions.
For Market Incumbents: Consolidate spray-drying capacity expansion in Norway's Bergen-Ålesund corridor to capture sports nutrition premiums while deepening captive fleet partnerships to defend against wild catch input volatility from EPA quota constraints. Investment in peptide fractionation capabilities below 10 kDa reinforces differentiation against acid hydrolysis substitution threats in cost-sensitive feed segments. For New Entrants and Emerging Players: Custom peptide profiling for sports nutrition brands represents a service-layer gap where incumbents under-serve batch-specific bioactivity requirements. India's FSSAI novel food pathways offer the most penetrable geography given underutilization by international suppliers relative to protein isolate competitors. Direct-to-brand e-procurement platforms provide the optimal go-to-market angle to bypass established distributor margin extraction. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated processors with MSC-certified captive fleet access and dedicated regulatory affairs functions capable of navigating EFSA authorization timelines. Long-term viability hinges on sustainability certification credibility inseparable from supply security. The signal to watch is EPA fisheries management quota adjustments that would reallocate raw material access across rendering operations.| Strategic Initiative | Industry Significance |
|---|---|
| MSC Certification Investment | Chain-of-custody status unlocks long-term offtake agreements with sustainability-linked pricing from sports nutrition brands. |
| Spray-Drying Capacity Expansion | Instantized powder production lines capture formulation premiums in nutraceutical applications requiring clean-label solubility specifications. |
| Captive Fleet Partnership | Direct vessel-level raw material sourcing secures supply continuity under EU MDR traceability documentation requirements. |
| Peptide Fractionation Capability | Bioactive molecular weight separation below 10 kDa enables documented functional claims for dietary supplement positioning. |
| Regulatory Affairs Function Buildout | Dedicated EFSA novel food and FDA GRAS navigation capabilities compress market access timelines versus smaller entrants facing authorization delays. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association reports through structured interviews with enzymatic hydrolysis plant managers, procurement leads at nutraceutical OEMs, marine ingredient distribution channel partners, and regulatory affairs directors. Primary data collection engaged supply chain stakeholders across Norway, Ireland, and the United States alongside secondary validation from customs records, Marine Stewardship Council certification databases, and SEC filings from publicly traded rendering operations. Bottom-up volume modeling triangulates against top-down market sizing across product format and application segments.
Segmentation dimensions modeled include product format tier, end-use application, delivery mode channel structure, and regional regulatory cluster across the analysis window. CAGRs derive from trend extrapolation of enzymatic processing capacity expansion, sports nutrition formulation adoption curves, and aquaculture feed substitution dynamics. Forecast inputs incorporate EPA fisheries quota trajectories, EFSA novel food authorization pipeline status, and spray-drying capital expenditure announcements from Nordic processors.
Forecasts assume regulatory continuity in EU Green Deal traceability mandates, FDA GRAS self-affirmation pathways, and EPA fisheries management frameworks; material policy shifts in any regime would require re-modeling. Specific risks that could revise projections include acid hydrolysis substitution acceleration in aquaculture feed, MSC certification audit backlogs constraining supply chain participation, and NMPA import registration barriers altering China market access. Practitioners should keep alternative scenarios live as sustainability verification requirements and carbon-neutral processing claims evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
South America Canned Seafood Market
Seafood
Canned Anchovy Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Rainbow Trout Market
Seafood
Fish Oil Market
Seafood
Food Clamshells Market
Seafood
Dry-Packaged Scallops Market
Seafood
United Arab Emirates Seafood Market
Seafood
Smoked Whiting Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Haddock Market
Seafood
Europe Salmon Market
Seafood
Smoked Salmon Market
Seafood
Latin America Salmon Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Global White Shrimp Market