
 Online 3D Printing Service Market | 2026-2036
Online 3D Printing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Online 3D Printing Service Market Insights
Shift from captive in-house printers to outsourced, multi-vendor digital manufacturing networks is broadening the addressable base for online service platforms. Xometry leverages its proprietary quoting engine to match buyers with distributed supplier capacity across North America and Europe. Protolabs anchors its model on domestic, quick-turn production cells that compete on speed rather than unit cost. Shapeways differentiates through consumer-facing storefront tools that let designers monetize digital files without managing fulfillment.
Online 3D printing services connect uploaded CAD geometry to networked industrial additive equipment, typically processing thermoplastic filaments, photopolymer resins, or powdered polymers through layer-wise deposition or photopolymerization to yield functional prototypes or end-use components. Fused Deposition Modeling dominates transaction volume due to low equipment barriers and material familiarity among mechanical engineers. Selective Laser Sintering captures premium margin pools in aerospace and medical verticals where nylon and polyamide performance justify higher per-part pricing. Stereolithography occupies a narrowing but defensible niche for dental and jewelry applications requiring fine feature resolution.
FDA oversight of patient-specific medical devices and FAA material qualification protocols for flight-critical printed parts create compliance moats that filter uncertified competitors from high-value segments. EPA emissions guidelines and OSHA respirable powder standards further shape facility investment and operational geography for service bureaus running metal or high-temperature polymer systems. Stakeholders must weigh whether to build captive certification expertise or partner with already-audited platforms as regulatory scope widens beyond finished parts into digital workflow traceability.
Market Dynamics
The market pivots on the tension between distributed manufacturing networks and centralized certification authority. Service platforms must reconcile buyer demand for geographic flexibility with FAA and FDA requirements for material traceability and process documentation.
Growth Catalysts
- REACH and RoHS material mandates:European compliance frameworks push mid-sized manufacturers toward audited service bureaus with certified supply chains rather than captive prototyping labs.
- Nylon 12 powder formulations:Selective Laser Sintering material advances enable functional aerospace brackets and medical guides that withstand thermal and mechanical stress without post-processing.
- Germany's Mittelstand density:Concentration of engineering-heavy SMEs without additive capacity creates sustained demand for outsourced production in Baden-Württemberg and Bavaria.
Market Restraints
- Titanium powder cost volatility:Metal additive feedstock prices swing with aerospace demand cycles and Russian supply disruptions, compressing margins for service bureaus running EOS or SLM Solutions equipment.
- FAA material qualification protocols:Flight-critical part certification requires 18-36 month validation timelines that lock out uncertified competitors from aerospace revenue pools.
- CNC machining substitution:Subtractive methods retain cost advantage above 1,000-unit production runs, capping addressable volume for printed end-use components.
Strategic Opportunities
- India's medical device PLI scheme:Domestic production incentives for patient-specific implants create opening for certified service platforms to establish local Cell Therapy-compliant facilities.
- Continuous Liquid Interface Production:Carbon's CLIP technology convergence with automated post-processing enables same-day dental aligner fabrication at throughput rates matching thermoforming.
- Digital workflow traceability:EU MDR requirements for device history records position blockchain-integrated platforms to capture premium pricing from risk-averse orthopedic OEMs.
Industry Challenges
- AM-specific design talent scarcity:Mechanical engineers trained in traditional CAD lack topology optimization and lattice generation skills required for weight-critical aerospace components.
- Multi-material certification backlog:FDA review queues for patient-specific polymer-ceramic composites delay commercialization timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online 3D Printing Service Market |
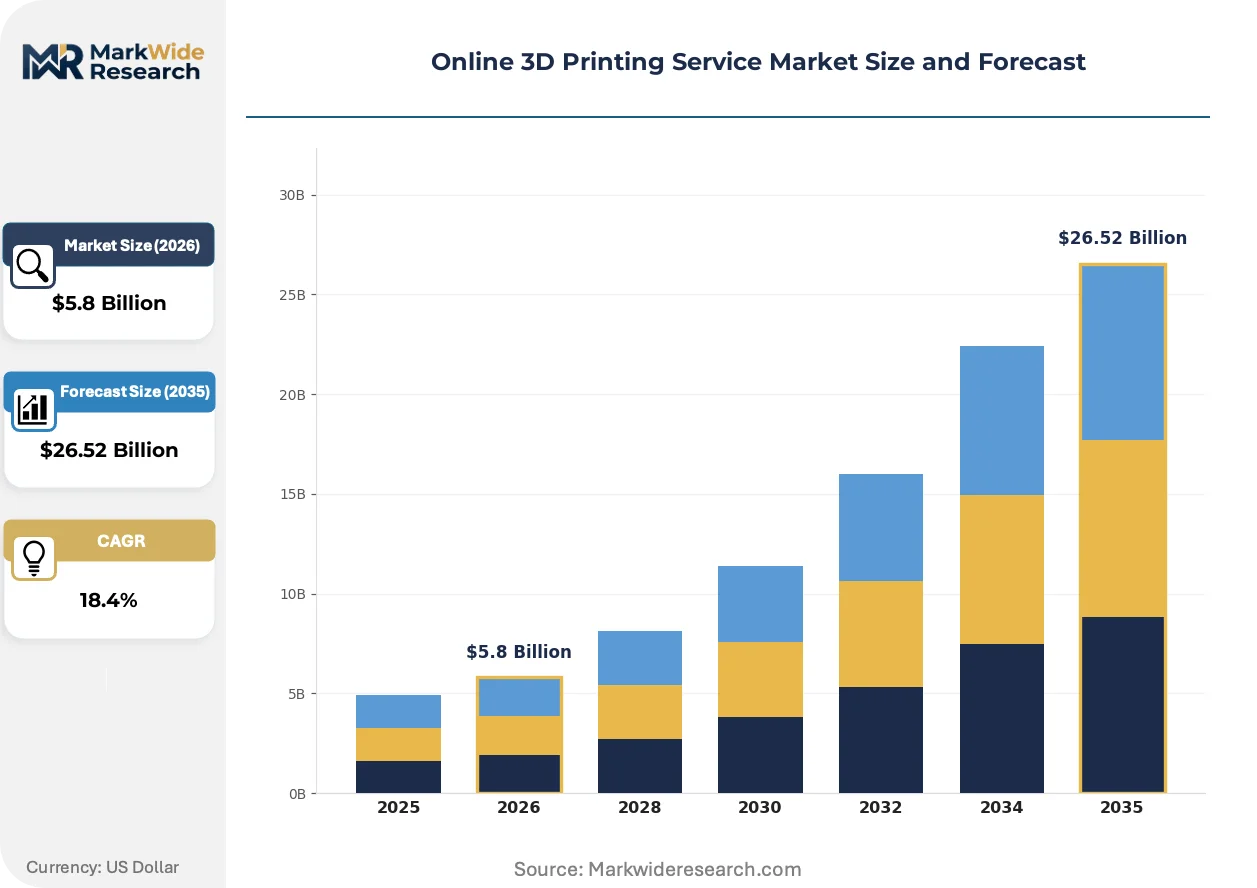
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Prototype Production, Custom Parts Manufacturing, Design Consultation, Bulk Printing Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Material: PLA, ABS, Nylon, Resin Industry Vertical: Aerospace, Automotive, Healthcare, Consumer Goods |
| Companies Covered | Shapeways, Xometry, Sculpteo, Craftcloud, Protolabs, Hubs, JLC3DP, FAMA 3D, Treatstock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online 3D Printing Service Market Trends and Innovations
Software-defined manufacturing workflows are collapsing the traditional boundary between design iteration and production execution. Three developments are restructuring how buyers access additive capacity and how providers monetize their installed base.
Cloud-native nesting and build preparation tools are decentralizing job routing decisions away from centralized procurement teams. Automotive Tier 1 suppliers now upload component geometries to multiple service platforms simultaneously, comparing real-time quotes across FDM, SLS, and Multi Jet Fusion options. This price transparency compresses supplier margins while expanding total transaction volume.
REACH substance restrictions on photoinitiator chemicals are forcing resin formulation changes across European service bureaus. ECHA's 2023-2025 restriction roadmap targets specific acrylate monomers used in dental and jewelry applications. Providers running Formlabs or Carbon hardware in Germany and the Netherlands are reformulating material libraries ahead of enforcement deadlines.
Engineering teams now source prototypes through corporate procurement cards rather than traditional vendor onboarding. This purchasing pattern shift accelerates supplier switching and rewards platforms with instant quoting engines. North American aerospace and medical device clusters show highest adoption of self-service procurement portals.
Online 3D Printing Service Market Segmentation
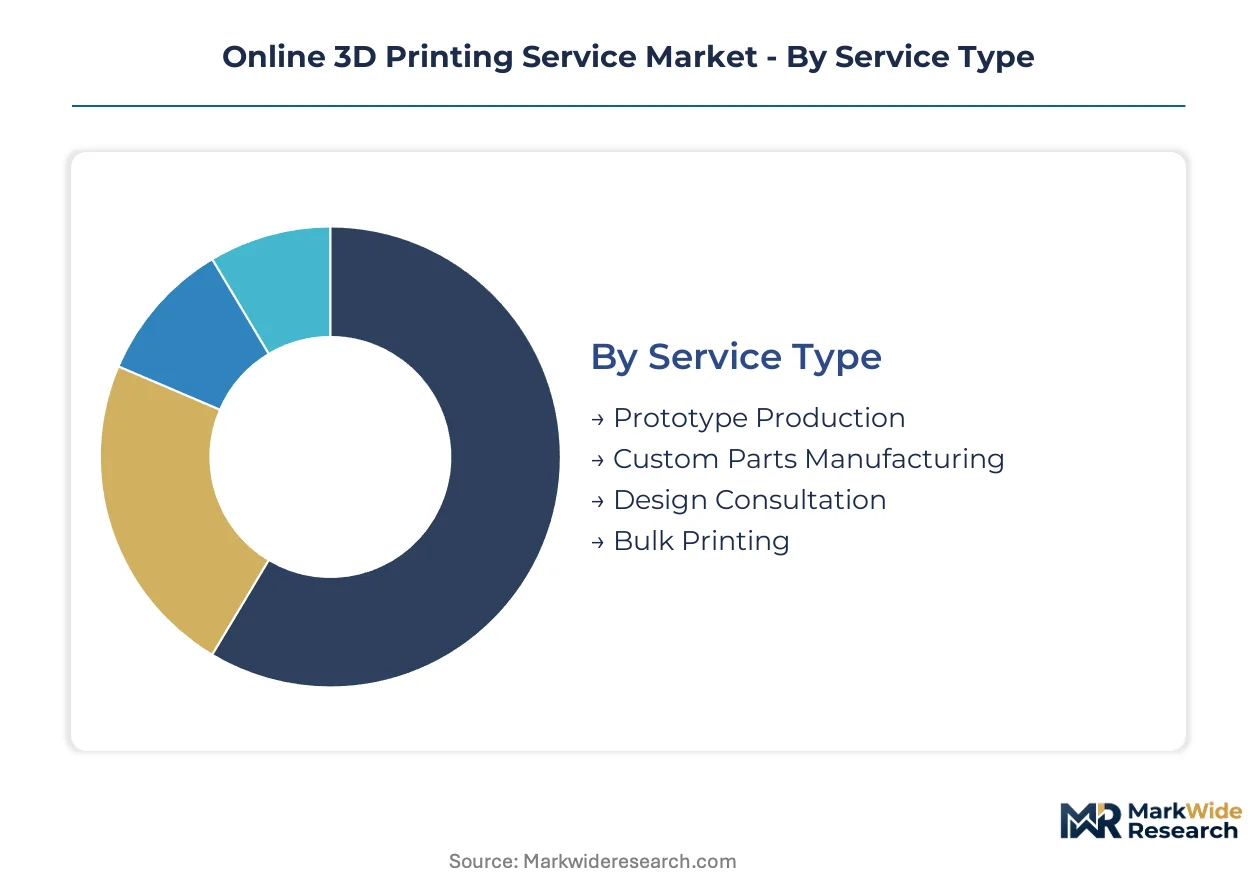
Online 3D printing services fragment across four dimensions that determine pricing power and customer retention. Service type and technology selection drive margin structure, while material and vertical focus shape compliance burden and contract duration.
Service Type:
Prototype Production commands transaction volume but Custom Parts Manufacturing captures premium pricing through recurring contracts and tighter quality specifications.
- Prototype Production:Rapid iteration cycles for functional validation dominate mechanical engineering workflows. Automotive suppliers in Germany's Mittelstand belt outsource early-stage component testing to avoid capital expenditure on captive equipment. Speed-to-quote determines platform selection more than unit cost.
- Custom Parts Manufacturing:Low-volume end-use production with material certification requirements sustains longer customer relationships. Aerospace brackets and medical device housings require full traceability documentation that locks buyers into audited supplier networks.
- Design Consultation:Topology optimization and lattice generation services address AM-specific talent scarcity among traditional mechanical engineers.
- Bulk Printing:Production runs of 100-1,000 units compete with injection molding economics through distributed manufacturing networks.
Today's leader: Custom Parts Manufacturing. Tomorrow's challenger: Design Consultation.
Technology:
Equipment cost tiers separate commodity service providers from certified aerospace and medical specialists.
- Fused Deposition Modeling:Thermoplastic filament deposition through heated nozzles offers lowest equipment barrier and broadest material familiarity. Transaction volume concentrates here due to mechanical engineer training and rapid quoting turnaround.
- Selective Laser Sintering:CO2 laser fusion of nylon and polyamide powders enables functional aerospace brackets and medical surgical guides without support structures. REACH-compliant powder formulations in Europe sustain premium positioning.
- Stereolithography:Photopolymer resin curing with ultraviolet lasers delivers finest feature resolution for dental aligners and jewelry patterns.
- Digital Light Processing:Projector-based photopolymerization achieves faster layer times than SLA for same-day dental appliance production.
FDM dominates volume. SLS gains share fastest in regulated verticals.
Material:
Certification requirements and supply chain traceability separate commodity thermoplastics from performance polymers.
- PLA:Corn-derived biodegradable filament serves lowest-cost prototyping with minimal thermal resistance requirements.
- ABS:Petroleum-based thermoplastic withstands higher temperatures for automotive interior component validation.
- Nylon:Polyamide 12 powder formulations enable functional aerospace brackets and medical guides that withstand thermal and mechanical stress.
- Resin:Acrylate and epoxy photopolymers face ECHA restriction timelines forcing European service bureau reformulation ahead of enforcement deadlines.
Nylon commands aerospace premium. Resin faces regulatory compression.
Industry Vertical:
Compliance burden intensity determines customer acquisition cost and contract stickiness across end-use sectors.
- Aerospace:FAA material qualification protocols for flight-critical parts require 18-36 month validation timelines that filter uncertified competitors from revenue pools. Titanium powder cost volatility compresses margins for metal additive service bureaus.
- Healthcare:FDA oversight of patient-specific devices and EU MDR device history record requirements position blockchain-integrated platforms to capture premium pricing from orthopedic OEMs.
- Automotive:Tier 1 suppliers now upload geometries to multiple platforms simultaneously, comparing real-time quotes across FDM, SLS, and Multi Jet Fusion options.
- Consumer Goods:Self-service procurement portals and corporate purchasing cards accelerate supplier switching and reward instant quoting engines.
Healthcare leads margin capture. Automotive drives price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with clearer certification pathways and lower compliance friction. Service bureaus cluster where FDA, EMA, or national aerospace regulators maintain reciprocal recognition agreements, reducing redundant qualification costs for cross-border contracts.
United States
Aerospace OEMs in Seattle and Los Angeles drive demand for titanium-qualified additive capacity. FAA material qualification protocols for flight-critical parts require 18-36 month validation timelines that filter uncertified competitors. The Pacific Northwest and Southern California clusters concentrate metal powder service bureaus serving Boeing and SpaceX supply chains.
Germany
REACH and RoHS compliance frameworks push mid-sized manufacturers toward audited service bureaus with certified supply chains. Baden-Württemberg and Bavaria host dense concentrations of Mittelstand engineering firms lacking captive additive capacity. Stuttgart's automotive tier-one suppliers outsource functional prototyping to avoid capital expenditure on in-house equipment.
China
Domestic medical device production incentives under the 14th Five-Year Plan accelerate demand for patient-specific implant fabrication. NMPA oversight of printed orthopedic devices creates compliance moats favoring certified domestic platforms. Yangtze River Delta industrial zones concentrate polymer powder service bureaus serving dental aligner manufacturers.
United Kingdom
Post-Brexit regulatory divergence from EU MDR delays market access for continental service platforms. London and Midlands aerospace clusters maintain dual-track qualification for EASA and UK CAA compliance. Oxford and Cambridge medical technology spin-offs drive demand for surgical guide prototyping with full device history records.
India
Production-linked incentive schemes for medical devices create openings for certified service platforms to establish CDSCO-compliant facilities. Maharashtra and Karnataka host emerging domestic additive capacity serving orthopedic OEMs. Bangalore's medical technology corridor concentrates demand for patient-specific cranial implant fabrication.
Online 3D Printing Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized certification verticals and geographic whitespace. The vendor base distributes across three maturity tiers: venture-backed platforms with proprietary quoting engines, legacy service bureaus with captive equipment fleets, and designer-facing storefronts monetizing digital file distribution. Two strategic archetypes dominate: speed-optimized domestic producers competing on turnaround time, and compliance-heavy specialists capturing aerospace and medical premiums. Competitive moves concentrate on M&A for certification asset acquisition and strategic partnerships for distributed manufacturing network expansion.
Among US-based platforms, Xometry and Protolabs exemplify contrasting archetypes—Xometry anchors the distributed network model matching buyers to supplier capacity across North America and Europe, while Protolabs represents the centralized quick-turn approach competing on domestic speed rather than unit cost. Shapeways occupies a distinct position within the designer-facing tier, offering consumer storefront tools that let independent creators monetize digital files without managing fulfillment infrastructure. These three companies illustrate how competitive positioning fragments across speed, compliance depth, and creator economy access.
| Leading Market Players |
|---|
| Shapeways |
| Xometry |
| Sculpteo |
| Craftcloud |
| Protolabs |
| Hubs |
| JLC3DP |
| FAMA 3D |
| Treatstock |
| Others |
Pricing and Supply Chain Analysis
Automotive Tier 1 suppliers uploading geometries to multiple platforms simultaneously compress supplier margins while expanding transaction volume across FDM, SLS, and Multi Jet Fusion options. This procurement transparency forces service bureaus to absorb titanium powder cost volatility and reformulate resin libraries ahead of ECHA enforcement deadlines.
Pricing Analysis
Input-cost pass-through from titanium powder volatility and photoinitiator chemical restrictions compresses margins unevenly across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates FAA-qualified aerospace specialists from uncertified commodity providers. Price differentiation hinges on certification grade and volume scale. Pricing pressure stems from real-time quote comparison engines that accelerate supplier switching. Consumer goods buyers exhibit highest price sensitivity; aerospace OEMs prioritize traceability documentation over unit cost.
Supply Chain Analysis
India's medical device PLI scheme and China's 14th Five-Year Plan domestic production incentives reshape sourcing patterns for patient-specific implant fabrication. Powdered polymer feedstock draws from Germany's Mittelstand belt, China's Yangtze River Delta, and the US Pacific Northwest. Raw material dependencies center on nylon 12 formulations, titanium powder, and acrylate photopolymers. Single-source vulnerability concentrates in Russian-origin titanium supply disruptions. Distribution runs through cloud-native platforms with automated nesting and build preparation tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH-compliant European service bureaus command premium pricing against lower-cost Indian platforms operating under CDSCO pathways with equivalent technical capability.
For Market Incumbents: Acquire certification asset portfolios including FAA material qualification protocols and FDA device history record systems to defend against emerging distributed manufacturing networks. Build backward integration into nylon 12 powder formulation to offset feedstock cost volatility. Lock in multi-year contracts with Baden-Württemberg automotive suppliers before procurement card purchasing accelerates supplier switching. For New Entrants and Emerging Players: Dental aligner manufacturers in China's Yangtze River Delta represent the most penetrable segment for uncertified platforms. Target India's Maharashtra and Karnataka medical technology corridors where CDSCO compliance costs filter established competitors. Pursue automated post-processing partnerships with Carbon CLIP technology adopters to bypass capital-intensive equipment ownership. For Investors and Strategic Acquirers: Asymmetric upside sits with blockchain-integrated platforms capturing EU MDR device history record premiums from orthopedic OEMs. Five-to-ten year viability favors compliance-heavy specialists over speed-optimized domestic producers as regulatory scope widens into digital workflow traceability. Monitor FDA review queue lengths for patient-specific polymer-ceramic composites as inflection indicator for multi-material certification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Asset Acquisition | FAA and FDA qualification protocols filter uncertified competitors from aerospace and medical revenue pools. |
| Backward Integration into Powder Formulation | In-house nylon 12 production insulates margins from titanium powder cost volatility and supply disruptions. |
| Blockchain-Integrated Traceability Platform | EU MDR device history record requirements position compliant platforms for premium orthopedic OEM pricing. |
| Geographic Expansion into India PLI Corridors | Maharashtra and Karnataka production incentives create openings for CDSCO-compliant patient-specific implant facilities. |
| Automated Post-Processing Partnership | Carbon CLIP convergence with same-day dental aligner fabrication matches thermoforming throughput rates. |
Research Methodology
Multiple input streams — primary interviews with service bureau operations directors, aerospace procurement managers, and medical device regulatory affairs leads; secondary validation through FAA material qualification databases, ECHA restriction roadmaps, and SEC filings from publicly traded additive platforms; customs and trade data on titanium powder flows — were reconciled through bottom-up transaction counting and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including service type, technology equipment tier, material certification grade, and industry vertical compliance burden. CAGRs were derived from installed base expansion rates and average revenue per transaction trends. Forecast inputs incorporated REACH substance restriction timelines and NMPA domestic production incentive trajectories.
Revisions become necessary when FAA material qualification protocols accelerate or decelerate, ECHA enforcement timelines shift, or titanium powder supply disruptions persist beyond aerospace demand cycle norms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
3D Printing in Consumer Goods Market