
 Metal 3D Printing Service Market | 2026-2036
Metal 3D Printing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Metal 3D Printing Service Market Insights
Aerospace component procurement is rebalancing toward metal additive manufacturing as OEMs compress development cycles and reduce buy-to-fly ratios. EOS dominates powder-bed fusion system supply for European aviation primes and sustains deep R&D partnerships with certification bodies. Nikon SLM Solutions specializes in multi-laser architectures for large-format aerospace structures, while Materialise controls digital workflow software that bridges design files to qualified production parameters.
Metal 3D printing services encompass the industrial fabrication of functional metallic components through layer-wise consolidation of powders or wires using directed energy sources, typically achieving relative densities above 99.5% and feature resolutions down to 20 micrometers depending on the modality. These services deliver net-shape or near-net-shape parts for applications where conventional subtractive or formative methods impose excessive material waste, tooling cost, or geometric constraint. Selective laser melting currently anchors the highest-value contract manufacturing streams due to its mature qualification pathways in medical implants and aerospace brackets. Binder jetting represents the fastest-growing technology segment as service bureaus pursue cost parity with metal injection molding for stainless steel and copper alloy production at scale. Custom manufacturing commands premium pricing relative to rapid prototyping because of the engineering intensity required for process parameter validation and first-article inspection.
FDA 21 CFR Part 820 quality system requirements and EASA Part 21G production organization approvals govern medical implant and flight-critical part certification respectively, creating significant compliance barriers for unqualified entrants. EPA air emissions standards and OSHA metal powder combustibility directives further shape facility capital requirements and operational protocols for service providers handling reactive alloys. Stakeholders must monitor evolving AM-specific standards from ISO/ASTM and national aviation authorities to anticipate which qualification investments will unlock captive demand versus commoditized contract overflow.
Market Dynamics
Metal 3D printing service providers face intense pressure from aerospace OEMs demanding qualified production capacity for flight-critical titanium structures, while REACH compliance costs for powder traceability reshape facility economics across European contract manufacturers.
Growth Catalysts
- EASA Part 21G Production Organization Approval:Aviation primes in Germany and France now mandate certified additive suppliers for bracket and manifold contracts, locking in multi-year service agreements with qualified bureaus.
- Titanium Powder Recycling Advances:Closed-loop argon atomization systems cut input material costs by recovering unfused powder, expanding margin headroom for medical implant contract runs.
- Wind Energy:Siemens Gamesa and Vestas specify additively manufactured copper heat exchangers for direct-drive generators, opening industrial-scale demand outside traditional aerospace and medical verticals.
Market Restraints
- Argon and Helium Supply Concentration:Qatar and Russia control over 60% of global helium refining capacity; price volatility in inert shielding gases compresses margins for laser powder-bed fusion operators.
- Machine Tool Oligopoly:EOS, Nikon SLM Solutions, and Trumpf dominate multi-laser system supply, limiting bargaining power for independent service bureaus seeking capacity expansion.
- Surface Roughness Limitations:As-built Ra values of 6-12 micrometers in selective laser melting require costly CNC finishing for hydraulic manifolds, constraining addressable market share against precision casting.
Strategic Opportunities
- India PLI Scheme for Medical Devices:Contract manufacturers establishing powder-bed fusion capacity in Gujarat and Telangana qualify for 5% incentive on incremental sales, capturing orthopedic implant demand from domestic hospital chains.
- Binder Jetting-Cold Isostatic Pressing Convergence:Service bureaus pairing ExOne/Desktop Metal systems with HIP furnaces achieve 99.8% density in stainless steel, competing directly with metal injection molding for firearm and automotive sensor housings.
- EU Green Deal Carbon Border Adjustment:Near-shore additive production of aluminum brackets avoids embedded emissions tariffs on Chinese die-cast imports, creating cost parity for European automotive tier-twos.
Industry Challenges
- Metallurgical Engineer Scarcity:Process parameter development for nickel superalloys requires PhD-level expertise in solidification microstructure; European technical universities produce fewer than 200 qualified graduates annually.
- FDA 510(k) Resubmission Timelines:Design changes to patient-specific cranial implants trigger 180-day review cycles, freezing work-in-progress capital and delaying revenue recognition for medical-focused service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal 3D Printing Service Market |
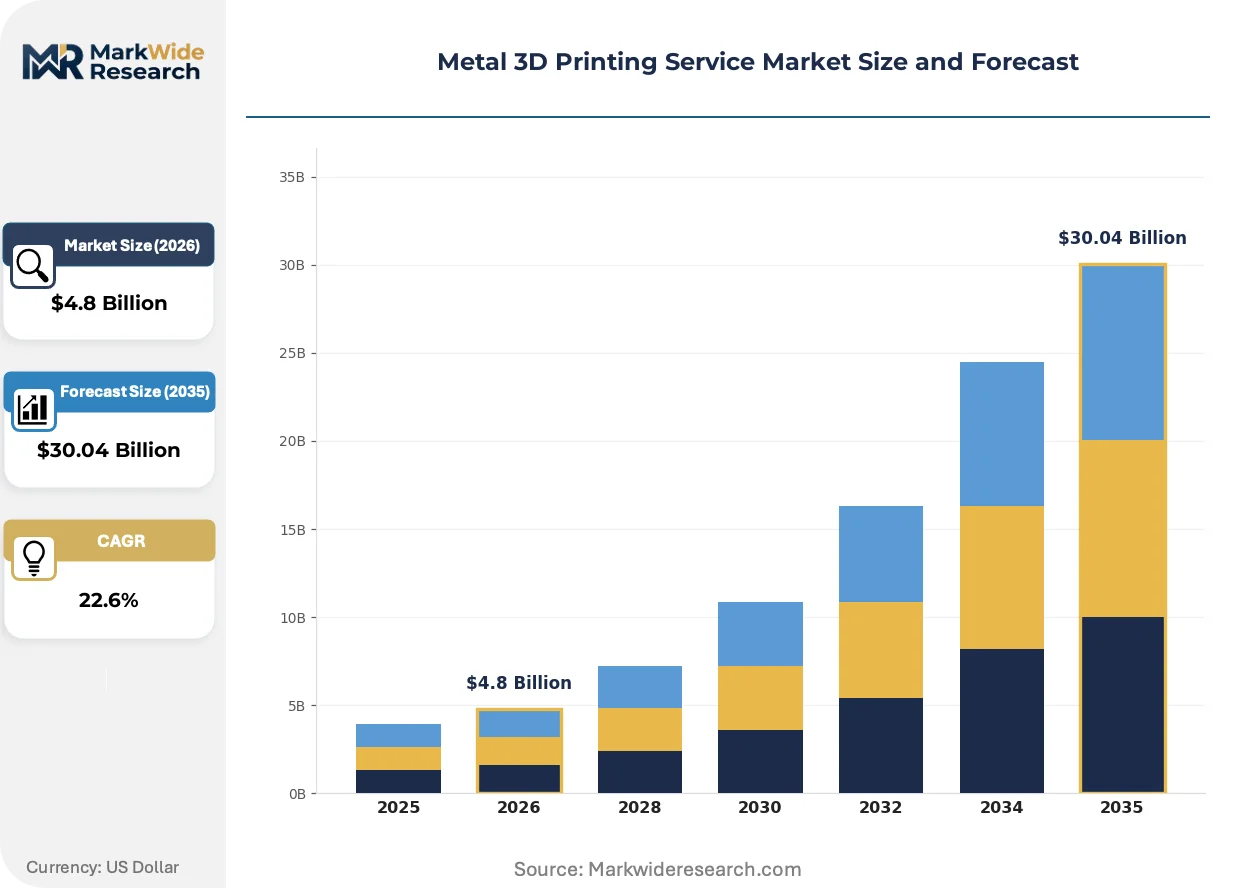
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.04 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rapid Prototyping, Low Volume Production, Custom Manufacturing, Tooling Solutions, Reverse Engineering Technology: Selective Laser Melting, Electron Beam Melting, Direct Metal Laser Sintering, Binder Jetting, Directed Energy Deposition Application: Aerospace Components, Medical Implants, Industrial Tooling, Consumer Products, Architectural Models End User Industry: Defense Equipment, Dental Laboratories, Automotive Suppliers, Educational Institutes, Jewelry Manufacturers |
| Companies Covered | EOS, BLT, Nikon SLM Solutions, 3D Systems, Colibrium Additive, Materialise, Stratasys Direct Manufacturing, Shapeways, Protolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal 3D Printing Service Market Trends and Innovations
Multi-laser powder-bed fusion architectures and in-process monitoring systems are compressing qualification timelines while regulatory bodies draft additive-specific certification pathways that diverge from legacy casting and forging standards.
Directed energy deposition with wire feedstock is absorbing demand from heavy equipment and energy sector repair operations. Caterpillar and Baker Hughes now specify wire-arc additive for remanufacturing worn excavator arms and drilling bit bodies. The technology is absorbing contract volume that previously flowed to plasma transfer arc welding and manual overlay processes.
REACH Annex XVII restrictions on nickel compound emissions are forcing powder atomization facilities in Belgium and Sweden to install wet scrubbing and baghouse upgrades. ECHA enforcement inspections tripled in 2023, pushing smaller toll atomizers toward consolidation with integrated gas suppliers. Medical implant service bureaus dependent on traceable powder provenance now face extended supplier qualification timelines.
Aviation procurement teams are consolidating vendor lists from 15-20 qualified additive suppliers per platform to 3-5 strategic partners with captive heat treatment and non-destructive testing capabilities. Boeing and Airbus airframe programs in Washington State and Toulouse now require single-source accountability for flight-critical bracket families. Tier-one aerostructures suppliers in Japan and Italy are responding by acquiring minority stakes in certified European service bureaus.
Metal 3D Printing Service Market Segmentation
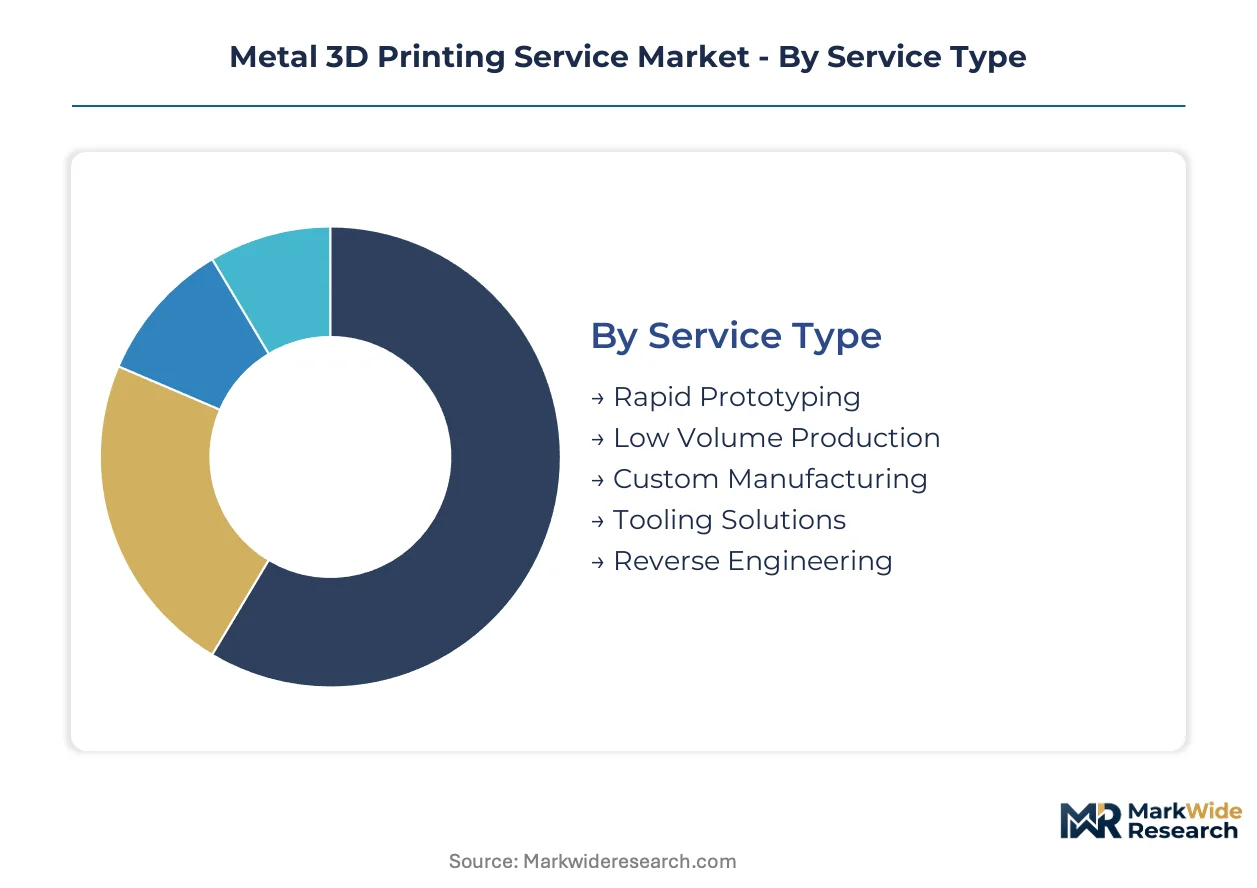
Metal 3D printing service procurement varies sharply by buyer sophistication and risk tolerance. Aerospace primes demand certified production with full traceability, while jewelry makers prioritize speed and surface finish over metallurgical documentation.
Service Type:
Engineering intensity and qualification burden drive buyer selection across service tiers.
- Custom Manufacturing:Process parameter validation and first-article inspection consume 40-60% of project timelines. Medical implant contracts in Germany and France command premium pricing due to EASA Part 21G and FDA 21 CFR Part 820 compliance requirements.
- Rapid Prototyping:Compressed lead times of 48-72 hours for titanium and aluminum geometries dominate early-stage aerospace design iterations. Tier-one suppliers in Toulouse and Seattle outsource iterative bracket development to qualified bureaus with in-house heat treatment.
- Low Volume Production:Bridge manufacturing for 50-500 unit runs avoids tooling investment for automotive sensor housings.
- Tooling Solutions:Conformal cooling channels in mold inserts reduce cycle times for injection molders in Guangdong and Michigan.
- Reverse Engineering:Legacy part digitization serves defense maintenance depots with obsolete drawings.
Custom manufacturing leads on scale; rapid prototyping leads on momentum.
Technology:
Capital intensity and material compatibility shape adoption patterns across modalities.
- Selective Laser Melting:Mature qualification pathways in medical implants and aerospace brackets anchor highest-value contract streams. EOS and Nikon SLM Solutions systems in Munich and Lübeck dominate European aviation supply chains.
- Binder Jetting:Cost parity pursuit with metal injection molding for stainless steel and copper alloys drives fastest expansion. Service bureaus pairing ExOne systems with HIP furnaces achieve 99.8% density for firearm and automotive sensor applications.
- Electron Beam Melting:Vacuum environment suits reactive titanium alloys for orthopedic implants.
- Direct Metal Laser Sintering:Legacy terminology still used in dental laboratory procurement specifications.
- Directed Energy Deposition:Wire-arc systems absorb heavy equipment repair demand from Caterpillar and Baker Hughes remanufacturing operations.
Selective laser melting holds installed base dominance; binder jetting shows steepest expansion trajectory.
Application:
Regulatory stringency and performance requirements fragment addressable markets.
- Aerospace Components:Flight-critical titanium structures demand qualified production capacity with full non-destructive testing. Boeing and Airbus programs now consolidate vendor lists to 3-5 strategic partners with captive heat treatment capabilities.
- Medical Implants:Patient-specific cranial implants trigger 180-day FDA 510(k) resubmission timelines for design changes. German and Swiss orthopedic device makers source from certified bureaus with closed-loop powder recycling.
- Industrial Tooling:Conformal-cooled mold inserts reduce injection molding cycle times for automotive tier-twos.
- Consumer Products:Eyewear and watch case production favors binder jetting for stainless steel surface finish.
- Architectural Models:Facade component prototyping serves design studios in London and Milan.
Aerospace components command revenue concentration; medical implants face regulatory friction.
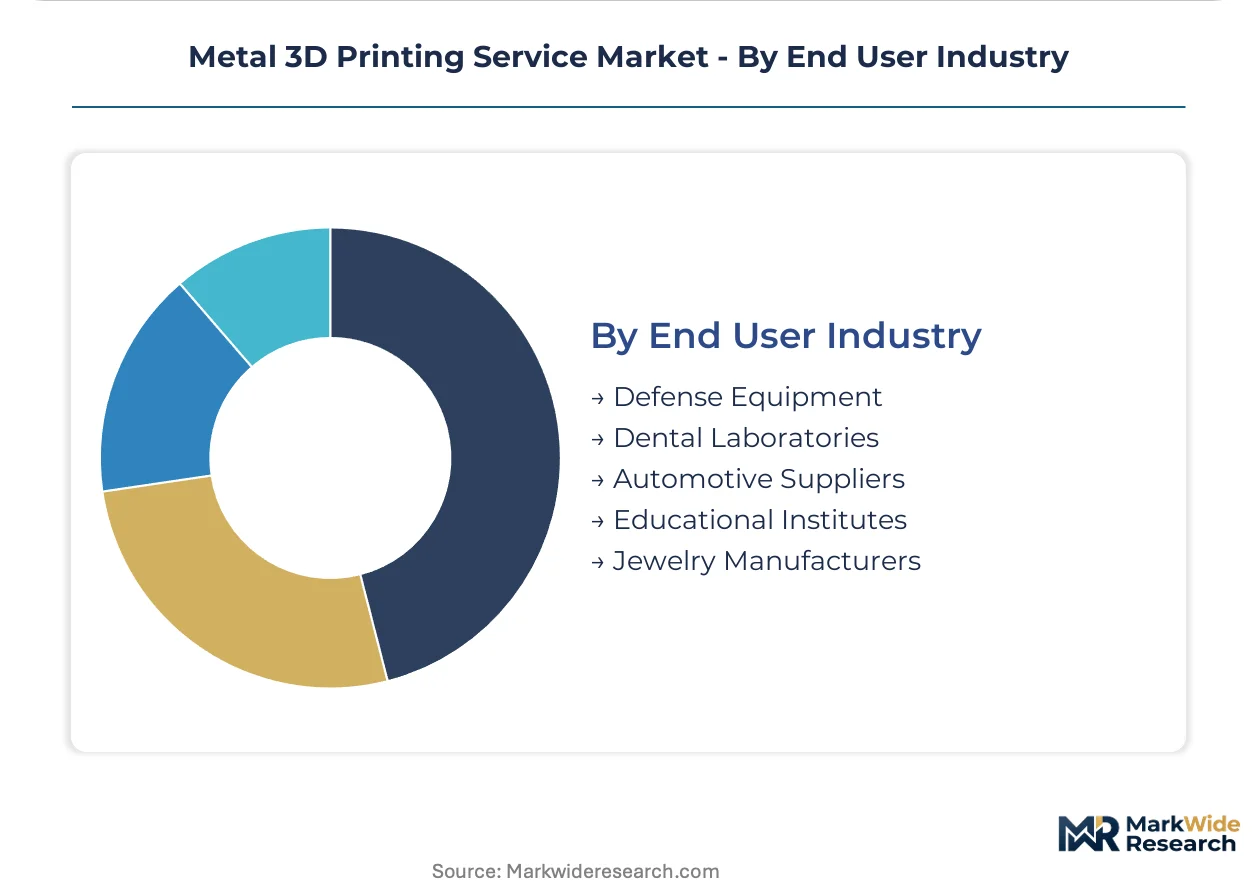
End User Industry:
Certification requirements and volume profiles determine service bureau targeting.
- Defense Equipment:Legacy system sustainment drives reverse engineering demand with ITAR/EAR compliance. US and European maintenance depots outsource obsolete part reproduction to qualified additive suppliers.
- Automotive Suppliers:Aluminum bracket near-shoring avoids EU Green Deal carbon border adjustment tariffs on Chinese die-cast imports. Tier-twos in Stuttgart and Turin qualify domestic service bureaus for production contracts.
- Dental Laboratories:Cobalt-chrome and titanium frameworks shift from casting to direct metal laser sintering.
- Educational Institutes:Research partnerships with technical universities train scarce metallurgical engineers.
- Jewelry Manufacturers:Precious metal direct printing serves luxury brands in Geneva and Mumbai.
Defense equipment sustains premium pricing; automotive suppliers drive volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as service bureaus migrate toward jurisdictions with streamlined certification pathways and lower compliance overhead for powder traceability and emissions control.
Germany
EASA Part 21G production organization approvals lock in multi-year service agreements for aviation primes seeking qualified titanium bracket suppliers. REACH Annex XVII enforcement on nickel compound emissions forces powder atomizers in North Rhine-Westphalia to install wet scrubbing infrastructure. Munich and Lübeck anchor industrial clusters where EOS and Nikon SLM Solutions systems dominate European aviation supply chains.
United States
FDA 21 CFR Part 820 quality system requirements and FAA certification pathways concentrate medical implant and flight-critical part production around qualified bureaus. ITAR compliance mandates shape defense contractor procurement for legacy system sustainment. Washington State and Greater Boston host Boeing and Airbus program offices consolidating vendor lists to strategic partners with captive heat treatment.
China
MIIT industrial additive manufacturing directives accelerate domestic powder-bed fusion capacity installation for aerospace and medical verticals. Dual carbon goals pressure service providers to adopt closed-loop argon recycling for titanium production. Yangtze River Delta and Pearl River Delta clusters concentrate mold insert fabrication for conformal cooling applications in automotive supply chains.
India
PLI scheme incentives for medical devices attract contract manufacturers establishing powder-bed fusion capacity in Gujarat and Telangana. CDSCO regulatory alignment with FDA pathways reduces qualification timelines for orthopedic implant exports. Domestic hospital chains in Maharashtra and Karnataka source patient-specific cranial implants from certified local bureaus.
Japan
METI technology roadmaps prioritize wire-arc additive for heavy equipment remanufacturing and energy sector repair operations. JIS standards development for metal AM processes lags European certification maturity, creating import dependence for flight-critical components. Nagoya and Osaka industrial zones concentrate directed energy deposition services for automotive tooling applications.
Metal 3D Printing Service Market Competitive Landscape
Strategic partnerships dominate the current landscape as tier-one suppliers acquire minority stakes in certified European bureaus to secure captive capacity. The vendor base stratifies across three tiers: integrated system manufacturers with captive service arms, independent qualified bureaus with full NDT and heat treatment capabilities, and rapid prototyping shops lacking production certification. Two competitive moves define positioning: backward integration into powder atomization to control material provenance, and geographic expansion into India and Southeast Asia to capture PLI incentives and near-shore demand.
Among Germany-based system manufacturers, EOS and Nikon SLM Solutions anchor the premium equipment supply tier, while Materialise occupies a distinct position bridging digital workflow software to qualified production parameters. These three entities exemplify divergent strategic archetypes: EOS represents integrated hardware-qualification partnerships with aviation primes, Nikon SLM Solutions exemplifies multi-laser architecture specialization for large-format structures, and Materialise anchors software-defined manufacturing orchestration across distributed production networks.
| Leading Market Players |
|---|
| EOS |
| BLT |
| Nikon SLM Solutions |
| 3D Systems |
| Colibrium Additive |
| Materialise |
| Stratasys Direct Manufacturing |
| Shapeways |
| Protolabs |
| Others |
Pricing and Supply Chain Analysis
Binder jetting's convergence with cold isostatic pressing is collapsing the cost gap with metal injection molding while simultaneously redrawing supplier power maps across European contract manufacturing. EOS and Nikon SLM Solutions anchor premium pricing tiers through multi-laser system lock-in, whereas independent service bureaus face margin compression from argon supply volatility and REACH compliance overhead.
Pricing Analysis
Distributor margins for qualified aerospace production run 15-25% above rapid prototyping tiers due to EASA Part 21G certification bundling. Three-tier pricing structure across premium certified production, standard industrial runs, and economy prototyping reflects quality grade and traceability documentation intensity. Cost compression in economy-tier prototyping is intensifying because binder jetting service bureaus compete with metal injection molding on stainless steel volume. Automotive tier-twos in Stuttgart exhibit highest price sensitivity; aviation primes in Toulouse and Seattle demonstrate lowest sensitivity due to single-source accountability requirements.
Supply Chain Analysis
Dual-sourcing mandates from Boeing and Airbus programs force qualified bureaus to maintain redundant heat treatment and non-destructive testing partnerships. Powder atomization concentrates in Germany, Belgium, and Sweden; machine tool supply rests on EOS, Nikon SLM Solutions, and Trumpf. Titanium powder, argon shielding gas, and multi-laser system components constitute critical input dependencies. Single-source vulnerability in helium refining from Qatar and Russia exposes laser powder-bed fusion operators to price volatility. Distribution runs through direct OEM contracting for aviation primes and regional service bureau networks for medical implant makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal 3D printing services function as a regulatory compounder where EASA Part 21G production organization approvals create multi-year revenue lock-in for qualified suppliers. The analysis identifies three stakeholder archetypes with divergent strategic imperatives.
For Market Incumbents: Lock in aviation prime vendor consolidation by acquiring captive heat treatment and non-destructive testing capabilities before Boeing and Airbus programs finalize 3-5 partner shortlists. Backward integration into closed-loop argon atomization defends margin position against powder traceability cost inflation from REACH Annex XVII enforcement.
For New Entrants and Emerging Players: The mid-tier price-point gap between EOS-certified production and rapid prototyping shops creates white-space opportunity in automotive sensor housings and firearm components. Target India's PLI scheme jurisdictions in Gujarat and Telangana for orthopedic implant contract manufacturing with 5% incentive capture. Pursue binder jetting-HIP convergence as the go-to-market angle for metal injection molding displacement.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent qualified bureaus with EASA Part 21G approval but without captive powder supply. Long-term viability hinges on certification moat sustainability across the analysis window. Monitor FDA 510(k) resubmission timeline compression as the inflection signal for medical implant service provider profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Atomization | Closed-loop argon recycling cuts titanium input costs and satisfies REACH traceability mandates. |
| Multi-Laser System Capacity Expansion | Nikon SLM Solutions architectures compress lead times for large-format aerospace bracket families. |
| Geographic Expansion into India PLI Zones | Gujarat and Telangana facilities capture 5% incentive on incremental medical device sales. |
| HIP Furnace Pairing with Binder Jetting | ExOne systems achieve 99.8% density to challenge metal injection molding on stainless steel volume. |
| Aviation Prime Vendor Consolidation | Single-source accountability requirements from Boeing and Airbus programs lock in multi-year contracts. |
Research Methodology
Multiple input streams — primary interviews with contract manufacturing executives, aviation procurement officers, and biomedical engineers; secondary validation through EASA certification databases, FDA 510(k) filings, and SEC equipment supplier disclosures — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured process parameter development timelines and powder recycling economics from German and French service bureaus. Secondary sources included REACH enforcement records, MIIT industrial additive directives, and customs data on titanium powder trade flows.
Data-stream reconciliation across the analysis window applied segment-specific growth assumptions for selective laser melting, binder jetting, and directed energy deposition modalities. Modeled dimensions spanned service type, technology, application, and end-user industry vertical. CAGRs were derived from installed base expansion curves and qualified production capacity utilization rates. Forecast inputs incorporated aviation prime vendor consolidation velocity and FDA regulatory pathway evolution for patient-specific implants.
Caveats apply where EASA Part 21G approval timeline acceleration or helium supply disruption from Qatar and Russia could materially shift the outlook. Forecasts reflect assumptions on certification barrier sustainability and powder atomization consolidation rates. Deviation in REACH enforcement intensity or aviation OEM dual-sourcing policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing Service Bureaus Market