
 Digital 3D Printing Market | 2026-2036
Digital 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital 3D Printing Market Analysis
The EU Green Deal is recalibrating procurement criteria across European manufacturing, compelling buyers to prioritize low-carbon additive processes. Stratasys leverages its fused deposition platform to serve certified aerospace workflows. EOS GmbH anchors industrial metal printing through its selective laser sintering systems. Materialise competes on software-to-hardware integration for patient-specific medical devices.
Digital 3D printing encompasses layer-by-layer fabrication from digital models, typically achieving tolerances of ±0.1 mm to ±0.3 mm depending on process parameters, with primary purpose spanning rapid prototyping, tooling, and end-use part production across industrial and medical domains. Fused deposition modeling occupies the broadest installed base due to low equipment cost and material accessibility, while selective laser sintering captures premium margin pools in aerospace and healthcare where metal durability and biocompatibility command pricing power. Powder bed fusion is displacing conventional casting in low-volume, high-complexity geometries where tooling amortization proves uneconomical.
FDA clearance pathways for patient-matched implants and EPA emissions standards for volatile photopolymer resins jointly shape product development timelines and facility siting decisions in the United States. EMA medical device regulations and REACH chemical restrictions in Europe impose parallel compliance burdens on material formulations and post-processing workflows. Stakeholders must monitor divergence between FDA breakthrough device criteria and EU MDR conformity assessment requirements when allocating R&D budgets across geographic markets.
Market Dynamics
Flight-critical component certification is rewriting competitive entry barriers in aerospace additive manufacturing, forcing equipment makers to absorb multi-year validation cycles before capturing OEM qualification status.
Growth Catalysts
- EU Green Deal procurement mandates:Public buyers across Germany, France, and the Netherlands now embed carbon intensity thresholds in additive manufacturing tenders, redirecting volume toward low-energy powder bed fusion systems.
- Titanium aluminide lattice structures:Aerospace engine manufacturers deploy these printed components for turbine blades, cutting weight by 40% versus cast equivalents while maintaining creep resistance at elevated temperatures.
- Patient-matched cranial implants:Neurosurgical centers in Belgium, Switzerland, and the United Kingdom accelerate adoption of PEEK and titanium patient-specific implants, compressing preoperative planning from weeks to 48 hours.
Market Restraints
- Noble metal powder volatility:Titanium and cobalt-chrome feedstock prices swing with aerospace build rates, squeezing margins for service bureaus locked into fixed-price medical device contracts.
- Post-processing bottleneck concentration:Hot isostatic pressing and precision machining capacity clusters in southern Germany and northern Italy, creating geographic chokepoints for aerospace part qualification.
- REACH chemical restrictions:ECHA scrutiny of photopolymer resin constituents forces reformulation of dental and hearing aid workflows, extending material validation timelines by 12-18 months.
Strategic Opportunities
- Swiss and Austrian medical device corridors:Underpenetrated precision manufacturing ecosystems around Basel and Vienna offer captive demand for ISO 13485-certified additive service providers.
- Multi-material extrusion convergence:Integration of continuous fiber reinforcement with thermoplastic deposition opens structural automotive applications previously reserved for stamped metal.
- CSRD supply chain disclosure rules:Large EU manufacturers must report Scope 3 emissions from subcontractors, creating preference for regional additive suppliers with verified carbon footprints over Asian tool-and-die imports.
Industry Challenges
- Process-specific metallurgical expertise:Qualified technicians who can interpret melt pool dynamics and predict microstructural anomalies in nickel superalloys command premium wages, constraining scale-up for Tier 2 suppliers.
- FDA breakthrough device pathway divergence:Patient-matched implant sponsors face mismatched evidentiary requirements between FDA de novo and EU MDR Annex IX conformity routes, forcing parallel clinical investments.
- Legacy ERP integration friction:Additive job scheduling and traceability systems require bespoke middleware to connect with SAP and Oracle deployments dominant at major aerospace primes, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital 3D Printing Market |
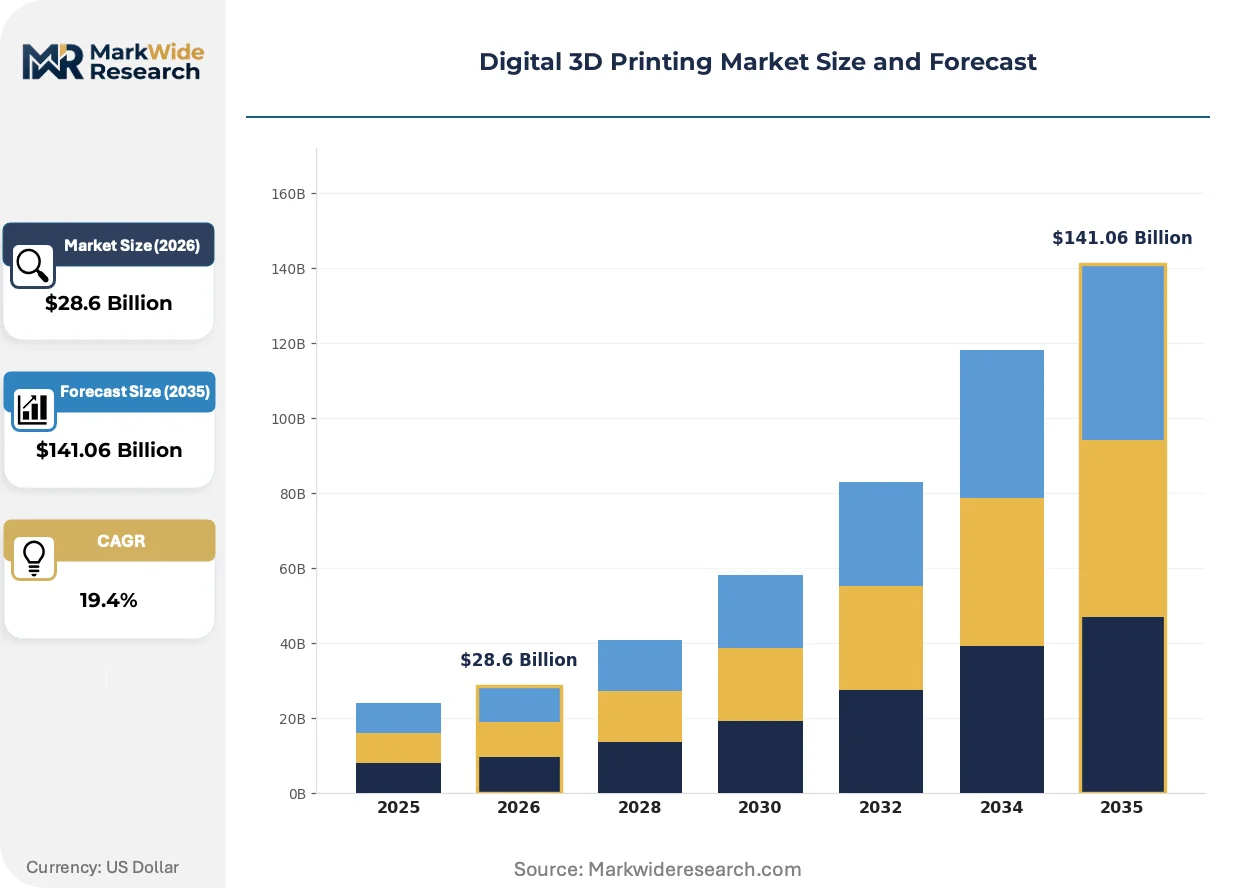
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Material Type: Plastic, Metal, Ceramic, Composite End User: Aerospace, Healthcare, Automotive, Consumer Goods Technology: Binder Jetting, Material Extrusion, Powder Bed Fusion, Vat Photopolymerization |
| Companies Covered | Stratasys, EOS GmbH, HP Development Company, 3D Systems, Materialise, Xometry, Protolabs, Carbon, Renishaw, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital 3D Printing Market Emerging Trajectories
Process monitoring systems and sustainable feedstock chemistries are compressing the gap between prototype validation and production qualification across European industrial clusters.
Continuous fiber-reinforced thermoplastic printing is rewriting structural part economics for mobility applications. Automotive seating and interior frame manufacturers in Germany and the Czech Republic pilot these systems for 500-unit vehicle programs. The technology is compressing tool-up costs from six-figure injection mold investments to five-figure printer depreciation schedules.
EMA's tightened MDR post-market surveillance requirements are forcing implant manufacturers to embed unique device identifiers and batch-level traceability into every printed component. Swiss orthopedic suppliers now dedicate 15-20% of production floor space to automated inspection and serialization stations. The regulatory burden falls heaviest on small-batch cranio-maxillofacial device sponsors with limited quality management infrastructure.
Buyers in Scandinavian defense and maritime sectors now specify performance-based service contracts for spare part availability rather than purchasing printer hardware. Danish ship operators contract for on-demand propeller component printing with guaranteed 72-hour delivery windows. The shift concentrates risk with equipment owners while insulating end-users from capacity utilization volatility.
Digital 3D Printing Market Segmentation
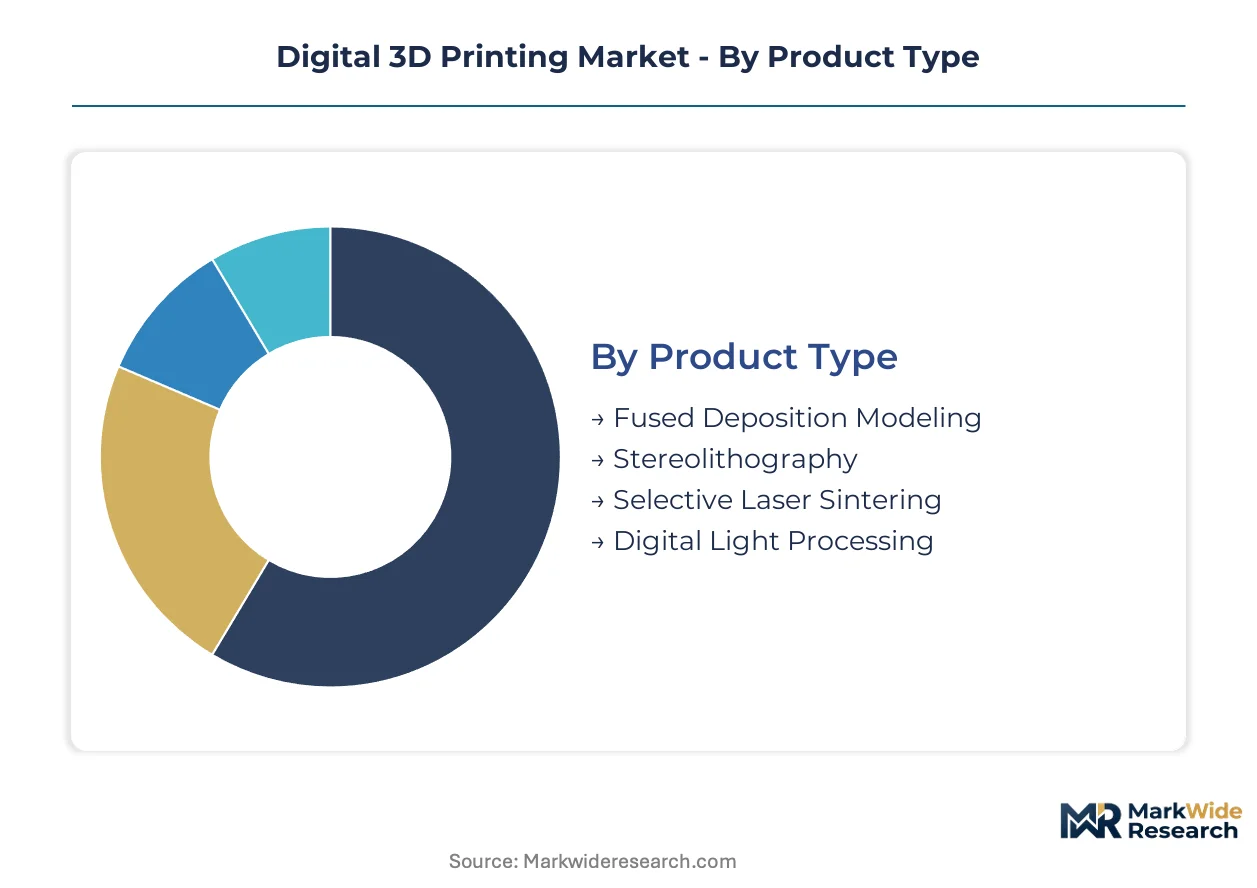
Segmentation reveals where capital deployment and technical expertise concentrate in additive manufacturing. Equipment cost, material certification burdens, and end-use qualification requirements create divergent margin structures across each dimension.
Product Type:
Capital intensity varies by an order of magnitude across these platforms, with metal-capable systems demanding substantially higher upfront investment and facility infrastructure than polymer alternatives.
- Selective Laser Sintering:High-power laser systems fuse polymer or metal powder beds with layer resolutions reaching 80 microns. Aerospace primes in Germany and France prioritize these platforms for flight-critical titanium components where void-free density exceeds 99.5%.
- Fused Deposition Modeling:Thermoplastic filament extrusion operates at equipment costs one-tenth of powder bed alternatives, explaining its dominance in prototyping and educational settings. Stratasys maintains installed base leadership through certified aerospace filament workflows.
- Stereolithography:UV laser curing of photopolymer resins delivers surface finishes unmatched by filament deposition, serving dental aligner and hearing aid manufacturers requiring sub-25-micron precision.
- Digital Light Processing:Projector-based vat polymerization accelerates batch production of identical small parts, finding traction in jewelry and dental model shops across Belgium and the Netherlands.
Most installed capacity flows through Fused Deposition Modeling. Expansion is steepest in Selective Laser Sintering.
Material Type:
Feedstock economics separate commodity polymer suppliers from specialized metal powder producers serving regulated medical and aerospace channels.
- Metal:Titanium, aluminum, and nickel superalloy powders command pricing multiples over polymer feedstock, with plasma atomization and gas atomization processes determining particle sphericity and flow characteristics essential for consistent melt pool behavior.
- Plastic:ABS, PLA, and nylon filaments dominate volume through accessibility and low barrier to entry, though aerospace-certified grades from Solvay and Arkema carry 4-5x premiums over commodity extrusion materials.
- Ceramic:Alumina and zirconia formulations serve dental crown production and investment casting shells, with binder jetting workflows requiring debinding furnaces that extend facility capital requirements.
- Composite:Continuous carbon fiber reinforcement embedded in thermoplastic matrices is displacing aluminum in automotive seating structures and drone frames where stiffness-to-weight ratios determine performance.
Plastic feedstock generates the highest absolute volume. Metal applications are climbing the fastest as qualification timelines compress.
End User:
Customer segmentation maps directly to regulatory burden and contract value, with medical and aerospace buyers demanding traceability systems that consumer goods producers rarely implement.
- Aerospace:Engine manufacturers and airframers deploy additive for turbine blades, fuel nozzles, and structural brackets where topology optimization reduces part count and assembly labor. FAA and EASA certification requirements extend validation cycles to 18-36 months.
- Healthcare:Patient-matched cranial implants and surgical guides require ISO 13485 quality systems and EMA MDR technical documentation, with Swiss and Belgian orthopedic centers driving adoption of PEEK and titanium devices.
- Automotive:Tooling and low-volume production parts dominate current applications, though BMW and Porsche pilot structural aluminum components for electric vehicle battery housings.
- Consumer Goods:Eyewear, footwear, and electronics housings exploit design freedom for aesthetic differentiation, with Adidas and Luxottica operating captive additive facilities for limited-edition production.
Aerospace commands the highest average contract value. Healthcare is expanding most quickly as regulatory pathways stabilize.
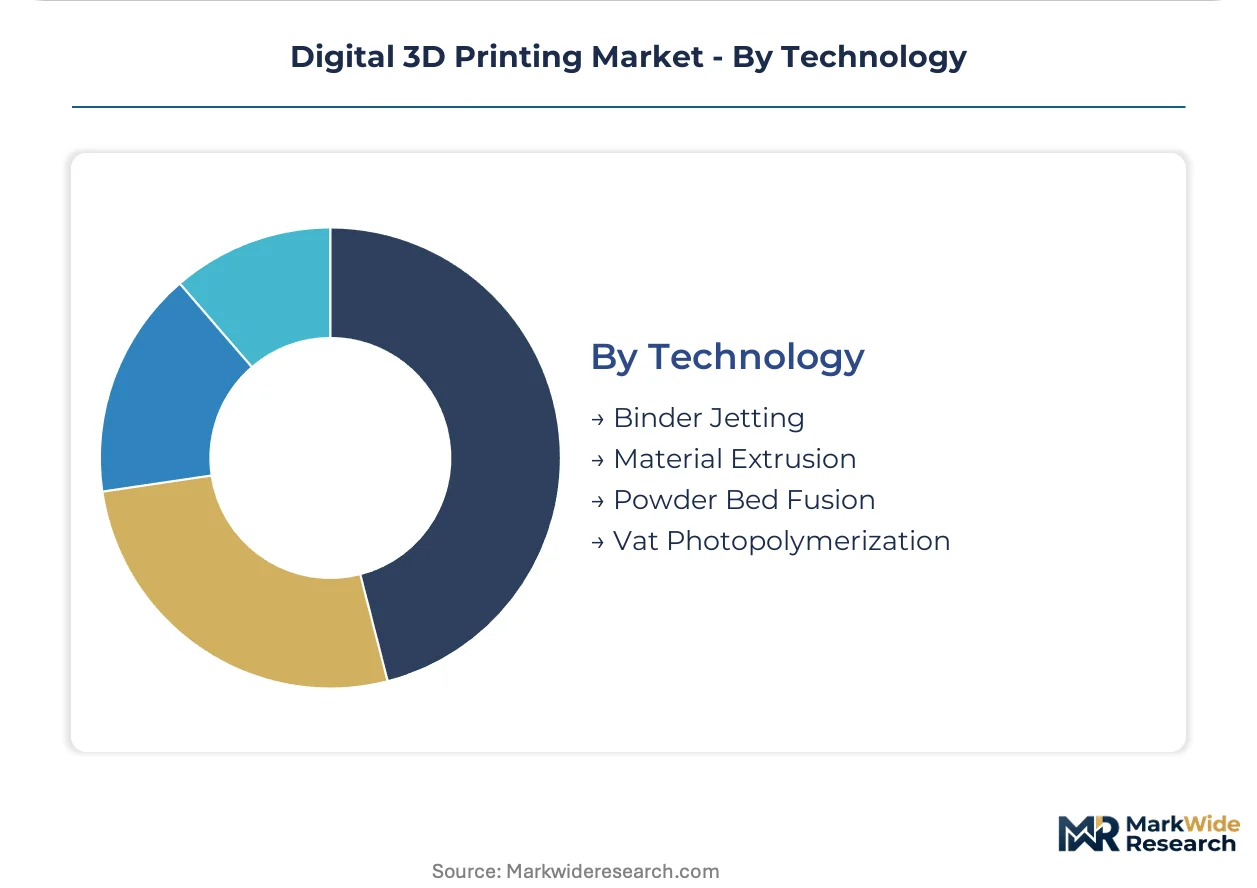
Technology:
Process selection determines achievable geometry complexity, surface finish, and production economics, with powder bed fusion and material extrusion representing opposing poles of the capability spectrum.
- Powder Bed Fusion:Laser or electron beam energy selectively melts metal or polymer powder layers, producing fully dense parts with mechanical properties approaching wrought material. EOS GmbH and SLM Solutions anchor European supply for aerospace and medical applications.
- Material Extrusion:Deposition of thermoplastic or concrete materials through heated nozzles offers the lowest equipment cost and broadest material compatibility, though anisotropic strength limits structural applications.
- Vat Photopolymerization:Stereolithography and DLP systems cure liquid resin with light energy, delivering injection-mold-equivalent surface quality for dental and jewelry applications where aesthetics dominate material properties.
- Binder Jetting:Liquid binding agents join powder layers before sintering or infiltration, enabling sand casting core production and metal part fabrication without thermal gradients that cause residual stress in laser-based systems.
Material Extrusion hosts the largest installed base. Powder Bed Fusion is gaining share fastest as metal qualification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technicians in powder bed fusion and metallurgical process control cluster in southern Germany, creating a talent moat that shapes competitive positioning across European additive manufacturing.
Germany
Aerospace primes in Bavaria and Baden-Württemberg drive demand for flight-critical titanium components, with BMW and Porsche piloting structural aluminum for electric vehicle battery housings. The EU Green Deal procurement mandates embed carbon intensity thresholds in public tenders, redirecting volume toward low-energy systems. Industrial clusters around Munich and Aachen host EOS GmbH and Fraunhofer research institutes anchoring selective laser sintering development.
United States
FDA clearance pathways for patient-matched implants and EPA emissions standards for volatile photopolymer resins jointly shape product development timelines. Defense and medical device manufacturers in Greater Boston and the Pacific Northwest concentrate demand for ISO 13485-certified workflows. Stratasys leverages its fused deposition platform to serve certified aerospace applications from Minnesota operations.
Belgium
Neurosurgical centers in Leuven and Brussels accelerate adoption of PEEK and titanium patient-specific cranial implants, compressing preoperative planning from weeks to 48 hours. EMA medical device regulations impose parallel compliance burdens on material formulations and post-processing workflows. Materialise anchors software-to-hardware integration for medical devices from its Leuven headquarters.
Switzerland
Orthopedic suppliers around Basel dedicate 15-20% of production floor space to automated inspection and serialization stations under tightened MDR post-market surveillance requirements. Swissmedic oversight of implant quality systems creates barrier to entry for non-certified competitors. The Basel-Vienna corridor offers underpenetrated precision manufacturing ecosystems for ISO 13485-certified additive service providers.
United Kingdom
Renishaw and aerospace supply chain participants in the Midlands and Southwest England focus on metal powder bed fusion for turbine blade applications. Divergence between FDA breakthrough device criteria and EU MDR Annex IX conformity routes forces parallel clinical investments for patient-matched implant sponsors. The Midlands cluster concentrates post-processing capacity for aerospace part qualification.
Digital 3D Printing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in additive manufacturing. Equipment manufacturers absorbing multi-year validation cycles for flight-critical certification face fundamentally different economics than software-anchored platforms connecting distributed demand to fulfillment networks. Three archetypes dominate: integrated hardware-software systems builders, specialized metal powder bed fusion equipment makers, and digital manufacturing marketplaces linking buyers to production capacity. Consolidation pressure concentrates among mid-scale service bureaus squeezed between noble metal powder volatility and fixed-price medical contracts.
Among German-origin systems specialists, EOS GmbH exemplifies the premium industrial tier anchored in selective laser sintering platforms. Stratasys represents the filament-based workflow category serving certified aerospace applications through fused deposition expertise. Materialise occupies a distinctive position bridging software-to-hardware integration for regulated medical device channels. These three entities illustrate how geographic clustering around research institutes and regulatory expertise creates defensive positioning against Asian equipment competitors.
| Leading Market Players |
|---|
| Stratasys |
| EOS GmbH |
| HP Development Company |
| 3D Systems |
| Materialise |
| Xometry |
| Protolabs |
| Carbon |
| Renishaw |
| Others |
Supply Flow & Price Mechanics
Titanium and cobalt-chrome powder feedstock flows from plasma atomization facilities in Germany and the United States through aerospace primes and medical device contract manufacturers, with price stratification tracking certification burden rather than raw material cost alone. Aerospace OEMs absorb premium pricing for EASA-qualified lot traceability while service bureaus serving dental aligner markets compete on commoditized photopolymer resin throughput.
Pricing Analysis
Bundled hardware-software-service contracts dominate aerospace and medical channels, while unbundled per-kilogram powder pricing prevails in prototyping service bureaus. Three-tier pricing structure across flight-certified, industrial-grade, and desktop systems reflects validation timeline differentials, with FDA breakthrough device pathway investments adding fifteen to twenty percent overhead to patient-matched implant workflows. Cost compression in polymer filament tiers is intensifying because Chinese equipment entrants are eroding Stratasys's historical installed base premiums. Dental laboratories exhibit highest price sensitivity, locking in volume commitments for photopolymer resins, whereas neurosurgical centers demonstrate lowest sensitivity due to reimbursement coverage for cranial reconstruction procedures.
Supply Chain Analysis
Gas-atomized titanium powder supply rests on specialty producers in Germany, the United Kingdom, and the United States, with plasma spheroidization capacity concentrated around aerospace clusters in Bavaria and the American Midwest. Nickel superalloy and aluminum feedstocks draw from conventional powder metallurgy channels, while photopolymer resin formulations hinge on Japanese and German specialty chemical houses. Single-source vulnerability concentrates in hot isostatic pressing capacity clustered in southern Germany and northern Italy, creating geographic chokepoints for aerospace part qualification. Distribution runs through certified service bureaus for regulated medical and flight-critical components, with direct equipment sales dominating prototyping and educational markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in additive manufacturing hinges on compressing noble metal powder exposure through closed-loop recycling systems and shifting volume toward patient-matched implant premiums where regulatory moats sustain pricing power.
For Market Incumbents: Anchor defensive positioning around EASA and FAA qualification status, extending validation timelines that emerging Asian equipment makers cannot easily replicate. Deepen backward integration into gas-atomized powder production to offset titanium price volatility squeezing fixed-price medical contracts. Prioritize software-to-hardware integration investments that lock in switching costs for hospital procurement committees evaluating cranial implant workflows. For New Entrants and Emerging Players: Regional additive service providers in the Swiss-Austrian corridor offer white-space access, with Basel and Vienna precision manufacturing ecosystems underpenetrated by ISO 13485-certified competitors. Target automotive seating and interior frame applications where continuous fiber-reinforced thermoplastic printing is displacing aluminum stampings in 500-unit vehicle programs. Pursue performance-based spare part availability contracts with Scandinavian defense and maritime buyers, insulating end-users from capacity utilization risk while concentrating equipment ownership economics. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale service bureaus face simultaneous noble metal powder margin compression and fixed-price medical contract rigidity. Long-term viability across the analysis window favors asset-light digital manufacturing platforms connecting distributed demand to certified production capacity over capital-heavy equipment manufacturers absorbing multi-year aerospace validation cycles. Watch FDA-EU MDR regulatory divergence as inflection indicator, with parallel clinical investment requirements favoring well-capitalized sponsors capable of sustaining dual-track approval strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Powder Recycling Integration | Captive titanium recovery reduces feedstock cost exposure for aerospace contract manufacturers. |
| Patient-Matched Implant Software Platform | Preoperative planning compression from weeks to 48 hours locks hospital system preference. |
| Continuous Fiber Thermoplastic Capacity Buildout | Automotive seating applications displace aluminum in German and Czech vehicle programs. |
| CSRD-Verified Carbon Footprint Certification | Scope 3 disclosure rules redirect EU manufacturer procurement from Asian tool-and-die imports. |
| Performance-Based Spare Part Service Contracts | Danish ship operators now specify guaranteed 72-hour propeller component delivery windows. |
Methodological Framework
Direct dialogue with additive manufacturing equipment engineers, aerospace procurement leads at Tier 1 suppliers, hospital biomedical engineering directors, and photopolymer resin formulation chemists grounded qualitative assessments in operational reality. Secondary validation drew from EASA certification databases, FDA 510(k) and de novo filing records, EU MDR technical documentation, and customs trade data tracking titanium powder flows. Bottom-up installed base estimates triangulated against top-down addressable market calculations across product type, material, end user, and technology dimensions.
Segmented projections across powder bed fusion, material extrusion, vat photopolymerization, and binder jetting technologies combined with metal, polymer, ceramic, and composite feedstock trajectories. Aerospace, healthcare, automotive, and consumer goods end-use demand curves integrated equipment replacement cycles and regulatory approval timelines throughout the forecast period. CAGRs derived from elasticity modeling against historical qualification compression patterns and EU Green Deal procurement mandate adoption curves.
Revisions become necessary when EASA-FAA regulatory divergence accelerates, noble metal powder price volatility exceeds historical bands, or Chinese equipment entrants achieve aerospace qualification breakthroughs. Forecasts reflect assumptions around certification timeline stability and REACH chemical restriction implementation schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Europe Industrial 3D Printing Market