
 Colombia Telecom Tower Market | 2026-2036
Colombia Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Telecom Tower Market Insights
Steel is consolidating its position as the dominant structural material for lattice and monopole configurations across Colombia, displacing aluminum in high-wind zones due to superior load-bearing economics at elevation. American Tower Corporation leverages its nationwide footprint to sustain co-location revenue density in urban corridors. SBA Communications Corporation anchors its presence through long-term lease agreements with Claro and Movistar. Andean Telecom Partners differentiates via specialized deployment in secondary cities where macro site penetration remains below metropolitan benchmarks.
Colombia telecom towers are steel or reinforced concrete structures engineered to support multiple antenna arrays, transmission lines, and auxiliary power systems at heights typically ranging from 30 to 120 meters, serving as the physical backbone for wireless signal propagation across varied topography. Lattice towers dominate the type segment due to their structural adaptability for multi-tenant loading on Andean ridgelines where wind shear exceeds 150 km/h. 5G NR infrastructure represents the fastest-expanding technology segment as operators densify mid-band coverage, while passive infrastructure commands the largest margin pool within the infrastructure category given its asset-light operational model and recurring lease structures.
The Colombian Ministry of Information and Communications Technologies shapes market access through spectrum auction terms that mandate coverage obligations in underserved departments, while the National Infrastructure Agency coordinates right-of-way protocols for fiber backhaul integration. ANE, the national spectrum agency, enforces technical standards for electromagnetic emissions that dictate tower spacing and antenna configuration parameters. Stakeholders must monitor how proposed reforms to infrastructure sharing mandates alter tenancy ratios and capital recovery timelines across the portfolio.
Market Dynamics
Mid-band 5G densification mandates from Colombia's Ministry of Information and Communications Technologies are forcing tower operators to reconfigure site portfolios for multi-tenant loading at tighter spacing intervals across Andean ridgelines.
Growth Catalysts
- Spectrum Coverage Obligations:The Colombian Ministry of Information and Communications Technologies mandates rural 4G and 5G expansion into underserved municipalities, creating tenancy demand in secondary cities.
- Infrastructure Sharing Frameworks:New spectrum allocation rules favor co-location models that reduce per-operator capital intensity while accelerating network rollout timelines.
- Andean Population Density:Bogotá, Medellín, and Cali generate sustained co-location economics that justify steel lattice investments for multi-tenant configurations.
Market Restraints
- Steel Price Volatility:Structural steel input costs fluctuate with global commodity cycles, compressing margin predictability for lattice tower fabrication contracts.
- Right-of-Way Fragmentation:The National Infrastructure Agency coordinates fiber backhaul protocols across departmental jurisdictions, creating permitting delays in rural corridor deployments.
- Wind Load Engineering Constraints:Andean ridgelines experience shear velocities exceeding 150 km/h, requiring reinforced foundation specifications that extend construction timelines.
Strategic Opportunities
- Secondary City Penetration:Macro site density in Colombia's secondary municipalities remains below metropolitan benchmarks, offering first-mower positioning for specialized deployers.
- Passive Infrastructure Monetization:Asset-light operational models with recurring lease structures generate superior margin pools compared to active equipment integration.
- ANE Technical Standard Alignment:Electromagnetic emission standards from the national spectrum agency create compliance barriers that favor established tower operators with proven configuration expertise.
Industry Challenges
- Multi-Tenant Load Engineering:Antenna array proliferation from 5G NR densification requires structural recertification of existing lattice configurations to accommodate heavier transmission line bundles.
- Specialized Installation Labor:Erection crews trained in high-altitude steel assembly across Colombia's cordillera terrain command premium wages that inflate site activation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Telecom Tower Market |
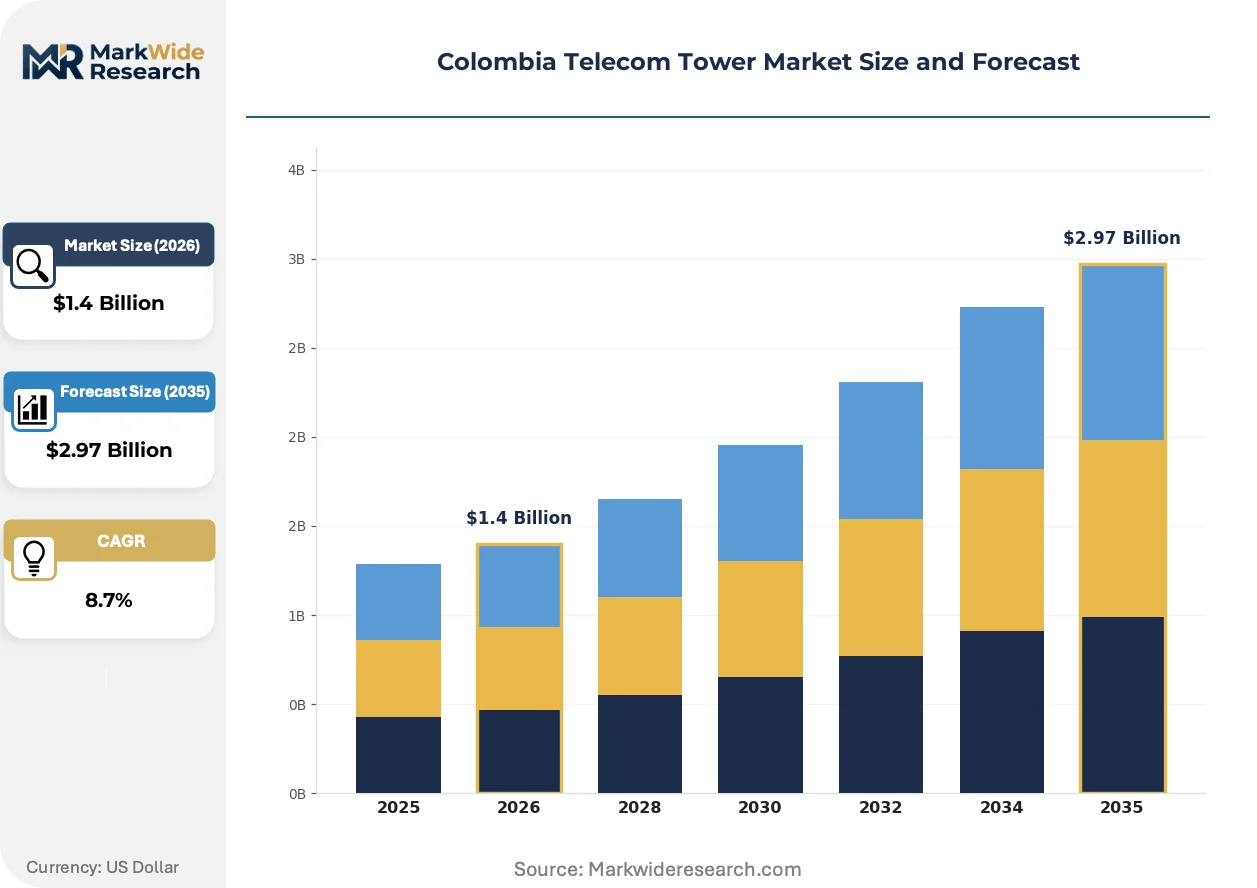
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Monopole, Lattice Tower, Guyed Tower, Rooftop Technology: 4G LTE, 5G NR, Microwave, Fiber Optic End User: MNOs, Private Network Operators, Government Agencies, Enterprises Infrastructure: Passive Infrastructure, Active Infrastructure, Small Cells, DAS |
| Companies Covered | American Tower Corporation, SBA Communications Corporation, Phoenix Tower International, Andean Telecom Partners (ATP), Telesites, Grupo TorreSur, Telxius, Torrecom Partners, Torresec (Innovattel), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Telecom Tower Market Trends and Innovations
Steel structural configurations are displacing aluminum alternatives as operators prioritize load-bearing economics for multi-tenant deployments in high-wind zones. Three convergent forces are reconfiguring how tower assets are engineered, regulated, and monetized across Colombian territory.
Steel lattice configurations are integrating advanced wind-resistance engineering for Andean ridgeline deployments where shear forces exceed 150 km/h. Mobile network operators specify these structures for multi-tenant loading scenarios that accommodate 4G and 5G antenna arrays simultaneously. The technology is integrating foundation specifications that reduce per-site concrete requirements while maintaining structural integrity across Colombia's varied topography.
ANE technical standards for electromagnetic emissions are mandating revised tower spacing and antenna configuration parameters across all new deployments. The regulation compresses permissible site densities in urban corridors while extending coverage obligation timelines for rural municipalities. Operators in the Andean region around Bogotá and Medellín are responding with co-location negotiations that maximize tenancy ratios within constrained geographic footprints.
Lease-based procurement models are displacing build-to-suit ownership structures among mobile network operators seeking capital efficiency. Tower companies with established portfolios capture this shift through long-term tenancy agreements that lock in revenue visibility. The pattern concentrates in Colombia's three major metropolitan clusters where population density justifies shared infrastructure economics over proprietary site development.
Colombia Telecom Tower Market Segmentation
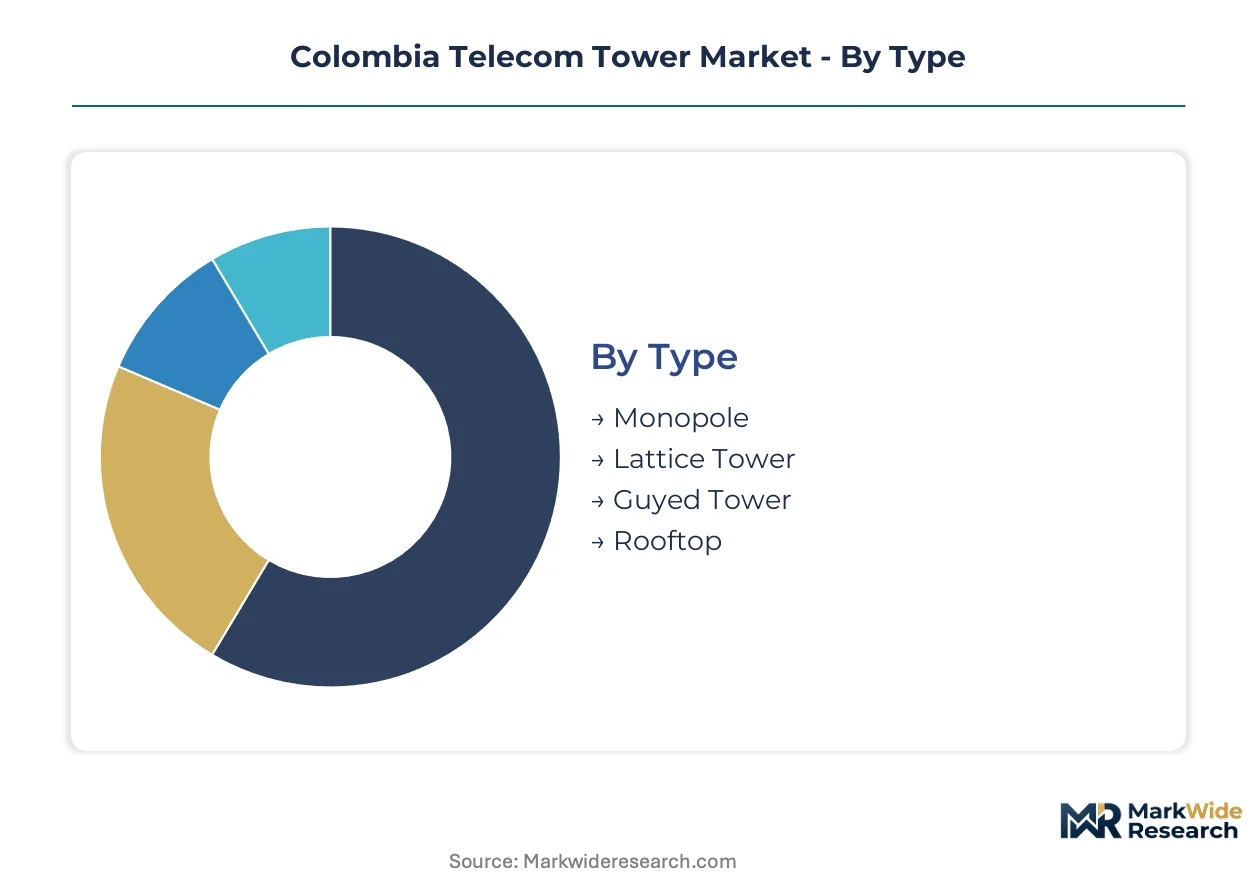
Colombia's telecom tower market segments along structural, technological, and operational dimensions that determine capital deployment patterns across Andean topography. Each segmentation axis reveals distinct margin profiles and tenancy economics that shape operator procurement decisions.
Type:
Supply concentration favors steel fabrication capabilities that can deliver lattice configurations at scale across Colombia's mountainous corridor.
- Lattice Tower:Triangular or square steel frameworks engineered for multi-tenant loading at elevations exceeding 3,000 meters. Demand concentrates along Andean ridgelines surrounding Bogotá and Medellín where wind shear mandates reinforced structural specifications and co-location economics justify higher per-site investment.
- Monopole:Single-shaft steel structures ranging 30-50 meters optimized for urban corridors with constrained footprint availability. Claro and Movistar deploy these across Cali's metropolitan zone where zoning restrictions and aesthetic requirements limit lattice deployment options.
- Guyed Tower:Masts stabilized by tensioned cable arrays requiring expansive ground anchor patterns. Rural municipalities in Colombia's llanos regions utilize guyed configurations where land availability exceeds structural steel cost sensitivity.
- Rooftop:Building-integrated antenna mounting systems leveraging existing commercial and residential structures. Secondary cities including Barranquilla and Cartagena show expanding rooftop tenancy as operators densify coverage without greenfield site acquisition.
Today's leader: Lattice Tower. Tomorrow's challenger: Rooftop.
Technology:
Cost tier differentiation separates legacy 4G deployments from capital-intensive 5G infrastructure requiring densified site portfolios.
- 5G NR:New radio interface operating in mid-band spectrum allocations driving site spacing compression to 500-800 meters in urban corridors. ANE spectrum mandates are accelerating 5G NR tenancy ratios across Bogotá's financial district where enterprises demand low-latency connectivity.
- 4G LTE:Mature radio access technology commanding stable tenancy volumes across Colombia's established metropolitan footprints. Rural coverage obligations from the Ministry of Information and Communications Technologies sustain 4G LTE deployment in municipalities below 50,000 population where 5G economics remain unfavorable.
- Microwave:Point-to-point wireless backhaul for fiber-unreachable sites across cordillera terrain. Microwave links serve as primary backhaul for 15-20% of Colombia's macro sites where National Infrastructure Agency fiber coordination remains incomplete.
- Fiber Optic:High-capacity terrestrial backhaul enabling 10Gbps+ site connectivity. Fiber optic integration commands premium lease rates in Medellín's innovation district where data traffic density justifies dedicated optical termination.
5G NR claims the steepest expansion trajectory; 4G LTE retains the revenue base.
End User:
Customer type fragmentation creates divergent contract structures ranging from long-term MNO leases to project-based government deployments.
- MNOs:Mobile network operators including Claro, Movistar, and Tigo comprise the core tenancy base with 10-15 year lease structures. MNO procurement concentrates co-location demand in Colombia's three primary metropolitan clusters where shared infrastructure economics outperform proprietary site development.
- Government Agencies:Public sector deployments for emergency communications, rural connectivity programs, and defense applications. The Ministry of Information and Communications Technologies directs government agency tower utilization through universal service fund allocations targeting underserved departments.
- Private Network Operators:Industrial and logistics enterprises deploying captive infrastructure for campus and corridor coverage. Mining operations in Antioquia and Cundinamarca drive private network operator demand where public network reliability falls below operational requirements.
- Enterprises:Corporate entities leasing tower space for dedicated WAN extension and IoT aggregation. Enterprise tenancy is expanding in Bogotá's peripheral industrial zones where manufacturing facilities require guaranteed connectivity SLAs.
MNOs anchor current revenue; Private Network Operators are gaining contract velocity.
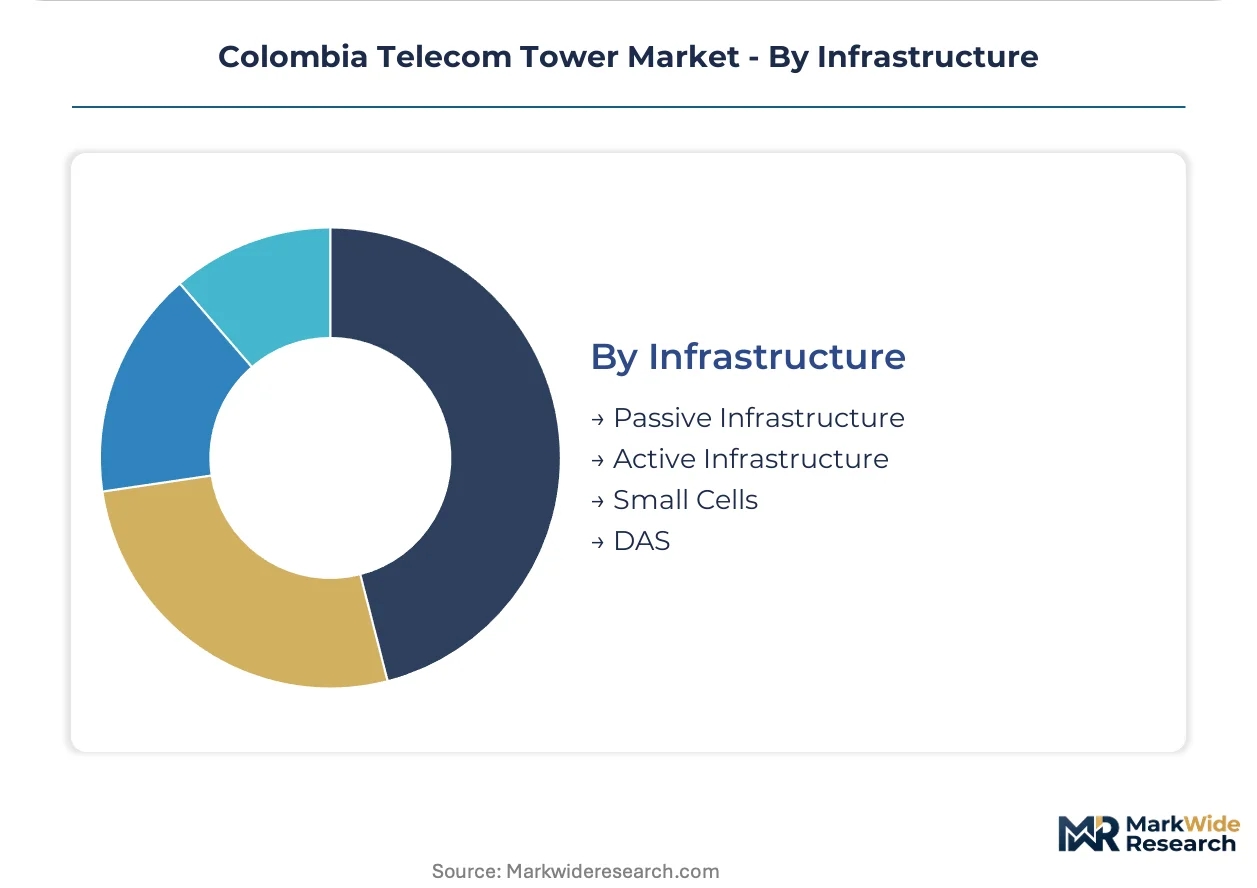
Infrastructure:
Margin structure separates asset-heavy active equipment integration from recurring lease streams in passive infrastructure.
- Passive Infrastructure:Tower structure, power systems, and physical site access without active radio equipment. Passive infrastructure generates superior margin pools through recurring lease structures that minimize operational complexity across Colombia's dispersed site portfolio.
- Small Cells:Low-power radio nodes deployed at 10-20 meter heights for hyperlocal capacity densification. Small cell proliferation is accelerating in Cali's urban core where pedestrian traffic density exceeds macro site spectral efficiency.
- Active Infrastructure:Integrated radio and antenna systems requiring ongoing equipment maintenance and upgrade cycles. Active infrastructure contracts concentrate with tower operators possessing technical integration capabilities for multi-vendor radio environments.
- DAS:Distributed antenna systems providing uniform indoor coverage across commercial complexes and transportation infrastructure. DAS deployment is expanding in Medellín's metro system and Bogotá's El Dorado International Airport where seamless connectivity commands premium tenancy rates.
Passive Infrastructure dominates margin capture; Small Cells are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Andean region surrounding Bogotá anchors tower deployment density in Colombia, with steel lattice configurations dominating ridgeline installations where multi-tenant economics justify reinforced structural investments.
Bogotá Capital District
Mid-band 5G densification and enterprise IoT aggregation drive tenancy demand in Colombia's primary metropolitan cluster. ANE electromagnetic emission standards mandate revised tower spacing that compresses permissible site densities in urban corridors. The financial district and peripheral industrial zones concentrate co-location negotiations as operators maximize tenancy ratios within constrained footprints.
Antioquia Department
Medellín's innovation district and surrounding mining operations generate dual demand streams from MNO coverage expansion and private network deployments. The Ministry of Information and Communications Technologies directs universal service fund allocations toward municipalities below 50,000 population in this department. Secondary cities including Rionegro and La Ceja exhibit macro site penetration gaps that attract specialized tower deployers.
Valle del Cauca Department
Cali's metropolitan zone faces zoning restrictions and aesthetic requirements that limit lattice deployment and accelerate monopole specifications. Claro and Movistar procurement concentrates co-location demand where shared infrastructure economics outperform proprietary site development. The Pacific port corridor drives fiber backhaul integration timelines coordinated through National Infrastructure Agency protocols.
Cundinamarca Department
Rural municipalities surrounding the capital generate coverage obligation deployments from spectrum auction terms mandating 4G expansion. Wind load engineering constraints across cordillera terrain require reinforced foundation specifications that extend construction timelines. Mining enclaves in eastern Cundinamarca sustain private network operator demand where public network reliability falls below operational requirements.
Caribbean Coast
Barranquilla and Cartagena exhibit expanding rooftop tenancy as operators densify coverage without greenfield site acquisition. Hurricane-resistant engineering specifications differentiate structural requirements from Andean wind-load calculations. The coastal corridor's flat topography enables guyed tower configurations where land availability exceeds structural steel cost sensitivity.
Colombia Telecom Tower Market Competitive Landscape
Global majors compete with regional champions across tenancy aggregation and rural deployment capabilities, producing a tiered structure where scale-driven portfolio operators coexist with specialized secondary-city deployers. Market concentration favors established players with proven ANE compliance expertise and existing right-of-way relationships. Three archetypes dominate: nationwide portfolio aggregators, Andean ridgeline specialists, and secondary-municipality first-movers. Competitive dynamics center on long-term lease lock-ins with MNOs and strategic fiber backhaul integration partnerships.
Among nationwide portfolio operators, American Tower Corporation and SBA Communications Corporation occupy positions as tenancy aggregation anchors with established metropolitan footprints. Andean Telecom Partners exemplifies the specialized deployment archetype, targeting secondary cities where macro site density remains below metropolitan benchmarks. These three entities represent distinct strategic postures—scale-driven co-location economics, long-term lease stability, and geographic differentiation—that collectively define competitive positioning across Colombia's varied topography.
| Leading Market Players |
|---|
| American Tower Corporation |
| SBA Communications Corporation |
| Phoenix Tower International |
| Andean Telecom Partners (ATP) |
| Telesites |
| Grupo TorreSur |
| Telxius |
| Torrecom Partners |
| Torresec (Innovattel) |
| Others |
Pricing and Supply Chain Analysis
ANE electromagnetic emission standards mandating revised tower spacing and antenna configurations are compressing permissible site densities in urban corridors, forcing supply chains to prioritize modular steel lattice fabrication with faster reconfiguration cycles and exerting upward pressure on specialized engineering premiums.
Pricing Analysis
Steel price volatility in global commodity markets passes directly through to lattice tower fabrication contracts, compressing margin predictability for operators locked into long-term lease structures. Pricing stratifies across premium, standard, and economy tiers based on wind-load engineering certification and fiber backhaul integration depth. Cost compression in standard-tier deployments is intensifying as Claro and Movistar consolidate procurement volumes. Government agencies exhibit highest price sensitivity due to universal service fund budget constraints, while private network operators in mining enclaves accept premium pricing for guaranteed connectivity SLAs.
Supply Chain Analysis
Decommissioned tower sections from Andean ridgeline sites flow into refurbishment networks for redeployment across Colombia's llanos regions, creating reverse-logistics value recovery in secondary markets. Manufacturing concentration rests on Brazil, Mexico, and domestic Colombian steel fabrication facilities. Structural steel, galvanized coating materials, and concrete foundation inputs anchor cost structures. Single-source vulnerability in specialized high-altitude erection crews creates bottleneck risk. Distribution runs through National Infrastructure Agency-coordinated right-of-way protocols with regional tower operators maintaining site inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's telecom tower market offers margin expansion through passive infrastructure monetization and tenancy ratio optimization as operators shift from build-to-suit ownership to lease-based procurement.
For Market Incumbents: Deepen co-location density in Bogotá and Medellín corridors where ANE spacing constraints limit new site permitting, locking in 10-15 year lease renewals with Claro and Movistar before secondary-city specialists achieve scale. Expand backward integration into steel fabrication partnerships to buffer commodity volatility exposure.
For New Entrants and Emerging Players: Capture macro site penetration gaps in Rionegro, La Ceja, and other Antioquia secondary municipalities where American Tower and SBA Communications maintain lighter footprints. Position through specialized Andean ridgeline engineering capabilities and fast-track ANE compliance certification as differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional deployers possessing established right-of-way relationships in Cundinamarca and Valle del Cauca. Long-term viability hinges on tenancy ratio trajectories across the projection horizon. Monitor Ministry of Information and Communications Technologies spectrum auction timing for coverage obligation intensity signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Passive Infrastructure Portfolio Expansion | Recurring lease structures generate superior margin pools compared to active equipment integration. |
| Secondary City Deployment Acceleration | Macro site density gaps in municipalities below 50,000 population attract first-mover positioning. |
| Fiber Backhaul Integration Partnership | National Infrastructure Agency coordination protocols create competitive moats for established operators. |
| ANE Compliance Certification Investment | Electromagnetic emission standards favor tower operators with proven configuration expertise. |
| Steel Fabrication Backward Integration | Captive supply of structural components buffers global commodity price volatility exposure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tower portfolio managers, MNO procurement leads, ANE technical standards officers, and National Infrastructure Agency coordination staff with secondary validation from customs records, SEC filings of listed tower operators, and Ministry of Information and Communications Technologies spectrum auction documentation. Bottom-up site-level tenancy modeling and top-down infrastructure investment flow analysis were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume projections across structural type, technology generation, end-user category, and infrastructure model dimensions. CAGRs were derived from fitted growth curves calibrated to historical deployment velocity and policy obligation timelines. Forecast inputs incorporated Andean ridgeline wind-load engineering specifications and rural coverage mandate intensity from spectrum auction terms.
Steel price volatility, ANE regulatory amendment timing, and MNO consolidation patterns are the dominant revision risks to modeled outcomes. Practitioners should monitor these triggers for early signals of trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market