
 3D Printer Market | 2026-2036
3D Printer Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printer Market Intelligence
The additive manufacturing engineering talent pool is bifurcating into software-centric digital designers and materials-focused process engineers, creating distinct competitive moats. Stratasys leverages its polymer expertise and healthcare certifications to anchor high-margin medical workflows. EOS GmbH dominates industrial metal printing with selective laser melting platforms that sustain aerospace qualification pipelines.
A 3D printer constructs three-dimensional objects by depositing, fusing, or curing successive layers of material based on digital CAD models, typically achieving layer resolutions between 25 and 100 microns depending on the process. Its primary purpose spans rapid prototyping, direct digital manufacturing of end-use parts, and custom tooling production across industrial and consumer domains. FDM systems occupy the volume-driven desktop and education segments where price sensitivity shapes purchasing. Metal technology commands the fastest expansion trajectory as flight-critical and orthopedic applications harden qualification requirements. Aerospace end users concentrate margin pools through long-term service contracts and certified supply agreements.
ISO/ASTM 52900 standards, FDA 510(k) clearance requirements for patient-specific devices, and EU MDR conformity assessments collectively shape product development cycles and market access barriers. The EPA monitors emissions from powder-based processes under Clean Air Act provisions, while China's SAMR enforces GB standards for industrial equipment safety. Stakeholders must weigh capital allocation between polymer platform scale and metal system qualification timelines as regulatory divergence across jurisdictions intensifies compliance complexity.
Market Dynamics
Flight-certification pipelines for polymer and metal printed components are compressing development cycles while fragmenting supplier tiers between qualified aerospace contractors and unqualified generalists.
Growth Catalysts
- FDA 510(k) pathway expansion:Patient-specific orthopedic implants gain accelerated clearance timelines, pulling hospital procurement toward certified additive workflows.
- China's dual carbon goals:MIIT incentives for localized, waste-reducing production methods redirect automotive tooling investment toward metal powder bed systems.
- Flight-critical aerospace adoption:Tier-1 manufacturers consolidate supply agreements around selective laser melting platforms for turbine brackets and fuel nozzles.
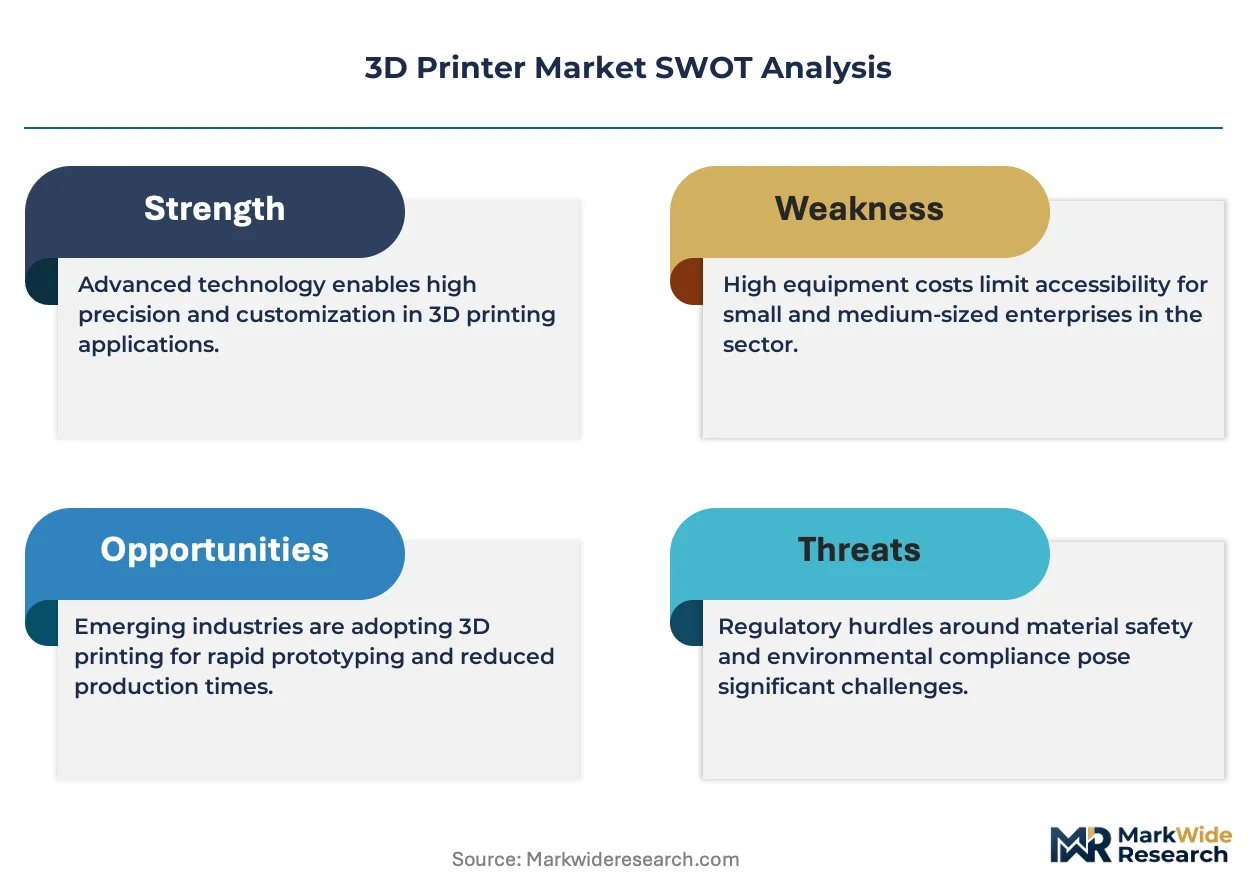
Market Restraints
- Titanium powder cost volatility:Sponge supply concentration in Russia and Kazakhstan generates input price instability for aerospace metal printing.
- EU MDR conformity timelines:Extended assessment periods for patient-matched devices delay revenue recognition for European medical device entrants.
- Post-processing bottleneck:Heat treatment and surface finishing requirements consume 60-70% of total production time, constraining throughput scaling.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract contract manufacturers seeking lower-cost FDA-inspected facilities outside China.
- Copper and aluminum alloy printing:Thermal and electrical conductivity applications in EV heat exchangers and RF components open non-aerospace metal demand.
- Digital inventory models:Spare parts on-demand contracts with industrial asset operators replace physical warehousing in oil and gas maintenance.
Industry Challenges
- Process engineer scarcity:Qualified operators for multi-laser powder bed fusion systems command premium wages, constraining capacity expansion at contract manufacturers.
- ISO/ASTM 52900 implementation gaps:Inconsistent facility certification across jurisdictions complicates cross-border production transfers for multinational OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printer Market |
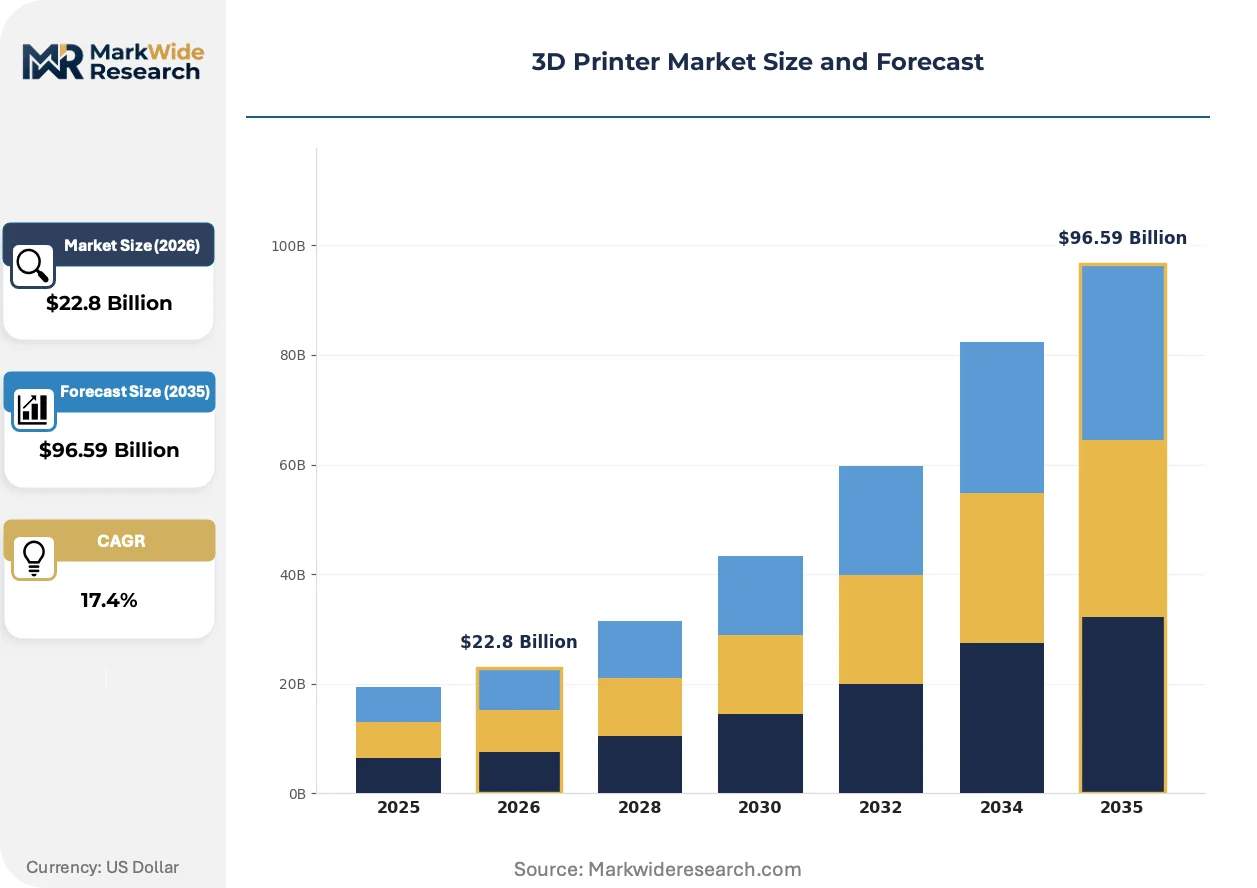
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $96.59 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FDM, SLA, SLS, DLP End User: Education, Aerospace, Automotive, Healthcare Technology: Metal, Plastic, Polymer, Ceramic Application: Prototyping, Manufacturing, Tooling, Art |
| Companies Covered | Stratasys, 3D Systems, HP Development Company, EOS GmbH, Materialise, Protolabs, Bright Laser, Farsoon, Xometry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printer Market Strategic Shifts & Innovations
Multi-laser powder bed fusion architectures and AI-driven process monitoring are compressing qualification timelines while elevating real-time quality assurance standards across safety-critical applications.
Continuous fiber-reinforced thermoplastic printing is supplanting machined aluminum brackets in unmanned aerial vehicle airframes. Chinese and Israeli drone manufacturers now specify automated fiber placement heads on gantry systems for structural members. This displacement collapses tooling lead times from sixteen weeks to seventy-two hours for low-rate initial production runs.
REACH restrictions on nickel powder classifications are forcing European metal printing facilities to relocate post-processing operations to Switzerland and Turkey. The ECHA hazard reclassification elevates occupational exposure compliance costs for German and French job shops. Medical implant producers now prioritize titanium-64 over cobalt-chrome alloys to preempt supply chain disruption.
Hospital systems are consolidating orthopedic implant procurement through long-term service agreements with certified design-to-manufacture partners. Traditional distributor networks lose share as Mayo Clinic, Charité Berlin, and Singapore General Hospital negotiate direct digital inventory contracts. This concentration favors vendors holding simultaneous FDA 510(k) and EU MDR approvals for patient-specific cranial plates and spinal cages.
3D Printer Market Segmentation
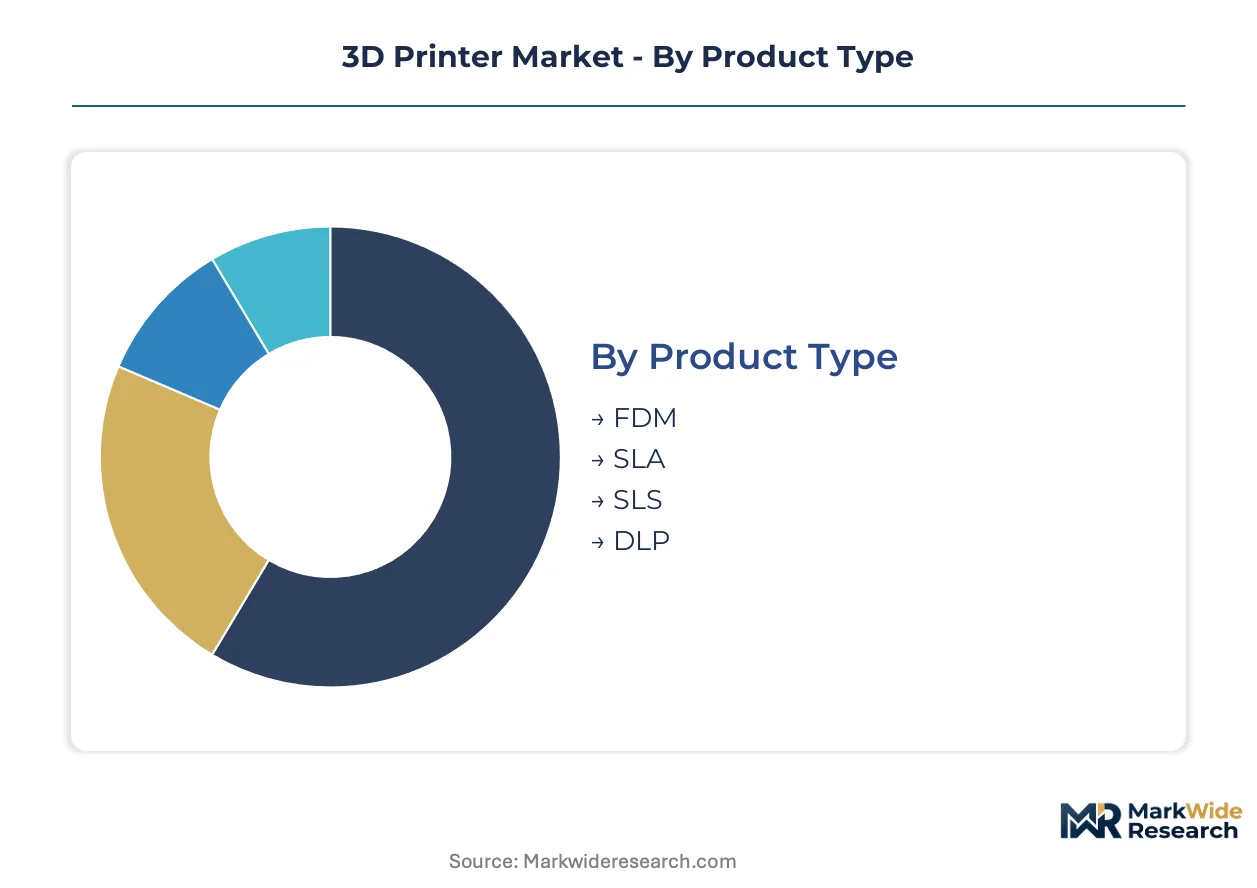
Segmentation in the 3D printer market reveals divergent profit pools between desktop polymer systems and industrial metal platforms. Technology selection directly determines regulatory pathway complexity and customer switching costs across end-use verticals.
Product Type:
FDM systems dominate domestic education and consumer channels, while SLA and SLS platforms concentrate in export-led contract manufacturing hubs serving medical and aerospace clients.
- FDM:Fused deposition modeling extrudes thermoplastic filaments through heated nozzles, building parts layer-by-layer with resolutions typically between 100-400 microns. Demand concentrates in German technical universities and US K-12 STEM programs where capital budgets cap hardware spending. Material cost sensitivity limits margin expansion despite high unit volumes.
- SLA:Stereolithography cures liquid photopolymer resins with ultraviolet lasers, achieving 25-50 micron precision for dental aligners and jewelry master patterns. Export demand from Chinese dental labs and Italian jewelry manufacturers in Valenza drives system shipments. Post-cure washing and resin handling elevate operational complexity beyond FDM workflows.
- SLS:Selective laser sinters nylon and TPU powders without support structures, enabling complex geometries for functional prototypes and end-use brackets. Aerospace interior component manufacturers in Toulouse and Hamburg specify SLS for cabin ducting and air vent housings.
- DLP:Digital light projection flashes entire layers simultaneously through micromirror arrays, accelerating print speeds for orthodontic models and investment casting patterns. Taiwanese foundry service bureaus deploy DLP for rapid jewelry and turbine blade mold production.
FDM holds the largest share; momentum sits with SLA as dental clear aligner volumes climb fastest.
End User:
Cost tier stratification separates capital-intensive aerospace qualification programs from budget-constrained education procurement cycles.
- Education:Universities and technical colleges deploy desktop FDM systems for mechanical engineering curricula and maker space facilities. German Fraunhofer institutes and Singapore polytechnics emphasize hands-on additive manufacturing training. Budget approval cycles align with academic fiscal years, creating seasonal demand concentration.
- Aerospace:Tier-1 manufacturers including Boeing, Airbus, and Safran qualify selective laser melting platforms for flight-critical titanium and nickel superalloy components. Long certification timelines with FAA and EASA gate revenue recognition until process validation completes. Service contracts extend ten to fifteen years post-initial system sale.
- Automotive:BMW, Ford, and Hyundai operate polymer printing centers for jigs, fixtures, and prototype interior trim. Tooling applications dominate over direct part production due to lower qualification burdens. China's MIIT incentives redirect some investment toward localized metal powder bed systems for electric vehicle thermal management.
- Healthcare:Hospital systems and contract manufacturers produce patient-specific cranial plates, spinal cages, and surgical guides. FDA 510(k) and EU MDR dual approvals differentiate qualified suppliers from generalist job shops. Mayo Clinic and Charité Berlin negotiate direct digital inventory contracts bypassing traditional distributors.
Aerospace commands premium pricing; healthcare shows steepest expansion trajectory as orthopedic personalization demand hardens.
Technology:
Application maturity separates established polymer workflows from emerging metal and ceramic qualification pipelines.
- Metal:Powder bed fusion and directed energy deposition systems process titanium, aluminum, and nickel alloys for structural aerospace and orthopedic implants. EOS GmbH and SLM Solutions dominate selective laser melting platform supply. Titanium powder cost volatility from Russian and Kazakh sponge concentration constrains margin stability.
- Plastic:ABS, PLA, and PETG filaments serve prototyping and non-structural end-use parts across consumer and industrial segments. Material recyclability and low toxicity support education and office environments. Price competition from Chinese filament manufacturers compresses hardware margins.
- Polymer:Engineering-grade nylons, PEEK, and ULTEM withstand elevated temperatures and chemical exposure for automotive underhood and medical sterilization applications. Stratasys holds extensive material patents and healthcare certifications. SLS and high-temperature FDM platforms process these feedstocks.
- Ceramic:Alumina, zirconia, and silicon carbide printing enables dental crowns, biomedical implants, and high-temperature industrial components. Binder jetting and photopolymer-derived ceramic processes remain pre-commercial for most industrial volumes. Japanese and German research institutes lead process development.
Polymer platforms retain volume leadership; metal technology gains share fastest as flight certification pipelines mature.
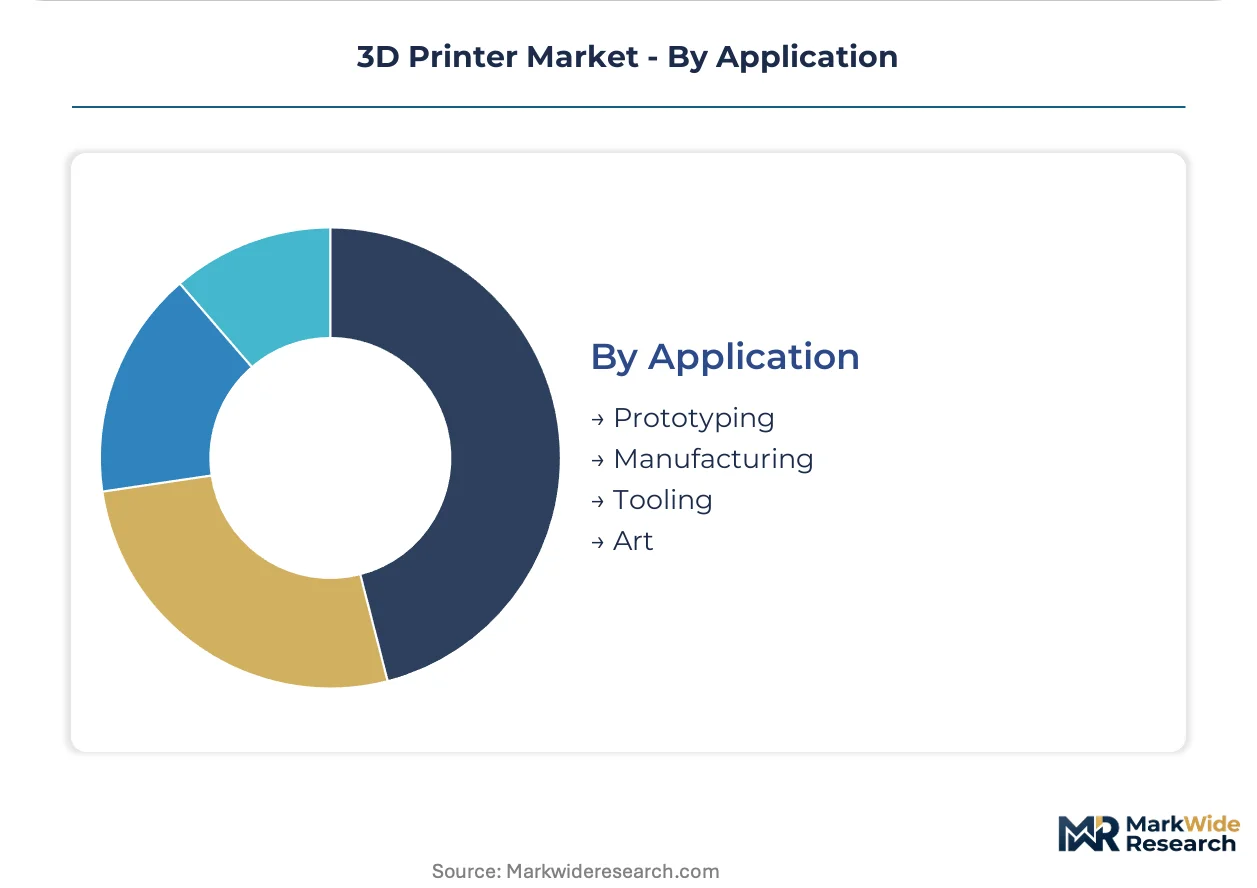
Application:
Customer type differentiation separates transactional prototyping sales from recurring manufacturing and tooling revenue streams.
- Prototyping:Design validation and form-fit-function testing consume the majority of desktop and mid-range system utilization. Industrial design firms in Milan and consumer electronics OEMs in Shenzhen iterate enclosure geometries before tooling commitment. Speed and geometric freedom outweigh material properties for this use case.
- Manufacturing:Direct digital production of end-use parts requires process validation, material traceability, and statistical quality control. Aerospace fuel nozzles and orthopedic implants exemplify qualified manufacturing applications. FDA and EASA oversight elevates compliance costs beyond prototyping workflows.
- Tooling:Jigs, fixtures, and mold inserts reduce lead times from weeks to days for automotive and industrial equipment production. Ford's Advanced Manufacturing Center produces assembly line tools at its Redford facility. Material durability under cyclic loading determines economic viability versus machined aluminum alternatives.
- Art:Sculptural and architectural applications exploit geometric complexity unavailable through subtractive methods. Dutch design studios and Chinese contemporary artists commission large-format polymer and metal installations. Aesthetic surface finish requirements drive post-processing investment beyond functional parts.
Prototyping generates highest unit volumes; manufacturing applications expand most quickly as qualification standards harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace manufacturers deploy metal powder bed systems for flight-certified turbine components, while Chinese automotive toolrooms favor polymer platforms for rapid jig production, revealing a technology-mix split between precision-critical and volume-flexible applications.
United States
Mayo Clinic and Charité Berlin negotiate direct digital inventory contracts for patient-specific implants, bypassing traditional distributors. FDA 510(k) pathway expansions accelerate orthopedic device clearances. Houston and Seattle aerospace clusters qualify selective laser melting platforms for fuel nozzles and brackets.
Germany
Fraunhofer institutes train additive manufacturing engineers on desktop FDM systems for technical curricula. ECHA REACH restrictions on nickel powder force post-processing relocations to Switzerland and Turkey. EOS GmbH anchors industrial metal printing supply from Krailling near Munich.
China
MIIT dual carbon incentives redirect automotive tooling investment toward localized metal powder bed systems for electric vehicle thermal management. Zhengzhou and Xi'an drone manufacturers specify continuous fiber-reinforced thermoplastic printing for unmanned aerial vehicle airframes.
Japan
METI-funded research institutes advance binder jetting processes for alumina and zirconia dental crowns. Toyota and Honda operate polymer printing centers for assembly line jigs and prototype interior trim. Nagoya aerospace suppliers pursue JIS certification for titanium implant workflows.
India
PLI scheme incentives for medical devices attract contract manufacturers seeking FDA-inspected facilities outside China. CDSCO alignment with international quality benchmarks tightens implant production standards. Gujarat and Karnataka host emerging dental lab clusters serving export markets.
3D Printer Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with polymer platform scale and metal system qualification timelines dividing competitive positions. Tier-1 manufacturers consolidate supply agreements around selective laser melting platforms, while desktop FDM vendors compete on filament cost and education channel access. Three archetypes dominate: integrated polymer-metal portfolios, pure-play metal powder bed specialists, and distributed manufacturing networks. M&A activity concentrates on healthcare certification assets and software workflow integration.
Within the integrated portfolio tier, Stratasys and 3D Systems occupy positions spanning polymer expertise and healthcare certifications. EOS GmbH exemplifies the metal powder bed specialist archetype with selective laser melting platform dominance. HP Development Company anchors the industrial-scale polymer segment with multi-jet fusion architectures.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| HP Development Company |
| EOS GmbH |
| Materialise |
| Protolabs |
| Bright Laser |
| Farsoon |
| Xometry |
| Others |
Cost & Logistics Intelligence
Titanium sponge substitution for recycled powder feedstock is redrawing procurement geography toward Kazakh and Japanese suppliers while compressing metal printing margins through volatile input pricing. Aerospace contractors now dual-source virgin and reprocessed titanium to hedge against Russian supply disruption, forcing tiered contract structures that separate flight-certified from industrial-grade pricing tiers.
Pricing Analysis
Long-term offtake agreements dominate aerospace metal printing, with ten-to-fifteen-year service contracts locking in selective laser melting platform pricing alongside powder supply commitments. Price differentiation rests on dual FDA 510(k) and EU MDR certification status and installed base scale, with qualified medical device vendors commanding substantial premiums over uncertified job shops. Cost compression in desktop FDM segments intensifies as Chinese filament manufacturers flood education channels, making German technical universities and US K-12 programs the most price-sensitive buyers while hospital systems show relative inelasticity for patient-specific implant workflows.
Supply Chain Analysis
Just-in-time powder delivery dominates aerospace and medical implant production, though titanium sponge stockpiling has resurfaced as a strategic preference among tier-1 manufacturers facing Kazakh and Russian supply concentration. The supply chain draws from China for rare-earth-doped fiber lasers, Germany for precision optics, and the United States for software-defined process control systems. Single-source vulnerability in Russian titanium sponge generates tariff exposure and price volatility that ripples through turbine bracket and orthopedic implant production. Distribution runs through authorized service partners for industrial metal systems and direct e-commerce for desktop polymer hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in additive manufacturing are approaching an inflection where interoperability between design software, process control systems, and post-processing equipment determines ecosystem lock-in. The shift toward hospital-integrated digital inventory models for patient-specific implants exemplifies this interoperability premium.
For Market Incumbents: Compound defensive moats through simultaneous FDA 510(k) and EU MDR certification maintenance for cranial and spinal implant portfolios, while securing captive titanium powder supply through backward integration into sponge processing or long-term offtake with Kazakh suppliers. Process engineer scarcity threatens capacity expansion at contract manufacturers; anchor talent through university pipeline partnerships with Fraunhofer institutes and Singapore polytechnics. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for patient-matched orthopedic devices open immediate white-space in hospital direct-procurement contracts bypassing traditional distributors. India's PLI scheme for medical devices offers the most penetrable geography for FDA-inspected production facilities outside China. Target copper and aluminum alloy printing for EV thermal management applications as the go-to-market angle, leveraging lower qualification burdens than flight-critical aerospace. For Investors and Strategic Acquirers: The market sits at a qualification-maturity phase that favors metal powder bed specialists with established aerospace certification pipelines over polymer platform generalists. Long-term viability across the projection horizon favors targets holding simultaneous medical device approvals and flight-critical process validation. Watch titanium powder price volatility as the inflection signal; sustained elevation above historical bands accelerates consolidation toward vertically integrated powder-to-part producers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous FDA 510(k) and EU MDR approvals unlock hospital direct-procurement contracts at Mayo Clinic and Charité Berlin. |
| Powder Supply Backward Integration | Captive titanium sponge sourcing from Kazakhstan hedges against Russian supply disruption and price volatility. |
| Hospital Digital Inventory Partnership | Long-term service agreements with Singapore General Hospital replace physical implant warehousing with on-demand production. |
| Multi-Laser Platform Deployment | EOS GmbH and SLM Solutions architectures compress aerospace qualification timelines while elevating throughput. |
| Continuous Fiber Thermoplastic Expansion | Automated fiber placement heads on gantry systems collapse UAV airframe tooling lead times from sixteen weeks to seventy-two hours. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with additive manufacturing engineering directors, hospital procurement committee members, aerospace Tier-1 supplier quality managers, and contract manufacturer operations heads; alongside secondary validation through FDA 510(k) clearance databases, EASA certification registries, and MIIT policy filings. Bottom-up triangulation across system shipment data, powder consumption metrics, and service contract values reconciled against top-down market sizing from industrial equipment trade flows and medical device import statistics.
Across the analysis window, the forecasting framework modeled volume and value trajectories by technology type, end-use vertical, material class, and geographic regulatory cluster. CAGRs derived from segment-level growth rate reconciliation against macro manufacturing investment cycles and medical device approval velocity. Industry-specific inputs incorporated flight-certification pipeline duration for aerospace components and orthopedic implant personalization demand curves from hospital procurement databases.
Decision-makers should treat outputs as directional under assumptions of sustained titanium powder supply from non-Russian sources and stable FDA 510(k) clearance timelines for patient-matched devices; material deviation would warrant model refresh. Revision becomes warranted when REACH nickel powder restrictions trigger additional European post-processing relocations or when Chinese dual carbon incentives redirect automotive metal printing investment volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Global 4D Printing in Healthcare Market