
 GCC Digital Printing Market | 2026-2036
GCC Digital Printing Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Digital Printing Market Insights
The gap between premium UV-cured packaging proofs and commodity toner-based office documents is realigning equipment investment across Gulf print houses. HP Inc. leverages its PageWide inkjet platforms to anchor high-volume corrugated contracts with Saudi food exporters. Canon Inc. competes through imagePRESS color systems that dominate commercial photobook production in Dubai and Abu Dhabi. Seiko Epson Corporation differentiates via PrecisionCore microTFP heads that sustain textile sublimation growth in Kuwait's garment hubs.
GCC digital printing encompasses electrophotographic, inkjet, and thermal transfer systems that deposit pigment or dye directly onto substrates without fixed image carriers, typically achieving resolutions between 600 and 2400 dpi for commercial and industrial applications. Inkjet printers lead equipment shipments as printheads accommodate water-based, solvent, and UV-curable inks for porous and non-porous media alike. UV printing technology commands premium pricing among packaging converters because instant polymerization permits direct decoration of polyethylene terephthalate and metallized films without primers. Digital flexography occupies a transitional niche where hybrid presses merge analog sleeve economies with digital job-change flexibility for mid-run label orders.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for printed food-contact materials shape ink formulation requirements across the Kingdom. UAE's Emirates Authority for Standardization and Metrology (ESMA) enforces ECAS certification for electrical printing equipment sold in Dubai and northern emirates. The Gulf Cooperation Council standardization body GSO maintains mutual recognition protocols that ease cross-border deployment of digital press fleets between Bahrain, Oman, Qatar, and Saudi Arabia. Stakeholders must monitor how SASO's expanding mandatory product listing affects spare-part sourcing timelines for imported printheads and curing lamps.
Market Dynamics
Packaging converters across Saudi Arabia and the UAE are restructuring capital allocation around shorter-run FMCG contracts, compressing job-change times from hours to minutes and displacing analog plate workflows.
Growth Catalysts
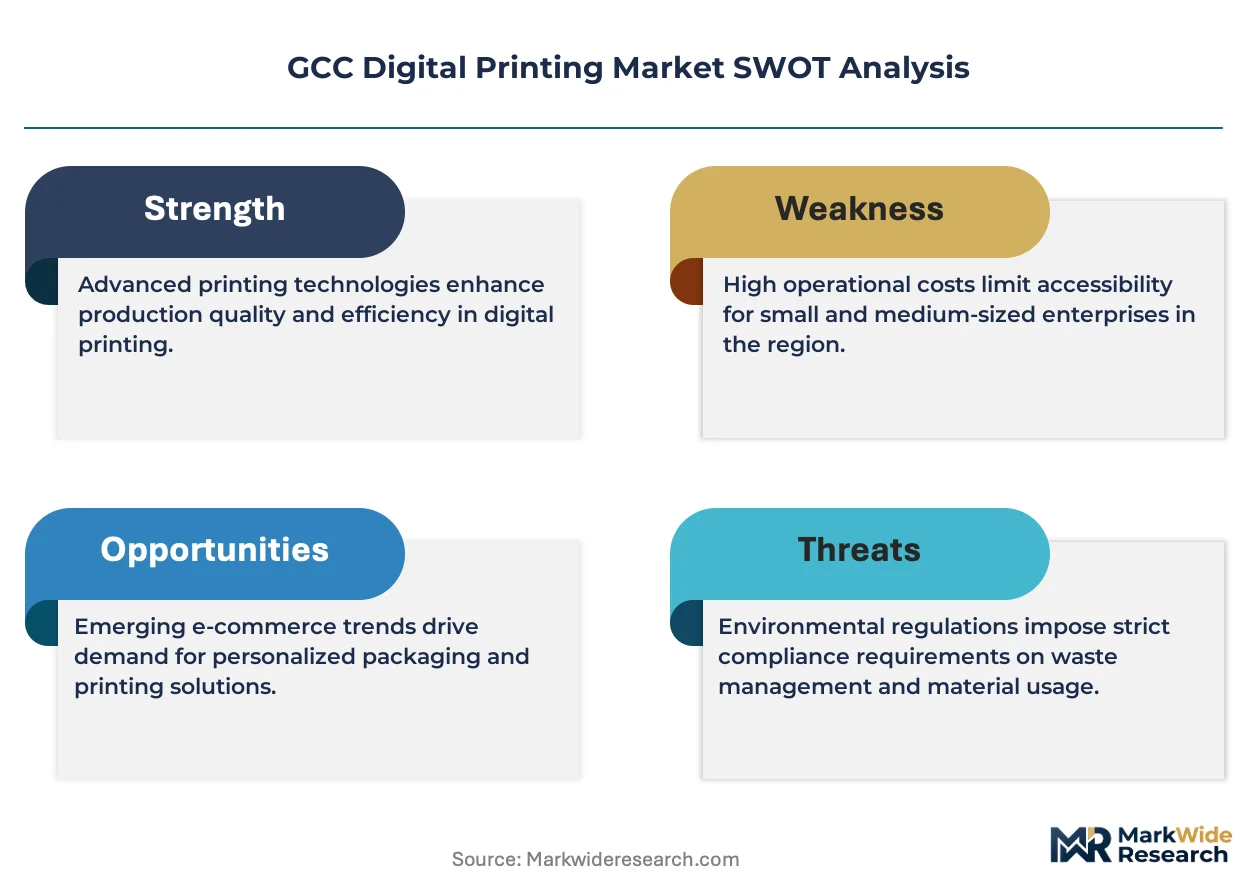
- SASO Food-Contact Mandates:Saudi technical regulations for printed packaging materials redirect procurement toward domestic digital service providers capable of rapid compliance documentation.
- Jebel Ali Free-Zone Incentives:Dubai's industrial corridor attracts inkjet and UV-curing equipment distributors through zero-duty import structures and consolidated logistics infrastructure.
- Textile Sublimation Demand:Kuwait's garment manufacturing hubs sustain investment in piezoelectric printhead arrays for polyester sportswear and regional fashion labels.
Market Restraints
- Import Dependency for Printheads:GCC digital press fleets rely on Japanese and German precision component suppliers, exposing operators to extended spare-part lead times during supply disruptions.
- UV Ink Cost Premium:Photoinitiator and oligomer formulations for instant-curing packaging applications carry 3-4x unit economics versus conventional solvent systems.
- Skilled Technician Scarcity:Regional vocational pipelines produce insufficient color management specialists and RIP software operators for installed base expansion.
Strategic Opportunities
- Oman Underpenetration:Muscat's commercial print sector retains analog dominance, creating first-mover positioning for digital sheetfed entrants targeting government document tenders.
- Hybrid Press Convergence:Digital-analog label systems merge sleeve economies with variable-data flexibility, capturing mid-run pharmaceutical and nutraceutical orders.
- Bahrain FinTech Documentation:Central bank digital transformation mandates accelerate demand for security-printed certificates and personalized financial instruments.
Industry Challenges
- ESMA Certification Timelines:UAE electrical safety approvals for imported curing lamp assemblies extend equipment commissioning cycles by 8-14 weeks.
- Legacy MIS Integration:Print shop management information systems require custom API development to ingest real-time ink consumption and substrate tracking from modern presses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Digital Printing Market |
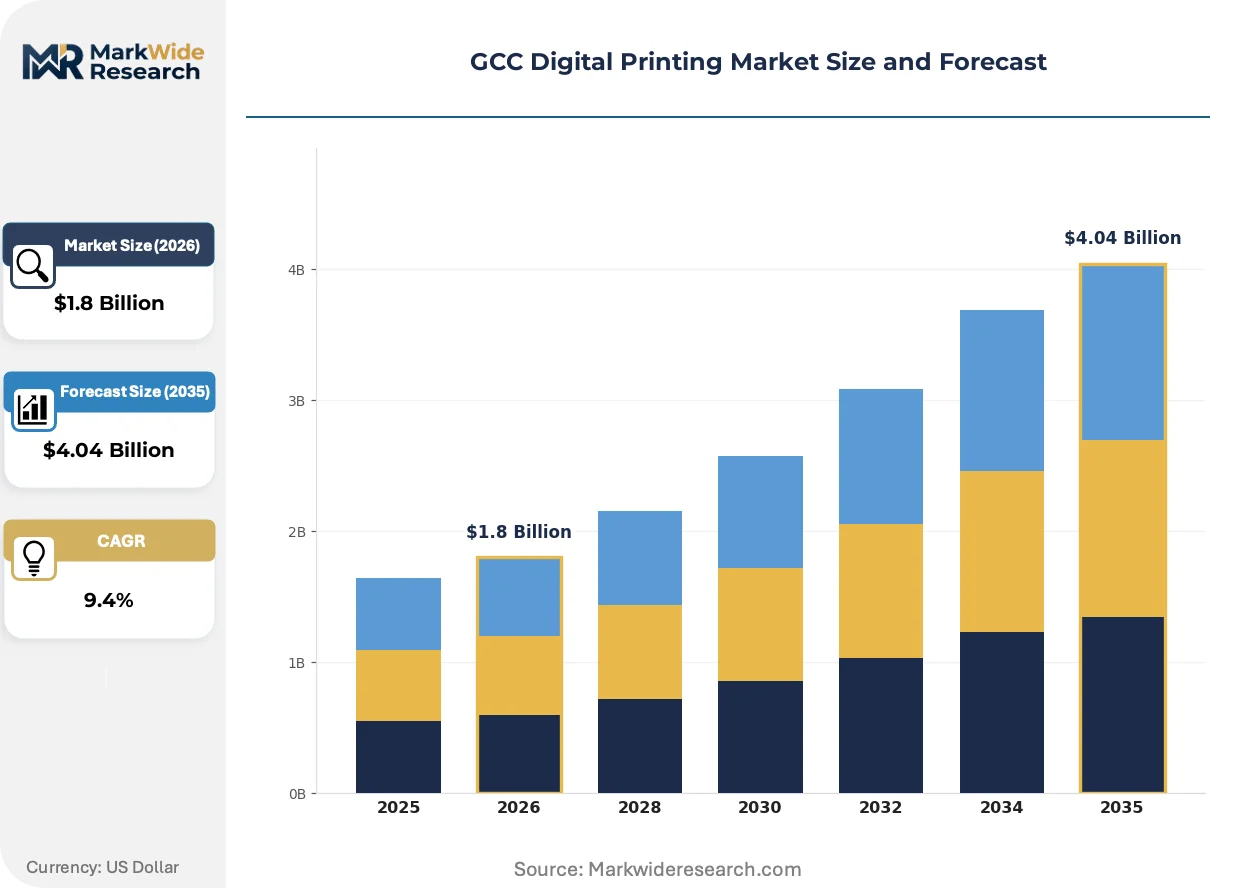
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, 3D Printers, Thermal Printers End User: Publishing, Packaging, Textile, Commercial Printing Technology: UV Printing, Eco-Solvent Printing, Dye-Sublimation, Digital Flexography Application: Advertising, Labeling, Decoration, Prototyping |
| Companies Covered | Konica Minolta Inc., Mondi PLC, HP Inc., Huhtamaki Oyj, Amcor PLC, Canon Inc., Seiko Epson Corporation, Xeikon NV, Xerox Holdings Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Digital Printing Market Trends and Innovations
Single-pass inkjet architectures are compressing the cost-per-thousand threshold against offset lithography, while regulatory pressure on food-contact materials accelerates chemistry reformulation across Gulf formulation labs.
Water-based pigment inkjet systems engineered for uncoated corrugated board are electrifying the Saudi food export packaging segment. Date processors and dairy cooperatives adopt these presses to eliminate solvent retention risks while maintaining 150-meter-per-minute throughputs. The technology is electrifying competitive positioning among Riyadh-based converters previously locked out of European retail supply chains.
SASO's expanding mandatory product listing for printed food-contact materials forces ink manufacturers to submit migration test documentation for every photoinitiator batch. Formulation houses in Dammam and Jeddah now maintain captive analytical laboratories to compress certification cycles. Domestic compounders gain preference over imported alternatives during Saudi Vision 2030 procurement reviews.
Brand owners in Dubai's FMCG cluster now specify lot-level traceability codes on secondary packaging, compressing procurement evaluation criteria toward digital-native suppliers. Traditional analog houses lose tender eligibility for multinational beverage and personal care contracts. The shift concentrates contract awards among Jebel Ali corridor operators with integrated variable-data workflows.
GCC Digital Printing Market Segmentation
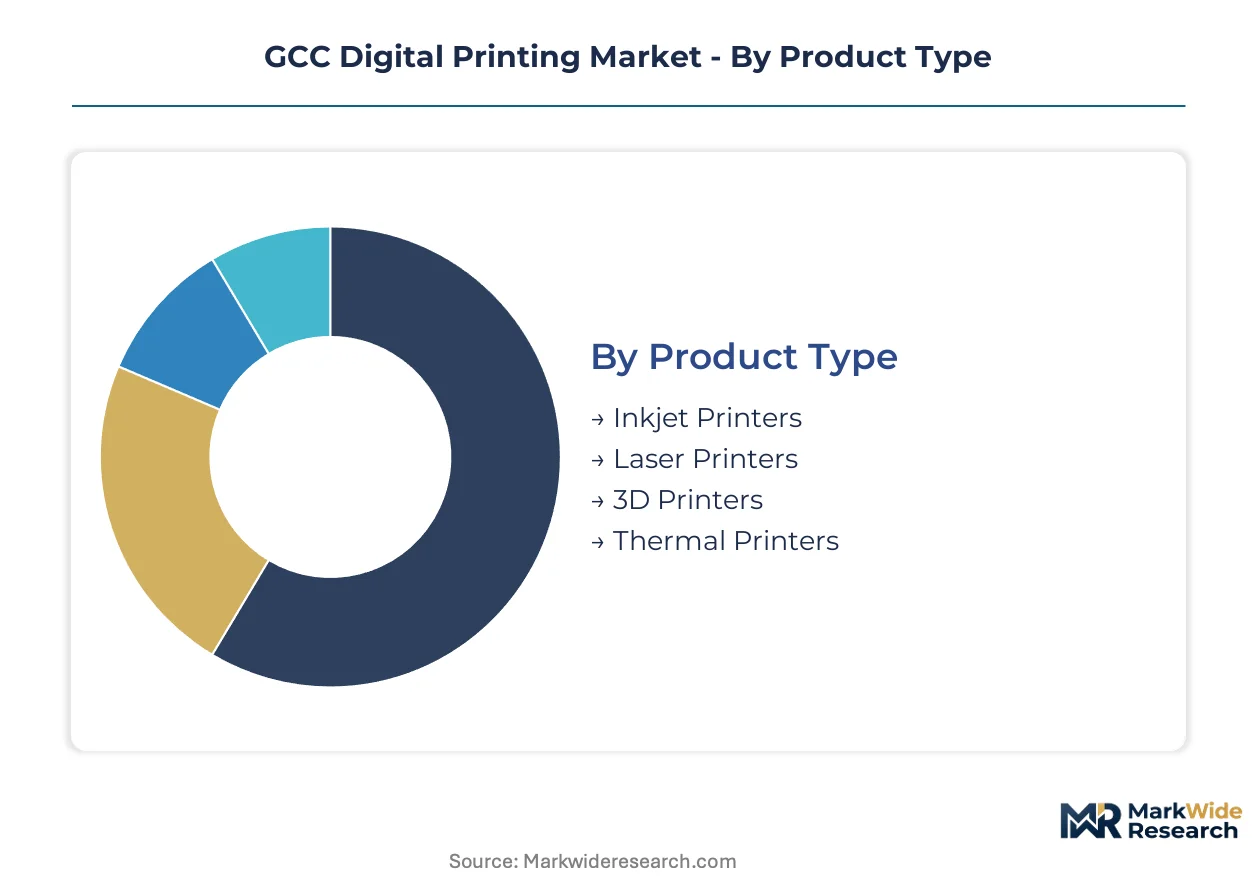
Equipment deployment across the GCC concentrates where substrate versatility meets regulatory compliance. Print houses segment procurement by technology maturity, end-use certification requirements, and duty-cycle economics.
Product Type:
Supply concentration tilts toward piezoelectric inkjet architectures that accommodate water-based, solvent, and UV-curable chemistries within single press configurations.
- Inkjet Printers:Piezoelectric drop-on-demand systems deposit pigment or dye solutions onto porous and non-porous media at resolutions between 600 and 2400 dpi. Packaging converters in Dubai's Jebel Ali corridor deploy these for corrugated board decoration serving Saudi food exporters. The technology absorbs the bulk of capital allocation from FMCG contract winners.
- Laser Printers:Electrophotographic engines fuse toner onto paper and synthetic substrates through laser-induced charge patterns. Commercial print shops in Abu Dhabi and Riyadh favor these for high-volume photobook and government document production where color consistency outweighs substrate flexibility. These systems dominate installed base in legacy commercial operations.
- 3D Printers:Additive manufacturing systems build resin or filament objects layer-by-layer for prototyping and short-run tooling applications.
- Thermal Printers:Direct thermal and thermal transfer systems generate barcodes, receipts, and shipping labels for logistics and retail inventory management.
Inkjet printers absorb the bulk of installed capacity; 3D printers are expanding most quickly among industrial prototyping centers.
End User:
Application economics separate capital-intensive packaging workflows from variable-data commercial operations.
- Packaging:Corrugated, flexible film, and label converters serve shorter-run FMCG orders with instant job-change capabilities. Saudi date processors and dairy cooperatives adopt water-based pigment systems to meet SASO food-contact mandates while maintaining European retail supply chain eligibility. This segment commands premium equipment pricing.
- Publishing:Newspaper, magazine, and book producers leverage digital presses for print-on-demand and backlist fulfillment. Commercial photobook production concentrates in Dubai and Abu Dhabi studios serving tourism and personal memory markets. Demand fluctuates with paper cost volatility.
- Textile:Polyester sportswear and regional fashion labels in Kuwait's garment hubs sustain investment in dye-sublimation and direct-to-garment systems.
- Commercial Printing:General print shops produce marketing collateral, business stationery, and variable-data direct mail for corporate clients.
Packaging absorbs the bulk of installed capacity; textile is gaining share fastest as Kuwait garment hubs expand sublimation capacity.
Technology:
Margin structures diverge between instant-curing premium systems and chemistry-flexible mid-range alternatives.
- UV Printing:Photoinitiator-driven polymerization enables direct decoration of polyethylene terephthalate and metallized films without primers. The 3-4x ink cost premium over solvent systems is offset by eliminated drying time and substrate pre-treatment. Packaging converters command higher contract pricing for UV-cured output.
- Eco-Solvent Printing:Mild-solvent ink formulations penetrate coated and uncoated vinyl for outdoor signage and vehicle wraps. Dubai's advertising sector favors these for billboard and building facade applications where durability exceeds indoor display requirements. Lower capital barriers support fleet expansion among mid-size operators.
- Dye-Sublimation:Heat-activated dye transfer bonds pigment into polyester fibers for soft signage, sportswear, and home textiles.
- Digital Flexography:Hybrid presses merge analog sleeve economies with digital job-change flexibility for mid-run pharmaceutical and nutraceutical label orders.
UV printing absorbs the bulk of installed capacity; digital flexography is climbing the fastest as label converters capture mid-run pharmaceutical contracts.
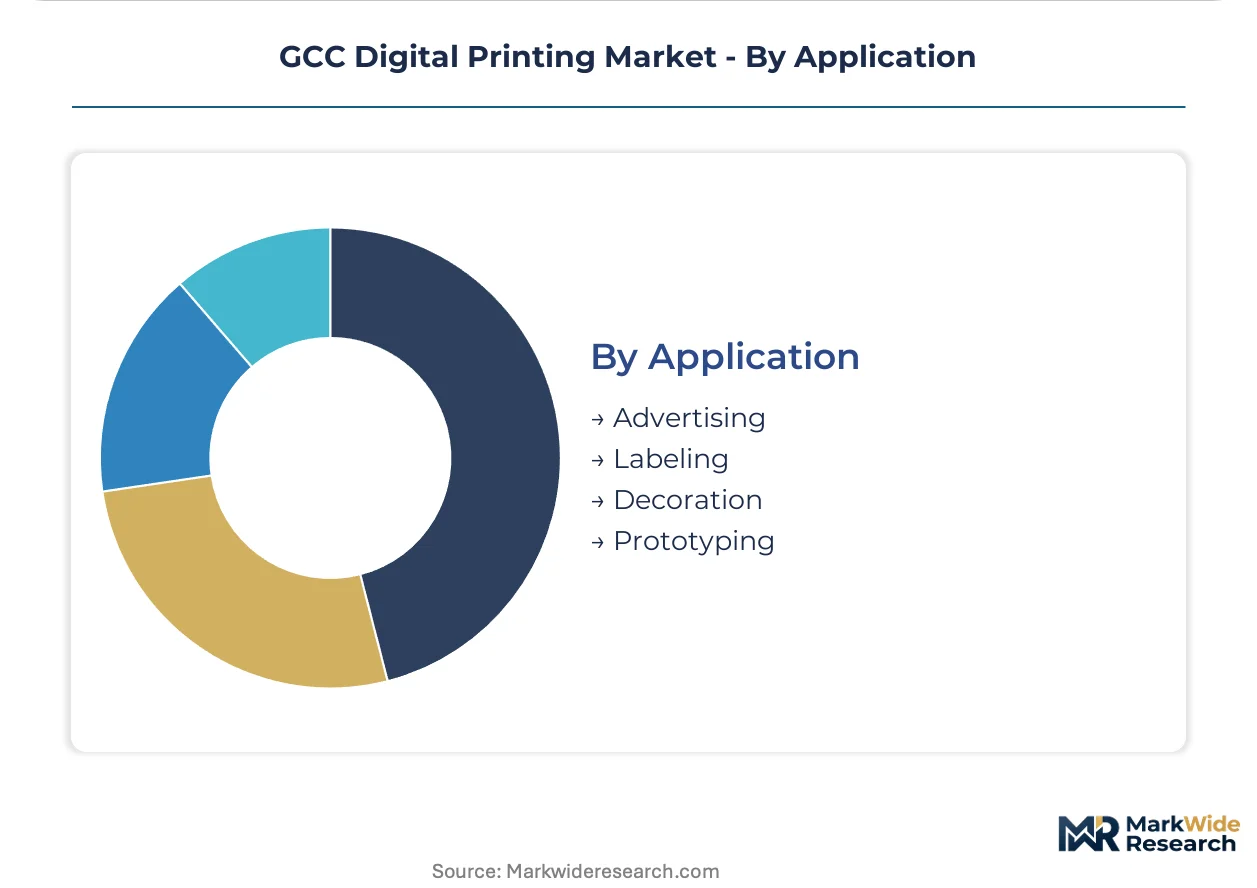
Application:
Customer procurement patterns concentrate volume among brand owners requiring lot-level traceability and variable-data integration.
- Labeling:Secondary and tertiary packaging carries serialized codes for supply chain tracking and anti-counterfeiting. Dubai FMCG clusters now specify digital-native suppliers for multinational beverage and personal care tenders, disqualifying analog houses lacking integrated variable-data workflows. Regulatory compliance documentation accelerates contract concentration.
- Advertising:Point-of-sale displays, outdoor signage, and event graphics demand high-impact color reproduction on diverse substrates. Retail and hospitality sectors in Abu Dhabi and Doha drive seasonal campaign volumes. Short turnaround requirements favor digital over analog screen printing.
- Decoration:Interior design, architectural finishes, and customized consumer products utilize direct-to-object printing.
- Prototyping:Product development cycles leverage 3D printing and short-run digital packaging mockups for market testing.
Labeling absorbs the bulk of installed capacity; prototyping is expanding most quickly among industrial design studios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali industrial corridor concentrates GCC digital printing demand through zero-duty import structures and consolidated logistics infrastructure serving Saudi food exporters and UAE FMCG clusters.
Saudi Arabia
Packaging converters in Riyadh and Dammam expand water-based pigment inkjet fleets to serve date processors and dairy cooperatives. SASO technical regulations for printed food-contact materials redirect procurement toward domestic providers capable of rapid compliance documentation. The Eastern Province houses captive analytical laboratories that compress certification cycles for ink formulation batches.
United Arab Emirates
Commercial photobook studios in Dubai and Abu Dhabi sustain demand for electrophotographic color systems serving tourism and personal memory markets. ESMA enforces ECAS certification for electrical printing equipment, extending curing lamp assembly commissioning cycles. Jebel Ali free-zone incentives attract inkjet and UV-curing equipment distributors from across the Gulf.
Kuwait
Garment manufacturing hubs sustain investment in piezoelectric printhead arrays for polyester sportswear and regional fashion labels. Dye-sublimation systems dominate textile applications where heat-activated dye transfer bonds pigment into synthetic fibers. The country's vocational pipelines produce color management specialists for installed base expansion.
Qatar
Retail and hospitality sectors in Doha drive seasonal campaign volumes for point-of-sale displays and event graphics. Short turnaround requirements favor digital over analog screen printing for advertising applications. The market absorbs UV-curing systems for high-impact color reproduction on diverse substrates.
Oman
Muscat's commercial print sector retains analog dominance, creating first-mover positioning for digital sheetfed entrants. Government document tenders present procurement opportunities for operators with integrated variable-data workflows. The underpenetrated market offers expansion potential for mid-run pharmaceutical and nutraceutical label converters.
GCC Digital Printing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ink chemistry and curing technology tiers. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with captive printhead manufacturing, specialized imaging equipment pure-plays, and packaging material integrators extending into print services. Consolidation pressures favor M&A activity between equipment distributors and regional service networks, while capacity expansion concentrates in Jebel Ali corridor free zones.
Among diversified technology conglomerates, HP Inc. and Canon Inc. anchor the premium equipment tier through integrated hardware-ink-substrate ecosystems. Seiko Epson Corporation exemplifies the precision component specialist archetype with microTFP head architectures. Konica Minolta Inc. occupies a position bridging commercial imaging and industrial print applications. These three entities represent distinct competitive vectors: page-wide production scale, precision microfabrication, and hybrid commercial-industrial positioning.
| Leading Market Players |
|---|
| Konica Minolta Inc. |
| Mondi PLC |
| HP Inc. |
| Huhtamaki Oyj |
| Amcor PLC |
| Canon Inc. |
| Seiko Epson Corporation |
| Xeikon NV |
| Xerox Holdings Corporation |
| Others |
Pricing and Supply Chain Analysis
Photoinitiator spot prices on Asian chemical exchanges cascade through GCC ink formulation costs, compressing margins for UV-curing packaging converters while elevating water-based pigment alternatives into premium positioning.
Pricing Analysis
Throughput-guaranteed service contracts anchor equipment pricing for Jebel Ali corridor operators serving Saudi food exporters. Three-tier pricing structure across premium UV-cured, standard eco-solvent, and economy toner-based tiers separates packaging converters from commercial print shops. Pricing pressure stems from Japanese printhead import costs and extended ESMA certification timelines for curing lamp assemblies. Mid-size commercial printers exhibit highest price sensitivity, while FMCG brand owners absorb premium UV ink costs for compliance documentation.
Supply Chain Analysis
Precision piezoelectric printhead supply rests on Japanese and German microfabrication specialists, with secondary sourcing from South Korean component integrators. Photoinitiator chemistries draw from Chinese specialty chemical producers, while UV-curable oligomer formulations concentrate among European polymer houses. Single-source vulnerability for microTFP head architectures exposes GCC operators to spare-part lead time volatility during regional logistics disruptions. Distribution runs through Dubai free-zone consolidation hubs serving Saudi Arabia, UAE, and Kuwait print houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printhead manufacturing capacity constraints prop equipment pricing power, as Japanese and German suppliers maintain order backlogs that shield premium-tier vendors from price erosion.
For Market Incumbents: Lock in long-term printhead supply agreements with Japanese microfabrication houses to secure allocation priority during capacity crunches. Capture captive analytical laboratory capabilities in Dammam and Jeddah to compress SASO certification cycles and disqualify import-dependent competitors. Defend against emerging Chinese equipment entrants by embedding variable-data workflow expertise into service contracts. For New Entrants and Emerging Players: Launch via government document tender specialization in Muscat's underpenetrated commercial print sector, where analog dominance creates first-mover positioning for digital sheetfed entrants. Target mid-run pharmaceutical label contracts through hybrid press configurations that merge sleeve economies with lot-level traceability capabilities. Prioritize Bahrain's security-printed financial instrument segment accelerated by central bank digital transformation mandates. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional service networks with captive spare-part inventories in Dubai free zones, positioned to consolidate fragmented aftermarket support infrastructure. Long-term viability hinges on vertical integration into ink formulation capabilities that satisfy expanding SASO mandatory product listing requirements. Monitor ESMA electrical safety approval timeline compression as inflection signal for equipment commissioning cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | Dammam compounders gain preference over imports during Saudi Vision 2030 procurement reviews. |
| Hybrid Press Fleet Expansion | Digital-analog label systems capture mid-run pharmaceutical orders from sleeve-dependent competitors. |
| Free-Zone Distribution Hub Establishment | Jebel Ali zero-duty structures consolidate logistics serving Saudi food exporters and UAE FMCG clusters. |
| Captive Analytical Laboratory Investment | In-house migration testing compresses SASO certification cycles for food-contact ink batches. |
| Variable-Data Workflow Integration | Lot-level traceability capabilities qualify operators for multinational beverage and personal care tenders. |
Research Methodology
Trade publications, customs import records, and equipment distributor shipment data formed the secondary backbone, supplemented by primary interviews with packaging converter operations directors, printhead procurement managers, and SASO compliance officers. Triangulation across bottom-up press installation counts and top-down ink consumption estimates validated market sizing. Stakeholder conversations spanned Riyadh, Dubai, and Kuwait City industrial zones.
Historical trendline analysis of installed base expansion and substrate consumption patterns informed projection modeling across the analysis window. Segmentation dimensions included technology type, end-use application, ink chemistry class, and country-level regulatory cluster. CAGRs derived from equipment replacement cycles and FMCG contract velocity assumptions. Forecast inputs incorporated Saudi localization mandate intensity and Jebel Ali free-zone incentive durability.
Photoinitiator price volatility, ESMA certification timeline shifts, and Japanese printhead allocation disruptions are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement consistency and supply chain normalization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Global Microprinting Market
Printing Technology
Web to Print Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Managed Print Services Market
Printing Technology
ID Card Printers Market
Printing Technology
Card Printers Market
Printing Technology
North America Commercial Printing Market
Printing Technology
RFID Printer Market
Printing Technology
Book Printing Service Market
Printing Technology
Digital Paper System Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Variable Data Printing Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Large Character Printers Market
Printing Technology
Industrial Printer Market