
 Food 3D Printing Market | 2026-2036
Food 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Food 3D Printing Market Analysis
The EU Green Deal is hardening sustainability requirements across European food manufacturing, pushing commercial adopters toward precision deposition technologies that curb ingredient waste. BeeHex leverages its NASA-derived heritage to sustain defense and aerospace catering contracts where portion precision matters. byFlow anchors European market development through its open-platform paste extrusion systems deployed in restaurant test kitchens. Natural Machines differentiates via countertop accessibility, competing for residential and small commercial segments with multi-material cartridge architectures.
Food 3D printing employs layer-by-layer additive manufacturing to shape edible pastes, batters, and hydrogels through controlled extrusion or binder jetting, typically operating at temperatures between 4°C and 250°C depending on substrate viscosity and thermal stability requirements. The technology serves commercial purposes spanning customized nutrition geometry, automated artistic plating, and waste-minimized small-batch production. Chocolate and protein formulations within the Product Type dimension occupy divergent maturity stages, with chocolate deposition representing established revenue pools while protein extrusion for alternative meat structures captures accelerated R&D investment. Extrusion technology dominates installed capacity owing to lower capital thresholds, though Binder Jetting commands margin concentration in confectionery applications requiring granular sugar consolidation without thermal degradation.
EFSA novel food assessments and FDA GRAS determinations shape ingredient permissibility for printed formulations, while CE marking mandates govern electrical and thermal safety in commercial kitchen deployments. REACH compliance for food-contact materials constrains polymer and metallic component selection in extrusion hardware, elevating stainless steel and food-grade silicone specifications. Stakeholders must monitor evolving novel food classification timelines across jurisdictions, as regulatory lag between ingredient approval and printer deployment capability will determine which manufacturers secure first-mover positioning in personalized nutrition segments.
Market Dynamics
Precision deposition technology is compressing batch sizes in commercial food manufacturing, forcing capital equipment decisions toward modular extrusion systems that reconcile customization economics with throughput requirements.
Growth Catalysts
- EU Green Deal waste mandates:Industrial bakeries in Germany deploy extrusion systems to eliminate trim waste from custom chocolate geometries, converting sustainability compliance into operational savings.
- Deposition-based fabrication:High-end restaurants adopt layer-by-layer systems for automated artistic plating, reducing skilled labor dependency during peak service windows.
- Defense catering contracts:Aerospace and military foodservice operations require portion precision for extended-duration missions, sustaining demand for calibrated deposition hardware.
Market Restraints
- Cocoa butter price volatility:Chocolate formulation printers face margin compression when cocoa futures spike, limiting deployment in price-sensitive confectionery segments.
- Stainless steel supply concentration:REACH-compliant food-grade extrusion hardware depends on German and Italian metal suppliers, creating procurement bottlenecks during alloy shortages.
- Thermal stability ceilings:Protein hydrogel extrusion remains constrained by substrate denaturation thresholds below 85°C, restricting alternative meat texture replication.
Strategic Opportunities
- Residential countertop accessibility:Multi-material cartridge architectures target small commercial kitchens and affluent households in France and the Netherlands where space constraints favor compact systems.
- Novel food regulatory tailwind:EFSA accelerated assessment timelines for printed protein formulations create first-mover positioning for manufacturers with pre-submitted dossiers.
- AI-driven print path optimization:Machine learning convergence with extrusion control software enables real-time viscosity compensation, opening medical nutrition personalization segments.
Industry Challenges
- Food safety certification timelines:CE marking for thermal safety in commercial kitchen deployments requires 14-18 month validation cycles, delaying revenue recognition for new hardware platforms.
- Cross-functional talent scarcity:Equipment manufacturers compete for process engineers fluent in both rheology and additive manufacturing controls, inflating compensation benchmarks.
- Legacy kitchen integration:Deposition systems must interface with existing HACCP monitoring infrastructure, complicating retrofit installations in established foodservice operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food 3D Printing Market |
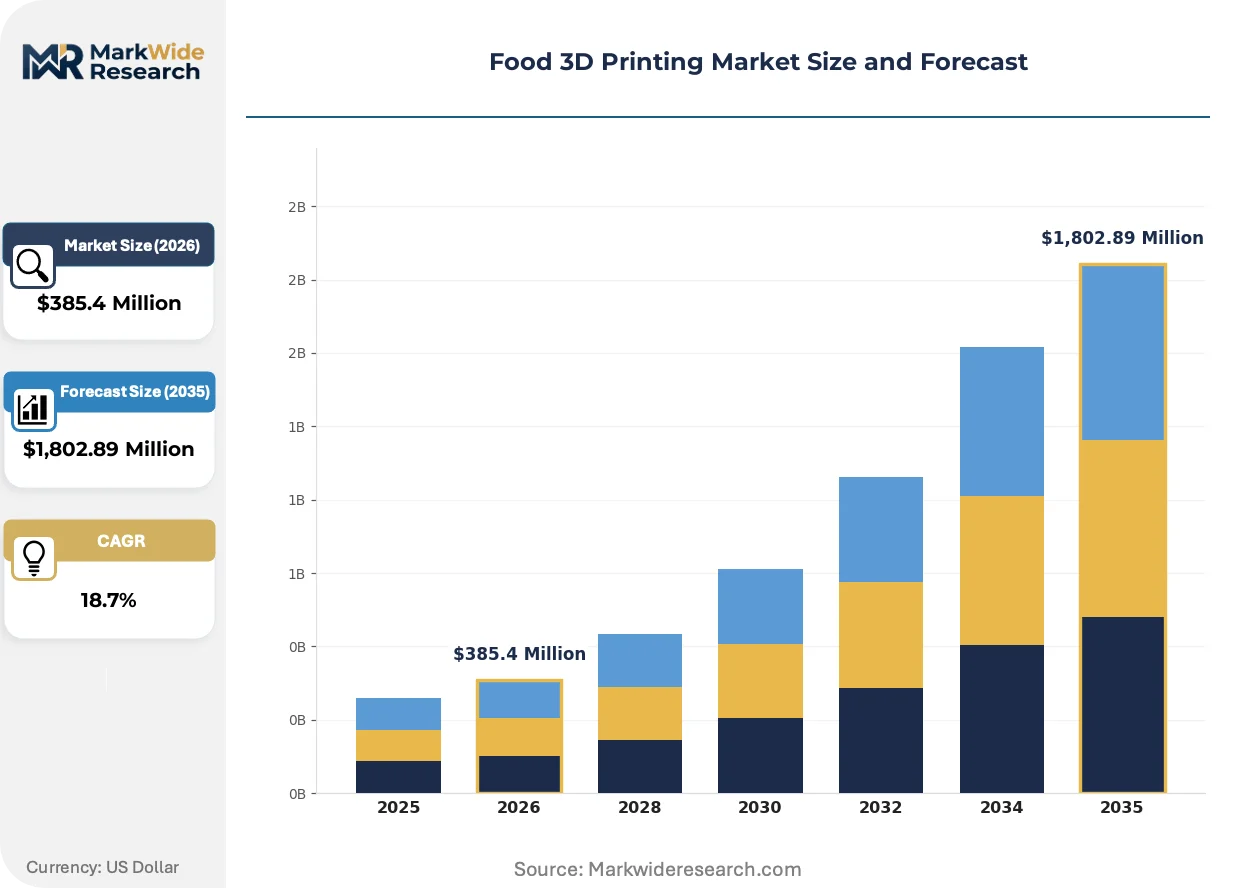
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Pasta, Sugar, Protein Technology: FDM, SLS, Binder Jetting, Extrusion End User: Restaurants, Bakeries, Catering Services, Food Manufacturers Application: Custom Desserts, Nutritional Foods, Artistic Plating, Meal Kits |
| Companies Covered | BeeHex, byFlow, Natural Machines, TNO, 3D Systems, Systems And Materials Research Corporation, Choc Edge, Revo Foods, Procusini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food 3D Printing Market Emerging Trajectories
Active reshaping in food 3D printing centers on the collision between precision nutrition requirements and regulatory acceleration of novel ingredient approvals, compressing development cycles for personalized edible formulations.
Multi-material paste extrusion is converging with real-time viscosity sensing to enable simultaneous deposition of incompatible substrates—hydrogels, tempered chocolate, and protein matrices—within single print jobs. High-end restaurant test kitchens in Spain and Belgium pilot these systems for composed dishes with textural contrast. The technology is converging with front-of-house presentation demands, collapsing the distinction between kitchen prep and plated artistry.
EFSA novel food assessments are hardening evidentiary requirements for printed protein structures, mandating comprehensive nutritional equivalence studies before market authorization. Industrial adopters in Germany and Italy front-load regulatory consulting costs to secure expedited review slots. Alternative meat startups reformulate extrusion recipes to preempt objections on allergenicity grounds, diverting R&D resources from sensory optimization toward dossier preparation.
Buyer concentration among institutional caterers and contract foodservice operators is consolidating procurement decisions toward approved vendor lists with pre-qualified equipment certifications. Small equipment manufacturers face exclusion from hospital and aged-care nutrition contracts unless they achieve ISO 22000 alignment. This certification-driven preference shift is most visible in Nordic countries where public procurement rules mandate documented food safety management systems for all kitchen technology acquisitions.
Food 3D Printing Market Segmentation
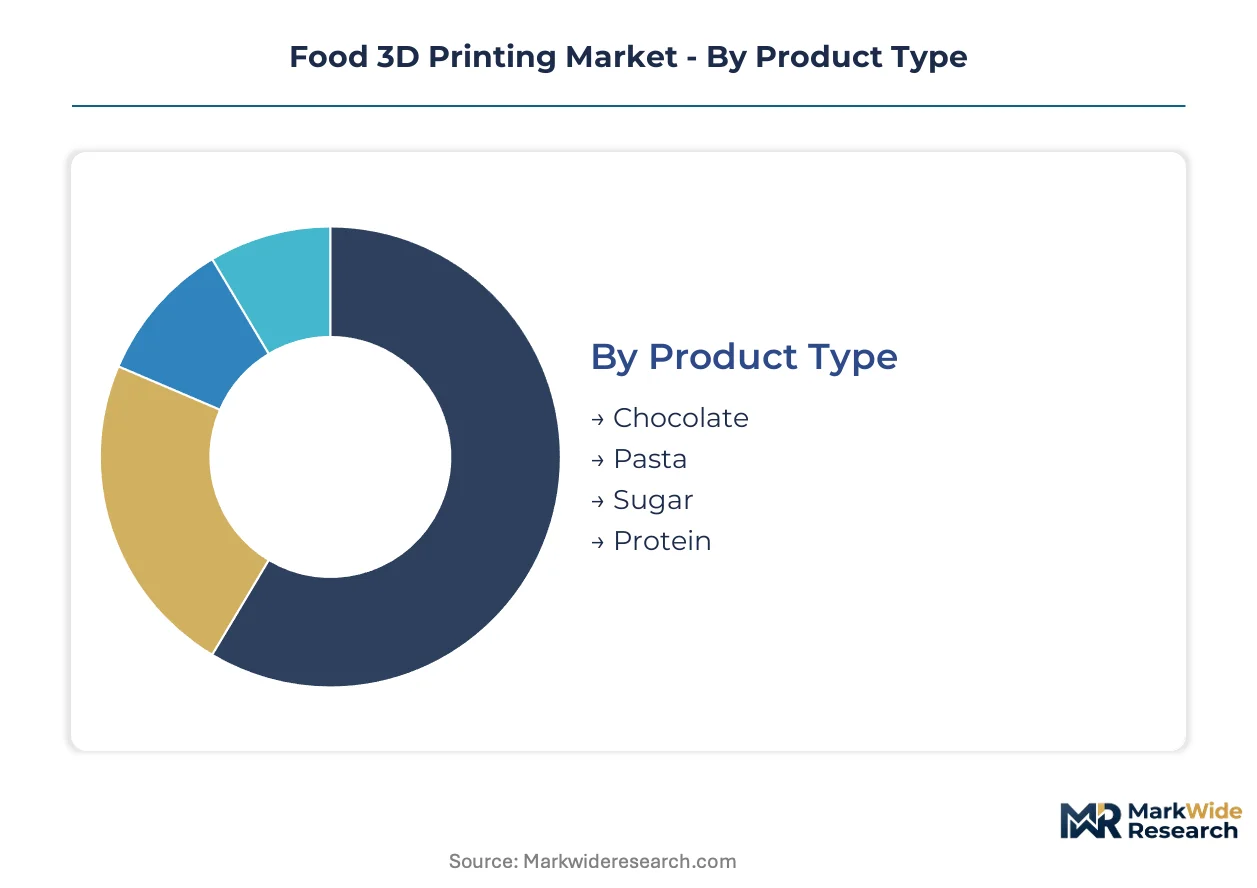
Food 3D printing segments diverge sharply in capital requirements, with industrial extrusion systems demanding stainless steel hardware and CE-certified thermal controls while countertop units target residential accessibility. Manufacturers configure platform architectures around substrate viscosity ranges and throughput economics, creating distinct competitive arenas across product categories.
Product Type:
Capital intensity escalates with thermal processing demands and regulatory compliance burdens, positioning protein formulations as the highest-investment segment due to EFSA novel food dossier requirements.
- Chocolate:Tempered cocoa butter deposition operates within established food safety frameworks, avoiding novel food classification. German industrial bakeries and Belgian confectionery houses concentrate demand for custom geometries that eliminate trim waste under EU Green Deal mandates.
- Protein:Alternative meat extrusion requires hydrogel matrix development below 85°C denaturation thresholds, with EFSA nutritional equivalence studies front-loading R&D expenditure. Dutch and Spanish startups dominate pilot installations as regulatory consulting costs filter out undercapitalized entrants.
- Pasta:Semolina and alternative flour extrusion leverages existing Italian processing expertise with moderate thermal requirements.
- Sugar:Granular substrate consolidation through binder jetting avoids thermal degradation but demands precise humidity control.
Chocolate absorbs the bulk of installed capacity; protein is expanding most quickly.
Technology:
Deposition method determines margin structure, with powder-bed systems commanding premium pricing in confectionery applications where thermal precision limits substrate damage.
- Extrusion:Paste-based layer deposition dominates commercial deployments due to lower capital thresholds and substrate flexibility. byFlow's open-platform systems anchor European restaurant adoption, with modular architectures allowing viscosity compensation across chocolate, dough, and protein matrices.
- Binder Jetting:Powder-bed binding with edible adhesives enables complex sugar geometries without thermal stress, concentrating in Belgian and French luxury confectionery where margin structures justify equipment premiums.
- FDM:Fused deposition modeling adapted for food-grade filaments serves niche educational and prototyping segments.
- SLS:Selective laser sintering remains pre-commercial for food applications due to thermal control challenges and regulatory uncertainty around laser-processed edibles.
Extrusion claims the deepest installed base; binder jetting captures the steepest expansion trajectory in premium confectionery.
End User:
Procurement authority concentrates in institutional foodservice operators with pre-qualified vendor lists, excluding uncertified equipment manufacturers from hospital and aged-care contracts.
- Restaurants:High-end establishments in Spain and Belgium deploy multi-material systems for front-of-house presentation, collapsing kitchen prep and plated artistry into continuous workflows. Real-time viscosity sensing enables textural contrast within composed dishes.
- Food Manufacturers:Industrial bakeries in Germany pilot extrusion lines for small-batch customization, converting sustainability compliance into operational savings through waste elimination.
- Bakeries:Artisan producers leverage compact systems for custom decoration and limited-run geometries.
- Catering Services:Contract operators prioritize portion precision for aerospace and defense contracts where NASA-derived calibration standards apply.
Food manufacturers deploy the heaviest equipment volumes; restaurants are gaining share fastest as front-of-house integration accelerates.
Application:
Use case maturity spans from established decorative functions to emerging medical nutrition segments, with regulatory timelines determining accessible market entry points.
- Custom Desserts:Chocolate and sugar geometry personalization represents the most penetrated application, with established CE marking pathways and HACCP integration protocols. French and Dutch retail channels concentrate demand for occasion-specific confections.
- Nutritional Foods:Medical nutrition personalization requires ISO 22000 alignment and AI-driven print path optimization for real-time dietary adjustment. Nordic public procurement rules mandate documented safety management systems, consolidating demand toward certified vendors.
- Artistic Plating:Automated composition reduces skilled labor dependency during peak service windows in fine dining.
- Meal Kits:Pre-portioned ingredient deposition targets convenience-oriented households with space-constrained kitchens.
Custom desserts generate the majority of current revenue; nutritional foods are climbing the fastest as regulatory acceleration compresses approval timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cologne anchors European food 3D printing deployment, where industrial bakeries pilot extrusion systems for custom chocolate geometries under EU Green Deal waste mandates.
Germany
Industrial bakeries in Cologne and Berlin deploy deposition systems to eliminate trim waste from custom confectionery, converting EU Green Deal compliance into operational savings. EFSA novel food assessments accelerate timelines for printed protein formulations. Bavarian confectionery manufacturers pilot binder jetting for complex sugar structures without thermal degradation.
Netherlands
Amsterdam and Rotterdam host restaurant test kitchens adopting multi-material paste extrusion for front-of-house presentation. REACH compliance for food-contact materials constrains polymer selection in extrusion hardware. Dutch startups concentrate in Eindhoven's food-tech corridor, developing hydrogel matrices for alternative meat structures below 85°C denaturation thresholds.
Spain
Barcelona and Madrid high-end establishments deploy real-time viscosity sensing for textural contrast in composed dishes. CE marking mandates govern thermal safety in commercial kitchen installations. Basque Country industrial clusters experiment with AI-driven print path optimization for medical nutrition personalization segments.
Belgium
Brussels and Antwerp luxury confectionery houses concentrate demand for binder jetting systems that preserve granular sugar integrity. EFSA nutritional equivalence studies front-load R&D expenditure for printed protein entrants. Flemish food manufacturers integrate deposition systems with existing HACCP monitoring infrastructure.
France
Paris and Lyon retail channels drive demand for occasion-specific custom desserts through compact countertop systems. ISO 22000 alignment requirements consolidate procurement toward certified vendors in hospital and aged-care nutrition contracts. Provence-Alpes-Côte d'Azur artisan producers leverage limited-run geometry capabilities for premium hospitality segments.
Food 3D Printing Market Vendor Landscape
The competitive structure tilts toward technology-specialist archetypes with NASA-derived heritage and open-platform architectures. Market concentration remains moderate, with distinct competitive arenas separating industrial extrusion systems from countertop accessibility plays. Two strategic archetypes dominate: precision deposition specialists serving defense and aerospace catering contracts, and modular platform providers targeting restaurant test kitchen adoption. Competitive moves center on regulatory pre-qualification for institutional vendor lists and AI convergence with extrusion control software.
Among European platform developers, byFlow and Natural Machines exemplify divergent accessibility strategies. BeeHex occupies a position within the mission-critical tier, leveraging aerospace heritage for portion precision contracts. These three anchors represent the spectrum from open-platform paste extrusion to countertop multi-material architectures, each sitting within distinct procurement channels that separate institutional catering from residential and small commercial segments.
| Leading Market Players |
|---|
| BeeHex |
| byFlow |
| Natural Machines |
| TNO |
| 3D Systems |
| Systems And Materials Research Corporation |
| Choc Edge |
| Revo Foods |
| Procusini |
| Others |
Supply Flow & Price Mechanics
Captive stainless steel sourcing from German and Italian metallurgical suppliers anchors both hardware cost structures and CE certification timelines for food-grade extrusion systems. REACH compliance for food-contact materials forces equipment manufacturers toward vertically integrated component production, compressing margin flexibility while extending procurement lead times for novel thermal control assemblies.
Pricing Analysis
Value-based pricing anchored to throughput yield and waste reduction outcomes dominates commercial extrusion system sales. Three-tier pricing structure across premium, standard, and economy levels separates NASA-derived precision deposition hardware from open-platform restaurant units and compact countertop systems. Cost compression in economy-tier residential segments is intensifying because cocoa butter price volatility limits chocolate printer affordability. Food manufacturers exhibit the lowest price sensitivity due to EU Green Deal waste mandate compliance savings, while artisan bakeries face acute margin pressure from stainless steel supply bottlenecks.
Supply Chain Analysis
Food-grade stainless steel supply rests on German and Italian specialty metallurgical producers with REACH-certified foundry capacity. Thermal control electronics draw from Dutch semiconductor packaging clusters, while food-safe silicone extrusion components source from French polymer compounders. Single-source vulnerability concentrates in CE-certified heating element assemblies, where Italian suppliers dominate precision temperature regulation hardware. Distribution runs through institutional foodservice procurement channels with pre-qualified vendor list requirements, excluding uncertified manufacturers from hospital and defense catering contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into food-safe thermal control component production represents the decisive upstream lever, as CE certification timelines and stainless steel supply concentration reward captive manufacturing capabilities.
For Market Incumbents: Anticipate regulatory acceleration of EFSA novel food assessments by front-loading ISO 22000 certification investments and pre-qualifying for Nordic public procurement vendor lists. Consolidate position through backward integration into stainless steel component machining, countering supply bottlenecks from German and Italian metallurgical suppliers while defending margins against emerging open-platform competitors. For New Entrants and Emerging Players: The price-point gap between premium aerospace-calibrated systems and economy countertop units creates entry space for mid-tier modular platforms targeting restaurant test kitchens in Spain and Belgium. Prioritize AI-driven viscosity compensation software as a differentiated go-to-market angle, leveraging real-time print path optimization to capture medical nutrition personalization segments before regulatory timelines compress. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by institutional foodservice equipment conglomerates seeking CE-certified thermal control expertise. Long-term viability hinges on regulatory pre-positioning in EFSA novel food dossier preparation, with acquisition target archetypes spanning hydrogel matrix startups and open-platform paste extrusion developers. Watch EFSA accelerated assessment timeline announcements as the critical inflection signal for personalized nutrition market entry.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Qualification | CE marking for thermal safety unlocks institutional catering procurement channels in Germany and France. |
| Backward Integration into Stainless Steel Components | Captive machining of REACH-compliant hardware mitigates supply bottlenecks from Italian metallurgical suppliers. |
| AI-Driven Viscosity Compensation Development | Real-time print path optimization enables medical nutrition personalization segments in Nordic hospital systems. |
| EFSA Novel Food Dossier Pre-Submission | Expedited regulatory review slots secure first-mover positioning in alternative meat extrusion markets. |
| ISO 22000 Alignment Investment | Documented food safety management systems qualify vendors for Nordic public procurement contracts. |
Methodological Framework
Independent corroboration across equipment manufacturer technical directors, restaurant executive chefs, and institutional foodservice procurement managers underwrites the qualitative findings. Primary interviews with EFSA regulatory consultants, thermal control component suppliers, and aerospace catering operations officers combined with secondary validation from CE marking databases, REACH compliance registries, and EU Green Deal implementation reports. Bottom-up unit economics from extrusion system deployments triangulate against top-down market sizing from food manufacturing capital expenditure tracking.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, technology modality, end-user procurement authority, and application maturity stage. CAGRs derive from installed capacity build rates, regulatory approval timeline assumptions, and substrate formulation pipeline assessments. Forecast inputs incorporate EFSA novel food assessment velocity, cocoa butter futures volatility patterns, and stainless steel alloy availability indices.
Inputs from equipment manufacturers and regulatory consultants were available through the study window; gaps in early-stage protein hydrogel extrusion performance data introduce uncertainty bands around alternative meat adoption curves. Forecasts reflect documented assumptions on CE certification cycle durations and REACH amendment trajectories. A small set of triggers—EFSA accelerated assessment announcements, cocoa supply shocks, and German metallurgical capacity utilization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printer Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
4D Printing Market