
 Corrugated Steel Panels Market | 2026-2036
Corrugated Steel Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Steel Panels Market Analytics
Indian flat-rolled steel capacity expansion is realigning regional supply availability for corrugated panel producers. JSW Steel leverages its integrated coastal mill network to dominate western India distribution. Tata BlueScope Steel anchors premium coated product lines through its joint-venture technical standards. Metal Sales Manufacturing Corporation sustains North American market presence via specialized agricultural and industrial building channels.
Corrugated steel panels are cold-formed sheet steel products with sinusoidal or trapezoidal profiles, typically manufactured from galvanized or coated steel in gauges ranging from 0.4 mm to 1.2 mm, designed primarily for structural roofing, wall cladding, and weather-resistant envelope applications. The roofing panels segment occupies the largest volume share due to replacement cycles in mature building stock across North America and Europe. Prefabricated installation is accelerating fastest as modular construction methods reduce on-site labor exposure and compress project timelines. Galvanized coating retains cost-sensitive volume leadership, though polyester-coated variants are capturing specification upgrades in commercial and institutional projects where color retention warranties extend asset lifespans.
India's BIS certification mandates for structural steel products are tightening market access for uncertified imports, while China's GB standards and SAMR enforcement on coating thickness are elevating domestic production quality floors. The EU's Construction Products Regulation and CE marking requirements continue to shape export competitiveness for Asian manufacturers serving European project specifications. Buyers and fabricators must monitor evolving carbon-border adjustment mechanisms and national green building codes that increasingly embed embodied-carbon thresholds in public procurement criteria.
Market Dynamics
Modular construction methods are compressing project timelines across warehouse and logistics infrastructure, forcing corrugated panel suppliers to reconfigure delivery models around prefabricated envelope systems rather than traditional on-site fabrication.
Growth Catalysts
- Cold-chain infrastructure mandates:India's western industrial corridor is adding manufacturing and cold-chain capacity at scale, driving specification-grade panel procurement in Gujarat and Maharashtra states.
- GB standards elevation:China's SAMR enforcement on coating thickness is pushing domestic mills toward higher-grade galvanized output, tightening quality floors across structural steel supply.
- Replacement cycle timing:Mature building stock across North America and Europe is entering roofing panel replacement windows, sustaining baseline demand for weather-resistant envelope materials.
Market Restraints
- Flat-rolled steel input volatility:Galvanized coil pricing swings directly compress panel fabricator margins, particularly for spot-market purchasers lacking mill-direct contracts.
- Western India supply concentration:JSW Steel's integrated coastal mill network dominates regional distribution, creating dependency risk for downstream fabricators outside captive supply arrangements.
- Polyester coating durability ceilings:Color retention warranties for standard coated variants lag commercial project lifespans, limiting specification penetration in institutional segments.
Strategic Opportunities
- EU carbon-border adjustment positioning:Asian manufacturers serving European project specifications can capture premium positioning by front-running embodied-carbon documentation requirements.
- Prefabricated installation acceleration:Modular construction methods reduce on-site labor exposure, creating white space for panel suppliers with integrated design-to-install capabilities.
- BIS certification barrier exploitation:India's tightening structural steel certification mandates are filtering uncertified imports, opening share capture for compliant domestic producers.
Industry Challenges
- Galvanizing line capex intensity:Continuous hot-dip coating capacity requires substantial furnace and bath investments, constraining mid-tier fabricator expansion.
- CE marking compliance timelines:European Construction Products Regulation documentation delays extend order-to-delivery cycles for Asian exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Steel Panels Market |
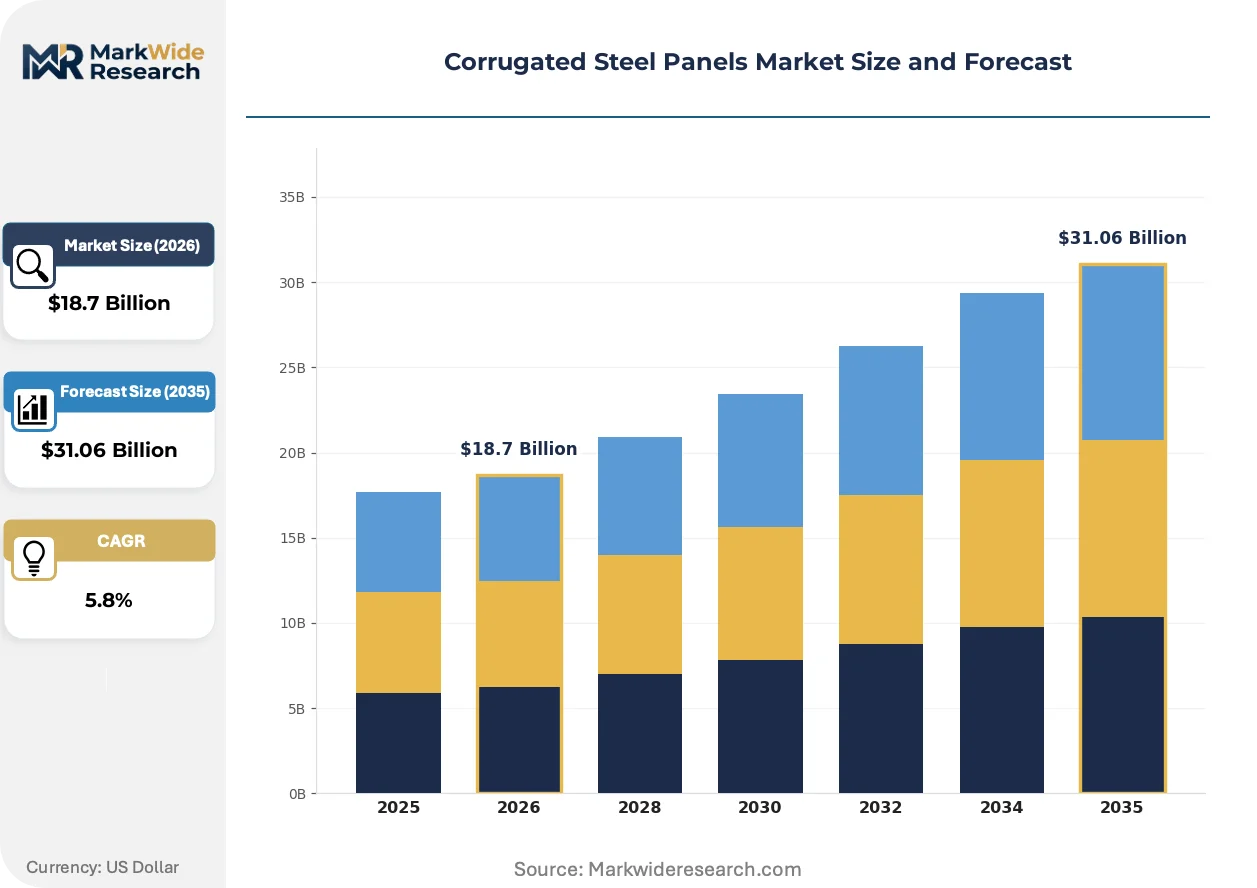
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roofing Panels, Siding Panels, Wall Panels, Decorative Panels End User: Construction, Agriculture, Mining, Manufacturing Installation Type: On-site, Prefabricated, Modular, Retrofits Coating Type: Galvanized, Painted, PVC Coated, Polyester Coated |
| Companies Covered | Tata BlueScope Steel, JSW Steel, McElroy Metal, Cornerstone Building Brands, Ternium, Metal Sales Manufacturing Corporation, BlueScope Steel Limited, Kingspan Group, VMZINC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Steel Panels Market Evolving Landscape
Corrugated steel panel manufacturing is pivoting toward precision-formed, high-performance envelope systems that embed thermal and structural functions previously handled by separate building layers.
Building-integrated photovoltaics is integrating thin-film solar laminates directly into trapezoidal panel profiles, enabling power generation from roof surfaces without separate mounting systems. Warehouse developers in Germany and the Netherlands are specifying these hybrid panels to meet EU Green Deal operational energy targets. The technology is integrating power infrastructure into structural envelopes, compressing separate trade coordination into single-source procurement.
REACH chemical restrictions on hexavalent chromium passivation are forcing coating chemistry transitions across European-bound production. Chinese mills serving EU project specifications are accelerating trivalent chromium and chromium-free pretreatment line conversions. Polyester-silicone hybrid topcoats are capturing specification share as buyers seek extended color warranty coverage against UV degradation.
Buyers are consolidating panel procurement around design-build contractors and integrated envelope specialists, displacing fragmented distributor relationships. Cold-storage developers in India are specifying single-source responsibility for insulated panel systems rather than sourcing corrugated shells and insulation separately. This concentration is most visible in Gujarat's pharmaceutical logistics corridor, where project scale justifies direct mill negotiation.
Corrugated Steel Panels Market Segmentation
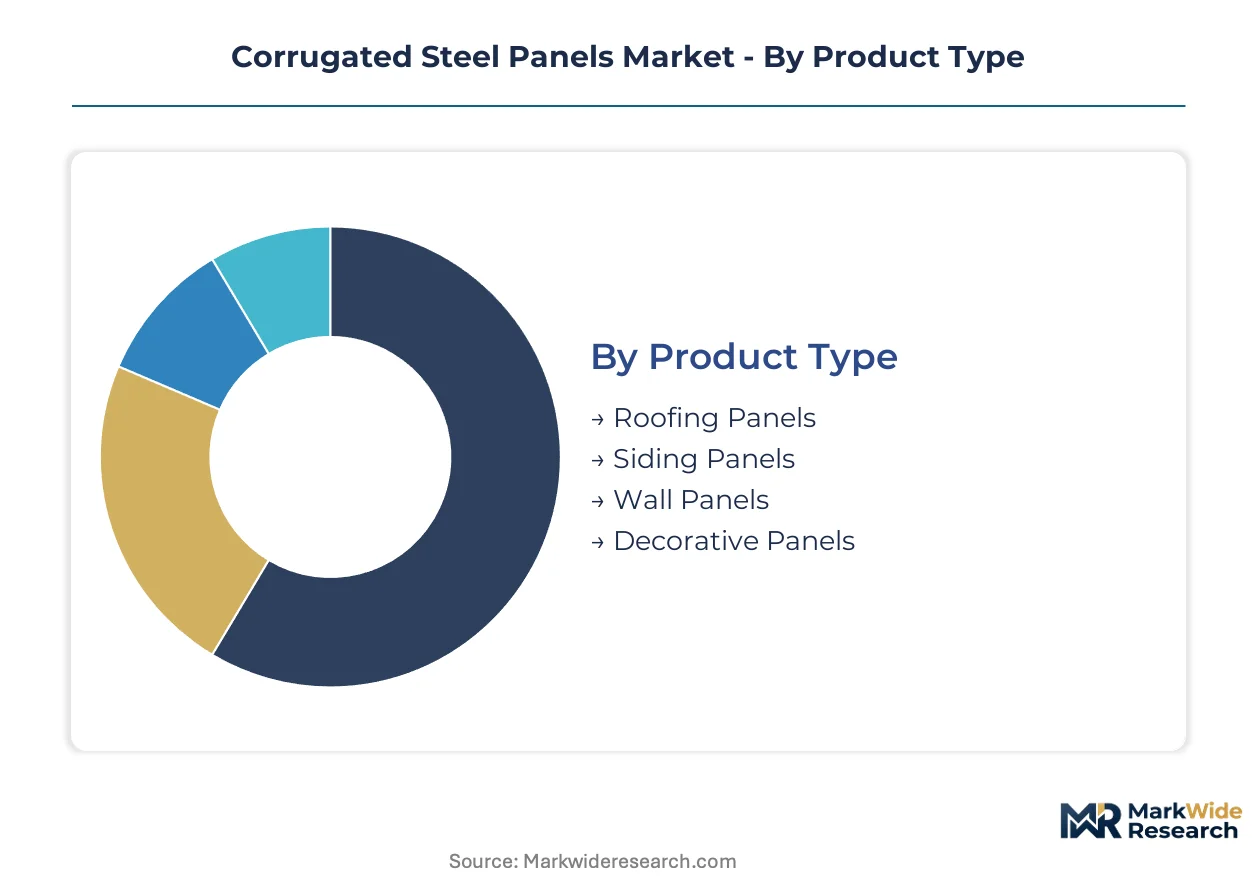
Corrugated steel panel buyers segment procurement by structural function, end-use durability requirements, and installation logistics. Specification-grade differentiation determines margin capture across construction, agriculture, and industrial verticals.
Product Type:
Buyers prioritize load-bearing capacity, weather exposure severity, and aesthetic requirements when selecting panel profiles for envelope applications.
- Roofing Panels:Trapezoidal and sinusoidal profiles engineered for water-shedding and snow-load resistance, typically specified in 0.47 mm to 0.8 mm galvanized substrates. Replacement cycles in North American commercial building stock sustain baseline procurement volumes for weather-resistant structural envelopes.
- Siding Panels:Vertical-rib and box-rib configurations designed for lateral wind resistance and impact durability, often specified with enhanced coating systems for UV degradation protection. Agricultural equipment storage facilities in the US Midwest specify these for machinery protection against hail and wind-driven debris.
- Wall Panels:Insulated composite configurations combining corrugated shells with thermal cores, increasingly specified for controlled-environment warehouses requiring temperature stability.
- Decorative Panels:Perforated and embossed surface treatments for architectural facades where visual texture supersedes pure structural function.
Roofing Panels lead volumes today; Prefabricated installation methods are gaining share fastest across commercial construction.
End User:
Application-specific durability standards and regulatory compliance requirements differentiate procurement patterns across vertical markets.
- Construction:Commercial, institutional, and residential building envelopes subject to local wind-load and fire-resistance codes. Warehouse developers in India's Gujarat pharmaceutical corridor specify BIS-certified structural panels for cold-chain compliance.
- Agriculture:Equipment storage, livestock housing, and grain protection structures requiring corrosion resistance in high-humidity environments. Metal Sales Manufacturing Corporation channels specialized agricultural product lines through dedicated distributor networks in North America.
- Mining:Harsh-environment processing facilities and remote camp infrastructure demanding heavy-gauge substrates and abrasion-resistant coatings.
- Manufacturing:Plant enclosures and lean-to additions where speed of enclosure completion drives specification toward standardized panel dimensions.
Construction commands the largest procurement volumes; Agriculture offers the most stable replacement-driven demand profile.
Installation Type:
Project timeline compression and labor cost exposure determine whether fabrication occurs at mill, fabricator, or final site location.
- On-site:Traditional roll-forming or panel fastening at construction location, retaining flexibility for dimension adjustments but extending weather-dependent exposure.
- Prefabricated:Factory-complete panel assemblies with integrated insulation and flashing components, compressing field installation to crane placement and seam sealing. Modular construction contractors in Germany specify these for logistics warehouse speed-to-occupancy targets.
- Modular:Fully integrated building envelope subsystems delivered as complete wall or roof sections, requiring design-build contractor coordination.
- Retrofits:Overlay and replacement panel systems designed for installation over existing substrates without full demolition.
On-site installation retains volume leadership; Modular approaches are climbing the fastest as design-build procurement consolidates.
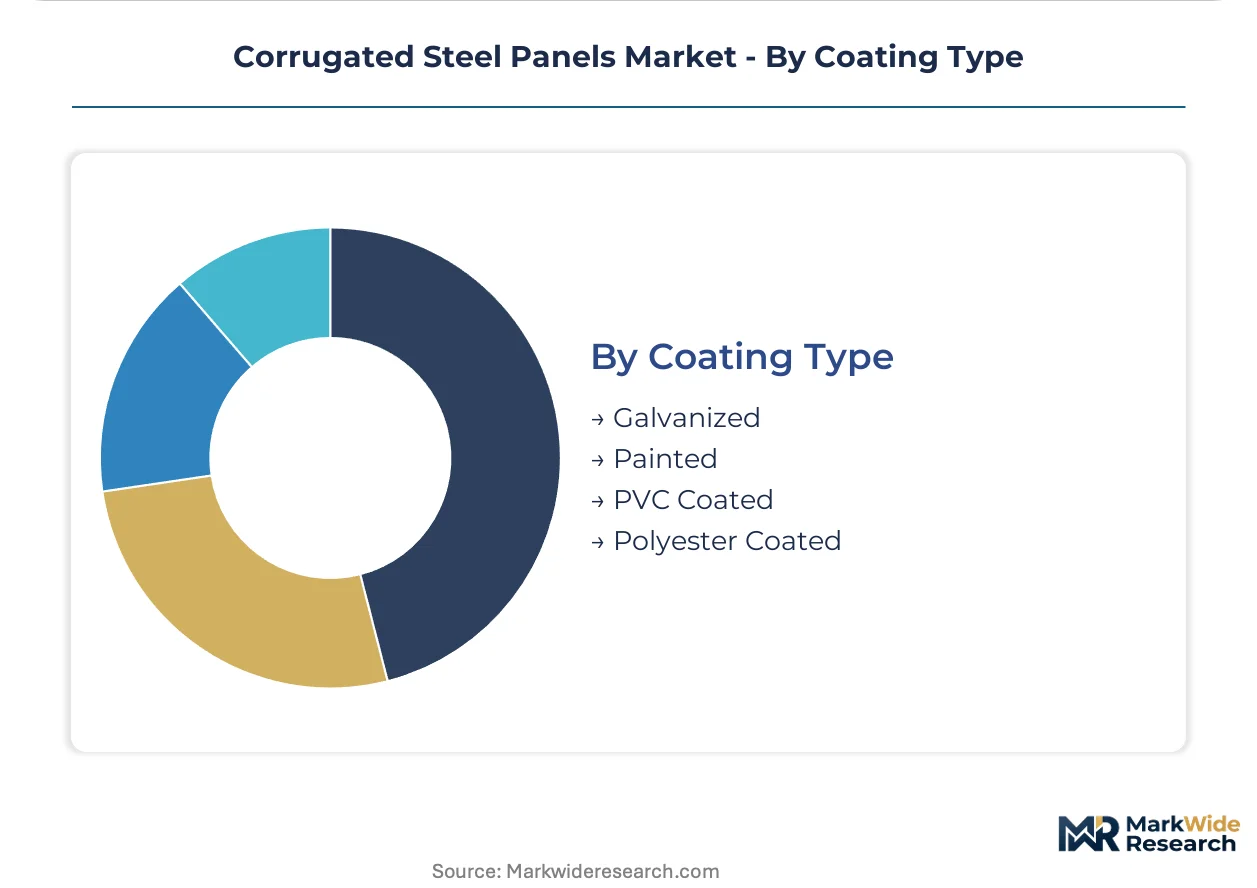
Coating Type:
Corrosion protection performance and color retention warranties drive specification tiering across cost-sensitive and premium project segments.
- Galvanized:Hot-dip zinc coatings at 100-275 g/m² providing sacrificial corrosion protection for structural substrates. China's SAMR enforcement on coating thickness minimums is elevating domestic production quality floors for structural steel bound for commercial projects.
- Painted:Post-formed liquid coating systems offering color customization at moderate cost, common in agricultural and light industrial applications where aesthetic longevity is secondary.
- PVC Coated:Laminated polymer films providing chemical resistance and color stability for aggressive industrial environments.
- Polyester Coated:Coil-coated fluoropolymer and silicone-modified polyester systems delivering extended color retention warranties for institutional and commercial facades. REACH chemical restrictions on hexavalent chromium passivation are forcing coating chemistry transitions across European-bound production lines.
Galvanized coatings dominate procurement volumes today; Polyester-coated variants are capturing specification upgrades in commercial and institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost gaps between jurisdictions are redirecting corrugated steel panel production toward markets with streamlined compliance pathways. Mills in lower-standard environments export to premium markets, while domestic producers in strict-regulation economies absorb certification overhead to defend local share.
China
GB standards and SAMR enforcement on coating thickness minimums are elevating quality floors for structural steel bound for commercial projects. Domestic mills serving European export specifications accelerate trivalent chromium line conversions to satisfy REACH chemical restrictions. Yangtze River Delta fabricators concentrate high-grade galvanized output for logistics warehouse developers in Germany and the Netherlands.
India
BIS certification mandates for structural steel products are filtering uncertified imports from Southeast Asian suppliers. PLI scheme incentives for specialty steel production attract integrated mill investment toward coated flat-rolled capacity. Gujarat's pharmaceutical logistics corridor and Maharashtra's cold-chain infrastructure expansion drive specification-grade panel procurement at scale.
United States
Replacement cycles in mature commercial building stock sustain baseline demand for weather-resistant roofing envelopes across the Midwest and Southeast. OSHA workplace safety regulations influence prefabricated installation preferences to reduce on-site labor exposure. Agricultural equipment storage facilities in Iowa and Kansas specify impact-resistant siding configurations for hail protection.
Germany
EU Green Deal operational energy targets push warehouse developers toward building-integrated photovoltaic panel specifications. CE marking requirements under the Construction Products Regulation extend documentation timelines for Asian exporters serving German project specifications. Logistics clusters in North Rhine-Westphalia specify single-source envelope procurement to compress speed-to-occupancy timelines.
United Arab Emirates
MOHAP and municipal building codes for controlled-environment facilities drive insulated composite panel specifications in pharmaceutical and food logistics. NEOM and Red Sea Project infrastructure timelines concentrate demand for modular envelope systems with crane-ready installation. Dubai-based contractors consolidate procurement around design-build envelope specialists to reduce trade coordination complexity.
Corrugated Steel Panels Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue prefabricated installation capabilities and carbon-compliant export positioning. Market structure concentrates around integrated steel mills with captive coating capacity and regional fabricators with specialized agricultural or industrial channel relationships. Three archetypes dominate: coastal integrated mills leveraging raw material access, joint-venture premium coaters with technical licensing advantages, and mid-tier roll-formers serving replacement-driven rural markets. Competitive moves center on backward integration into galvanizing capacity and strategic partnerships with modular construction contractors.
Among India-based integrated producers, JSW Steel and Tata BlueScope Steel exemplify divergent positioning archetypes. JSW Steel represents scale-driven coastal mill dominance with captive flat-rolled supply reaching western industrial corridor fabricators. Tata BlueScope Steel occupies the premium-tier joint-venture position, leveraging technical standards access for specification-grade coated products. Metal Sales Manufacturing Corporation anchors North American agricultural and industrial channel presence through specialized distributor relationships.
| Leading Market Players |
|---|
| Tata BlueScope Steel |
| JSW Steel |
| McElroy Metal |
| Cornerstone Building Brands |
| Ternium |
| Metal Sales Manufacturing Corporation |
| BlueScope Steel Limited |
| Kingspan Group |
| VMZINC |
| Others |
Value Network & Pricing Analysis
EU carbon-border adjustment mechanisms gate both qualified supply and premium-tier pricing access, filtering out uncertified Asian exporters while rewarding mills with embodied-carbon documentation. This regulatory filter concentrates pricing power among compliant producers and forces downstream fabricators into longer-term contract structures.
Pricing Analysis
Distributor margin layers compress as mill-direct procurement consolidates around large warehouse developers in India and Germany. Three-tier pricing structure across premium, standard, and economy levels tracks coating durability and certification grade, with polyester-silicone hybrid systems commanding widest spreads. Cost compression in standard galvanized tiers is intensifying because JSW Steel's coastal mill network captures western India volume with captive flat-rolled supply. Agricultural equipment storage buyers in the US Midwest show highest price sensitivity; cold-chain developers in Gujarat's pharmaceutical corridor show lowest.
Supply Chain Analysis
Single-source vulnerability sits with China's Yangtze River Delta concentration of high-grade galvanizing capacity serving European export specifications. Raw material flows draw from Australian iron ore, Indonesian nickel for specialty alloys, and South Korean zinc for coating baths. Tariff exposure on coated flat-rolled steel into the EU and US threatens margin structures for Asian exporters lacking local conversion presence. Distribution runs through design-build contractors consolidating envelope procurement rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's tightening BIS certification barriers and Southeast Asia's lower compliance costs, rewarding early positioning in certified domestic capacity.
For Market Incumbents: Extend coating chemistry capabilities toward trivalent chromium and chromium-free pretreatment lines to satisfy REACH restrictions on European-bound output. Deepen backward integration into continuous hot-dip galvanizing furnaces to offset flat-rolled steel input volatility threatening fabricator margins.
For New Entrants and Emerging Players: Enter via prefabricated installation capabilities serving modular construction contractors in Germany and the Netherlands, where speed-to-occupancy targets outpace traditional on-site fabrication. White space concentrates in insulated composite wall systems for India's cold-chain infrastructure expansion, with direct mill negotiation replacing distributor relationships at project scale.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier roll-formers with specialized agricultural channel relationships in North America. Long-term viability hinges on carbon-compliant export positioning and captive galvanizing capacity. The signal to watch is BIS certification timeline acceleration filtering import competition in India's western industrial corridor.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing Capacity | Captive coating lines insulate fabricator margins from zinc price volatility and coil supply disruptions. |
| Prefabricated Envelope System Development | Factory-complete panel assemblies compress German logistics warehouse timelines from months to weeks. |
| Trivalent Chromium Line Conversion | REACH-compliant pretreatment chemistry preserves EU market access for Chinese and Indian mills. |
| Direct Mill Negotiation Contracts | Bypassing distributor layers captures volume discounts for Gujarat cold-chain developers at pharmaceutical scale. |
| Building-Integrated Photovoltaic Integration | Thin-film solar laminates embedded in trapezoidal profiles meet EU Green Deal operational targets without separate mounting infrastructure. |
Research Methodology
Multiple input streams — primary interviews with coating line engineers and procurement directors at warehouse developers, secondary validation through customs trade data and BIS certification registries, and technical literature on GB standards evolution — were reconciled through bottom-up and top-down triangulation. Stakeholder roles included galvanizing plant managers, cold-chain project developers in Gujarat and Maharashtra, distributor network heads, and regulatory compliance officers at mills serving EU export specifications. Secondary sources comprised SEC filings from listed steel producers, CDSCO pharmaceutical logistics infrastructure disclosures, and Yangtze River Delta industrial output statistics.
Data-stream reconciliation anchored volume and value outputs to modeled segmentation across product type, coating chemistry tier, installation method, and end-use vertical through the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle timing in North American commercial stock and infrastructure buildout rates in India's western corridor. Industry-specific forecast inputs included SAMR enforcement trajectory on coating thickness minimums and PLI scheme incentive disbursement patterns for specialty steel capacity.
Inputs from BIS certification databases and EU carbon-border pilot program disclosures were available through the study window; gaps in real-time galvanizing line utilization rates at private Chinese mills introduce uncertainty bands around supply-side capacity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Tile Backer Boards Market