
 Air Pressure Booster System Market | 2026-2036
Air Pressure Booster System Market Size, Share, and Industry Trends Forecast 2026-2036
Air Pressure Booster System Market Outlook
German precision equipment manufacturers is consolidating supply chains for high-pressure gas boosters used across European process industries. Haskel International Inc. leverages its legacy in hydraulics to sustain dominance in aerospace testing applications. Maximator GmbH anchors its position through deep specialization in custom-engineered pressure intensification systems for automotive component validation.
An air pressure booster system amplifies low-pressure inlet gas to substantially higher discharge pressures, typically achieving ratios from 2:1 to 100:1 through piston-driven or diaphragm-based mechanical amplification. These systems serve critical functions in leak testing, gas transfer, and pressure generation where standard compressor output proves insufficient for process requirements. Pumps command the largest installed base among product types due to their versatility across pressure ranges and media compatibility, while electrical technology variants are gaining traction fastest as facilities prioritize energy recovery and precise pressure modulation. The manufacturing end-user segment concentrates margin pools through long service contracts and aftermarket parts demand tied to continuous production uptime requirements.
OSHA workplace safety mandates and EPA emissions controls in the United States compel operators to replace aging pneumatic infrastructure with sealed, low-leakage booster configurations. The EU Machinery Directive and CE marking requirements enforce design validation protocols that favor established suppliers with documented conformity assessment histories. Stakeholders must weigh capital allocation between electrical technology migration and retrofitting mechanical installed bases as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Electrification of pressure intensification equipment is compressing capital deployment cycles and forcing incumbent mechanical-system suppliers to reengineer sealed-drive architectures for EPA-compliant low-emission operation.
Growth Catalysts
- Deepwater exploration mandates:Middle Eastern national oil companies require high-pressure gas boosters for reservoir stimulation at depths exceeding 5,000 meters, where conventional compressor output fails.
- REACH substance restrictions:European chemical manufacturers are replacing pneumatically actuated process equipment with sealed electrical boosters to eliminate fugitive emissions of fluorinated greenhouse gases.
- Automotive lightweighting validation:German Tier-1 suppliers deploy custom pressure intensification systems for hydroforming aluminum chassis components, sustaining demand for precision-engineered boosters.
Market Restraints
- Specialized alloy supply concentration:High-strength stainless steel forgings for pressure vessels source predominantly from Japanese and German metallurgical suppliers, exposing lead times to regional capacity constraints.
- Electrical retrofit capex burden:Facilities with extensive pneumatic infrastructure face prohibitive replacement costs for sealed electrical systems, delaying compliance with OSHA workplace safety mandates.
- Diaphragm pump technical ceiling:Elastomer diaphragm materials impose pressure ratio limits near 50:1, constraining application in ultra-high-pressure testing above 10,000 psi.
Strategic Opportunities
- Hydrogen fueling infrastructure:Germany's H2Mobility initiative and EU Alternative Fuels Infrastructure Regulation create demand for 700-bar hydrogen compression and dispensing systems at port and highway corridors.
- Modular skid-mounted systems:Packaged booster assemblies with integrated controls and energy recovery circuits enable rapid deployment for temporary well testing and mobile manufacturing lines.
- CE marking pathway expansion:Machinery Directive conformity assessment protocols favor documented suppliers, creating barriers for new entrants and consolidating margin pools with established European manufacturers.
Industry Challenges
- Cross-functional engineering talent scarcity:Systems integrating high-pressure hydraulics, electrical drives, and process control require specialists conversant in ASME pressure vessel codes and IEC motor standards.
- Legacy pneumatic integration friction:Brownfield facilities struggle to interface sealed electrical boosters with existing shop air distribution networks and control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Pressure Booster System Market |
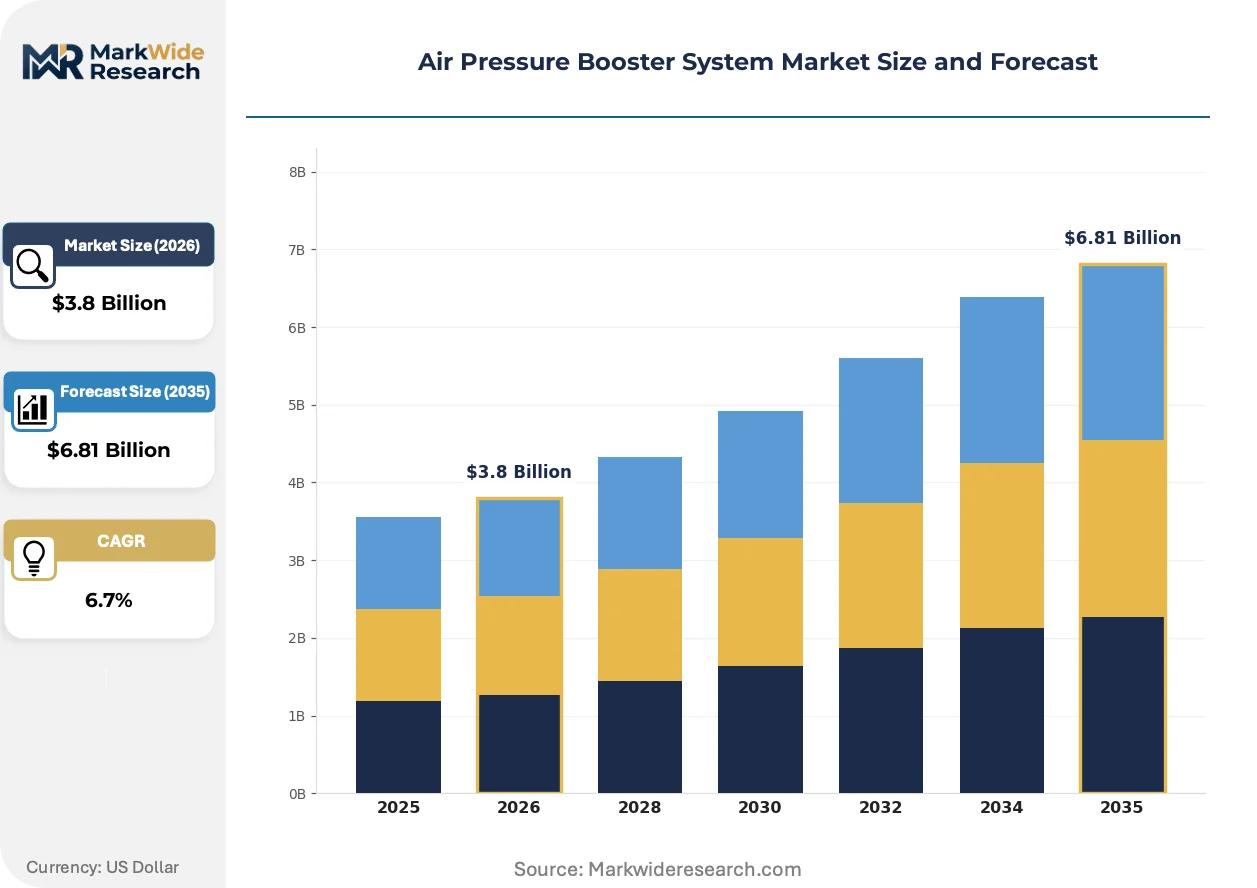
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Compressors, Blowers, Regulators Technology: Mechanical, Pneumatic, Electrical, Hydraulic Application: Industrial, Automotive, Aerospace, HVAC End User: Manufacturing, Construction, Oil & Gas, Food & Beverage |
| Companies Covered | Haskel International Inc., MaxPro Technologies Inc., High Pressure Technologies LLC, Maximator GmbH, Hydraulics International Inc., Atlas Copco AB, Ingersoll Rand Inc., Kaeser Kompressoren, Camozzi Automation SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Pressure Booster System Market Strategic Shifts
Active standardization of electrical drive architectures is compressing the performance gap between mechanical and sealed pressure intensification systems. Three developments are restructuring competitive positioning and procurement patterns.
Integrated servo-electric drive technology is modularizing pressure booster architectures. These systems combine permanent magnet motors with digitally controlled piston kinematics to enable precise pressure modulation and energy recovery during decompression cycles. Aerospace test facilities in France and the United States are adopting these configurations for fuel system validation. The technology is modularizing supplier ecosystems by separating drive electronics from pressure generation modules, enabling third-party control integration.
The EU F-Gas Regulation phase-down is mandating replacement of pneumatically actuated equipment in refrigeration and semiconductor process lines. Industrial operators face compliance deadlines that compress procurement cycles for sealed electrical alternatives. German process industries are most affected, with chemical manufacturers accelerating validation of diaphragm-based electrical boosters for fluorinated gas handling.
After-sales service unbundling is fragmenting long-term revenue streams for equipment suppliers. Manufacturing end-users in the United States are separating maintenance contracts from initial capital purchases, engaging third-party service providers for predictive diagnostics and spare parts logistics. This pattern is most visible in automotive component validation facilities, where specialized calibration requirements previously locked buyers into OEM service agreements.
Air Pressure Booster System Market Segmentation
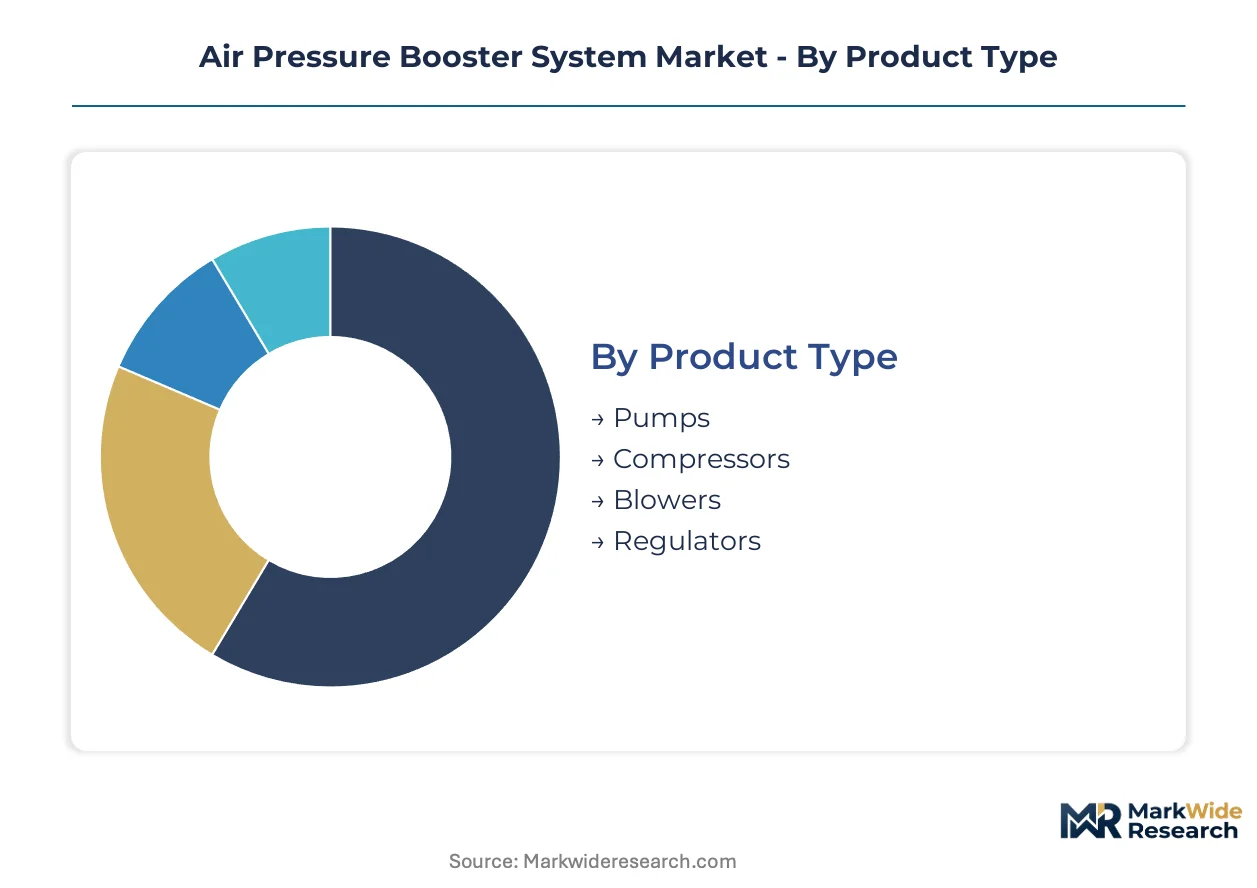
Segmentation in the air pressure booster system market reveals how capital deployment, regulatory exposure, and operational intensity vary across equipment categories. Procurement patterns diverge sharply between process industries seeking sealed electrical architectures and legacy facilities maintaining pneumatic infrastructure.
Product Type:
Pumps and compressors demand the heaviest upfront capital outlays due to pressure vessel certification requirements and precision machining of alloy components.
- Pumps:Piston-driven and diaphragm-based architectures dominate installed capacity across pressure ranges from 2:1 to 100:1 ratios. German precision equipment manufacturers concentrate supply chains for these systems serving European process industries. Demand concentrates in manufacturing end-use segments through long service contracts and aftermarket parts tied to continuous production uptime.
- Compressors:Centrifugal and reciprocating configurations handle higher volumetric throughput for gas transfer and reservoir stimulation applications. Middle Eastern national oil companies deploy these systems for deepwater exploration exceeding 5,000 meters where conventional output fails. Capital intensity peaks here due to specialized stainless steel forgings sourcing predominantly from Japanese and German metallurgical suppliers.
- Blowers:Lower-pressure amplification systems serve HVAC and pneumatic conveying with reduced pressure ratio requirements.
- Regulators:Pressure control components integrate with booster assemblies for precise downstream modulation in automated process lines.
Most installed capacity flows through pumps. Expansion is steepest in compressors.
Technology:
Electrical and hydraulic systems command premium pricing tiers driven by energy recovery capabilities and sealed-drive architectures for emissions compliance.
- Electrical:Servo-electric drives with permanent magnet motors enable precise pressure modulation and energy recovery during decompression cycles. Aerospace test facilities in France and the United States adopt these configurations for fuel system validation. Facilities prioritize this technology for EPA-compliant low-emission operation and OSHA workplace safety mandate compliance.
- Hydraulic:Fluid-power intensification delivers ultra-high-pressure generation above 10,000 psi for component validation and hydroforming applications. German Tier-1 automotive suppliers deploy these systems for aluminum chassis lightweighting validation. Capital requirements scale with high-pressure sealing technology and ASME pressure vessel code compliance.
- Mechanical:Traditional piston-driven architectures maintain cost advantages in brownfield facilities with existing pneumatic infrastructure.
- Pneumatic:Air-driven boosters face replacement pressure from EU F-Gas Regulation phase-down mandates and REACH substance restrictions on fluorinated greenhouse gas handling.
Mechanical systems retain the largest installed base. Electrical configurations are climbing the fastest as regulatory thresholds tighten across multiple jurisdictions.
Application:
Industrial and automotive applications concentrate procurement volume through validation protocols and continuous production requirements.
- Industrial:Process industries deploy boosters for leak testing, gas transfer, and pressure generation where standard compressor output proves insufficient. Chemical manufacturers across Germany accelerate validation of sealed electrical alternatives under EU F-Gas Regulation compliance deadlines. This segment locks in margin pools through predictive diagnostics contracts and spare parts logistics.
- Automotive:Component validation and hydroforming operations require custom-engineered pressure intensification systems. German Tier-1 suppliers sustain demand for precision-engineered boosters in aluminum chassis production. Capital cycles compress as lightweighting mandates intensify across European OEM supply chains.
- Aerospace:Fuel system and hydraulic component testing drives adoption of modular servo-electric architectures with third-party control integration.
- HVAC:Refrigeration process lines face equipment replacement mandates under fluorinated gas phase-down regulations.
Industrial applications anchor current revenue. Automotive validation represents the steepest expansion trajectory.
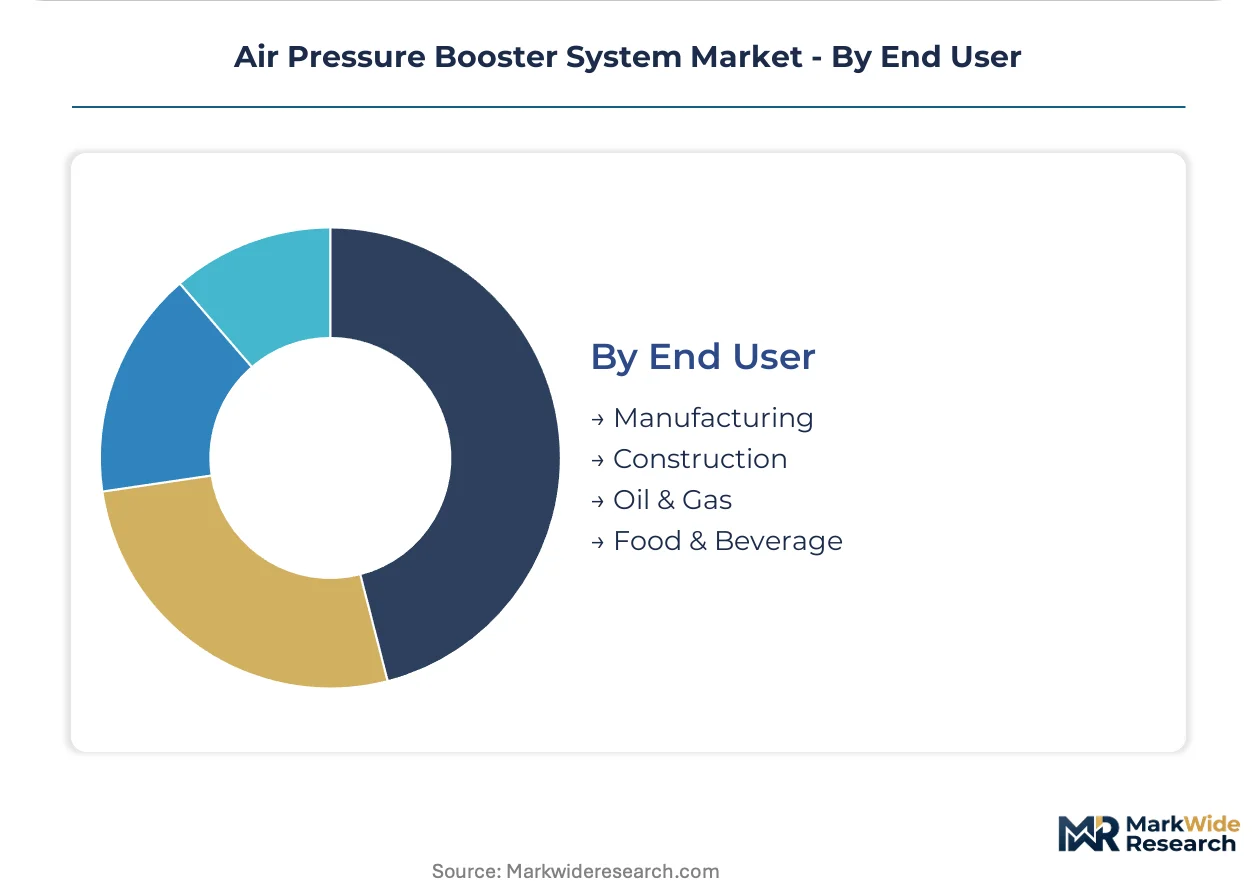
End User:
Manufacturing and oil and gas operations present contrasting capital deployment profiles between continuous uptime requirements and project-based procurement cycles.
- Manufacturing:Continuous production environments generate recurring aftermarket demand through service contracts and spare parts logistics. United States automotive component validation facilities are unbundling maintenance agreements from initial capital purchases, engaging third-party providers for specialized calibration. Margin pools concentrate here through long-term technical support relationships.
- Oil & Gas:Exploration and reservoir stimulation drives demand for high-pressure gas boosters in deepwater applications. Middle Eastern national oil companies require specialized compressor configurations for depths exceeding 5,000 meters. Procurement cycles align with project timelines and reservoir development schedules.
- Construction:Temporary well testing and mobile manufacturing lines favor modular skid-mounted booster assemblies with rapid deployment capabilities.
- Food & Beverage:Process line requirements emphasize sealed electrical configurations for workplace safety and contamination control.
Manufacturing end-users command the largest service contract value. Oil and gas project demand is gaining share fastest in the Middle East.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity is shifting toward jurisdictions where REACH and F-Gas compliance costs are offset by precision manufacturing ecosystems. The cost-of-compliance gap between sealed electrical architectures and legacy pneumatic systems is reshaping supplier location decisions across three continents.
Germany
Precision equipment manufacturers in Baden-Württemberg and Bavaria consolidate supply chains for high-pressure gas boosters serving European process industries. The EU Machinery Directive and CE marking requirements enforce design validation protocols that favor established suppliers with documented conformity assessment histories. Stuttgart's automotive component validation cluster sustains demand for custom-engineered pressure intensification systems in aluminum chassis hydroforming.
United States
OSHA workplace safety mandates and EPA emissions controls compel operators to replace aging pneumatic infrastructure with sealed, low-leakage booster configurations. Aerospace test facilities in California and Texas adopt modular servo-electric architectures with third-party control integration for fuel system validation. The Southeast automotive corridor unbundles maintenance agreements from initial capital purchases, engaging third-party providers for specialized calibration.
United Arab Emirates
National oil companies require high-pressure gas boosters for reservoir stimulation at depths exceeding 5,000 meters where conventional compressor output fails. The country's national petroleum regulator enforces equipment certification standards aligned with API specifications for wellhead pressure control. Abu Dhabi's industrial free zones concentrate procurement for deepwater exploration projects across the Arabian Gulf.
China
Process industries accelerate validation of diaphragm-based electrical boosters under the country's dual carbon goals and industrial emissions reduction targets. The national standardization administration issues GB standards for high-pressure equipment safety that parallel ASME pressure vessel codes. Yangtze River Delta chemical manufacturers deploy sealed electrical alternatives to eliminate fugitive emissions from fluorinated gas handling.
France
Aerospace test facilities adopt integrated servo-electric drive technology for precise pressure modulation and energy recovery during decompression cycles. The national aviation regulator enforces equipment qualification protocols for fuel system validation that favor modular control architectures. Toulouse's aeronautical engineering cluster drives procurement of digitally controlled piston kinematics for next-generation aircraft development programs.
Air Pressure Booster System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrification and modular skid-mounted configurations as differentiation vectors. The vendor base stratifies between legacy hydraulic specialists and servo-electric innovators. Three archetypes dominate: precision-engineered custom system builders, scale-driven compressor conglomerates, and niche hyperbaric equipment fabricators. Competitive moves concentrate on backward integration into high-strength alloy forging supply and technology licensing for sealed-drive architectures.
Among German-based specialists, Maximator GmbH and Haskel International Inc. exemplify the precision-engineered custom system tier, anchoring positions through deep specialization in pressure intensification for validation applications. Atlas Copco AB represents the scale-driven compressor conglomerate archetype, occupying a position spanning industrial gas handling and mobile equipment rental networks. These three entities collectively illustrate how geographic concentration in German precision manufacturing and Nordic industrial equipment conglomeration structures competitive positioning.
| Leading Market Players |
|---|
| Haskel International Inc. |
| MaxPro Technologies Inc. |
| High Pressure Technologies LLC |
| Maximator GmbH |
| Hydraulics International Inc. |
| Atlas Copco AB |
| Ingersoll Rand Inc. |
| Kaeser Kompressoren |
| Camozzi Automation SpA |
| Others |
Value Chain & Pricing Dynamics
Middle Eastern national oil companies concentrate procurement volume for deepwater reservoir stimulation equipment, anchoring contract-based long-term offtake pricing with suppliers qualified under API specifications. This buyer concentration compresses margin negotiation leverage for equipment vendors while rewarding documented conformity assessment histories under CE marking protocols.
Pricing Analysis
Distributor margins for aftermarket parts and service contracts run through manufacturing end-users in Germany and the United States, where predictive diagnostics contracts lock in recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified systems from CE-marked configurations and uncertified mechanical alternatives. Cost compression in standard-tier pneumatic retrofits is intensifying because OSHA workplace safety mandates compel sealed electrical migration. Automotive component validation facilities exhibit lowest price sensitivity due to specialized calibration requirements, while construction end-users deploying modular skid-mounted systems show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Dual-sourcing requirements from German precision equipment manufacturers mandate qualified suppliers for high-strength stainless steel forgings in both Japan and Germany, exposing lead times to regional capacity constraints. Component sourcing draws from Japanese metallurgical suppliers for pressure vessel alloys, German machining centers for precision piston assemblies, and Italian control system integrators for servo-electric drives. Single-source vulnerability concentrates in specialized alloy supply for ultra-high-pressure applications above 10,000 psi. Distribution runs through OEM-direct channels for large compressor configurations and authorized distributor networks for aftermarket parts and field service deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air pressure booster system market functions as a stable compounder, with regulatory compliance mandates across EPA, OSHA, and EU F-Gas Regulation frameworks generating replacement-driven demand cycles that smooth revenue volatility.
For Market Incumbents: Extend backward integration into high-strength alloy forging supply to secure captive capacity for ASME pressure vessel certification requirements. Deepen investment in servo-electric drive architectures to defend against emerging entrants commercializing modular skid-mounted systems with rapid deployment capabilities for temporary well testing applications.
For New Entrants and Emerging Players: Enter via hydrogen fueling infrastructure deployment corridors in Germany's H2Mobility initiative, where 700-bar compression systems face supply gaps from established vendors focused on legacy oil and gas applications. Target modular packaged booster assemblies with integrated energy recovery circuits as the most penetrable product configuration for mobile manufacturing lines and construction end-users.
For Investors and Strategic Acquirers: Industrial compressor conglomerates with established CE marking pathways represent the most active acquirer in this space, consolidating precision-engineered custom system builders to capture margin pools in automotive validation applications. The acquisition target archetype is mid-cap specialists with documented Machinery Directive conformity assessment histories and captive relationships with German Tier-1 automotive suppliers. Watch for inflection in EU F-Gas Regulation enforcement intensity as the signal indicating acceleration of sealed electrical replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive supply of Japanese and German pressure vessel materials secures ASME certification compliance timelines. |
| Servo-Electric Drive Platform Launch | Modular architectures with permanent magnet motors enable EPA-compliant low-emission operation for aerospace test facilities. |
| CE Marking Pathway Expansion | Documented Machinery Directive conformity assessment histories create barriers for new entrants in European process industries. |
| Long-Term Service Contract Unbundling | Third-party predictive diagnostics providers capture margin pools previously locked by OEM aftermarket agreements. |
| Hydrogen Infrastructure Partnership | 700-bar compression systems for Germany's H2Mobility corridors open new demand beyond traditional oil and gas applications. |
Study Parameters
Direct dialogue with plant engineers at German automotive Tier-1 suppliers, maintenance directors at Middle Eastern national oil companies, aftermarket service heads at US aerospace test facilities, and procurement leads at French chemical manufacturers grounded qualitative findings. Secondary validation drew from EPA emissions compliance filings, EU ECHA REACH substance restriction databases, SEC 10-K equipment supplier disclosures, and API specification documentation for wellhead pressure control systems. Bottom-up equipment shipment data and top-down industrial capital expenditure estimates were triangulated to anchor market sizing.
Bottom-up modeling tracked installed base depreciation schedules and replacement cycles across the projection horizon, while top-down analysis calibrated against industrial compressor market trajectories and oil and gas capital expenditure patterns. Segmentation dimensions included product type, technology architecture, application vertical, and end-user industry, with additional granularity on regulatory compliance tier. CAGRs were derived from regression analysis of historical replacement rates and forward projection of mandate-driven upgrade cycles, incorporating hydrogen infrastructure deployment timelines and F-Gas Regulation phase-down schedules as industry-specific inputs.
Inputs from OEM procurement teams and national petroleum regulators were available through the study window; gaps in real-time project sanctioning data for deepwater exploration introduce uncertainty bands around Middle Eastern demand forecasts. Deviation in OSHA workplace safety enforcement intensity or EPA emissions control implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
HVAC Control System Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Marine HVAC Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Europe Boiler System Market