
 North America HVAC Equipment Market | 2026-2036
North America HVAC Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America HVAC Equipment Market Analytics
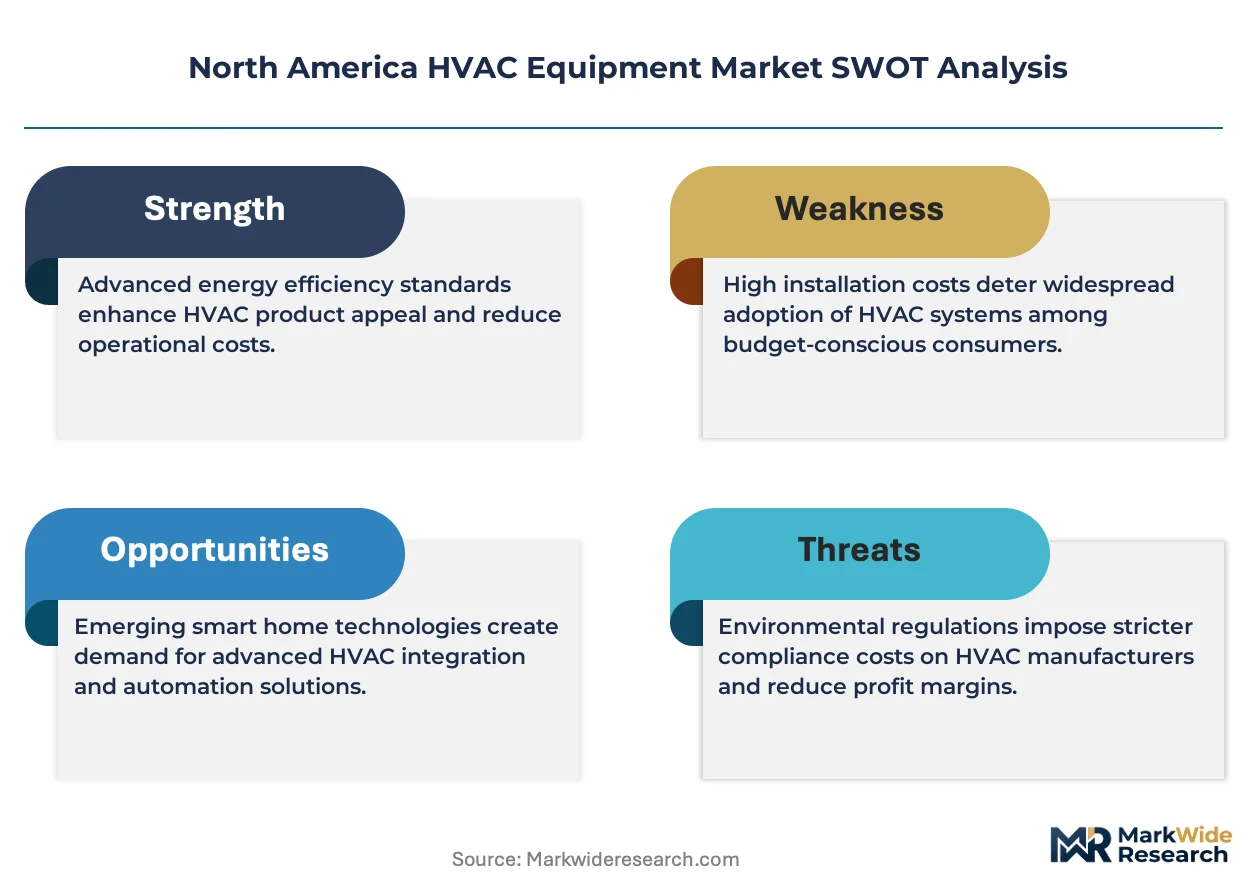
Certified refrigeration technician availability is bifurcating the North America HVAC Equipment Market into serviced metropolitan corridors and constrained secondary markets. Carrier Global Corporation leverages its dealer network density to anchor installation capacity in Sun Belt metros. Daikin Industries competes through vertical manufacturing scale that sustains shorter lead times for ductless and VRF systems.
North America HVAC equipment encompasses electromechanical systems designed to regulate indoor temperature, humidity, and air quality through vapor-compression cycles, combustion processes, or heat transfer fluids, typically operating within SEER ratings of 14–25 for cooling and AFUE ranges of 80–98.5% for gas-fired heating. Heat pumps capture expanding share as cold-climate performance thresholds improve, while furnaces retain dominance in legacy residential basements across the northern United States and Canada. Variable Refrigerant Flow systems concentrate margin pools in commercial retrofits where zoning flexibility commands premium positioning over centralized chiller replacements.
The EPA's AIM Act mandates an 85% phasedown of HFC production by 2036, reshaping compressor and refrigerant line designs across domestic manufacturing. DOE appliance efficiency standards and ASHRAE 90.1 building code iterations tighten minimum performance thresholds, filtering market access toward R&D-intensive suppliers. Stakeholders must weigh refrigerant transition timelines against heat pump electrification mandates in California, New York, and Canadian provincial codes when allocating capital between product platforms.
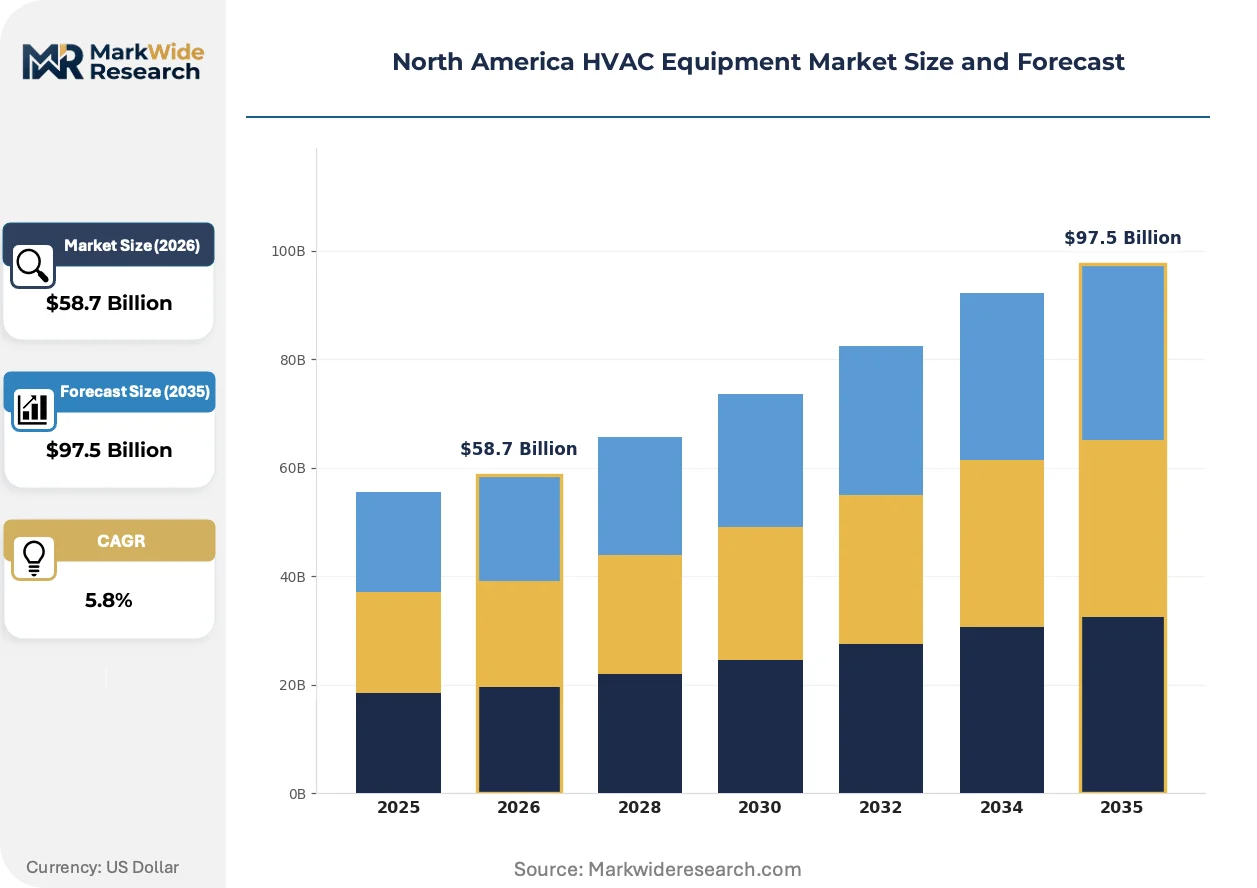
Market Dynamics
The EPA's AIM Act refrigerant phasedown is forcing equipment redesigns across domestic manufacturing, compressing product development cycles while reshaping supplier qualification requirements for lower-GWP compressor architectures.
Growth Catalysts
- Data center cooling demand:Hyperscale operators in the United States and Canada are accelerating unit shipments for precision cooling systems. Facility expansion timelines now compress equipment procurement windows.
- Heat pump electrification mandates:California, New York, and Canadian provincial codes are mandating cold-climate heat pump performance thresholds. Building code iterations are pulling replacement cycles forward in legacy housing stock.
- Building stock age concentration:Texas, California, and Florida contain the highest density of HVAC systems exceeding fifteen years of operational life. Climate severity in these states accelerates failure rates and replacement urgency.
Market Restraints
- Copper and aluminum price volatility:Coil and heat exchanger input costs fluctuate with commodity markets. Manufacturers absorb margin compression or pass through pricing that dampens residential replacement demand.
- Compressor supply concentration:Domestic production of low-GWP compressors concentrates among a limited set of qualified suppliers. Equipment OEMs face allocation constraints during peak construction seasons.
- Refrigerant transition friction:The AIM Act timeline forces parallel inventory management of R-410A and A2L alternatives. Service technician certification gaps slow field deployment of next-generation systems.
Strategic Opportunities
- Variable Refrigerant Flow retrofits:Commercial building owners in the United States are replacing centralized chillers with zoned VRF systems. Zoning flexibility commands premium positioning in Class B office renovations.
- DOE efficiency standard escalation:Appliance efficiency thresholds tighten minimum SEER and AFUE ratings. R&D-intensive suppliers gain market access as marginal producers exit non-compliant product lines.
- Ductless mini-split penetration:Secondary markets in the United States and Canada remain underpenetrated relative to metropolitan corridors. Dealer network expansion into these geographies captures replacement demand outside serviced corridors.
Industry Challenges
- Certified refrigeration technician scarcity:EPA Section 608 certification requirements for A2L refrigerant handling lag training program capacity. Secondary markets face installation backlogs that extend project timelines.
- Legacy system integration complexity:Cold-climate heat pump retrofits into existing furnace-basement configurations require electrical panel upgrades and ductwork modifications. Homeowner hesitation compresses conversion rates despite operating cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America HVAC Equipment Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Heat Pumps, Furnaces, Boilers End User: Residential, Commercial, Industrial, Institutional Technology: Smart Thermostats, Variable Refrigerant Flow, Ductless Systems, Chillers Installation Type: New Construction, Retrofit, Modular, Centralized |
| Companies Covered | Trane Technologies, Daikin Industries, Carrier Global Corporation, Johnson Controls, Lennox International, Rheem Manufacturing Company, Mitsubishi Electric, Ingersoll Rand, Nortek Global HVAC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America HVAC Equipment Market Evolving Landscape
Equipment architecture is fragmenting across refrigerant chemistry, electrification pathways, and digital control layers. Manufacturers must now synchronize hardware redesigns with software-enabled service models.
Magnetic bearing centrifugal chillers are decomposing the traditional compressor maintenance cycle in large commercial installations. Facility operators in the United States are adopting oil-free systems to eliminate bearing replacement intervals. The technology is decomposing aftermarket service revenue pools while shifting vendor relationships toward performance-based contracts.
The EPA's AIM Act mandates an 85% HFC production reduction by 2036. Equipment manufacturers must requalify compressor lines for A2L refrigerants with lower flammability ratings. The residential split-system segment faces the steepest redesign burden as R-410A inventory phases out ahead of field technician readiness.
Building owners are unbundling equipment procurement from installation and maintenance contracts. Commercial segments in the United States increasingly separate capital expenditure decisions from long-term service agreements. This pattern concentrates pricing pressure on OEMs while elevating independent contractor influence in aftermarket channels.
North America HVAC Equipment Market Segmentation
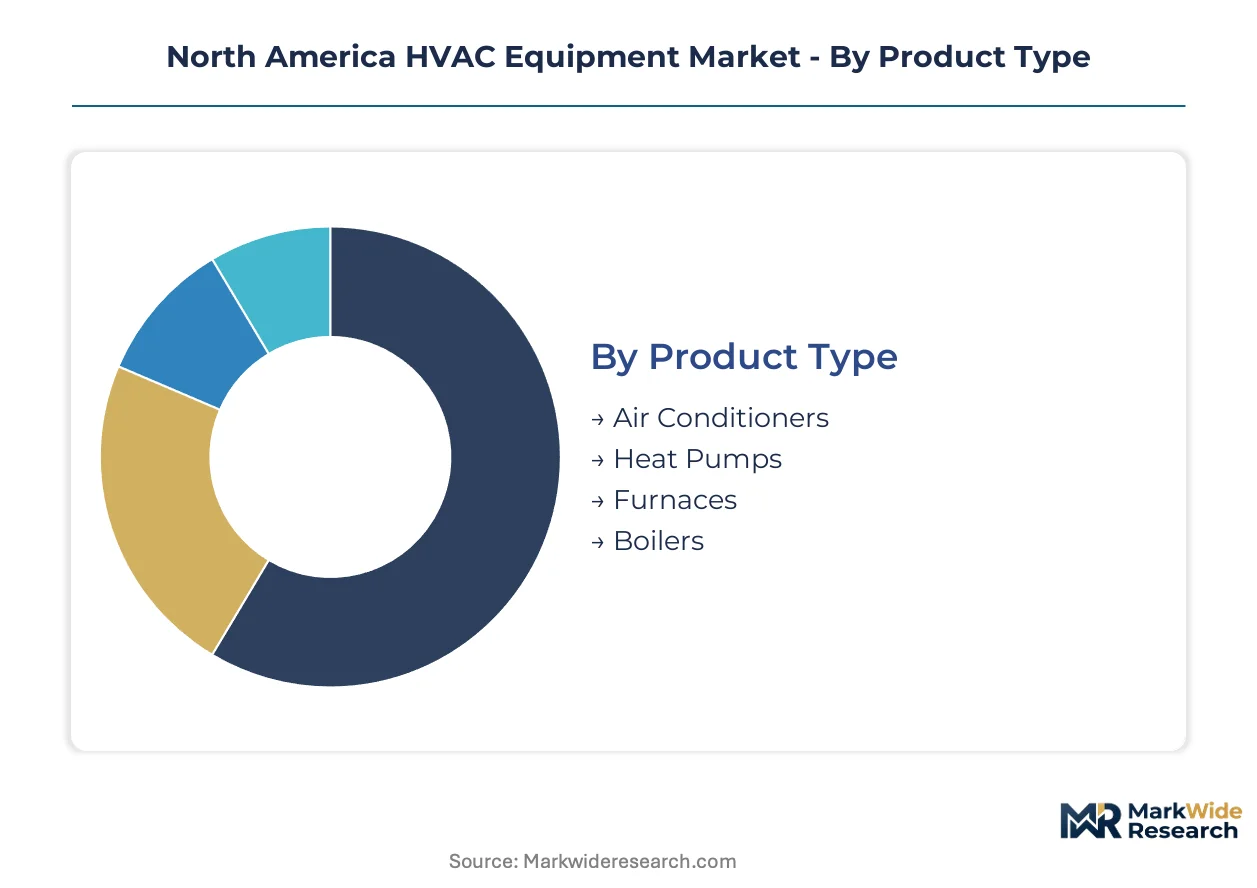
Equipment segmentation in the North America HVAC Equipment Market channels capital allocation toward refrigerant transition timelines and electrification mandates. Product type and technology choices determine compliance exposure to EPA AIM Act phasedown schedules. End user and installation type classifications shape service network density requirements across metropolitan and secondary corridors.
Product Type:
Distribution channels bifurcate around replacement urgency versus new construction procurement cycles, with product type determining whether equipment flows through dealer networks or direct contractor relationships.
- Air Conditioners:Split-system and packaged units operate on vapor-compression cycles with SEER ratings between 14 and 25. Demand concentrates in Texas, California, and Florida where climate severity accelerates replacement of systems exceeding fifteen years of operational life. The residential replacement channel dominates volume, though commercial rooftop units sustain higher margin pools through packaged service contracts.
- Heat Pumps:Cold-climate heat pumps now achieve operational thresholds below -15°F through enhanced vapor-injection compressors and variable-speed fan coils. California, New York, and Canadian provincial codes mandate heat pump electrification in new construction and major renovations. The technology is climbing the fastest as building code iterations pull replacement cycles forward in legacy housing stock.
- Furnaces:Gas-fired forced-air systems retain dominance in legacy residential basements across the northern United States and Canada.
- Boilers:Hydronic heating systems concentrate in commercial and institutional applications requiring radiant distribution.
Furnaces dominate installed base across northern climates. Heat pumps are where expansion concentrates as electrification mandates tighten.
End User:
Customer type stratifies procurement behavior around capital expenditure cycles, with institutional and industrial segments favoring performance-based contracts over equipment-only transactions.
- Residential:Single-family and multifamily dwellings drive unit volume through replacement of aging systems and new construction penetration. Texas, California, and Florida replacement cycles accelerate due to climate severity and building stock age concentration.
- Commercial:Class B office renovations and retail footprints command premium positioning for zoned systems over centralized chiller replacements. Variable Refrigerant Flow retrofits capture margin pools where zoning flexibility justifies higher first cost.
- Industrial:Process cooling and manufacturing facility climate control require specialized chiller configurations.
- Institutional:Schools, hospitals, and government facilities operate on extended procurement timelines with outcome-based service requirements.
Residential commands absolute unit volume. Commercial is where margin expansion concentrates through retrofit premiums.
Technology:
Technology selection determines refrigerant chemistry exposure and service technician certification requirements under EPA Section 608 mandates.
- Smart Thermostats:Connected control layers enable demand response participation and predictive maintenance scheduling. Data center cooling demand from hyperscale operators accelerates adoption of integrated building management systems.
- Variable Refrigerant Flow:Zoned refrigerant distribution systems modulate capacity across multiple indoor units from a single outdoor compressor rack. Commercial building owners in the United States replace centralized chillers with VRF where zoning flexibility commands premium positioning.
- Ductless Systems:Mini-split configurations penetrate secondary markets in the United States and Canada that remain underpenetrated relative to metropolitan corridors.
- Chillers:Large-tonnage centrifugal and screw-compressor systems serve commercial and industrial base loads.
Chillers dominate commercial installed base. VRF is where retrofit revenue concentrates.
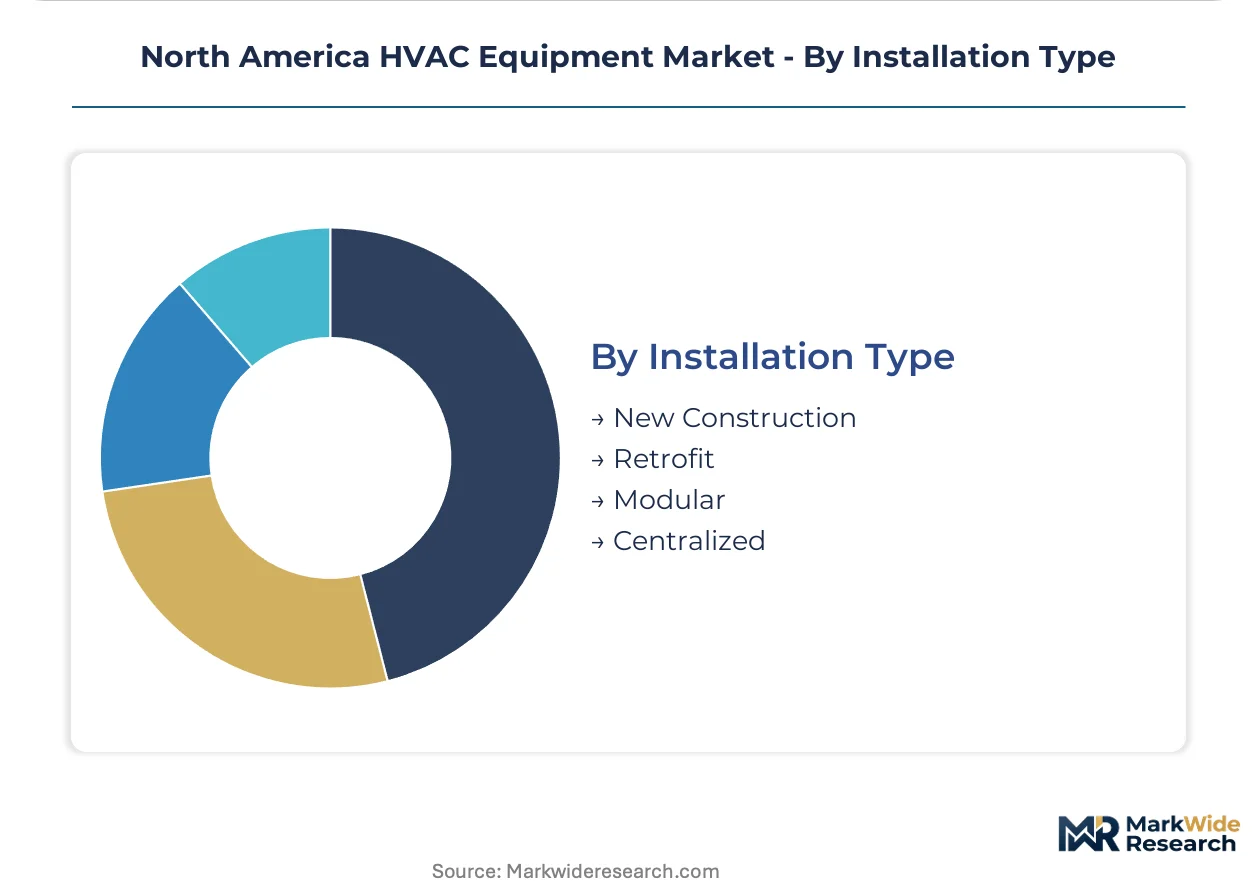
Installation Type:
Installation classification shapes project timeline compression and electrical infrastructure upgrade requirements.
- New Construction:Greenfield developments integrate HVAC specifications during architectural design phases. DOE appliance efficiency standards and ASHRAE 90.1 building code iterations tighten minimum performance thresholds, filtering market access toward R&D-intensive suppliers.
- Retrofit:Existing building system replacements require compatibility assessment with legacy ductwork and electrical panels. Cold-climate heat pump retrofits into furnace-basement configurations face homeowner hesitation despite operating cost advantages.
- Modular:Prefabricated mechanical packages accelerate deployment timelines for data center and industrial applications.
- Centralized:Single-point distribution systems serve large-footprint commercial and institutional facilities.
Retrofit dominates replacement volume. New construction is where efficiency standard compliance concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes HVAC equipment through replacement-heavy residential channels, while Canada emphasizes cold-climate heat pump electrification and Mexico concentrates on commercial infrastructure expansion. This three-country consumption mix shapes divergent product specifications and regulatory compliance burdens across North America.
United States
Texas, California, and Florida drive replacement cycles for systems exceeding fifteen years of operational life. The EPA's AIM Act mandates an 85% HFC production phasedown by 2036, forcing compressor requalification for lower-GWP refrigerants. Data center cooling demand from hyperscale operators in Northern Virginia and Phoenix accelerates precision cooling procurement timelines.
Canada
Provincial building codes in British Columbia and Quebec mandate cold-climate heat pump performance thresholds below -15°F. Natural Resources Canada's Greener Homes Initiative subsidizes residential electrification retrofits. The Toronto-Waterloo corridor concentrates commercial VRF installations in Class B office renovations.
Mexico
Commercial construction in Mexico City and Monterrey pulls packaged rooftop unit shipments for retail and hospitality footprints. The country's energy efficiency standards under CONUEE tighten minimum SEER ratings for imported equipment. Northern border states concentrate maquiladora facility climate control upgrades tied to nearshoring manufacturing expansion.
North America HVAC Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated manufacturing scale controlling compressor supply and refrigerant platform transitions. The upper tier commands dealer network density and captive distribution, while mid-scale competitors compete on regional installation capacity and retrofit specialization. Strategic archetypes include full-stack climate solution providers, component-integrated system assemblers, and regional service-intensive distributors. Competitive moves concentrate on vertical integration into low-GWP compressor sourcing and geographic densification of certified technician training networks.
Among North American climate solution providers, Carrier Global Corporation and Trane Technologies exemplify the integrated tier through captive manufacturing scale and dealer network anchoring. Daikin Industries occupies a position representing Japanese-origin vertical manufacturing discipline that sustains shorter lead times for specialized system architectures. These three entities sit within the structural core where refrigerant transition timelines and electrification mandates concentrate capital allocation decisions.
| Leading Market Players |
|---|
| Trane Technologies |
| Daikin Industries |
| Carrier Global Corporation |
| Johnson Controls |
| Lennox International |
| Rheem Manufacturing Company |
| Mitsubishi Electric |
| Ingersoll Rand |
| Nortek Global HVAC |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day compressor lead times from qualified A2L refrigerant suppliers concentrate pricing power among domestic OEMs with captive distribution networks, while spot-market aluminum and copper coil costs feed directly into equipment markup decisions across residential replacement channels.
Pricing Analysis
Contract-based long-term offtake agreements dominate commercial and industrial procurement, insulating large buyers from spot volatility in copper and aluminum coil inputs. Price differentiation rests on SEER certification tiers and cold-climate heat pump performance ratings mandated by DOE efficiency standards. Pricing pressure stems from commodity cost pass-through requirements that dampen residential replacement demand in price-sensitive secondary markets. Single-family homeowners exhibit highest price sensitivity, while data center hyperscale operators prioritize uptime guarantees over capital expenditure optimization.
Supply Chain Analysis
Inbound logistics costs through West Coast ports and the Panama Canal trade lane compress margin structures for coil and heat exchanger imports from Mexico and China. Domestic manufacturing draws from copper strip mills in Arizona and Tennessee, compressor casting facilities in Texas, and electronic control module assembly in Mexico. Single-source vulnerability concentrates in low-GWP compressor architectures qualified under EPA Section 608 mandates. Distribution runs through captive dealer networks for residential split-systems and direct contractor relationships for commercial rooftop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America HVAC Equipment Market sits at a high-growth inflection as EPA AIM Act refrigerant phasedown forces parallel inventory management and equipment redesign cycles across domestic manufacturing.
For Market Incumbents: Fortify installation capacity through certified technician training network densification in Sun Belt metros where replacement urgency concentrates. Anchor dealer exclusivity agreements in Texas, California, and Florida to defend against independent contractor channel erosion. Prioritize backward integration into A2L compressor sourcing to secure allocation during peak construction seasons. For New Entrants and Emerging Players: Differentiate on cold-climate heat pump performance thresholds below -15°F where incumbent product lines lag electrification mandates. Target secondary markets in the United States and Canada that remain underpenetrated relative to metropolitan corridors for ductless mini-split penetration. Pursue direct-to-contractor digital procurement platforms that unbundle equipment from legacy service contracts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven replacement cycle play because AIM Act compliance timelines and building code electrification mandates lock in sustained equipment turnover regardless of macroeconomic conditions. Acquisition targets should exhibit captive low-GWP compressor supply or dense certified technician networks. Watch EPA Section 608 certification program capacity as the signal for installation bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive A2L refrigerant compressor supply secures allocation priority during peak construction seasons. |
| Certified Technician Training Network Expansion | EPA Section 608 certification capacity anchors installation throughput in replacement-heavy metropolitan corridors. |
| Cold-Climate Heat Pump Product Line Investment | DOE efficiency standard escalation filters market access toward R&D-intensive suppliers with sub-zero performance. |
| Direct-to-Contractor Digital Platform Launch | Unbundled procurement models capture commercial segments separating capital expenditure from service agreements. |
| Variable Refrigerant Flow Retrofit Specialization | Zoning flexibility commands premium positioning in Class B office renovations across the United States. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment OEM procurement directors, EPA-certified refrigeration technicians, commercial facility maintenance managers, and independent HVAC contractors; and secondary validation through DOE appliance efficiency standard filings, EPA AIM Act implementation timelines, ASHRAE 90.1 code iteration records, and customs trade data on copper and aluminum coil imports. Bottom-up unit shipment estimates from state-level building permit databases triangulated against top-down manufacturer revenue disclosures.
Across the projection horizon, the analytical framework modeled equipment segmentation by product type, end-user category, refrigerant chemistry platform, and installation classification. CAGRs derived from replacement cycle velocity in climate-severe states and electrification mandate adoption curves. Industry-specific forecast inputs incorporated data center cooling procurement timelines from hyperscale operator facility expansion disclosures and provincial heat pump performance threshold mandates in Canada.
Material uncertainties — commodity price volatility in copper and aluminum, EPA Section 608 certification program capacity constraints, and building code adoption timing across Canadian provinces — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as refrigerant transition timelines and heat pump electrification mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market