
 HVAC Actuators Market | 2026-2036
HVAC Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Actuators Market Analysis
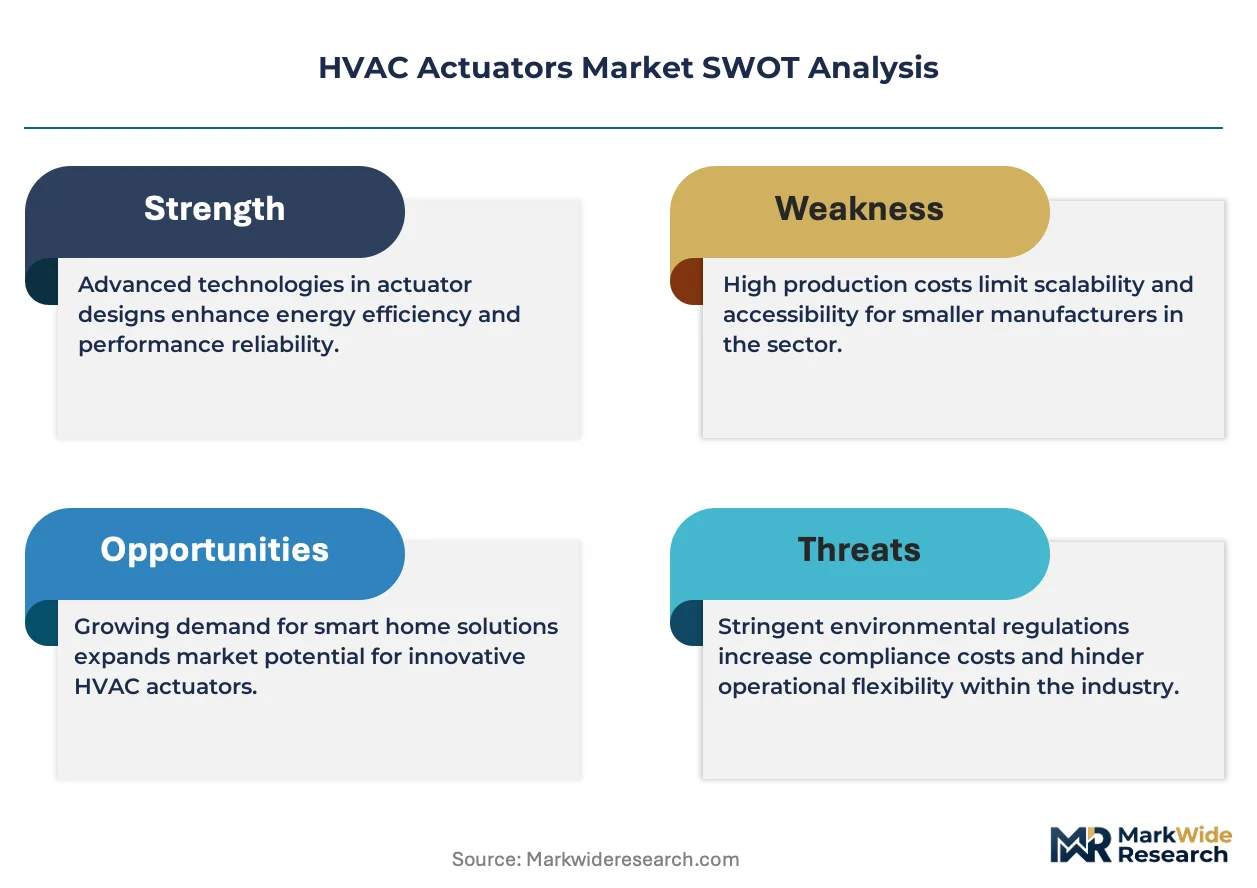
The divergence between premium smart actuators and commodity on-off units is repositioning competitive dynamics across the supply base. Belimo leverages its precision airflow specialization to command specification-driven channels in pharmaceutical cleanrooms. Siemens AG anchors large-scale building automation contracts through its Desigo platform integration, while Honeywell International competes on sensor-actuator convergence for connected HVAC ecosystems.
HVAC actuators are electromechanical or fluid-power devices that convert control signals into mechanical motion to regulate dampers, valves, and air handling units, typically operating within torque ranges from 2 Nm to 40 Nm and temperature tolerances between -20°C and 50°C. Their primary purpose is to enable automated climate control, energy recovery, and zone-level precision in heating, ventilation, and air conditioning systems. Electric actuators dominate installed volume due to wiring simplicity and compatibility with Building Management Systems, though smart control technology is capturing disproportionate margin expansion as BACnet and Modbus integration becomes standard. Proportional control variants are maturing in commercial buildings, while modulating control segments are gaining traction in industrial facilities requiring tight humidity and pressure parameters.
The US Department of Energy appliance standards and ASHRAE 90.1 energy codes are tightening minimum efficiency requirements for actuator-driven damper and valve assemblies, directly influencing product design cycles. In Europe, the Ecodesign Directive and F-Gas Regulation are forcing HVAC OEMs to specify actuators compatible with lower-GWP refrigerant systems and heat pump architectures. Stakeholders must monitor how regional decarbonization timelines reshape actuator specification sheets and certification burdens.
Market Dynamics
Smart building automation systems are compressing specification cycles for HVAC actuators, forcing manufacturers to integrate BACnet and Modbus protocols natively while simultaneously meeting tightening energy efficiency mandates across commercial real estate portfolios.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating heat pump retrofits across Germany, Poland, and France, each requiring proportional control actuators for precise thermal management.
- Data center cooling:Hyperscale facilities in Virginia, Frankfurt, and Singapore are deploying modulating damper actuators to optimize airflow containment and reduce PUE metrics.
- Electrification of heating:Cold-climate heat pump installations are concentrating in Scandinavia and the northeastern United States, driving demand for low-temperature torque-rated actuators.
Market Restraints
- Rare earth magnet volatility:Neodymium and dysprosium price swings from Chinese processing concentration are squeezing margins on brushless DC motor assemblies.
- Semiconductor lead times:Microcontroller shortages from Taiwanese foundry bottlenecks are extending actuator delivery schedules by 12-18 weeks for smaller OEMs.
- Copper and aluminum input costs:Wiring harness and housing material inflation is pressuring commodity on-off actuator pricing floors.
Strategic Opportunities
- Retrofit building stock:Pre-2000 commercial properties in Chicago, London, and Tokyo represent underpenetrated zones for wireless actuator upgrades bypassing conduit installation.
- Industrial humidity control:Pharmaceutical manufacturing in Switzerland and Singapore requires ultra-precise modulating valves for cleanroom pressurization.
- Grid-interactive buildings:California Title 24 and New York Local Law 97 are mandating demand-responsive HVAC, creating specification pull for actuators with embedded power monitoring.
Industry Challenges
- Cybersecurity certification:IEC 62443 compliance for connected actuators is extending product development timelines and requiring third-party penetration testing.
- Legacy pneumatic system integration:Converting compressed-air infrastructure to electric actuation in aging hospitals and universities demands custom mounting adapters and control signal translation.
- Skill gaps in building automation programming:Shortages of technicians proficient in BACnet/IP configuration are delaying commissioning and eroding customer satisfaction scores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Actuators Market |
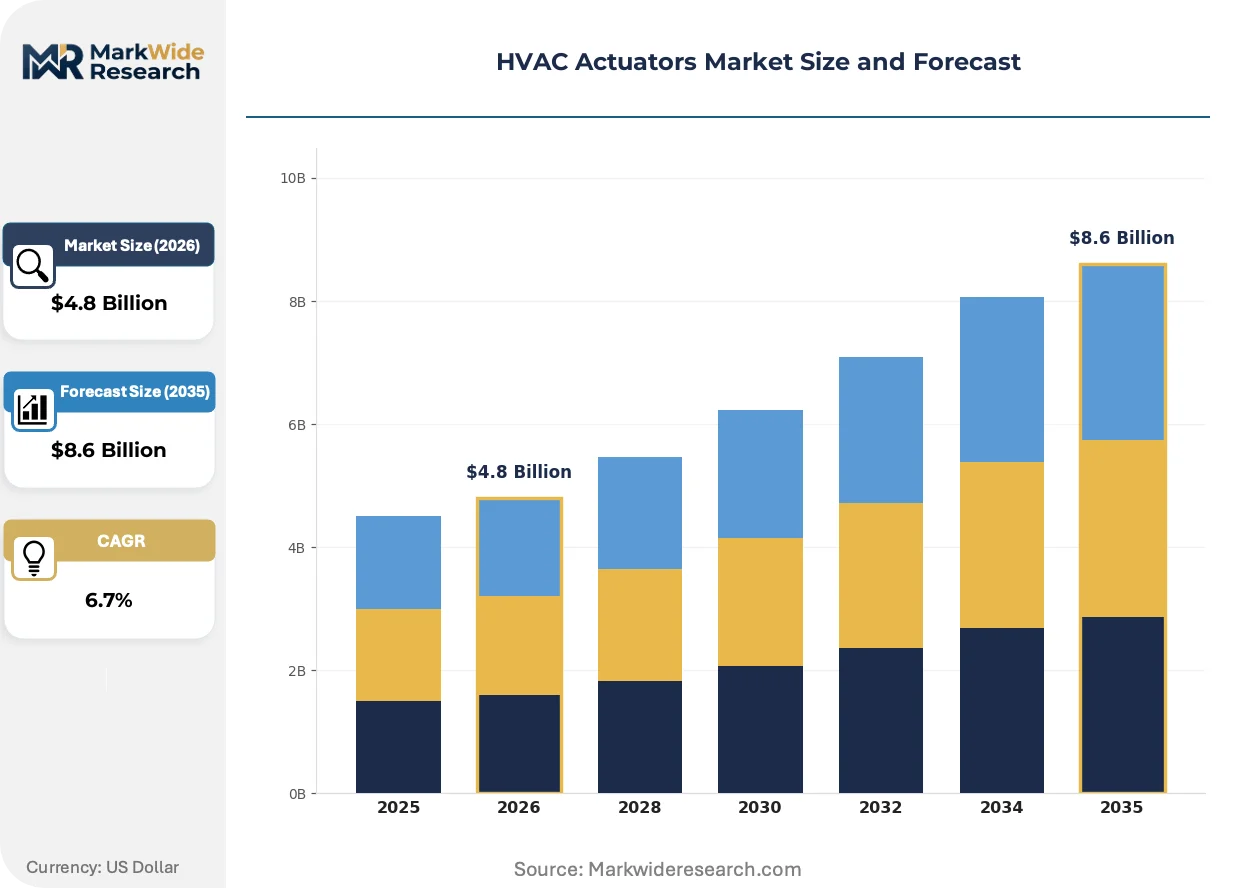
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Pneumatic Actuators, Hydraulic Actuators, Thermal Actuators Technology: On-Off Control, Proportional Control, Modulating Control, Smart Control Application: Commercial Buildings, Industrial Facilities, Residential Spaces, Automotive Systems Installation Type: Ceiling Mounted, Wall Mounted, Floor Mounted, Integrated Systems |
| Companies Covered | Schneider Electric SE, Belimo, Honeywell International, Rotork Plc, Robert Bosch GmbH, Siemens AG, Danfoss, Sauter, Johnson Controls International PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Actuators Market Emerging Trajectories
Edge computing architectures are redistributing control intelligence from central building management systems to distributed actuator nodes, enabling faster loop response times and reducing network dependency for critical climate functions.
Wireless mesh protocols are decentralizing actuator deployment in historic buildings and concrete-heavy structures where running dedicated control wiring proves prohibitively expensive or architecturally invasive. Museum and university facilities in Boston, Vienna, and Kyoto are adopting battery-harvesting actuators that eliminate power cabling entirely. This topology is compressing installation costs and enabling zone-level retrofits that were previously uneconomical.
The F-Gas Regulation's escalating refrigerant restrictions are forcing HVAC OEMs to redesign heat exchanger and expansion valve architectures, which in turn demands actuators with expanded stroke ranges and corrosion-resistant materials compatible with CO2 and hydrocarbon systems. Equipment manufacturers serving the German industrial corridor are prioritizing stainless steel gear trains and specialized seals. Component suppliers must recertify torque ratings under these new thermal and chemical operating envelopes.
Facility managers are consolidating vendor relationships and demanding actuator-to-sensor bundled procurement, displacing the historical pattern of separate specification for dampers, valves, and their respective drivers. Integrated packages from building automation specialists are capturing preference in new construction projects across Texas, Ontario, and Victoria. This consolidation is compressing margins for standalone actuator manufacturers while rewarding those with in-house sensing capabilities or strategic sensor partnerships.
HVAC Actuators Market Segmentation
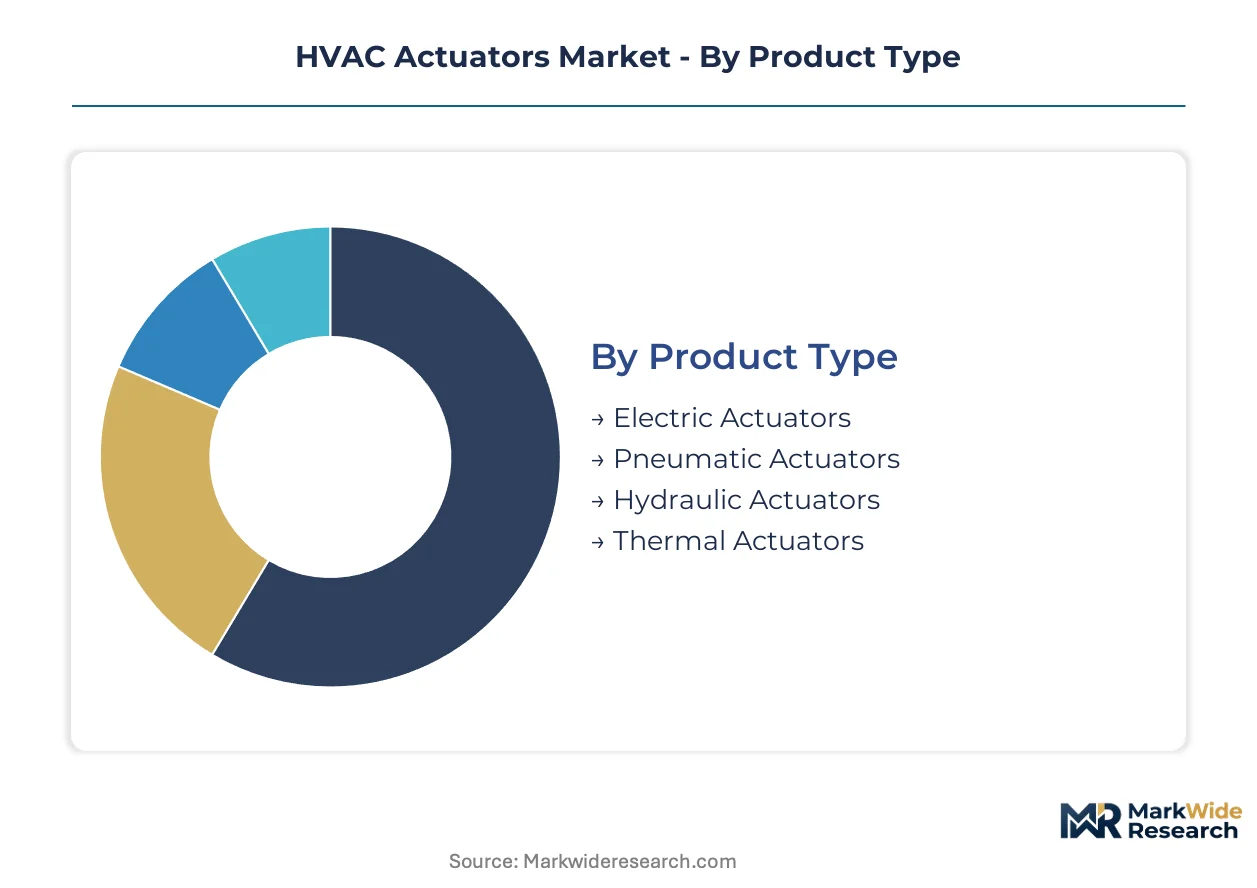
HVAC actuator segmentation reveals divergent margin profiles across electromechanical technologies and control architectures. Product type and technology categories dominate specification decisions, while application and installation dimensions determine procurement patterns and channel economics.
Product Type:
Electric actuators command volume leadership through wiring simplicity and Building Management System compatibility, while pneumatic and hydraulic variants retain defensible positions in specialized torque and safety-critical environments.
- Electric Actuators:Brushless DC motor assemblies with 2-40 Nm torque ranges dominate commercial building retrofits. Demand concentrates in Germany's industrial corridor where F-Gas Regulation compliance is accelerating heat pump specification. BACnet-native models capture disproportionate margin expansion.
- Pneumatic Actuators:Compressed-air systems with explosion-proof ratings persist in chemical processing and oil refining facilities. Deployment concentrates in Texas and Louisiana petrochemical clusters where intrinsic safety requirements override electrification trends. Legacy infrastructure conversion costs sustain incumbent positions.
- Hydraulic Actuators:High-force fluid-power units serve damper applications exceeding 40 Nm in tunnel ventilation and subway systems.
- Thermal Actuators:Wax-filled passive devices provide fail-safe positioning in radiator valves and small-zone applications without electrical supply.
Mature deployment sits with Pneumatic Actuators in legacy industrial infrastructure. Newer deployment is concentrated in Electric Actuators with embedded smart control capabilities.
Technology:
Control sophistication tiers separate commodity replacement demand from specification-driven new construction, with protocol integration and edge intelligence defining competitive positioning.
- Smart Control:Actuators with embedded microcontrollers, power monitoring, and wireless mesh capability are gaining share fastest in grid-interactive building mandates. California Title 24 and New York Local Law 97 are pulling demand for demand-responsive units with embedded BACnet/IP stacks. Cybersecurity certification per IEC 62443 extends development timelines.
- Modulating Control:Continuous positioning with 0-10V or 4-20mA feedback enables precise humidity and pressure management. Pharmaceutical cleanrooms in Switzerland and Singapore specify these for cleanroom pressurization. Stainless steel gear trains accommodate CO2 refrigerant compatibility requirements.
- Proportional Control:Intermediate positioning between fully open and closed serves variable air volume systems in commercial office buildings.
- On-Off Control:Binary positioning remains the cost floor for residential and light commercial applications with minimal automation requirements.
Proportional Control dominates current installed base in commercial real estate. Modulating and Smart Control segments are climbing the fastest through specification upgrades in data center and pharmaceutical end-uses.
Application:
End-use differentiation separates price-sensitive residential replacement cycles from engineered specification processes in commercial and industrial new construction.
- Commercial Buildings:Office towers, retail centers, and hospitality properties drive the largest absolute volume through damper and valve automation. Hyperscale data centers in Virginia and Frankfurt deploy modulating damper actuators for airflow containment and PUE optimization. Wireless retrofit solutions bypass conduit installation in pre-2000 building stock.
- Industrial Facilities:Manufacturing plants and process industries require corrosion-resistant actuators for aggressive environments. Cold-climate heat pump installations in Scandinavia demand low-temperature torque-rated units for electrified heating systems.
- Residential Spaces:Single-family and multi-family housing operate on replacement cycles with lower control sophistication requirements.
- Automotive Systems:Vehicle HVAC modules represent a distinct procurement channel with volume-scale pricing and thermal cycling durability specifications.
Residential Spaces anchor replacement volume through commodity on-off units. Commercial Buildings represent the steepest expansion trajectory through smart building automation and energy code compliance mandates.
Installation Type:
Mounting configuration determines labor economics and retrofit feasibility, with wireless and battery-harvesting topologies disrupting traditional conduit-dependent deployment.
- Ceiling Mounted:Plenum-rated actuators for air handling units and variable air volume boxes constitute the standard commercial configuration. Museums and university facilities in Boston and Vienna are adopting battery-harvesting ceiling units to eliminate power cabling in historic structures.
- Wall Mounted:Terminal unit applications including fan coil units and unit ventilators require compact form factors and quiet operation.
- Floor Mounted:Large valves and dampers in mechanical rooms and utility spaces accommodate higher torque requirements with accessible maintenance access.
- Integrated Systems:Factory-mounted actuator-damper or actuator-valve combinations from building automation specialists are capturing preference in Texas and Ontario new construction through consolidated vendor relationships.
Ceiling Mounted deployment dominates current commercial specification. Integrated Systems are expanding most quickly through bundled procurement preferences and compressed commissioning timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor concentrates the most intensive HVAC actuator specification activity, with F-Gas Regulation compliance accelerating retrofit demand across manufacturing clusters and commercial portfolios simultaneously.
United States
Virginia's hyperscale data center concentration drives modulating damper actuator procurement for airflow containment and PUE optimization. ASHRAE 90.1 energy codes tighten minimum efficiency requirements for damper and valve assemblies. The Pacific Northwest's cold-climate heat pump installations demand low-temperature torque-rated units for electrified heating systems.
Germany
Heat pump retrofits across the industrial corridor require proportional control actuators for precise thermal management under refrigerant phase-down mandates. The EU F-Gas Regulation forces OEMs to specify actuators compatible with lower-GWP refrigerant systems. Stuttgart and Munich manufacturing zones prioritize stainless steel gear trains for CO2 compatibility.
China
Dual carbon goals accelerate smart building automation deployment in Yangtze River Delta commercial real estate. GB standards and MIIT efficiency directives reshape equipment specification cycles. Shanghai and Shenzhen technology zones concentrate demand for BACnet-native electric actuators with embedded power monitoring.
Switzerland
Pharmaceutical cleanrooms in Basel and Zurich specify ultra-precise modulating valves for pressurization control. Swissmedic and national energy efficiency codes tighten certification burdens for HVAC components. The country's precision manufacturing ecosystem sustains premium actuator specification channels.
Singapore
Tropical data center cooling requirements drive demand for humidity-critical modulating control systems. The country's national building regulator mandates green building standards that compress specification cycles for smart actuators. Biomedical manufacturing clusters in Tuas require corrosion-resistant actuators for aggressive climate control environments.
HVAC Actuators Market Vendor Landscape
Premium-margin players sit above commodity-margin players across control sophistication tiers, with smart BACnet-native units capturing disproportionate value against on-off replacements. The supply base organizes into three layers: integrated building automation platforms, standalone precision specialists, and volume-scale component fabricators. Consolidation pressure intensifies as facility managers demand actuator-to-sensor bundled procurement. Geographic expansion and technology licensing represent the dominant competitive vectors.
Within the integrated platform tier, Schneider Electric SE and Siemens AG exemplify building automation consolidation through Desigo-style ecosystem control. Honeywell International occupies a position at the sensor-actuator convergence point for connected HVAC infrastructure. These three anchors demonstrate how specification-driven channels reward vertical capability depth over standalone component manufacturing.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Belimo |
| Honeywell International |
| Rotork Plc |
| Robert Bosch GmbH |
| Siemens AG |
| Danfoss |
| Sauter |
| Johnson Controls International PLC |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates qualified supply and premium-tier pricing access, as actuators compatible with lower-GWP refrigerant systems and CO2 heat pump architectures command specification premiums while commodity on-off units face margin compression from raw material volatility.
Pricing Analysis
Energy efficiency outcomes anchor value-based pricing for smart BACnet-native actuators with embedded power monitoring and demand-responsive capabilities, while commodity on-off units trade on per-unit transactional terms. Three-tier pricing structure across premium smart control, standard proportional, and economy on-off levels separates specification-driven pharmaceutical cleanroom projects from residential replacement cycles. Pricing pressure stems from rare earth magnet volatility in brushless DC motor assemblies and semiconductor input cost inflation, with smaller OEMs absorbing the steepest cost compression.
Supply Chain Analysis
Container freight rates from Chinese processing hubs to German industrial corridors and North American distribution centers directly influence landed cost structures for electric actuator assemblies. Manufacturing concentration in China, Germany, and the United States draws from neodymium and dysprosium rare earth dependencies, copper wiring harness inputs, and Taiwanese microcontroller sourcing. Single-source vulnerability in semiconductor foundry capacity represents the dominant structural risk, while distribution runs through building automation OEMs and specialized HVAC component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive sensor capabilities and in-house power monitoring chip design determine margin capture against bundled procurement demands from facility managers.
For Market Incumbents: Anchor specification-driven channels through IEC 62443 cybersecurity certification investment and backward integration into power monitoring semiconductor design. Wireless mesh protocol development defends against emerging battery-harvesting actuator specialists. Desigo-style ecosystem control over standalone component manufacturing preserves margin position. For New Entrants and Emerging Players: Building automation system integrators represent the most accessible channel partner type for bypassing incumbent specification lock-in. Pre-2000 commercial building stock in Chicago and Tokyo offers underpenetrated white-space for wireless retrofit solutions. Target pharmaceutical cleanroom humidity control applications where modulating valve precision commands premium positioning. For Investors and Strategic Acquirers: F-Gas Regulation refrigerant phase-down acceleration is the leading indicator that stainless steel gear train and CO2-compatible seal capabilities will concentrate acquisition value. Long-term viability favors vertically integrated platforms with sensor-actuator convergence over standalone component fabricators. Monitor California Title 24 and New York Local Law 97 enforcement velocity as grid-interactive building mandate inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Actuator Convergence | Honeywell International and Siemens AG capture bundled procurement preferences from facility managers consolidating vendor relationships. |
| Cybersecurity Certification Investment | IEC 62443 compliance extends development timelines but gates specification access in pharmaceutical and data center end-uses. |
| Wireless Mesh Protocol Development | Battery-harvesting topologies enable historic building retrofits in Boston and Vienna where conduit installation is architecturally invasive. |
| Backward Integration into Power Monitoring | In-house embedded chip design defends margin compression from Taiwanese foundry bottlenecks and semiconductor lead time volatility. |
| CO2 Refrigerant Compatibility Engineering | Stainless steel gear trains and specialized seals recalibrate torque ratings for German industrial corridor heat pump retrofits. |
Methodological Framework
Independent corroboration across HVAC OEM procurement directors, building automation system integrators, and facility management executives underwrites the qualitative findings. Primary fieldwork with plant engineers, aftermarket service heads, and OEM specification teams combined with secondary validation from ASHRAE 90.1 code filings, EU F-Gas Regulation implementation documents, and SEC 10-K equipment supplier disclosures. Bottom-up actuator shipment triangulation against top-down building automation market sizing anchors volume estimates.
Comparable historical reference periods spanning pre-pandemic baseline, supply disruption peak, and normalization phases anchored the forecast window across the projection horizon. Segmentation modeling incorporated product type, control technology tier, application end-use, and installation topology dimensions. CAGRs derived from regression analysis against energy code tightening velocity and refrigerant phase-down timelines, with heat pump electrification penetration and data center PUE optimization requirements as industry-specific demand inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration beyond current EU F-Gas Regulation timelines and breakthrough solid-state actuator technologies. Forecasts reflect documented assumptions about rare earth supply stabilization and semiconductor capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
France HVAC Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Global Split Systems Market