
 United Kingdom District Heating Market | 2026-2036
United Kingdom District Heating Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom District Heating Market Analytics
The residential sector is pivoting toward communal heat solutions as tower block retrofits accelerate across England's major cities. Vital Energi Utilities Ltd leverages its installed base of urban heat networks to sustain recurring maintenance revenue. Vattenfall Heat UK anchors large-scale low-carbon schemes in London's regeneration zones. ENGIE competes through integrated energy service contracts spanning design, build, and operation phases.
District heating comprises centralized heat generation plants distributing thermal energy via insulated pipe networks to multiple buildings, typically operating at flow temperatures between 70°C and 120°C depending on network age and insulation standard. The technology serves commercial and institutional clusters where load density justifies capital-intensive underground infrastructure. Heat pump technology leads new-build installations as operators phase out gas-fired plant ahead of building regulation tightening. Biomass occupies a niche in rural Scottish schemes with local fuel supply chains. Direct distribution channels dominate where utilities retain end-customer relationships, though third-party logistics providers are capturing metering and billing subcontracts.
Ofgem administers heat network regulation including consumer protection standards and zoning designation under the Energy Act 2023. The Heat Networks (Metering and Billing) Regulations enforce consumption-based charging, compelling operators to upgrade legacy unmetered systems. Building Regulations Part L and Future Homes Standard shape new construction specifications toward low-carbon heat. Stakeholders must monitor zoning rollouts and consumer price cap consultations to calibrate capital deployment timelines.
Market Dynamics
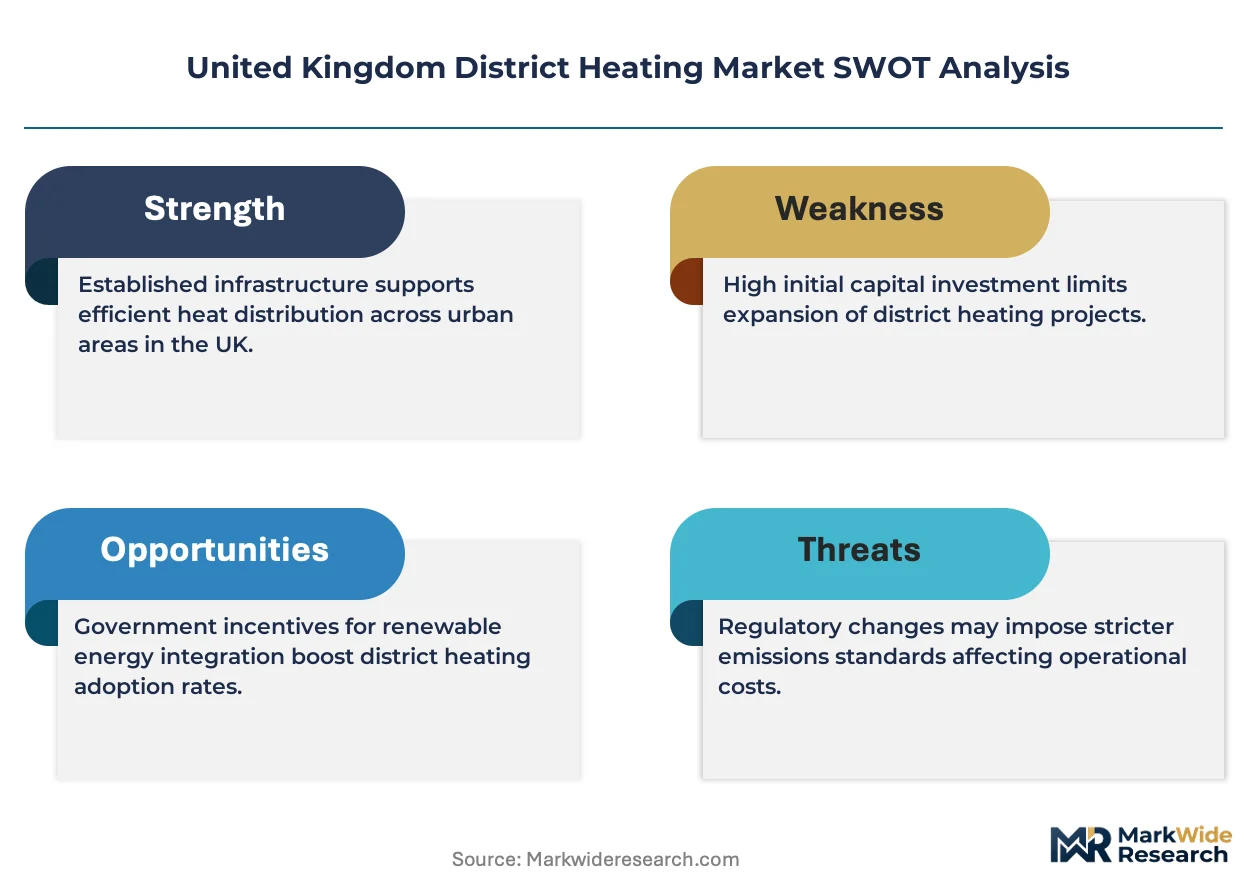
The Energy Act 2023's heat network zoning mandate is compressing capital deployment timelines across English cities. Operators must secure pipe routes before designation locks in local monopolies.
Growth Catalysts
- Heat Networks (Metering and Billing) Regulations:Consumption-based charging mandates are forcing landlords to replace unmetered legacy systems with compliant heat interface units.
- Fourth-generation heat networks:Ultra-low temperature distribution at 40-60°C is cutting heat losses and enabling heat pump integration in Scottish social housing retrofits.
- Urban regeneration clusters:London's Thamesmead and Manchester's Victoria North are anchoring large-scale low-carbon heat schemes with guaranteed anchor loads.
Market Restraints
- Steel and polymer pipe costs:Pre-insulated district heating pipe prices fluctuate with petrochemical feedstock volatility, squeezing project IRRs.
- Heat network zoning delays:Ofgem's designation timeline uncertainty is freezing land procurement decisions in Birmingham and Leeds.
- Gas boiler residual value:Existing building stock retains functional gas heating, creating substitution inertia among private landlords outside compliance zones.
Strategic Opportunities
- Wales and Northern Ireland heat networks:These territories show minimal penetration relative to England and Scotland, offering first-mover advantages in town center schemes.
- Data center waste heat recovery:Slough's hyperscale computing clusters are piloting heat export to adjacent residential developments.
- Green Heat Network Fund:BEIS capital grants covering up to 50% of construction costs are de-risking low-carbon generation investments for housing associations.
Industry Challenges
- Heat network engineering skills shortage:Chartered institution accreditation for thermal network design remains scarce, constraining project delivery capacity.
- Legacy system interoperability:Retrofitting 1970s tower block heating circuits with modern heat interface units requires bespoke hydraulic rebalancing.
- Consumer redress exposure:Ofgem's proposed price cap and compensation framework threatens operator margins in high-cost legacy zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom District Heating Market |
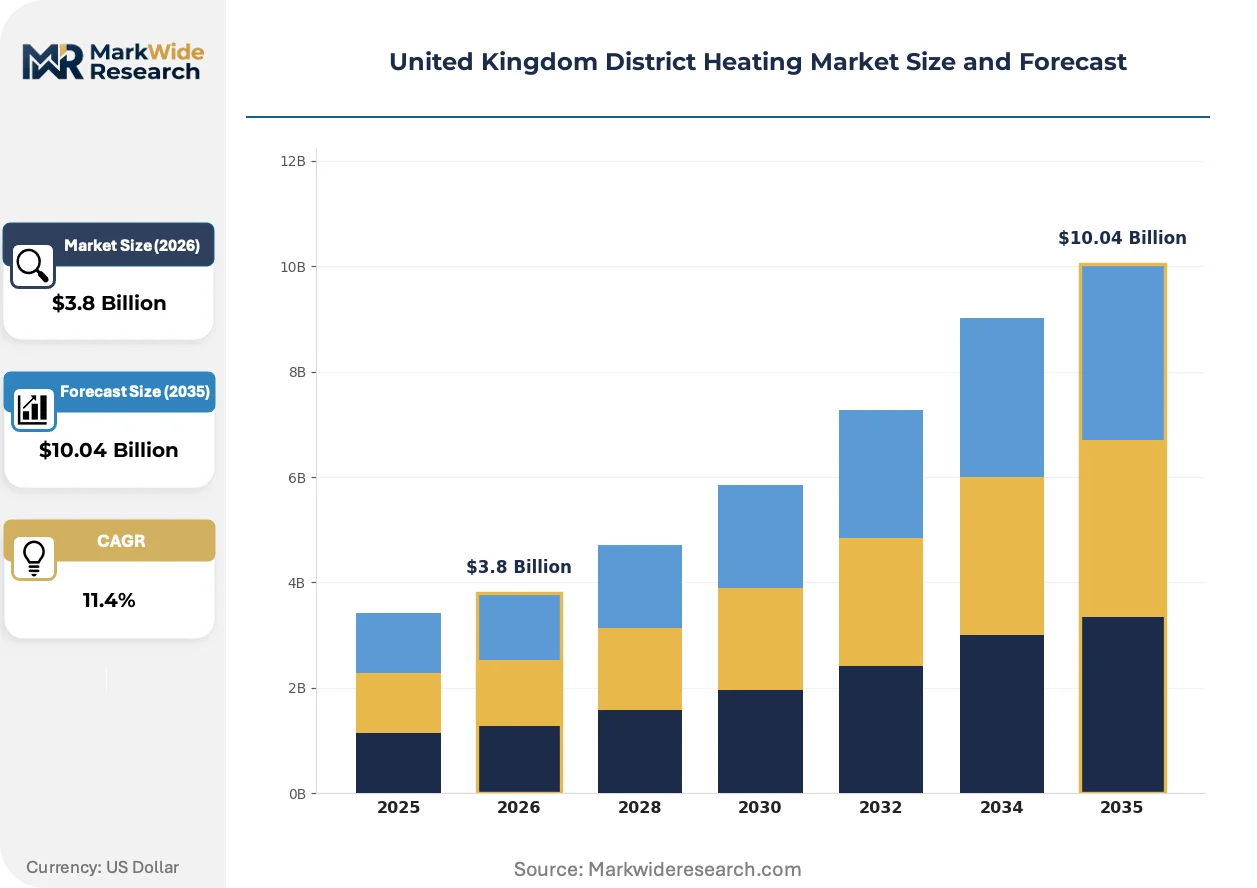
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electric Boilers, Gas Boilers, Heat Pumps, Biomass Distribution Channel: Direct Distribution, Third-Party Logistics, Public Sector, Private Sector End User: Residential, Commercial, Institutional, Industrial Application: Space Heating, Water Heating, Process Heating, District Cooling |
| Companies Covered | Vital Energi Utilities Ltd, 1 Energy Group Limited, Baxi Heating UK, Ramboll UK Limited, Veolia Environnement SA, Vattenfall Heat UK, Kensa Contracting, ENGIE, Danfoss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom District Heating Market Evolving Landscape
Heat network architecture is pivoting from centralized gas plant to distributed low-temperature loops. This shift demands new control systems, pipe specifications, and operator skill sets.
Heat pump technology is decentralizing thermal generation across United Kingdom networks. Large-scale air-source and water-source units are replacing gas-fired combined heat and power in new-build schemes. Housing associations in Bristol and Nottingham are deploying shared ground arrays serving 200+ dwellings each. This topology is compressing the dominance of single-point generation assets and enabling renewable electricity procurement.
The Energy Act 2023's zoning framework is mandating heat network readiness in designated areas. Local authorities must identify zones where district heating represents the lowest-cost decarbonization pathway. Developers in Cambridge and Oxford are pre-installing heat network infrastructure to avoid future retrofit costs. This regulatory pressure is accelerating standardization of connection protocols and metering specifications.
Resident engagement models are shifting from passive billing to active consumption feedback. Smartphone-enabled heat cost allocators are replacing opaque annual reconciliation charges. Social housing providers in Glasgow and Edinburgh are piloting real-time usage dashboards to drive behavioral efficiency. This transparency push is most visible in Scotland's Net Zero retrofit programs, where tenant buy-in determines scheme viability.
United Kingdom District Heating Market Segmentation
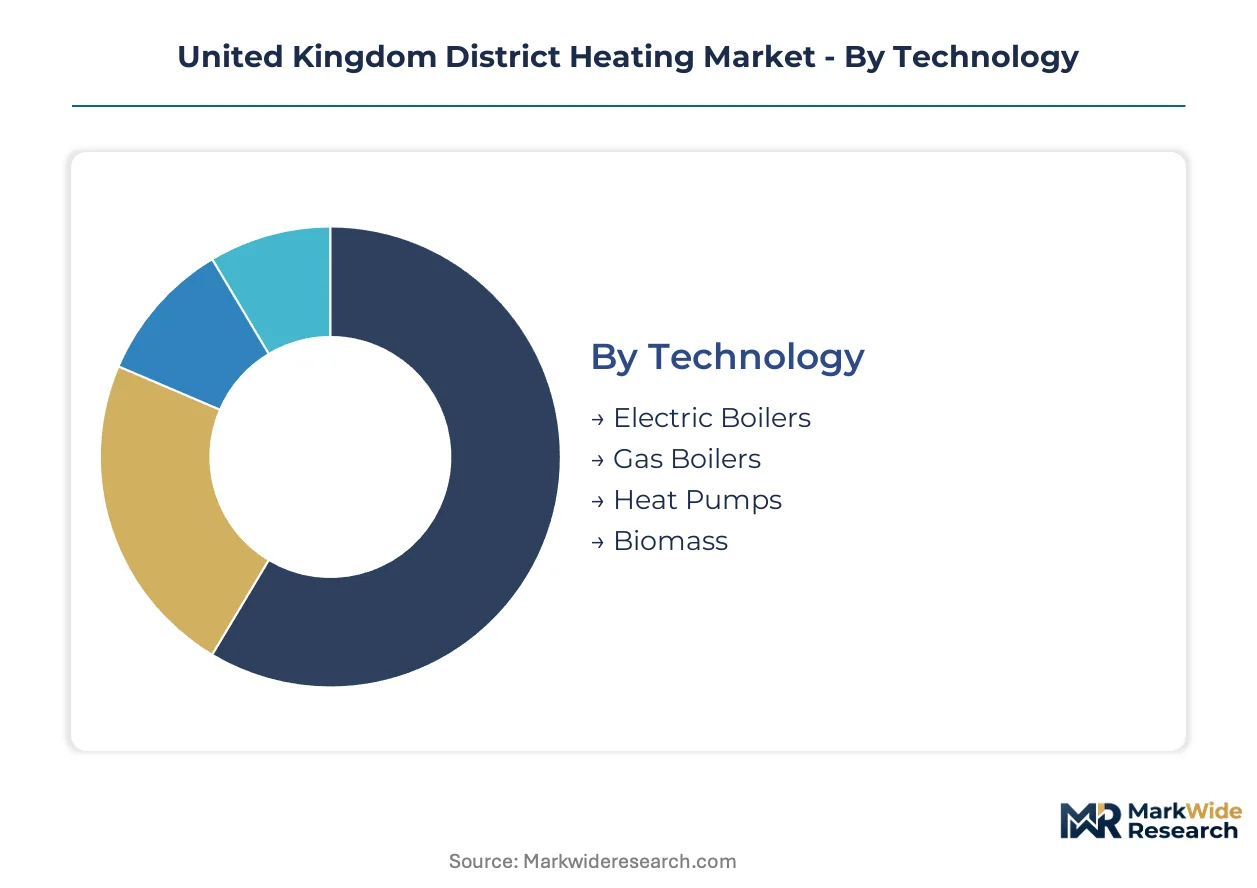
Technology choices in United Kingdom district heating determine regulatory compliance pathways and capital recovery timelines. Network operators must align segment selection with Ofgem's zoning designations and the Heat Networks (Metering and Billing) Regulations.
Technology:
Ofgem's consumer protection standards and building regulation tightening create divergent certification burdens across generation technologies. Heat pumps face Part L compliance scrutiny while biomass installations navigate local air quality permitting.
- Heat Pumps:Air-source and water-source units distribute thermal energy at 40-60°C flow temperatures, enabling fourth-generation low-temperature network architecture. Demand concentrates in Scottish social housing retrofits where Net Zero targets and Green Heat Network Fund grants de-risk capital deployment.
- Gas Boilers:Combined heat and power plant and condensing boilers remain prevalent in legacy networks, though operators face accelerating obsolescence risk from building regulation tightening. Manchester and London regeneration zones are phasing out gas-fired plant ahead of zoning mandates.
- Electric Boilers:Resistance heating serves peak-load backup and emergency redundancy in hybrid configurations.
- Biomass:Wood pellet and chip systems occupy rural Scottish schemes with established local fuel supply chains.
Leading the category by volume: Gas Boilers. Growing fastest: Heat Pumps.
Distribution Channel:
Channel structure determines margin capture and customer relationship ownership across England, Scotland, and Wales.
- Direct Distribution:Utility-operated networks retain end-customer billing relationships and maintenance revenue streams. London's Thamesmead and Manchester's Victoria North anchor schemes demonstrate this model's scale economics.
- Public Sector:Local authority and housing association procurement channels dominate Scotland's social housing estate retrofits.
- Third-Party Logistics:Metering and billing subcontractors are capturing service layers previously held by network operators.
- Private Sector:Commercial developers in Cambridge and Oxford pre-install infrastructure to avoid future compliance costs.
Dominant by contract value: Direct Distribution. Expanding most quickly: Third-Party Logistics.
End User:
Load density and consumption predictability shape network viability across customer types.
- Residential:Tower blocks in London and Manchester generate concentrated thermal demand with guaranteed anchor loads. Scotland's social housing estates drive retrofit program volume under Net Zero commitments.
- Commercial:Office clusters and retail parks in urban regeneration zones provide stable daytime baseload.
- Institutional:Universities and hospitals in Bristol and Nottingham anchor large-scale shared ground array deployments.
- Industrial:Process heat requirements in manufacturing clusters remain underserved by current network topology.
Maximum installed capacity: Residential. Steepest expansion trajectory: Institutional.
Application:
Seasonal load profiles and temperature requirements dictate network design specifications.
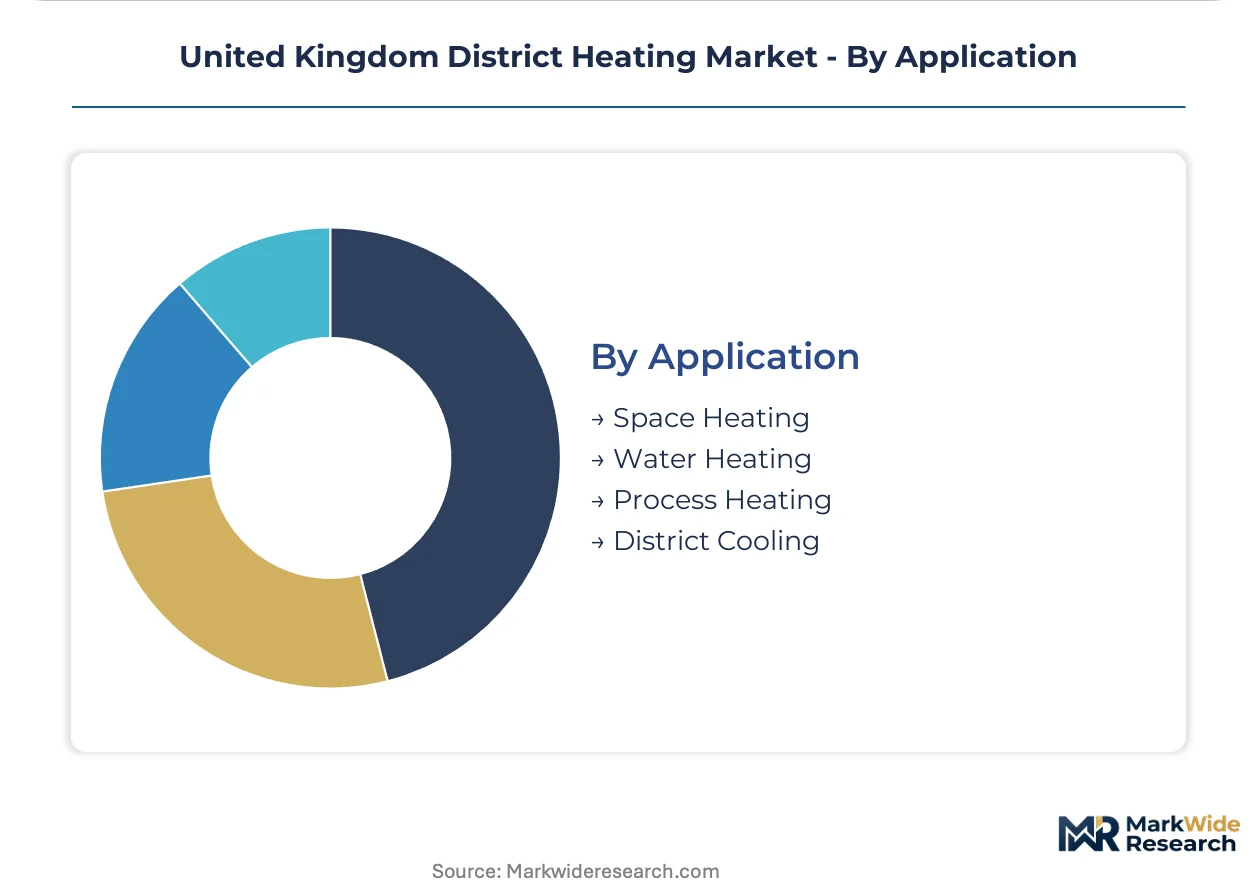
- Space Heating:Seasonal demand peaking in winter months drives network sizing and storage requirements. Glasgow and Edinburgh social housing providers pilot real-time usage dashboards to drive behavioral efficiency.
- Water Heating:Year-round baseload improves network utilization factors and project economics.
- Process Heating:Industrial temperature requirements exceed standard district heating flow temperatures.
- District Cooling:Absorption chilling and heat-driven cooling extend network utilization into summer months.
Highest revenue concentration: Space Heating. Gaining share fastest: District Cooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generation capacity concentrates in Scotland's central belt while consumption gravity pulls toward England's southeastern corridor. Network infrastructure investment flows disproportionately to urban regeneration zones where zoning mandates under the Energy Act 2023 compress deployment timelines.
London and Southeast England
Tower block retrofits across Tower Hamlets and Southwark generate concentrated thermal demand with guaranteed anchor loads. The Heat Networks (Metering and Billing) Regulations enforce consumption-based charging, compelling housing associations to upgrade legacy unmetered systems. Thamesmead regeneration anchors large-scale low-carbon heat schemes with integrated heat pump generation.
Scotland
Social housing estates in Glasgow and Edinburgh drive retrofit program volume under Net Zero targets and Green Heat Network Fund grants. Fourth-generation ultra-low temperature networks at 40-60°C flow temperatures cut heat losses and enable heat pump integration. Scottish housing associations pilot real-time usage dashboards to secure tenant buy-in for scheme viability.
North England
Manchester's Victoria North regeneration zone anchors municipal heat network expansion with guaranteed commercial baseload. Ofgem's zoning designation timeline uncertainty freezes land procurement decisions in Leeds and Birmingham. Local authorities pre-install heat network infrastructure to avoid future compliance costs under pending zoning mandates.
Wales
Town center schemes show minimal penetration relative to England and Scotland, offering first-mover advantages for utility operators. The Welsh Government's retrofit programs lack the capital intensity of Scotland's social housing estates. Cardiff and Newport present concentrated demand clusters where direct distribution channels retain end-customer relationships.
Northern Ireland
Heat network infrastructure remains embryonic compared to Great Britain's urban corridors. Belfast's housing stock lacks the tower block density that justifies capital-intensive underground pipe networks in English cities. Local fuel supply chains for biomass occupy niche rural applications without scaling potential.
United Kingdom District Heating Market Competitive Landscape
Top-tier vendors anchor large-scale regeneration schemes, while mid-tier specialists capture metering and billing subcontracts. The vendor base stratifies across integrated energy service providers, utility-scale network operators, and component fabricators. Two archetypes dominate: vertically integrated design-build-operate contractors and technology-agnostic infrastructure funds. Competitive moves concentrate on pre-zoning land procurement and heat interface unit standardization.
Among UK-based network operators, Vital Energi Utilities Ltd and Vattenfall Heat UK exemplify the integrated utility archetype, while ENGIE occupies a position spanning energy service contracting and infrastructure ownership. Kensa Contracting represents the specialist tier focused on shared ground array deployment. These three anchors illustrate how competitive positioning diverges between scale-driven regeneration plays and technology-specific retrofit specialists.
| Leading Market Players |
|---|
| Vital Energi Utilities Ltd |
| 1 Energy Group Limited |
| Baxi Heating UK |
| Ramboll UK Limited |
| Veolia Environnement SA |
| Vattenfall Heat UK |
| Kensa Contracting |
| ENGIE |
| Danfoss |
| Others |
Value Network & Pricing Analysis
Steel futures volatility on the London Metal Exchange cascades through pre-insulated pipe manufacturing into three-tier pricing structure across premium, standard, and economy levels for United Kingdom district heating infrastructure. Housing associations in Scotland's Net Zero retrofit programs absorb premium-tier costs for fourth-generation low-temperature networks, while English landlords facing Heat Networks (Metering and Billing) Regulations compliance deadlines default to standard-tier heat interface units.
Pricing Analysis
Margin tightening in standard-tier equipment reflects petrochemical feedstock volatility squeezing polymer pipe suppliers. Three-tier pricing structure across premium, standard, and economy levels separates fourth-generation heat pump-ready networks from legacy gas-fired retrofits and basic compliance-grade metering installations. Price differentiation hinges on certification grade under Ofgem consumer protection standards and after-sales service bundling. Housing associations demonstrate highest price sensitivity due to Green Heat Network Fund grant dependency, while institutional anchor loads in London regeneration zones show lowest sensitivity.
Supply Chain Analysis
Direct-to-utility channels handle large-scale regeneration zone procurement across England and Scotland. Manufacturing concentrates in Germany, Denmark, and Poland for pre-insulated steel and polymer pipe systems. Raw material dependencies include steel coil, polyurethane foam insulation, and corrosion-resistant jacketing. Supply chain risk centers on single-source vulnerability for specialized heat interface unit controllers. Distribution runs through utility-operated networks retaining end-customer relationships, with third-party logistics providers capturing metering and billing subcontracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom district heating market is consolidating around operators with pre-zoning land positions and Ofgem-compliant metering infrastructure, as regulatory compliance costs force sub-scale landlords toward asset sales.
For Market Incumbents: Deploy heat interface unit standardization to lock in recurring maintenance revenue streams across London and Manchester tower block portfolios. Deepen backward integration into pipe route procurement ahead of Energy Act 2023 zoning designations freezing competitive entry. Counter emerging technology-agnostic infrastructure funds by anchoring large-scale regeneration schemes with guaranteed anchor loads. For New Entrants and Emerging Players: Capture Wales and Northern Ireland town center schemes where heat network penetration lags England and Scotland. Target social housing retrofit procurement channels in Cardiff and Newport where direct distribution channels retain end-customer relationships. Enter through shared ground array specialization serving 200-plus dwelling clusters, mirroring Kensa Contracting's proven deployment model. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier metering and billing specialists in Scotland facing consumer redress exposure from Ofgem's proposed price cap framework. Long-term viability across the five-to-ten year window rests on zoning mandate execution velocity and heat pump technology cost curves. Watch Green Heat Network Fund allocation exhaustion as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Zoning Land Procurement | Secures pipe routes before Energy Act 2023 designations freeze competitive entry in English cities. |
| Heat Interface Unit Standardization | Enables recurring maintenance revenue capture across unmetered legacy system upgrade cycles. |
| Shared Ground Array Deployment | Compresses single-point generation dominance through distributed heat pump topology in social housing. |
| Third-Party Logistics Partnership | Captures metering and billing service layers previously retained by utility-operated networks. |
| Green Heat Network Fund Utilization | De-risks low-carbon generation investments for housing associations under Net Zero commitments. |
Research Methodology
Independent corroboration across network operator engineering directors, housing association procurement leads, Ofgem policy officials, and heat pump system integrators underwrites the qualitative findings. Primary interviews with utility planning officers, EPC contractors, and district heating engineering specialists combined with secondary validation from BEIS policy documents, Ofgem consumer protection standards filings, and Green Heat Network Fund allocation records. Bottom-up project pipeline enumeration triangulates against top-down regulatory mandate sizing.
Rate-of-change decomposition separates flow temperature technology transitions, zoning designation sequencing, and retrofit program acceleration across the projection horizon. Segmentation dimensions modeled include generation technology, distribution channel ownership, end-user load density, and application temperature requirements. CAGRs derive from project-level capital deployment tracking and regulatory compliance timeline phasing. Heat network engineering skills shortage constraints and biomass fuel supply chain maturity serve as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ofgem zoning designation delays and steel futures volatility. Forecasts reflect documented assumptions regarding Energy Act 2023 implementation velocity and Green Heat Network Fund renewal probability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Air Conditioning Compressor Market