
 Louver Dampers Market | 2026-2036
Louver Dampers Market Size, Share, and Industry Trends Forecast 2026-2036
Louver Dampers Market Insights
Skilled welder availability for alloy blade fabrication is collapsing across the industrial ventilation supply base, forcing OEMs to automate seam welding or outsource to certified pressure-vessel shops. Greenheck Fan Corporation leverages captive foundry capacity to control stainless steel blade lead times. Johnson Controls sustains specification dominance through deep integration with building automation protocols. Ruskin Company specializes in coastal-corrosion-resistant coatings for offshore and marine exhaust applications.
Louver dampers are flow-modulation devices consisting of parallel or opposed blades mounted on a common shaft within a duct frame, typically fabricated from galvanized steel or extruded aluminum with elastomer or metal edge seals rated for temperatures from ambient to over 1000°F in industrial service; they regulate airflow volume, pressure, or direction in HVAC, process exhaust, and combustion air systems. Motorized actuation commands the specification premium in commercial and industrial portfolios where remote damper positioning ties to BAS and fire-life-safety networks. Steel construction anchors heavy-industrial demand where thermal cycling and particulate loading degrade lighter alloys. Smoke control applications represent the fastest-growing specification segment as building codes mandate compartmentalization in high-rise and atrium designs.
ASHRAE Standard 90.1, NFPA 92 smoke control requirements, and EPA Maximum Achievable Control Technology rules collectively dictate blade leakage ratings, actuator response times, and materials of construction across the installed base. The Department of Energy fan efficiency regulations are extending to damper-induced system pressure losses, reshaping aerodynamic blade profile R&D priorities. Stakeholders must monitor how evolving carbon border adjustments and domestic content incentives recalibrate sourcing economics for extruded aluminum and cast actuator housings.
Market Dynamics
EPA Maximum Achievable Control Technology rules and ASHRAE Standard 90.1 are compressing blade leakage tolerances and forcing alloy upgrades across the installed base, while skilled welder shortages for stainless fabrication concentrate supply risk in certified pressure-vessel shops.
Growth Catalysts
- NFPA 92 smoke control mandates:High-rise compartmentalization requirements in United States building codes are expanding specification volume for fire-rated louver dampers with rapid-actuation protocols.
- Power generation retrofit cycles:United States utility operators are replacing legacy dampers in coal and gas turbine exhaust systems to manage corrosive flue gas streams and optimize draft control.
- Stainless steel blade fabrication:Captive foundry investments by dominant OEMs are stabilizing lead times for corrosion-resistant alloys in marine and wastewater treatment applications.
Market Restraints
- Alloy input cost volatility:Nickel and molybdenum price swings in commodity markets compress margin predictability for stainless steel blade production.
- Welder certification concentration:ASME Section IX certified welders cluster in Great Lakes and Gulf Coast industrial corridors, creating geographic supply bottlenecks.
- Actuator integration complexity:Legacy pneumatic systems in heavy industrial plants resist seamless retrofit to BAS-compatible electric actuation without full duct section replacement.
Strategic Opportunities
- India industrial infrastructure buildout:Central Electricity Authority thermal plant expansions and BIS ventilation code adoption are opening specification channels for heavy-duty dampers in power and cement sectors.
- Carbon border adjustment mechanics:European Union CBAM implementation is incentivizing regional extruded aluminum sourcing and captive melting capacity investments.
- Digital twin convergence:Integration of damper position feedback with predictive maintenance platforms creates aftermarket service attach rates in commercial building portfolios.
Industry Challenges
- Multi-protocol actuator programming:BAS integration teams must reconcile BACnet, Modbus, and proprietary Johnson Controls protocol stacks within single fire-life-safety networks.
- Coastal coating certification timelines:NORSOK M-501 and ISO 12944 C5-M qualification cycles for offshore marine dampers extend product launch schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Louver Dampers Market |
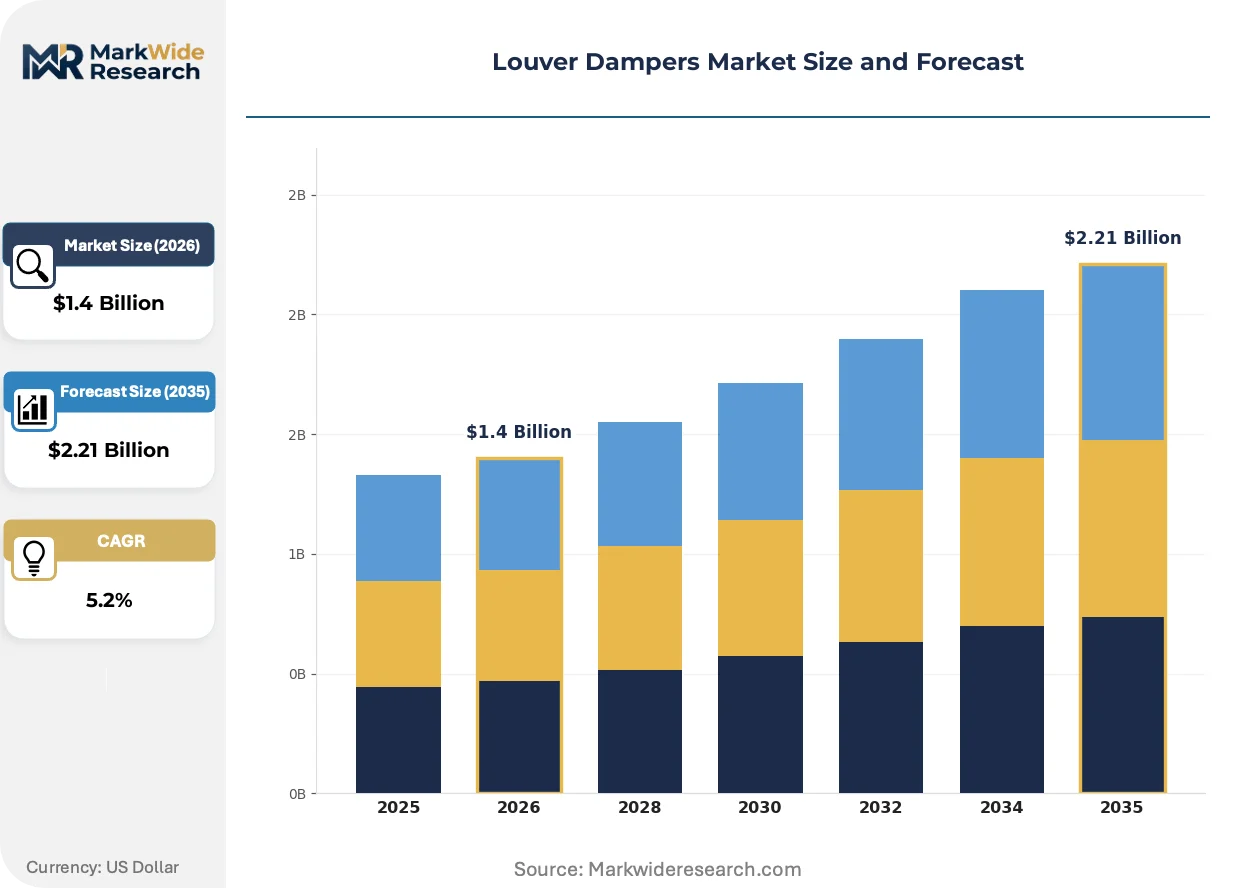
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Motorized, Manual, Fixed, Adjustable Material: Aluminum, Steel, Plastic, PVC Application: HVAC Systems, Exhaust Ventilation, Airflow Control, Smoke Control End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Greenheck Fan Corporation, Johnson Controls, Ruskin Company, TROX, FläktGroup, Systemair AB, Nailor Industries, Halton Group, Swegon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Louver Dampers Market Trends and Innovations
Actuator miniaturization and edge-computing integration are redefining how damper position data flows into building automation and predictive maintenance architectures.
Aerodynamic blade profiling is fragmenting the specification landscape. Computational fluid dynamics-optimized airfoil sections reduce system pressure losses by reshaping laminar flow patterns across blade arrays. Data center operators in Northern Virginia and Phoenix are specifying these profiles to meet Department of Energy fan efficiency regulations. The technology is fragmenting procurement decisions by separating premium CFD-optimized dampers from legacy flat-blade alternatives in performance-critical segments.
REACH restrictions on hexavalent chromium coatings are forcing conversion to trivalent chrome and zinc-nickel alternatives for corrosion protection. European damper fabricators must reformulate surface treatment lines to maintain CE marking compliance for industrial exhaust applications. German and Dutch HVAC contractors are now demanding coating certificates traceable to ECHA substance of very high concern screening.
Integrated specification purchasing is consolidating vendor relationships in commercial real estate portfolios. Facility managers at Blackstone and Brookfield properties are bundling damper, actuator, and controls procurement under single-source agreements with extended warranty terms. This behavior concentrates most visibly in United States Class A office retrofits where LEED certification drives coordinated mechanical system upgrades.
Louver Dampers Market Segmentation
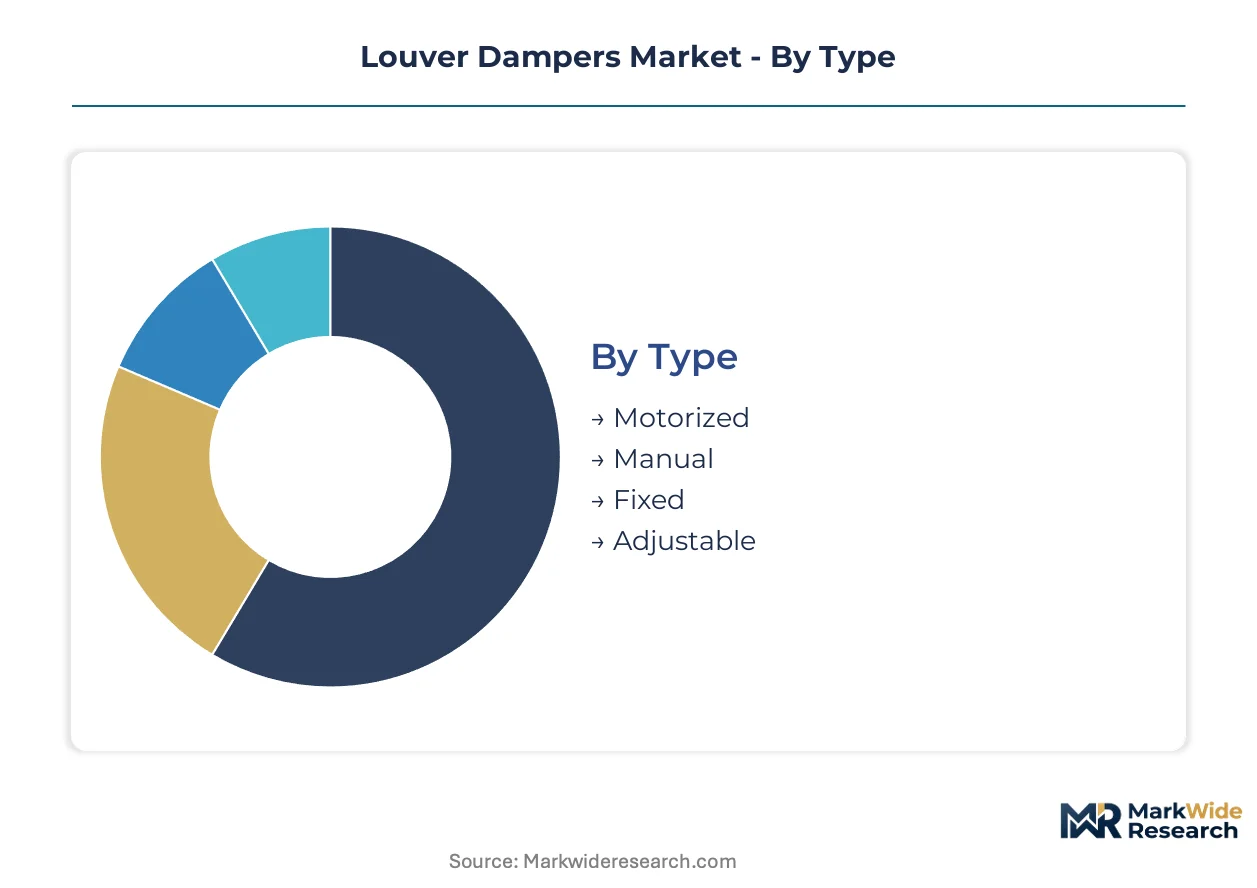
Louver damper procurement splits sharply across actuation methods, material specifications, and regulatory compliance tiers. Specification engineers weight smoke control certification and BAS integration compatibility as primary selection filters in commercial and industrial portfolios.
Type:
Motorized dampers command the widest margin pools across this category, driven by actuator integration complexity and fire-life-safety network compatibility requirements.
- Motorized:Electric or pneumatic actuation enables remote positioning through building automation systems. Demand concentrates in United States high-rise commercial retrofits where NFPA 92 mandates rapid-actuation smoke control protocols tied to fire alarm networks.
- Manual:Hand-operated quadrant or chain-wheel positioning suits isolated duct sections without BAS connectivity. Wastewater treatment facilities in the Gulf Coast specify these for periodic maintenance access where automated response is unnecessary.
- Fixed:Non-adjustable blade arrays provide constant airflow resistance for passive ventilation balance. Data center operators in Northern Virginia deploy fixed configurations in redundant air handler arrays where variable modulation adds failure points.
- Adjustable:Multi-position mechanical stops allow field calibration without powered actuation. Industrial boiler rooms in Ohio and Pennsylvania favor adjustable dampers for combustion air trim where precise but infrequent tuning suffices.
Motorized dampers hold installed capacity. Adjustable configurations are rotating up the share rankings in cost-sensitive industrial retrofits.
Material:
Material selection tracks thermal cycling severity and coastal corrosion exposure, with alloy grades separating premium specification tiers from commodity procurement.
- Aluminum:Extruded 6061-T6 or 6063-T5 profiles deliver weight advantages and corrosion resistance in coastal HVAC applications. European Union CBAM implementation is incentivizing regional sourcing and captive melting capacity investments for extruded aluminum supply security.
- Steel:Galvanized or stainless fabrication anchors heavy-industrial demand where temperatures exceed 500°F and particulate loading degrades lighter alloys. Power generation exhaust systems in Texas and Arizona specify 316L stainless for flue gas corrosion resistance.
- Plastic:Glass-reinforced polymer construction suits corrosive fume exhaust in semiconductor and chemical process environments. Cleanroom facilities in Oregon and New Mexico specify plastic dampers for etching and deposition tool ventilation.
- PVC:Rigid polyvinyl chloride offers chemical resistance at ambient temperatures for laboratory and light industrial fume handling. University research buildings in Massachusetts and California deploy PVC dampers in fume hood exhaust stacks.
Steel dominates heavy-industrial specification volume. Aluminum is climbing fastest in commercial HVAC replacement cycles.
Application:
Application segmentation reflects divergent certification burdens, with fire-rated smoke control commanding specification premiums against standard airflow modulation.
- HVAC Systems:Temperature and volume control in commercial building air distribution networks. ASHRAE Standard 90.1 compliance drives blade leakage rating upgrades in United States Class A office retrofits.
- Exhaust Ventilation:Process fume and heat removal in industrial and laboratory environments. EPA Maximum Achievable Control Technology rules mandate corrosion-resistant construction in chemical and power generation facilities.
- Airflow Control:Pressure balancing and draft optimization in combustion and process systems. Coal and gas turbine operators in West Virginia and Louisiana replace legacy dampers to manage corrosive flue gas streams.
- Smoke Control:Compartmentalization and exhaust evacuation in fire-life-safety networks. Building codes in Illinois and Florida mandate fire-rated louver dampers with rapid-actuation protocols for high-rise and atrium designs.
HVAC Systems anchor baseline procurement volume. Smoke Control is expanding most quickly as code adoption tightens across United States jurisdictions.
End User:
End user segmentation tracks capital intensity and specification authority, with industrial and government procurement subject to stringent domestic content and certified fabrication requirements.
- Residential:Single-family and multifamily ventilation in new construction and renovation. Production homebuilders in Florida and Texas specify manual aluminum dampers for cost-sensitive attic and crawlspace ventilation.
- Commercial:Office, retail, hospitality, and institutional building mechanical systems. Integrated specification purchasing by Blackstone and Brookfield property managers bundles damper, actuator, and controls procurement under single-source agreements.
- Industrial:Power generation, manufacturing, wastewater treatment, and process exhaust applications. Skilled welder shortages for ASME Section IX certified stainless fabrication concentrate supply risk in Great Lakes and Gulf Coast industrial corridors.
- Government:Federal, state, and municipal infrastructure including military, correctional, and public utility facilities. Federal infrastructure spending channels investment toward heavy-duty industrial damper replacements in United States utility retrofit cycles.
Industrial end users command specification authority for corrosion-resistant alloys. Commercial portfolios are consolidating vendor relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and ASHRAE ventilation codes anchor procurement intensity in the United States, while European REACH restrictions and Asian infrastructure buildouts reshape alloy sourcing and specification patterns across major industrial corridors.
United States
Utility retrofit cycles and federal infrastructure spending drive heavy-duty damper replacement demand. NFPA 92 smoke control mandates tighten compartmentalization requirements in high-rise commercial buildings. Industrial clusters in Texas and Arizona specify 316L stainless steel for flue gas corrosion resistance in power generation exhaust systems.
Germany
Data center operators in Frankfurt and Berlin specify CFD-optimized blade profiles to meet fan efficiency regulations. REACH restrictions on hexavalent chromium coatings force conversion to trivalent chrome alternatives for CE marking compliance. German HVAC contractors now demand coating certificates traceable to ECHA substance of very high concern screening.
China
Thermal plant expansions under central electricity authority planning open specification channels for heavy-duty dampers. GB standards and MIIT industrial ventilation codes align with international blade leakage rating benchmarks. Manufacturing clusters in Jiangsu and Shandong provinces concentrate extruded aluminum fabrication capacity for regional supply security.
India
Central Electricity Authority thermal plant expansions and BIS ventilation code adoption create demand in power and cement sectors. Skilled welder shortages concentrate supply risk in certified fabrication shops near Mumbai and Chennai. Domestic infrastructure buildout favors adjustable damper configurations in cost-sensitive industrial retrofits.
United Arab Emirates
Coastal corrosion exposure in Dubai and Abu Dhabi drives specification of marine-grade coatings and aluminum alloys. Federal building codes adopt NFPA-equivalent smoke control standards for high-rise developments. Desalination and wastewater treatment facilities expand procurement for managing corrosive exhaust streams.
Louver Dampers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry capacity and automation investments separating premium-positioned OEMs from regional fabricators. The structure rewards backward integration into stainless steel blade production and deep building automation protocol integration. Two strategic archetypes dominate: vertically integrated HVAC conglomerates with captive alloy supply, and coastal-corrosion specialists with certified marine coating capabilities. Competitive moves concentrate on actuator-BAS integration partnerships and automated seam welding capacity expansion to offset skilled welder shortages.
Among North American fabricators, Greenheck Fan Corporation exemplifies the integrated archetype through captive foundry investments, while Johnson Controls anchors the building automation convergence tier. Ruskin Company occupies a specialist position within coastal-corrosion-resistant applications. These three represent the dominant competitive positioning vectors: upstream supply control, digital integration depth, and niche environmental certification.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| Johnson Controls |
| Ruskin Company |
| TROX |
| FläktGroup |
| Systemair AB |
| Nailor Industries |
| Halton Group |
| Swegon |
| Others |
Pricing and Supply Chain Analysis
Aluminum-for-steel substitution in coastal HVAC specifications simultaneously redraws sourcing maps toward Jiangsu and Shandong extrusion clusters and compresses margin pools for legacy carbon-steel fabricators serving inland commercial retrofits. This materials pivot concentrates pricing power with OEMs holding captive melting capacity while fragmenting procurement economics across alloy-grade tiers.
Pricing Analysis
Geographic price spreads widen between Gulf Coast industrial corridors and Midwest commercial markets, with 316L stainless steel dampers commanding premiums against galvanized alternatives. Three-tier pricing structure across premium CFD-optimized, standard fire-rated, and economy manual configurations separates specification tiers. Cost compression in economy segments intensifies because of nickel and molybdenum commodity volatility. Wastewater treatment procurement teams exhibit highest price sensitivity, while data center operators prioritize aerodynamic performance over unit cost.
Supply Chain Analysis
Inventory lead times for ASME Section IX certified stainless fabrication stretch across Great Lakes and Gulf Coast industrial corridors where welder certification bottlenecks concentrate. Supply geography anchors in the United States, Germany, and China for extruded aluminum and actuator components. Raw material flows draw from nickel ore processing, molybdenum concentrate refining, and elastomer seal compound production. Single-source vulnerability in certified pressure-vessel welding capacity threatens delivery reliability. Distribution runs through OEM direct sales for industrial projects and HVAC wholesale channels for commercial replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across smoke control, marine corrosion, and digital integration niches creates entry points for specialists as building codes and industrial emissions rules multiply certification requirements.
For Market Incumbents: Shield specification authority by securing captive foundry capacity for 316L and 2205 duplex stainless grades before nickel price volatility destabilizes competitor cost structures. Deepen BAS protocol integration through BACnet and Modbus certification investments to lock out actuator retrofit competitors. Prioritize automated seam welding capacity expansion to offset ASME Section IX welder shortages threatening delivery commitments. For New Entrants and Emerging Players: Lead with marine-grade coating certification as the most penetrable white space, where NORSOK M-501 and ISO 12944 C5-M qualification cycles extend incumbent product launch schedules by 18-24 months. Target India's Central Electricity Authority thermal plant expansions where BIS ventilation code adoption lags specification expertise. Deploy digital twin integration as the primary go-to-market angle for predictive maintenance service contracts in commercial building portfolios. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated HVAC conglomerates with captive alloy supply and certified marine coating capabilities. Long-term viability hinges on backward integration into stainless blade production and automation investments that neutralize skilled welder scarcity. Watch carbon border adjustment implementation timelines as the critical inflection signal for regional extruded aluminum sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Investment | Greenheck's stainless blade capacity insulates against nickel volatility and welder shortages. |
| BAS Protocol Integration | Johnson Controls leverages building automation convergence to lock specification dominance. |
| Marine Coating Certification | Ruskin's NORSOK M-501 qualification creates 18-24 month barriers for offshore competitors. |
| Automated Seam Welding | OEM automation offsets ASME Section IX welder concentration in Gulf Coast corridors. |
| Digital Twin Convergence | Damper position feedback integration opens predictive maintenance aftermarket attach rates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA MACT filings, ASHRAE Standard 90.1 documentation, and utility procurement databases. Primary interviews engaged specification engineers at power generation operators, BAS integration contractors, and HVAC wholesale distributors. Secondary validation drew from FERC infrastructure spending disclosures, NFPA 92 code adoption tracking, and customs data on extruded aluminum trade flows. Bottom-up damper shipment analysis triangulates against top-down construction spending and industrial ventilation equipment forecasts.
Segmentation dimensions modeled span actuation method, material specification grade, application compliance tier, and end-user capital intensity across the projection horizon. CAGRs derive from regression against utility retrofit cycle timing, federal infrastructure appropriation trajectories, and building code adoption curves. Industry-specific inputs include welder certification capacity by census region and nickel futures price correlation with stainless steel damper procurement delays.
Forecasts assume regulatory continuity in EPA emissions enforcement and ASHRAE ventilation code adoption; material policy shifts would require re-modeling. Nickel and molybdenum commodity volatility, skilled welder availability shocks, and carbon border adjustment implementation pace constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Warming Cabinet Market