
 Kitchen Hood Market | 2026-2036
Kitchen Hood Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Hood Market Outlook
Stainless steel is rebalancing toward coated cold-rolled alternatives and composite resin panels as manufacturers seek weight reduction and acoustic dampening without sacrificing corrosion resistance. BSH Home Appliances leverages captive motor production in Germany to sustain margin control across its premium chimney lines. Elica S.P.A anchors its competitive stance through deep specialization in island hood architectures for open-plan residential layouts. Faber S.P.A competes on manufacturing scale, operating integrated stamping and enameling facilities that supply multiple OEM brands across Southern Europe.
A kitchen hood is a mechanical ventilation appliance designed to capture, filter, and exhaust airborne grease, combustion products, smoke, odors, heat, and steam from cooking surfaces, typically achieving capture efficiencies of 70-90% at specified airflow rates measured in cubic feet per minute. Wall-mounted units dominate volume in retrofit applications where existing cabinetry constrains installation geometry, while island configurations command premium positioning due to ducting complexity and aesthetic visibility requirements. Ducted technology leads in markets with established building ventilation infrastructure, whereas ductless variants with charcoal filtration stages are displacing conventional configurations in dense urban apartments where external venting is structurally impractical.
The US Department of Energy enforces minimum efficiency standards for residential range hoods, while the EU Ecodesign Directive mandates maximum power consumption thresholds and noise limits that manufacturers must certify through notified bodies. China's GB standards for household electrical appliances specify safety and performance benchmarks enforced by SAMR market surveillance protocols. Stakeholders must monitor evolving interoperability standards between hood controllers and broader kitchen automation ecosystems, as platform exclusivity risks fragmenting replacement part availability and service access across installed bases.
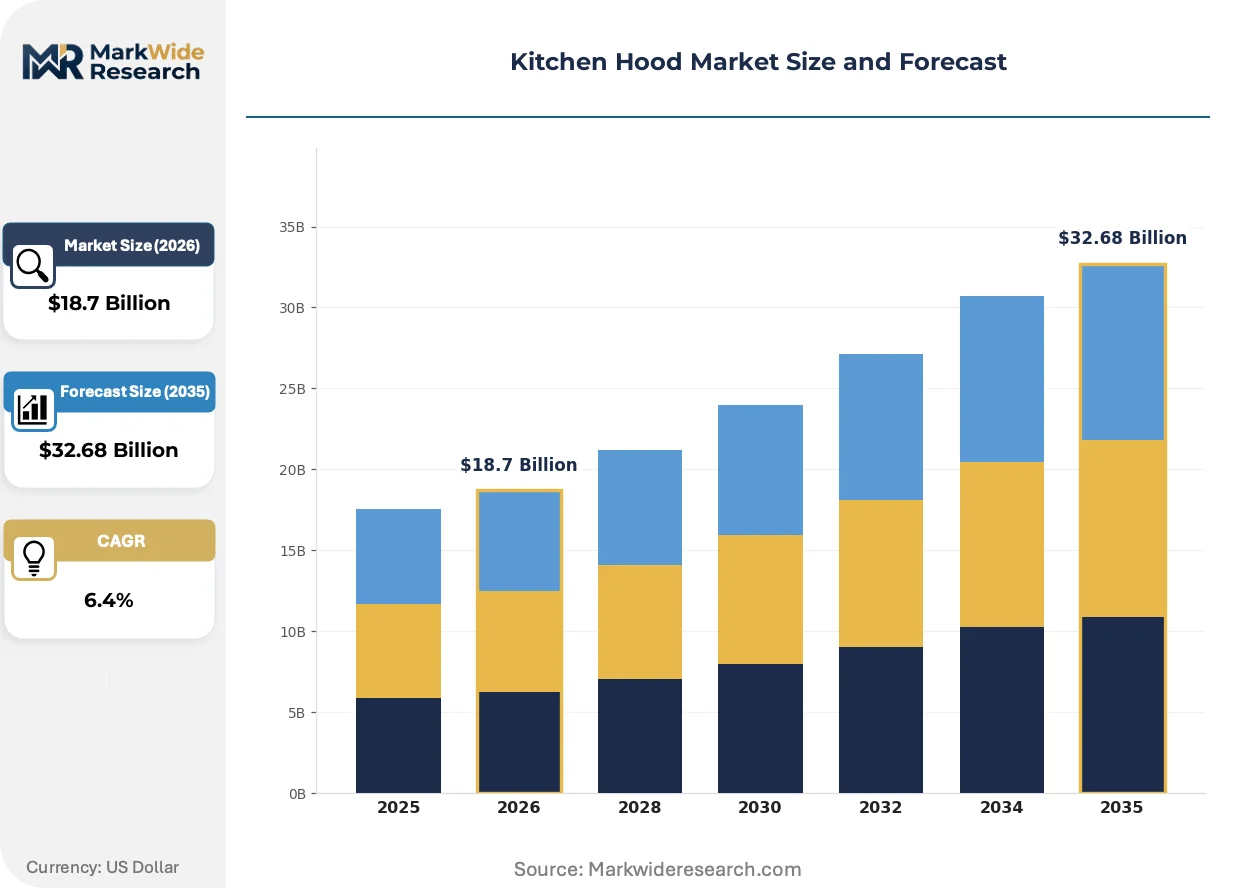
Market Dynamics
Brushless DC motor platforms are forcing wholesale redesign of kitchen hood architectures as US DOE efficiency standards and EU Ecodesign Directive thresholds tighten simultaneously, compressing legacy AC motor supply chains and rewarding captive motor production.
Growth Catalysts
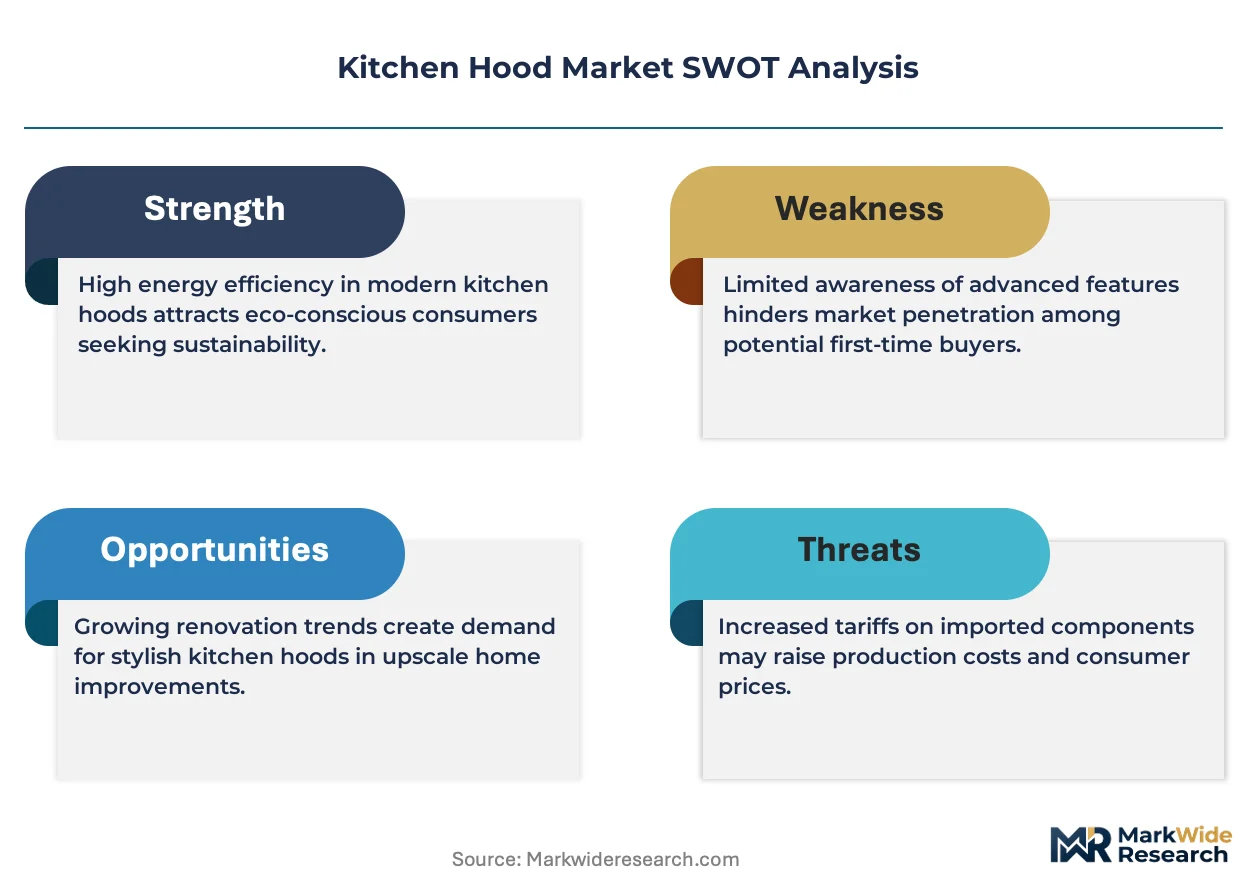
- EU Ecodesign Directive:Maximum power consumption thresholds and noise limits are certifying brushless DC architectures through notified bodies, accelerating platform standardization across European residential construction.
- Urban kitchen renovation cycles:Shortening replacement intervals in Chinese metropolitan housing stock are creating recurring demand for smart-home-compatible replacement units with integrated automation controllers.
- Charcoal filtration innovation:Advanced activated carbon stages in ductless configurations are enabling penetration of dense urban apartments where external venting is structurally impractical.
Market Restraints
- Copper and cold-rolled steel volatility:Input cost swings for motor windings and coated panel substrates are compressing margin stability for manufacturers without backward integration into metal forming.
- German motor supply concentration:Captive brushless DC production clusters in Southern Germany are creating bottleneck risk for premium chimney line expansion outside captive supply networks.
- Acoustic performance ceilings:Physical limits on fan blade tip speed versus noise generation are constraining CFM escalation in open-plan residential layouts.
Strategic Opportunities
- India residential premiumization:Underpenetrated high-CFM specification in urban housing developments offers white space for island hood architectures as open-plan kitchen adoption accelerates.
- Smart-home interoperability:Convergence of hood controllers with broader kitchen automation ecosystems creates platform lock-in potential for ecosystem-integrated OEMs.
- US Inflation Reduction Act:Residential energy efficiency incentives are creating tailwinds for certified high-efficiency unit replacement in existing housing stock.
Industry Challenges
- Electronics firmware certification:SAMR market surveillance protocols in China and FCC electromagnetic compliance in the US are extending product launch timelines for controller-integrated units.
- Cross-platform service fragmentation:Proprietary automation protocols are complicating replacement part availability and technician training across installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Hood Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wall-Mounted, Island, Under-Cabinet, Downdraft Installation Type: Fixed, Portable, Retractable, Ceiling-Mounted Technology: Filterless, Charcoal, Ducted, Ductless Feature: Auto-Sensor, LED Lighting, Variable Speed, Remote Control |
| Companies Covered | BSH Home Appliances, Elica S.P.A, Faber S.P.A, Broan-NuTone, Asko Appliances, Whirlpool Corporation, Haier Smart Home, Samsung Electronics, Vent-A-Hood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Hood Market Strategic Shifts
Sensor-driven airflow modulation is automating capture efficiency optimization, while regulatory pressure on motor efficiency and noise is converging with smart-home integration demands to reshape product architecture roadmaps.
Brushless DC motor platforms with integrated variable frequency drives are automating real-time CFM adjustment based on cooking surface temperature and particulate detection. Residential builders in premium housing developments are specifying these units as baseline for smart-home-ready inventory. The technology is automating the trade-off between capture efficiency and acoustic comfort that previously required manual user intervention.
EU Ecodesign Directive amendments are tightening maximum power consumption thresholds for residential range hoods while mandating standby power limits. Manufacturers must certify compliance through notified bodies, extending development cycles. Island hood configurations for open-plan layouts face the steepest engineering challenges given their aesthetic visibility and ducting complexity requirements.
Builder procurement of kitchen appliances is consolidating toward ecosystem-integrated packages rather than standalone unit sourcing. Premium residential developers in China and the US are bundling hood controllers with broader kitchen automation platforms. This behavior is most visible in Shanghai and Shenzhen metropolitan clusters where smart-home infrastructure is becoming a competitive differentiator in new construction marketing.
Kitchen Hood Market Segmentation
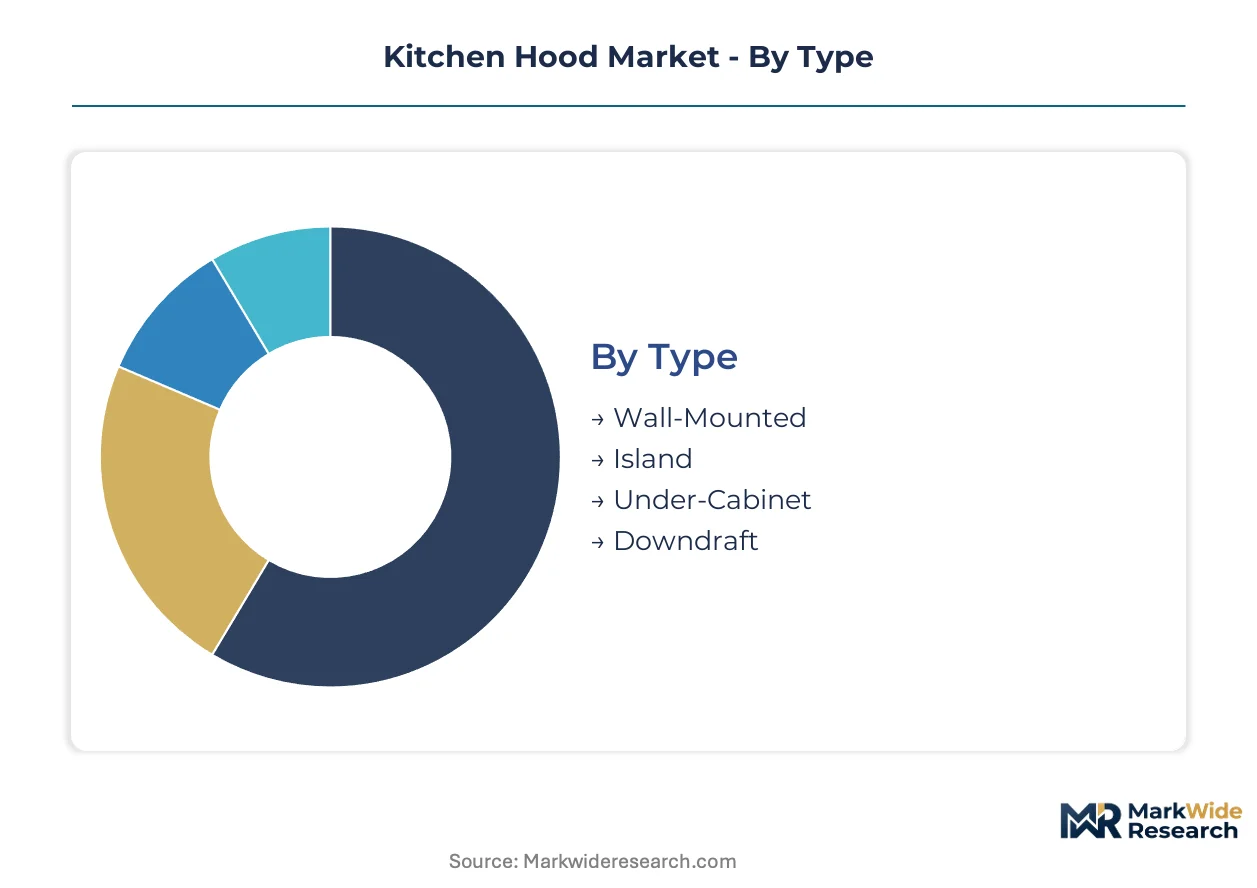
Kitchen hood segmentation reveals how supply-side capabilities align with divergent installation constraints and ventilation infrastructure across residential construction. Manufacturers configure motor platforms, filtration stages, and control architectures differently for each segment, creating distinct margin profiles and certification requirements.
Type:
Supply concentration clusters around wall-mounted platforms where standardized ducting geometry enables scale economies in motor and housing production.
- Wall-Mounted:These units attach directly to vertical surfaces above cooking ranges, leveraging existing cabinetry footprints and standardized 6-inch or 8-inch ducting. Demand concentrates in North American and European retrofit markets where kitchen layouts remain fixed and external wall penetration is structurally straightforward. US DOE efficiency standards are accelerating brushless DC motor adoption in this segment.
- Island:Suspended from ceilings above centrally located cooking surfaces, these configurations require complex overhead ducting and command premium positioning due to aesthetic visibility. Demand concentrates in Chinese and Indian premium residential developments where open-plan kitchen adoption is accelerating. EU Ecodesign Directive noise limits pose acute engineering challenges given the exposed installation geometry.
- Under-Cabinet:Compact units integrated beneath overhead storage, prioritizing space efficiency over maximum CFM. These dominate volume in Japanese and South Korean apartment construction.
- Downdraft:Retractable ventilation rising from countertops, eliminating overhead visual intrusion. These serve niche demand in ultra-premium European minimalist kitchen specifications.
Today's leader: Wall-Mounted. Tomorrow's challenger: Island.
Installation Type:
Cost tier differentiation separates fixed installations from portable alternatives, with retractable and ceiling-mounted configurations occupying intermediate price positioning.
- Fixed:Permanent mounting with hardwired electrical and rigid ducting connections, delivering maximum airflow capacity and noise isolation. These anchor specification in German and Italian premium housing developments where building codes mandate dedicated ventilation infrastructure.
- Portable:Freestanding units with flexible ducting or recirculating filtration, serving rental markets and temporary kitchen configurations. Demand concentrates in Brazilian and Mexican urban apartments where tenant turnover discourages permanent installation investment.
- Retractable:Motorized deployment mechanisms that conceal units within cabinetry when inactive. These are gaining share fastest in French and Spanish kitchen renovations where aesthetic minimalism drives specification.
- Ceiling-Mounted:Integrated flush with overhead surfaces, requiring specialized structural reinforcement. These serve ultra-premium island configurations in Dubai and Singapore luxury residential towers.
Fixed installations dominate current revenue. Retractable mechanisms represent the steepest expansion trajectory as smart-home integration enables automated deployment.
Technology:
Application requirements dictate filtration architecture, with ducted infrastructure availability determining regional technology mix.
- Filterless:Centrifugal grease separation without replaceable media, reducing maintenance burden and operating cost. These are expanding most quickly in Australian and Canadian markets where water-based separation technologies meet local efficiency certifications.
- Charcoal:Activated carbon filtration stages enabling recirculating operation without external venting. Demand concentrates in Chinese and Japanese dense urban apartments where structural constraints prohibit ducting penetration.
- Ducted:Direct exhaust to exterior, achieving highest capture efficiency and lowest noise. These dominate in US and German single-family construction with established ventilation infrastructure.
- Ductless:Combined grease and odor filtration with internal air recirculation, serving markets where external venting is impractical. These face margin pressure from charcoal filtration innovation.
Ducted technology leads in established markets. Charcoal filtration is climbing the fastest as urban density intensifies across Asia-Pacific metropolitan clusters.
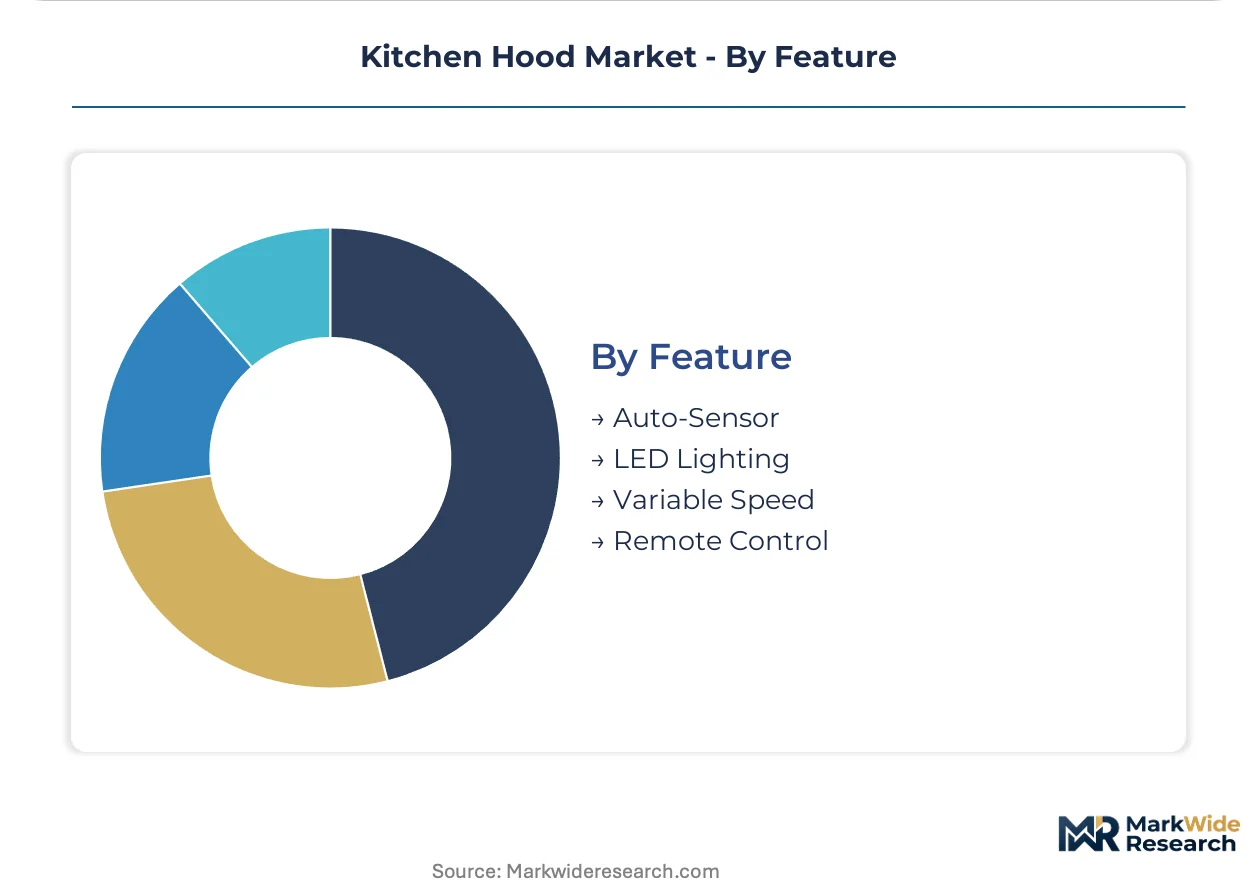
Feature:
Customer type stratification separates smart-home-integrated specifications from basic functionality, with variable speed and LED lighting now baseline in premium tiers.
- Auto-Sensor:Particulate and temperature detection automating airflow modulation without user intervention. These anchor specification in Chinese smart-home-integrated developments where MIIT interoperability standards are converging with household appliance controllers.
- LED Lighting:Integrated task illumination with color temperature adjustment, now standard in mid-tier and above across European markets. EU Ecodesign standby power limits are driving efficiency optimization in driver electronics.
- Variable Speed:Multi-stage or continuous airflow adjustment, balancing capture efficiency against acoustic comfort. These dominate specification in open-plan residential layouts where noise constraints are acute.
- Remote Control:Wireless or app-based operation, increasingly bundled with broader kitchen automation platforms. FCC electromagnetic compliance requirements extend development timelines for US-bound units.
Auto-sensor functionality is gaining share fastest. Remote control integration faces standardization headwinds as proprietary protocols fragment service ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motor production clusters anchor supply-side capacity for premium chimney architectures, while Chinese metropolitan renovation cycles and Indian open-plan adoption reshape demand geography across three continents.
United States
Residential builders in premium housing developments specify high-CFM units with brushless DC motors as baseline inventory. The US Department of Energy enforces minimum efficiency standards that compress legacy AC motor supply chains. Specification concentrates in California and Texas metropolitan clusters where smart-home-ready inventory differentiates new construction marketing.
Germany
Captive brushless DC production in Southern Germany sustains margin control for premium chimney line expansion. The EU Ecodesign Directive mandates maximum power consumption thresholds and noise limits certified through notified bodies. Manufacturing gravity centers on Baden-Württemberg and Bavaria where integrated stamping and enameling facilities serve OEM networks across Southern Europe.
China
Urban kitchen renovation cycles are shortening in Shanghai and Shenzhen metropolitan clusters, creating recurring demand for smart-home-compatible replacement units. SAMR market surveillance protocols enforce GB standards for household electrical appliances through firmware certification requirements. MIIT interoperability standards are converging with hood controllers in Yangtze River Delta and Pearl River Delta manufacturing hubs.
India
Open-plan kitchen adoption in Mumbai and Delhi-NCR urban housing developments offers white space for island hood architectures with premium positioning. BIS safety and performance benchmarks regulate household electrical appliance imports and domestic production. Specification is accelerating in Maharashtra and Karnataka residential towers where Western kitchen aesthetics displace traditional ventilation configurations.
Italy
Deep specialization in island hood architectures serves open-plan residential layouts across European and Middle Eastern export markets. CE marking requirements align with EU Ecodesign Directive amendments tightening standby power limits. Design and prototyping clusters concentrate in Emilia-Romagna and Lombardy where aesthetic visibility requirements drive engineering differentiation.
Kitchen Hood Market Competitive Environment
Global majors compete with regional champions across motor technology and installation geometry specialization, producing a tiered structure where captive production assets separate premium positioning from scale-driven supply. The vendor base organizes around three strategic archetypes: integrated appliance conglomerates with captive motor production, specialist ventilation fabricators with deep installation-type expertise, and electronics-led platform players leveraging smart-home ecosystems. Competitive moves concentrate on backward integration into brushless DC motor supply and ecosystem partnership formation for automation controller integration.
Among European specialist fabricators, Elica S.P.A and Faber S.P.A exemplify divergent scale-versus-specialization positioning within Italian ventilation manufacturing. BSH Home Appliances anchors the integrated conglomerate archetype through captive motor production in Germany. These three entities represent distinct competitive vectors: deep installation-type specialization, manufacturing scale across OEM supply networks, and vertical control over critical component supply.
| Leading Market Players |
|---|
| BSH Home Appliances |
| Elica S.P.A |
| Faber S.P.A |
| Broan-NuTone |
| Asko Appliances |
| Whirlpool Corporation |
| Haier Smart Home |
| Samsung Electronics |
| Vent-A-Hood |
| Others |
Value Chain & Pricing Dynamics
Copper and cold-rolled steel price indices cascade through kitchen hood manufacturing tiers, compressing margins for non-integrated producers while rewarding manufacturers with captive motor production and backward integration into metal forming. Input cost volatility feeds directly into three-tier pricing stratification across premium chimney lines, mid-tier wall-mounted units, and economy under-cabinet configurations.
Pricing Analysis
Input-cost pass-through mechanisms differentiate pricing power between integrated and non-integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates brushless DC-equipped island hoods from AC motor wall units and basic recirculating models. Price differentiation hinges on certification grade and volume scale, with EU Ecodesign Directive compliance adding cost layers to European-bound inventory. Pricing pressure stems from copper winding and coated panel substrate volatility, squeezing tier-two manufacturers without metal forming assets. Rental market buyers in Brazilian and Mexican urban apartments exhibit highest price sensitivity, while German and Italian premium residential developers demonstrate lowest elasticity.
Supply Chain Analysis
Certification and qualification gating through notified bodies and SAMR firmware protocols constrain supplier eligibility for controller-integrated units. Manufacturing gravity centers on Germany, China, and Italy, with Southern German clusters anchoring brushless DC motor supply and Yangtze River Delta hubs dominating electronics integration. Raw material dependencies rest on copper for motor windings, cold-rolled steel for coated panels, and rare-earth magnets for permanent-motor platforms. Single-source vulnerability concentrates in German captive motor production networks. Distribution runs through builder procurement channels and kitchen renovation retailers, with ecosystem-integrated OEMs capturing specification lock-in through automation platform bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kitchen hood demand has shifted toward premium specifications as residential developers specify smart-home-compatible, high-CFM units as baseline inventory, making this a late-cycle quality story where margin sustainability favors integrated producers.
For Market Incumbents: Anticipate margin compression from charcoal filtration innovation displacing conventional ductless configurations by securing captive supply of activated carbon media and accelerating brushless DC platform standardization. Defensive consolidation should prioritize backward integration into motor production and certification investment for SAMR and FCC electromagnetic compliance to extend product launch timelines as a competitive moat. For New Entrants and Emerging Players: Indian premium residential developers represent an underserved buyer archetype with accelerating open-plan kitchen adoption and underpenetrated island hood specification. White-space targets include Mumbai and Delhi-NCR metropolitan clusters where Western kitchen aesthetics displace traditional ventilation, and retractable mechanism segments in French and Spanish renovation markets. A go-to-market angle through smart-home ecosystem partnerships enables platform lock-in without proprietary protocol development. For Investors and Strategic Acquirers: Asymmetric upside sits with specialist ventilation fabricators possessing deep installation-type expertise and regional certification infrastructure. Long-term viability favors entities with demonstrated EU Ecodesign Directive compliance pathways and MIIT interoperability convergence. The signal to watch is builder procurement consolidation toward ecosystem-integrated packages, which will accelerate margin separation between platform-integrated and standalone suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless DC Motors | Captive motor production in Germany sustains margin control across premium chimney lines amid tightening efficiency standards. |
| Smart-Home Ecosystem Partnership | Integration with MIIT interoperability standards in Chinese manufacturing hubs enables platform lock-in for replacement demand. |
| Charcoal Filtration Innovation | Advanced activated carbon stages unlock dense urban apartment penetration where external venting is structurally impractical. |
| Regional Certification Investment | SAMR firmware certification and FCC electromagnetic compliance extend development timelines as competitive barriers. |
| Island Hood Architecture Specialization | Deep expertise in open-plan residential layouts commands premium positioning in Chinese and Indian metropolitan developments. |
Study Parameters
Multiple input streams — primary interviews with appliance manufacturing executives, regulatory affairs specialists, and residential builder procurement managers, alongside secondary validation through customs records, SEC filings, and EU Ecodesign Directive certification databases — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement encompassed motor platform engineers, kitchen automation system integrators, and aftermarket service technicians across German, Chinese, and North American supply clusters.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning installation geometry, motor technology platform, filtration architecture, and smart-home integration tier. CAGRs were derived from fitted growth curves against historical replacement cycle data and regulatory compliance timelines. Industry-specific forecast inputs included urban kitchen renovation frequency in Chinese metropolitan clusters and open-plan kitchen adoption rates in Indian premium housing.
Underlying measurement precision varies by segment; ducted technology and wall-mounted configurations carry tighter precision than emerging retractable and downdraft categories where adoption trajectories remain less certain. Forecasts reflect assumptions regarding regulatory enforcement continuity and raw material price stability. A model refresh is warranted upon material change in EU Ecodesign Directive amendment schedules or MIIT interoperability standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Europe Air Conditioning Equipment Market