
 Engineered Wood Product Market | 2026-2036
Engineered Wood Product Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered Wood Product Market Analysis
Buyer concentration among large residential contractors is consolidating as national homebuilders standardize engineered wood framing packages across multi-state developments. West Fraser Timber Co. Ltd. leverages integrated softwood lumber supply to control input costs for oriented strand board mills. Weyerhaeuser Company sustains extensive distribution reach through direct contractor relationships in the southern United States. LP Building Solutions specializes in high-performance sub-floor panels that anchor its position in production homebuilding.
Engineered wood products comprise structural and non-structural composite materials manufactured from wood strands, veneers, fibers, or particles bonded with adhesives under heat and pressure, typically achieving uniform strength properties exceeding solid sawn lumber of equivalent dimensions. These materials serve primary load-bearing functions in walls, floors, and roofs while reducing construction waste and enabling longer clear spans than conventional framing. Plywood and oriented strand board dominate volume in North American residential sheathing applications where building codes recognize their structural equivalence. Laminated veneer lumber and glulam command premium positioning in commercial and architectural projects requiring exposed timber aesthetics with reliable load capacity.
Building codes developed by the International Code Council in the United States, CE marking requirements under the European Construction Products Regulation, and CSA O86 engineering standards in Canada collectively shape product certification, fire-resistance ratings, and market access for structural engineered wood. EPA formaldehyde emission standards and evolving green building certifications further filter which adhesive systems and manufacturing processes qualify for specification. Stakeholders must monitor code amendments permitting taller mass-timber structures and the resulting specification shifts that will redistribute volume across product categories.
Market Dynamics
Building code amendments permitting taller mass-timber structures are redistributing specification authority from commodity sheathing suppliers toward engineered structural timber specialists with fire-engineering capabilities.
Growth Catalysts
- International Code Council Tall Wood Building Provisions:The ICC's 2021 code expansion permits mass-timber construction up to 18 stories, unlocking mid-rise residential and commercial segments previously reserved for steel and concrete.
- Cross-laminated timber fire performance:CLT's charring behavior satisfies extended fire-resistance ratings without chemical treatments, qualifying it for exposed structural applications in institutional buildings.
- Japan's mid-rise timber mandate:METI's Wood Use Promotion Act requires public buildings to incorporate wood, with 2024 amendments extending obligations to private commercial structures over 3,000 square meters.
Market Restraints
- Adhesive input cost volatility:Methanol and formaldehyde feedstock prices fluctuate with natural gas benchmarks, compressing margins for OSB and LVL manufacturers locked into six-month construction procurement contracts.
- Softwood lumber supply concentration:British Columbia and US Pacific Northwest timber harvest constraints limit veneer and strand supply to engineered wood mills, creating geographic chokepoints.
- Steel-frame substitution in seismic zones:Post-tensioned concrete and moment-frame steel retain specification advantages in high-seismic regions where building officials impose additional testing burdens on timber systems.
Strategic Opportunities
- India's affordable housing shortfall:The country's Pradhan Mantri Awas Yojana targets 20 million urban housing units, creating demand for prefabricated wall panels that engineered wood suppliers can serve through local joint ventures.
- Carbon-accounting procurement mandates:France's RE2020 environmental regulation requires embodied carbon disclosure for new construction, favoring timber systems with verified negative carbon profiles over conventional materials.
- Hybrid timber-concrete floor systems:TCC (timber-concrete composite) technology combines CLT slabs with thin concrete toppings, extending spans for commercial office fit-outs while reducing dead load by 40 percent versus conventional construction.
Industry Challenges
- Mass-timber fire engineering certification backlog:Third-party testing laboratories face 12-18 month queues for CLT and glulam fire-resistance rating validation, delaying project approvals.
- Plant retrofit capex intensity:Converting traditional plywood facilities to continuous OSB presses requires $80-120 million per line, stranding capital in legacy equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered Wood Product Market |
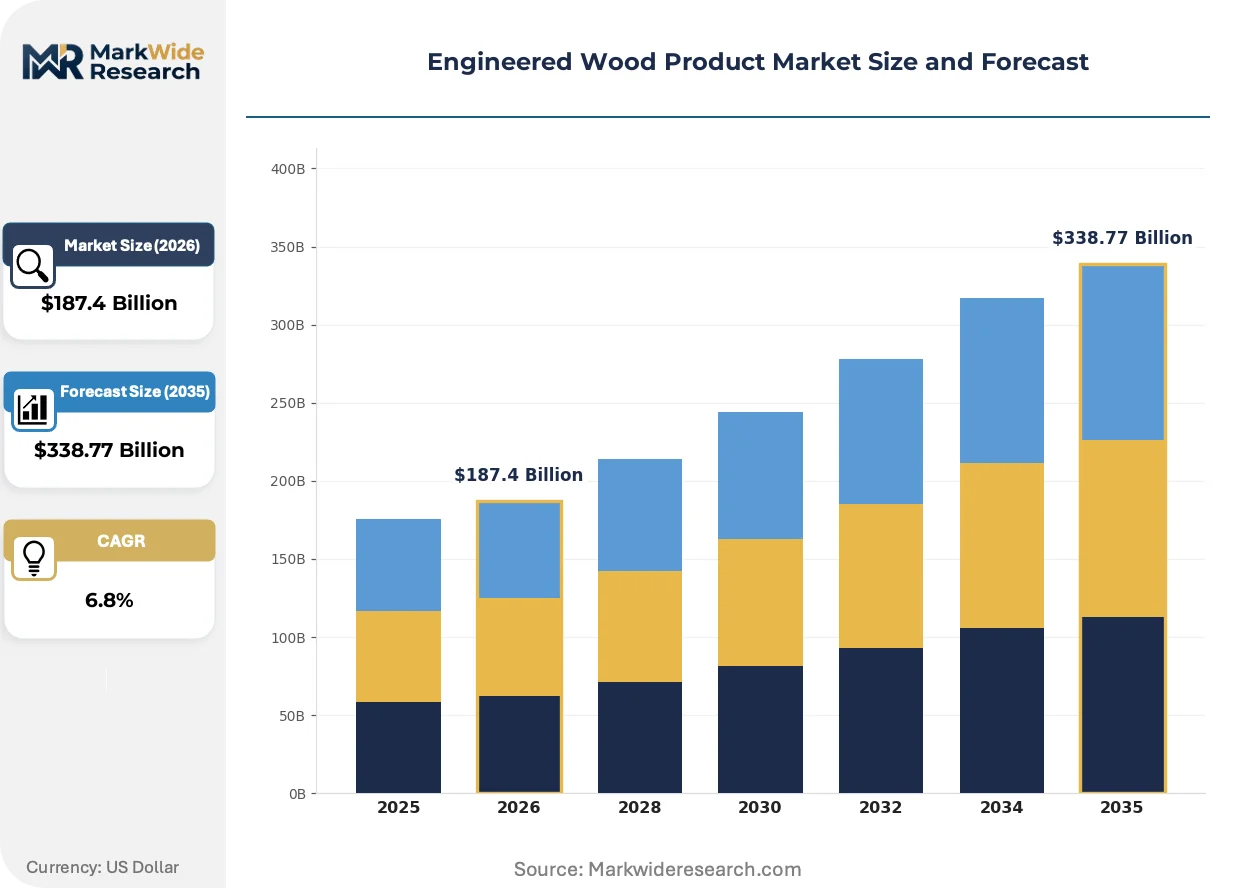
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Laminated Veneer Lumber, Oriented Strand Board, Glulam Application: Residential Construction, Commercial Construction, Furniture Manufacturing, Flooring End User: Contractors, DIY Enthusiasts, Architects, Furniture Makers Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | West Fraser Timber Co. Ltd., Roseburg Forest Products, Weyerhaeuser Company, Universal Forest Products, Inc., Huber Engineered Woods LLC, Boise Cascade Company, Georgia-Pacific LLC, Stora Enso, LP Building Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered Wood Product Market Emerging Trajectories
Digital fabrication and bio-based adhesive chemistry are compressing the gap between architectural design intent and manufactured timber component precision, reducing field modification and waste.
Mass-timber design software is unifying structural engineering, manufacturing, and construction sequencing into single-platform workflows. Architects in Scandinavia and the Pacific Northwest are specifying parametrically optimized CLT panels with CNC-cut connection details. This capability is compressing the traditional design-bid-build timeline and shifting risk allocation toward fabricators with in-house engineering capacity.
REACH restrictions on formaldehyde-based resins are accelerating phenol-formaldehyde substitution with soy-based and tannin-bonded alternatives in European OSB production. ECHA's 2023 reclassification of certain isocyanates as respiratory sensitizers has triggered reformulation investments across adhesive suppliers. German and Austrian panel manufacturers are responding with certified low-emission product lines that qualify for Blue Angel and Nordic Swan ecolabel procurement preferences.
Prefabrication is consolidating procurement authority among national homebuilders with standardized engineered wood packages. Production builders in the southern United States are bypassing traditional lumberyard distribution through direct mill contracts for floor and roof cassettes. This channel compression is most visible in Texas and Florida metropolitan markets where speed-to-enclosure drives contractor selection criteria.
Engineered Wood Product Market Segmentation
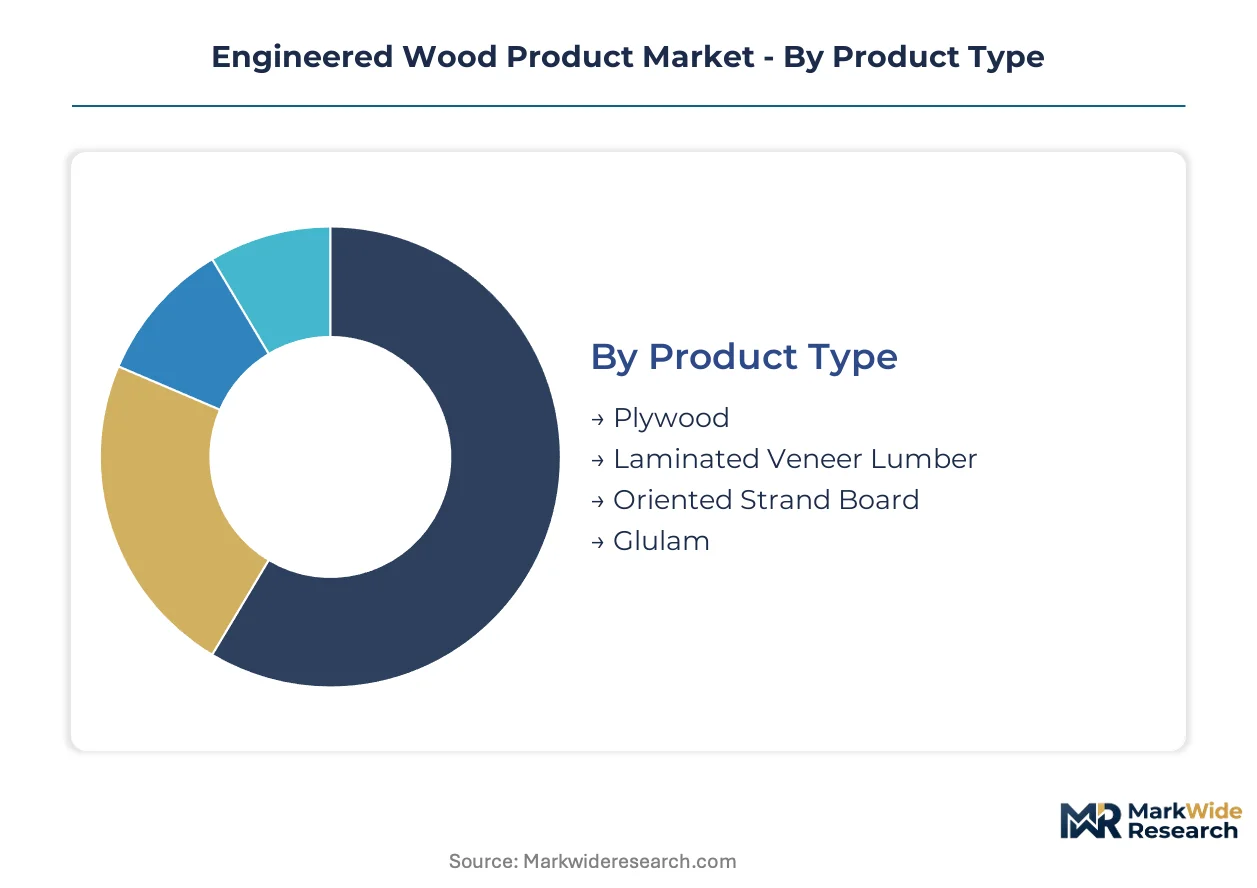
Segmentation in engineered wood products reveals how manufacturing scale, specification authority, and channel control distribute across product categories and customer types. Supply concentration in strand-based panels contrasts with fragmentation in specialty timber systems, creating divergent margin profiles and competitive dynamics.
Product Type:
Mill configuration and raw material access determine competitive intensity across structural panel and engineered timber categories.
- Plywood:Cross-laminated veneer construction delivers consistent dimensional stability under cyclic moisture exposure, making it indispensable for concrete formwork and marine applications in Japan and coastal United States markets. Japanese construction standards specify Douglas fir and larch veneers for high-strength grades, concentrating procurement among regional Pacific Northwest suppliers.
- Laminated Veneer Lumber:Continuous veneer lamination produces beams with predictable load-bearing capacity across longer spans than solid sawn alternatives. Demand concentrates in commercial roof structures across Germany and Austria where exposed timber aesthetics command specification priority.
- Oriented Strand Board:Flake orientation technology maximizes structural efficiency from lower-grade aspen and southern yellow pine feedstock.
- Glulam:Finger-jointed lamstock enables curved and tapered beam profiles for architectural expression.
OSB absorbs the bulk of installed capacity; LVL is expanding most quickly.
Application:
Building height allowances and fire-engineering requirements segment demand between commodity sheathing and performance-engineered systems.
- Residential Construction:Platform framing standardization drives volume demand for sub-floor, wall, and roof sheathing in production homebuilding across Texas and Florida metropolitan corridors. National builders specify engineered wood packages to accelerate cycle times and reduce jobsite waste.
- Commercial Construction:Mass-timber structural systems satisfy extended fire-resistance ratings through charring behavior, qualifying CLT and glulam for mid-rise office and institutional projects in British Columbia and Oregon where code amendments permit 12-18 story construction.
- Furniture Manufacturing:Decorative veneer faces and consistent core density enable precision machining for cabinetry and fixture production.
- Flooring:Engineered plank construction stabilizes hardwood wear layers over dimensionally stable cores.
Residential construction commands the dominant share of volume; commercial construction is climbing the fastest.
End User:
Specification authority and procurement scale separate professional builders from discretionary purchasers in channel strategy.
- Contractors:Production homebuilders in the southern United States negotiate direct mill contracts for floor and roof cassettes, bypassing traditional lumberyard distribution to compress construction schedules. Speed-to-enclosure criteria drive standardization across multi-state developments.
- DIY Enthusiasts:Retail-accessible panel products and pre-cut project kits serve renovation and hobbyist demand through home center channels.
- Architects:Exposed timber specifications require fire-engineering documentation and aesthetic grading control.
- Furniture Makers:Custom fabricators source specialty veneer and composite cores for millwork applications.
Contractors represent the largest procurement volume; architects are gaining specification influence fastest.
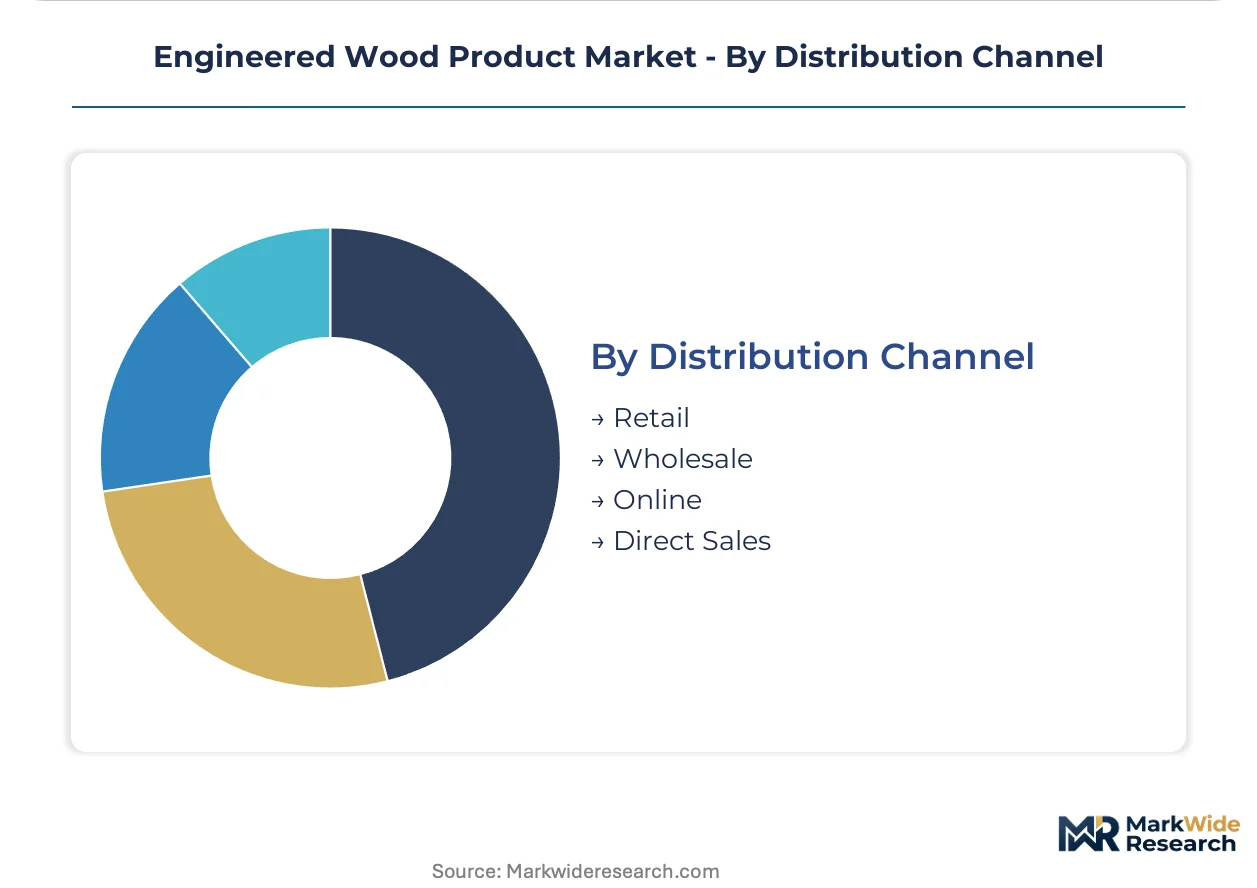
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to manufacturing capacity.
- Retail:Home center networks stock commodity OSB and plywood sheathing for immediate contractor pickup and homeowner project demand, concentrating inventory turns in metropolitan markets with active residential permitting.
- Wholesale:Regional lumberyards provide credit terms, jobsite delivery, and takeoff services for mid-sized builders across the United States Midwest and Southeast.
- Online:Digital procurement platforms aggregate specialty product availability for project-specific specification.
- Direct Sales:National production builders contract directly with West Fraser and Weyerhaeuser mill systems for standardized engineered wood packages.
Wholesale channels handle the majority of transaction volume; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest softwood forests supply veneer and strand feedstock to engineered wood mills across North America and Asia. British Columbia harvest constraints redirect raw material flows toward US South processing capacity. Code harmonization between jurisdictions accelerates cross-border specification of mass-timber systems.
United States
Production homebuilders in Texas and Florida metropolitan corridors negotiate direct mill contracts for floor and roof cassettes. The International Code Council's 2021 Tall Wood Building Provisions permit mass-timber construction up to 18 stories, unlocking mid-rise segments. Southern yellow pine plantations around Augusta, Georgia anchor oriented strand board capacity expansion.
Germany
Exposed timber specifications in commercial roof structures drive demand for laminated veneer lumber with aesthetic grading control. REACH restrictions on formaldehyde-based resins accelerate phenol-formaldehyde substitution with bio-based alternatives. The Stuttgart-Tübingen corridor hosts prefabrication specialists supplying CLT panels to French and Swiss projects.
Japan
METI's Wood Use Promotion Act mandates wood incorporation in public buildings, with 2024 amendments extending obligations to private commercial structures over 3,000 square meters. Douglas fir and larch veneer procurement concentrates among Pacific Northwest suppliers serving Japanese construction standards. The Osaka-Kobe industrial zone hosts finger-jointing specialists for glulam export production.
Canada
British Columbia timber harvest constraints limit veneer and strand supply to engineered wood mills, creating geographic chokepoints for North American capacity. CSA O86 engineering standards shape product certification and fire-resistance ratings for structural engineered wood. Quebec's Saguenay-Lac-Saint-Jean region hosts cross-laminated timber manufacturing serving northeastern US markets.
France
RE2020 environmental regulation requires embodied carbon disclosure for new construction, favoring timber systems with verified negative carbon profiles. Mass-timber design software adoption unifies structural engineering and manufacturing sequencing in single-platform workflows. The Grenoble-Lyon corridor anchors glulam production for alpine and Mediterranean commercial projects.
Engineered Wood Product Market Vendor Landscape
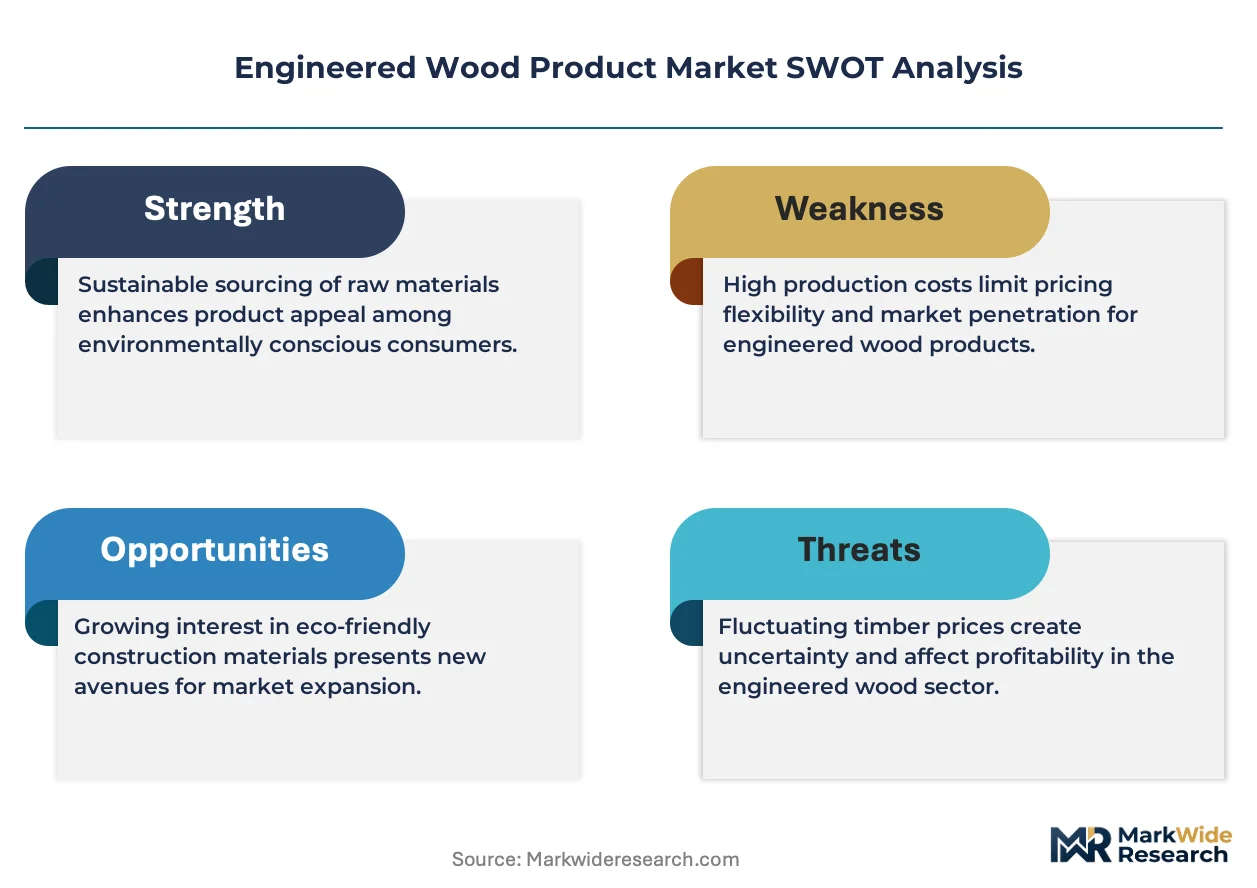
Established producers occupy the standard tier; emerging entrants pursue mass-timber engineering and fire-certification capabilities. The vendor base stratifies between commodity panel manufacturers with scale advantages and specialty timber fabricators with design-assist competencies. Three archetypes dominate: integrated forest-products conglomerates controlling raw material supply, regional mill operators serving contractor direct-procurement channels, and engineered-timber specialists with in-house structural engineering capacity. Competitive moves concentrate on backward integration into plantation forestry and strategic partnerships with national homebuilders for standardized package supply.
Among North American forest-products conglomerates, West Fraser Timber Co. Ltd., Weyerhaeuser Company, and LP Building Solutions exemplify scale-driven positioning across sheathing and structural timber categories. These entities represent integrated supply-chain control from softwood harvest through finished panel distribution. European competitors including Stora Enso occupy positions emphasizing certified low-emission product lines and mass-timber system integration.
| Leading Market Players |
|---|
| West Fraser Timber Co. Ltd. |
| Roseburg Forest Products |
| Weyerhaeuser Company |
| Universal Forest Products, Inc. |
| Huber Engineered Woods LLC |
| Boise Cascade Company |
| Georgia-Pacific LLC |
| Stora Enso |
| LP Building Solutions |
| Others |
Supply Flow & Price Mechanics
Softwood lumber feedstock costs cascade through three distinct pricing tiers for engineered wood products, with British Columbia harvest constraints amplifying volatility for strand-based panels while German and Austrian mills absorb REACH-compliant adhesive premiums into certified low-emission product lines. National homebuilders in Texas and Florida leverage direct mill contracts to compress procurement spreads, shifting margin pressure toward regional lumberyards serving mid-sized contractors without volume scale.
Pricing Analysis
Warranty-backed fire-engineering documentation and structural design-assist services bundle into premium CLT and glulam quotations, while commodity OSB and plywood trade on spot-indexed transactional terms without technical support. Three-tier pricing structure across premium, standard, and economy levels separates mass-timber systems with char certification from code-compliant sheathing and untreated commodity panels. Cost compression in standard-grade OSB is intensifying because methanol and formaldehyde feedstock prices fluctuate with natural gas benchmarks, locking mills into margin squeeze against six-month construction procurement contracts. Production homebuilders with multi-state developments exhibit lowest price sensitivity due to cycle-time priorities, while independent regional contractors face acute margin pressure from adhesive cost pass-through.
Supply Chain Analysis
Single-source vulnerability sits with British Columbia and the US Pacific Northwest for veneer and strand feedstock, where timber harvest constraints create geographic chokepoints for North American engineered wood capacity. Raw material supply draws from Douglas fir and larch stands in coastal British Columbia, aspen feedstock in Canadian boreal forests, and southern yellow pine plantations around Augusta, Georgia. Tariff exposure on cross-border softwood lumber flows between Canada and the United States threatens input cost stability for US South OSB expansion. Distribution runs through direct mill contracts for national production builders, bypassing traditional lumberyard channels in metropolitan Texas and Florida corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber and mass-timber engineering capabilities are displacing legacy plywood and commodity OSB specification authority in mid-rise construction, creating a technology-transition window where fire-certification capacity determines competitive survival.
For Market Incumbents: To counter specification authority migration toward mass-timber specialists with in-house fire-engineering capabilities, West Fraser and Weyerhaeuser should accelerate certification investment for CLT and glulam product lines while securing backward integration into Pacific Northwest plantation forestry to control veneer supply. Channel control through direct contractor relationships in the southern United States remains a defensive lever against wholesale bypass. For New Entrants and Emerging Players: The price-point gap between premium European mass-timber systems and economy-grade Asian plywood imports creates entry space for mid-tier CLT producers offering code-compliant fire ratings without aesthetic-grade premiums. India's affordable housing shortfall under Pradhan Mantri Awas Yojana represents the most penetrable geography, served through local joint ventures for prefabricated wall panel production targeting 20 million urban unit mandates. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional mill operators with stranded OSB capacity in the US South, where capital expenditure intensity for continuous press conversion has left legacy plywood facilities underutilized. Fire-engineering certification backlog at third-party testing laboratories signals long-term viability for fabricators with in-house validation capacity. Watch ICC code amendment adoption velocity across US municipalities as the inflection indicator for mass-timber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Forestry | Captive softwood supply insulates OSB and LVL margins from British Columbia harvest volatility. |
| Fire-Engineering Certification Investment | In-house CLT and glulam validation capacity bypasses 12-18 month third-party laboratory queues. |
| Direct Mill Contracting with National Homebuilders | Bypasses wholesale lumberyard channels in Texas and Florida speed-to-enclosure markets. |
| Joint Venture Formation in India | Local prefabricated wall panel production addresses Pradhan Mantri Awas Yojana urban housing targets. |
| Bio-Based Adhesive Reformulation | REACH-compliant soy and tannin alternatives qualify for Blue Angel and Nordic Swan procurement preferences. |
Methodological Framework
Multi-period observation of ICC code adoption timelines, METI Wood Use Promotion Act amendment implementation, and RE2020 embodied carbon disclosure compliance anchored the trend analysis, supplemented by interviews with engineered wood mill operations directors, national homebuilder procurement executives, fire-engineering laboratory technical leads, and regional lumberyard distribution managers. Secondary validation incorporated International Code Council Tall Wood Building Provisions documentation, EPA formaldehyde emission standard filings, CSA O86 engineering standard revisions, and customs data on Pacific Northwest softwood lumber trade flows. Bottom-up capacity and demand modeling triangulated against top-down construction spending forecasts.
Segment-weighting across product type, application, end user, and distribution channel dimensions shaped volume and value projections throughout the forecast period. Modeled categories included structural panels versus engineered timber systems, residential versus commercial construction, contractor versus architect specification authority, and direct mill versus wholesale channel procurement. CAGRs were derived from regression analysis of historical price-quantity relationships and elasticity estimates for construction material substitution. Industry-specific forecast inputs encompassed building code amendment adoption curves and mass-timber fire-resistance rating validation throughput at third-party laboratories.
Inputs from engineered wood producers, building code officials, and construction procurement databases were available through the study window; gaps in real-time CLT project pipeline tracking and adhesive feedstock price forward curves introduce uncertainty bands around near-term volume projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
US Contract Glazing Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Fly Ash Bricks Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Global Facade Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Portland Cement Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Composite Decking and Railing Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Roof Cover Boards Market