
 Latin America Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
Latin America Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Bladder Cancer Therapeutics and Diagnostics Market Foresight
Immunotherapy agents are recalibrating treatment economics across Latin America by displacing conventional platinum-based chemotherapy in frontline muscle-invasive bladder cancer protocols. Pfizer Inc. leverages its established oncology infrastructure to sustain market presence across major Latin American markets. Bristol Myers Squibb differentiates through checkpoint inhibitor portfolios that anchor premium positioning in hospital formularies. Merck & Co., Inc. competes on PD-1 pathway expertise, extending its reach through regional clinical trial networks.
Bladder cancer therapeutics and diagnostics encompass pharmaceutical interventions, biological response modifiers, and clinical detection systems designed to treat or identify urothelial malignancies through molecular targeting, immune modulation, or visual and biomarker-based identification methods. These products serve to reduce mortality through earlier detection and more precise therapeutic selection based on tumor genomic profiles. Immunotherapy commands the largest revenue pool among product types, while liquid biopsies represent the fastest-expanding technology segment as healthcare institutions seek less invasive monitoring protocols. Diagnostics applications in hospital settings generate the most substantial volume, though outpatient clinics are gaining share as point-of-care molecular platforms mature.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce varying registration standards that shape market access timelines and clinical evidence requirements for novel therapeutics and companion diagnostics. The EU-MDR alignment pressures and WHO prequalification pathways further influence product development priorities for manufacturers targeting Latin America. Stakeholders must monitor reimbursement policy shifts for biomarker-driven therapies as national health systems evaluate cost-effectiveness frameworks for precision oncology.
Market Dynamics
Immunotherapy's displacement of platinum-based chemotherapy in frontline muscle-invasive bladder cancer protocols is restructuring treatment economics and hospital procurement priorities across Latin American oncology centers.
Growth Catalysts
- ANVISA harmonization:Brazil's regulatory alignment with EU-MDR standards compresses product registration timelines for novel therapeutics and companion diagnostics entering the market.
- Hospital infrastructure upgrades:Oncology centers in São Paulo and Rio de Janeiro are deploying advanced molecular testing platforms to support precision treatment selection.
- Reimbursement expansion:National health systems in Mexico and Argentina are incorporating biomarker-driven therapies into public coverage frameworks.
Market Restraints
- Biologics cold chain limitations:Temperature-controlled distribution infrastructure gaps in secondary cities restrict immunotherapy access outside major metropolitan hubs.
- Companion diagnostic cost concentration:High capital requirements for NGS-based testing platforms concentrate molecular diagnostic capacity in tertiary hospital networks.
- Clinical evidence requirements:COFEPRIS in Mexico mandates local bridging studies that extend registration timelines for novel checkpoint inhibitors.
Strategic Opportunities
- Outpatient clinic penetration:Point-of-care molecular platforms are creating decentralized diagnostic access in Colombian and Chilean urban centers.
- Liquid biopsy convergence:Integration of ctDNA monitoring with radiologic assessment is opening less-invasive surveillance protocols for post-treatment monitoring.
- Public-private partnership models:Argentina's oncology infrastructure investments are enabling risk-sharing arrangements for high-cost immunotherapy access.
Industry Challenges
- Molecular pathology workforce scarcity:Trained personnel for genomic test interpretation remain concentrated in Brazil and Mexico, limiting diagnostic scale-up.
- Supply chain reconfiguration friction:Temperature-sensitive biologics require specialized logistics partnerships that few regional distributors can sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Bladder Cancer Therapeutics and Diagnostics Market |
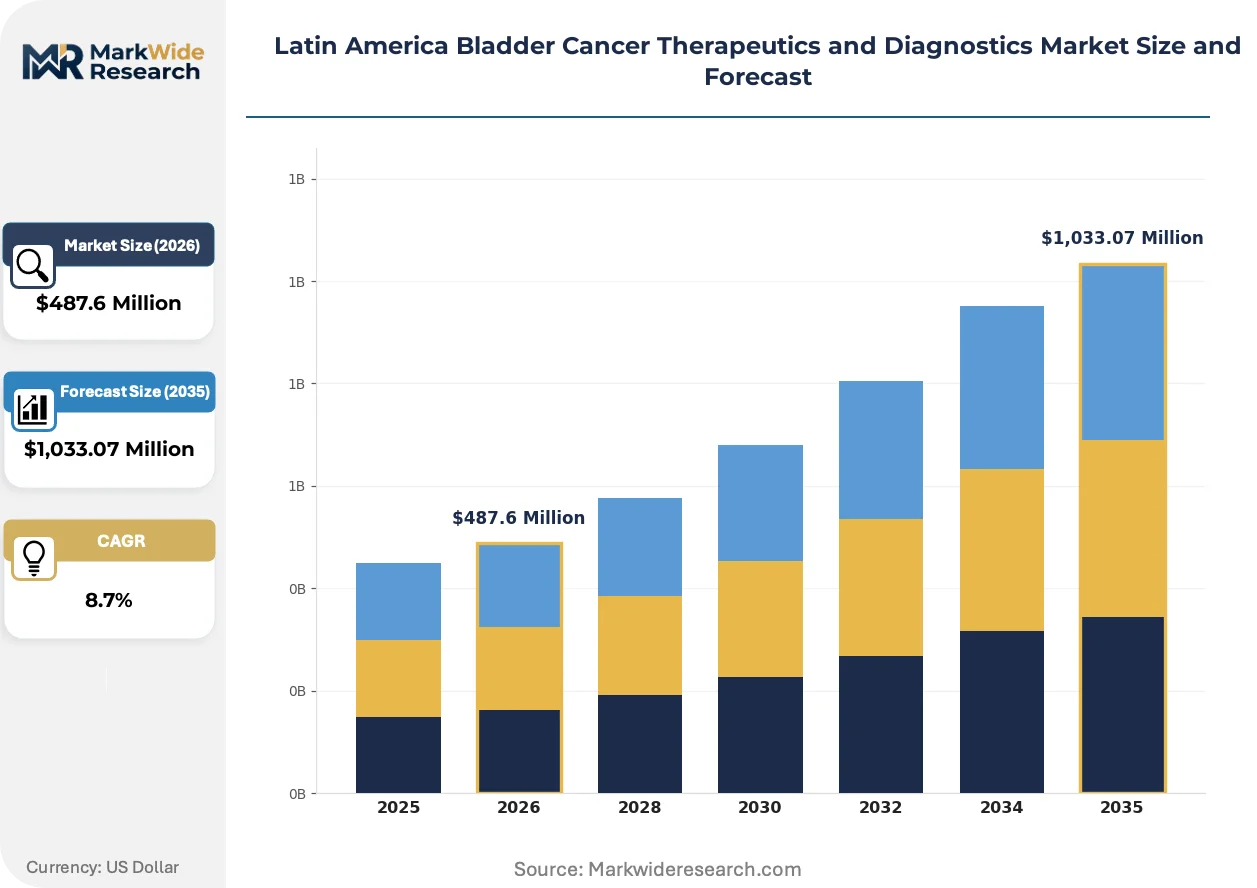
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Diagnostics Application: Hospital Settings, Outpatient Clinics, Home Care, Research Labs End User: Oncologists, Urologists, General Practitioners, Healthcare Institutions Technology: Biomarkers, Imaging Techniques, Genomic Profiling, Liquid Biopsies |
| Companies Covered | Pfizer Inc., Johnson and Johnson, AstraZeneca Plc, Bristol Myers Squibb, Merck & Co., Inc., Roche, Eli Lilly and Company, Novartis AG, GlaxoSmithKline Plc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Bladder Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Liquid biopsy platforms are compressing diagnostic workflows while regulatory convergence and procurement centralization are reshaping how technologies reach patients across Latin American healthcare networks.
Next-generation sequencing-based liquid biopsy technology detects circulating tumor DNA through peripheral blood draws, eliminating invasive tissue sampling requirements. Hospital-based oncology departments in Brazil and Mexico are adopting these platforms for treatment monitoring and recurrence detection. The technology is expanding into adjuvant therapy selection and minimal residual disease assessment, compressing the timeline between molecular profiling and treatment initiation.
ANVISA's progressive alignment with EU-MDR technical documentation requirements is elevating clinical evidence standards for in vitro diagnostic registrations. Manufacturers must now submit expanded performance validation data and post-market surveillance plans. This regulatory shift most affects companion diagnostic developers targeting the Brazilian market, who are restructuring quality management systems and local clinical trial investments to maintain access.
Hospital procurement committees are consolidating vendor relationships for molecular diagnostics through multi-year framework agreements that bundle equipment, reagents, and bioinformatics support. This purchasing consolidation displaces transactional spot-buying for individual test kits and platforms. The pattern is most visible in Brazilian and Mexican tertiary oncology centers, where integrated supply contracts now cover sequencing infrastructure, liquid biopsy assays, and interpretive reporting services.
Latin America Bladder Cancer Therapeutics and Diagnostics Market Segmentation
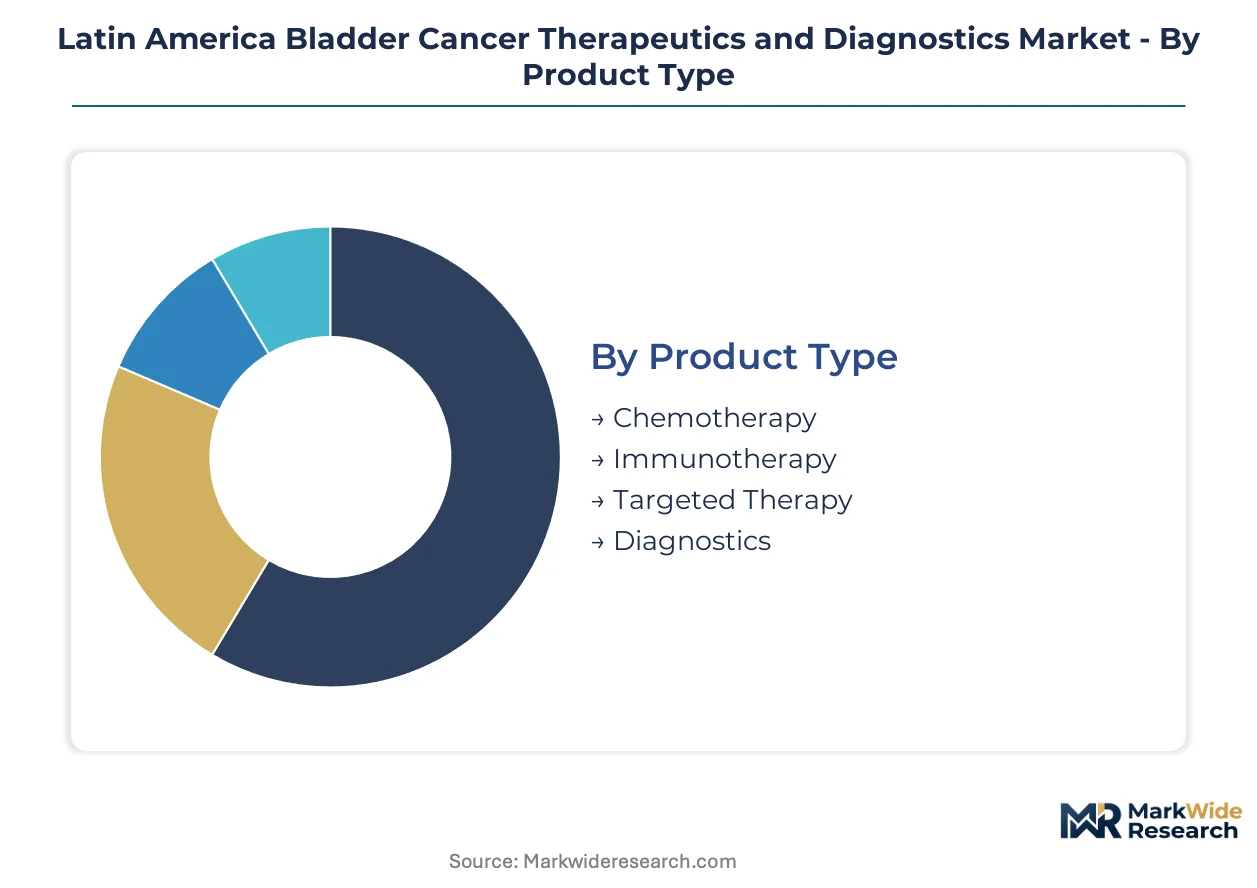
Segmentation in the Latin America bladder cancer market reveals how treatment delivery and diagnostic access fragment across infrastructure tiers. Supply concentration in major metropolitan centers shapes where each segment gains traction.
Product Type:
Supply concentration for biological therapies clusters in São Paulo, Mexico City, and Buenos Aires distribution hubs.
- Immunotherapy:Checkpoint inhibitors and PD-1/PD-L1 pathway modulators require cold chain infrastructure that only major metropolitan hospital networks can sustain. Brazilian oncology centers in São Paulo and Rio de Janeiro absorb the majority of regional immunotherapy procurement as ANVISA streamlines registration for these biologics.
- Diagnostics:Molecular testing platforms, including NGS-based profiling and companion diagnostic assays, concentrate in tertiary hospital laboratories with trained pathology workforces. Mexican oncology institutes in Mexico City and Monterrey are expanding diagnostic capacity to support precision therapy selection.
- Chemotherapy:Platinum-based regimens (cisplatin, gemcitabine) remain accessible through broader distribution networks due to less stringent storage requirements.
- Targeted Therapy:FGFR inhibitors and other molecularly directed agents serve biomarker-selected patient subsets in specialized treatment centers.
Immunotherapy absorbs the bulk of installed capacity; diagnostics is expanding most quickly as liquid biopsy platforms decentralize access.
Application:
Cost tier stratification separates high-complexity interventions from routine monitoring and surveillance protocols.
- Hospital Settings:Tertiary oncology centers perform radical cystectomies, intravesical therapy administration, and complex diagnostic workups. Brazilian public hospital networks in São Paulo state and Argentine oncology institutes in Buenos Aires concentrate surgical and advanced therapeutic capacity.
- Outpatient Clinics:Community urology practices and ambulatory cancer centers manage non-muscle-invasive bladder cancer surveillance and chemotherapy administration. Colombian cities including Bogotá and Medellín are expanding outpatient infusion capacity to reduce hospital congestion.
- Home Care:Oral targeted agents and supportive care medications reach patients through specialty pharmacy distribution in metropolitan areas with established oncology nursing networks.
- Research Labs:Academic medical centers in Brazil and Mexico conduct biomarker discovery and clinical trial correlative science, generating data for regional regulatory submissions.
Hospital settings command the highest procedure volumes; outpatient clinics are climbing the fastest as point-of-care platforms mature.
End User:
Volume concentration among specialist physicians creates referral pattern dependencies that shape market access strategies.
- Oncologists:Medical oncologists in Brazilian and Mexican tertiary centers prescribe systemic therapies and coordinate multidisciplinary tumor boards. These specialists drive adoption of immunotherapy protocols and molecular profiling for treatment selection.
- Urologists:Urological surgeons perform transurethral resections, cystectomies, and intravesical therapy administration. Argentine and Chilean urology societies are expanding training programs for robotic-assisted surgical techniques.
- General Practitioners:Primary care physicians in underserved regions provide initial hematuria evaluation and referral coordination, though diagnostic confirmation remains specialist-dependent.
- Healthcare Institutions:Public health systems and private hospital networks negotiate formulary placement and procurement contracts that determine patient access to novel therapeutics.
Oncologists absorb the bulk of systemic therapy decision-making; urologists are gaining share fastest as surgical innovation expands.
Technology:
Margin structures favor high-value molecular platforms over commoditized imaging modalities.
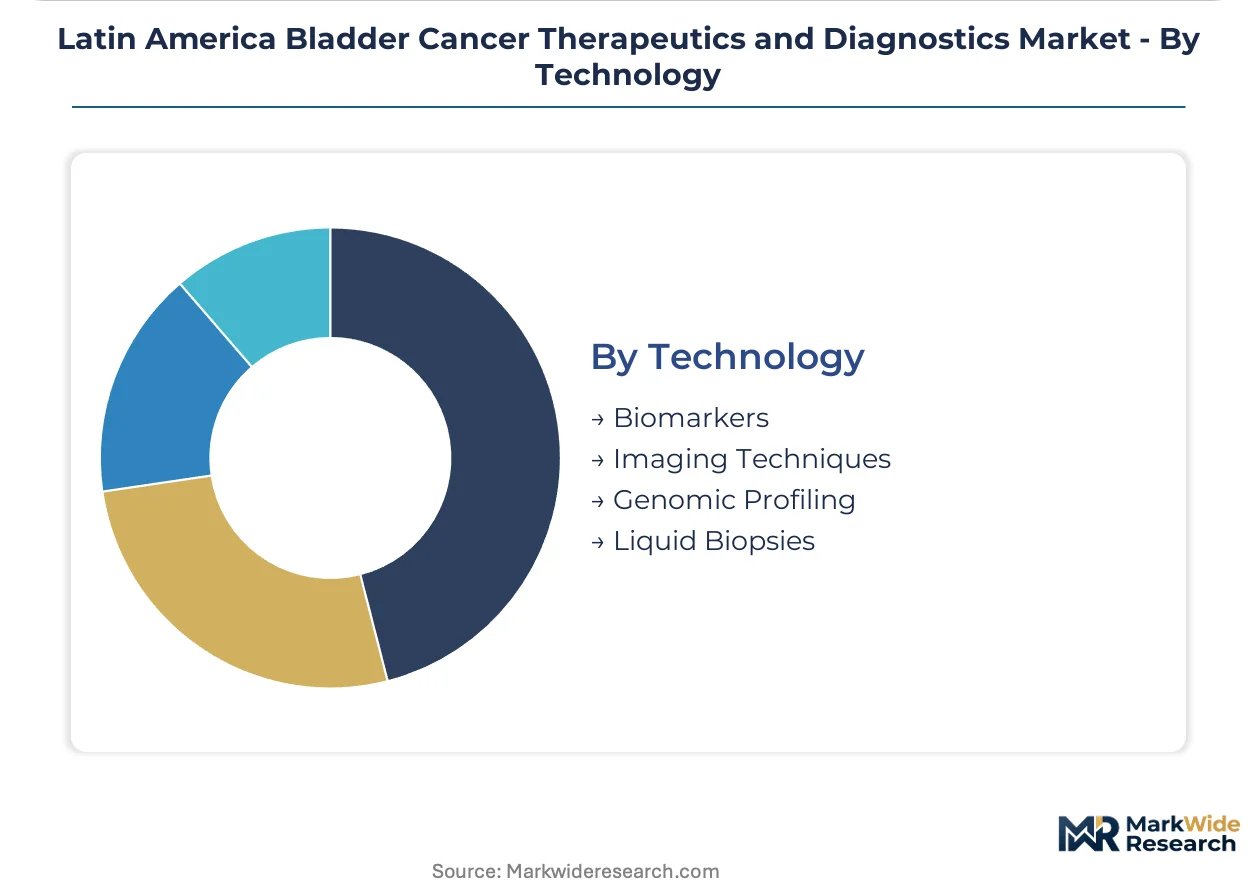
- Liquid Biopsies:Circulating tumor DNA detection through peripheral blood draws enables non-invasive monitoring and recurrence surveillance. Brazilian hospital laboratories in São Paulo and Mexican oncology centers are adopting ctDNA platforms for post-treatment surveillance.
- Genomic Profiling:Next-generation sequencing of tumor tissue identifies actionable alterations for targeted therapy selection. Colombian and Chilean molecular pathology services are building NGS capacity to reduce sample referral abroad.
- Biomarkers:Urine-based assays and protein markers support non-invasive screening and risk stratification in community settings with limited cystoscopy access.
- Imaging Techniques:CT urography, MRI, and PET-CT staging studies remain standard for locoregional and metastatic disease assessment across all market geographies.
Liquid biopsies command the steepest expansion trajectory; imaging techniques retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bladder cancer therapeutics and diagnostics concentrates in Brazil, Mexico, and Argentina as these countries expand oncology infrastructure and reimbursement for molecular testing. Hospital procurement committees in São Paulo and Mexico City are consolidating vendor relationships for advanced diagnostic platforms. Cold chain distribution networks remain concentrated in major metropolitan hubs, limiting immunotherapy access in secondary cities.
Brazil
Oncology centers in São Paulo and Rio de Janeiro absorb the majority of regional immunotherapy procurement as hospital networks upgrade molecular testing capacity. ANVISA's alignment with EU-MDR technical documentation standards compresses registration timelines for novel therapeutics and companion diagnostics entering the market. Tertiary hospital laboratories in São Paulo state are deploying NGS-based profiling platforms to support precision therapy selection for muscle-invasive bladder cancer protocols.
Mexico
Mexican oncology institutes in Mexico City and Monterrey are expanding diagnostic capacity to support biomarker-driven treatment decisions in public and private hospital networks. COFEPRIS mandates local bridging studies for novel checkpoint inhibitors, extending registration timelines compared to Brazilian pathways. The Mexico City metropolitan area concentrates surgical and advanced therapeutic capacity through consolidated public hospital procurement frameworks.
Argentina
Argentine oncology institutes in Buenos Aires concentrate radical cystectomy capacity and intravesical therapy administration for non-muscle-invasive disease. Public-private partnership models are enabling risk-sharing arrangements for high-cost immunotherapy access through national health system negotiations. Urology societies are expanding training programs for robotic-assisted surgical techniques in Buenos Aires and Córdoba metropolitan clusters.
Colombia
Community urology practices and ambulatory cancer centers in Bogotá and Medellín are expanding outpatient infusion capacity to reduce hospital congestion for surveillance protocols. The country's national pharmaceutical regulator enforces varying registration standards that shape market access timelines for novel companion diagnostics. Point-of-care molecular platforms are creating decentralized diagnostic access in Colombian urban centers for post-treatment monitoring.
Chile
Molecular pathology services in Santiago are building NGS capacity to reduce sample referral abroad for genomic profiling of urothelial malignancies. The national health system evaluates cost-effectiveness frameworks for precision oncology, influencing reimbursement policy for biomarker-driven therapies. Outpatient clinics in Santiago and Valparaíso are adopting liquid biopsy platforms for less-invasive surveillance protocols in post-cystectomy patients.
Latin America Bladder Cancer Therapeutics and Diagnostics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical developers commanding premium positioning in hospital formularies while diagnostic platform vendors compete on integrated service contracts. The vendor base clusters around three strategic archetypes: multinational oncology majors with established regional infrastructure, emerging biopharma specialists leveraging clinical trial networks for market entry, and molecular diagnostic platform providers bundling equipment with bioinformatics support. Competitive moves concentrate on strategic partnerships for cold chain distribution and technology licensing for companion diagnostic co-development.
Among the multinational oncology majors, Pfizer Inc., Bristol Myers Squibb, and Merck & Co., Inc. occupy positions that exemplify distinct competitive approaches to the Latin American market. Pfizer Inc. represents the established infrastructure archetype, leveraging its historical presence across major metropolitan hospital networks. Bristol Myers Squibb exemplifies premium checkpoint inhibitor positioning within hospital procurement committees. Merck & Co., Inc. anchors the clinical trial network strategy, extending reach through regional investigator sites for pipeline development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson and Johnson |
| AstraZeneca Plc |
| Bristol Myers Squibb |
| Merck & Co., Inc. |
| Roche |
| Eli Lilly and Company |
| Novartis AG |
| GlaxoSmithKline Plc |
| Others |
Supply & Pricing Matrix
Tertiary hospital procurement committees in São Paulo, Mexico City, and Buenos Aires concentrate purchasing power for immunotherapy and molecular diagnostics, enforcing three-tier pricing structure across premium, standard, and economy levels based on cold chain capability and biomarker complexity.
Pricing Analysis
Volume concentrates in platinum-based chemotherapy while margins accrue to checkpoint inhibitors and companion diagnostics. Price differentiation rests on cold chain infrastructure requirements and NGS platform certification tiers under ANVISA and COFEPRIS standards. Cost compression in standard chemotherapy is intensifying because of biosimilar entry and tender-based public procurement. Outpatient clinics exhibit highest price sensitivity due to limited reimbursement for molecular testing, while tertiary oncology centers absorb premium pricing for integrated diagnostic-therapeutic bundles.
Supply Chain Analysis
Dual-sourcing requirements for temperature-sensitive biologics mandate that Brazilian and Mexican hospital networks qualify multiple distributors for checkpoint inhibitors. Supply draws from USA, Switzerland, and Singapore for active pharmaceutical ingredients, with regional fill-finish in Brazil and Mexico. Cold chain logistics for monoclonal antibodies and ctDNA reagents faces single-source vulnerability in secondary city last-mile delivery. Distribution runs through specialized oncology distributors with validated temperature monitoring, bypassing general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America bladder cancer market has become a vertical-integration race as manufacturers pursue captive supply of companion diagnostic platforms to secure formulary placement and pricing power.
For Market Incumbents: Anchor formulary position by acquiring or in-licensing liquid biopsy platforms to bundle diagnostic access with therapeutic procurement. Secure cold chain partnerships in Colombian and Chilean secondary cities before regional competitors establish distribution exclusivity. Backward integration into NGS reagent manufacturing reduces dependency on single-source suppliers for critical assay components. For New Entrants and Emerging Players: Regional molecular diagnostic laboratories represent the most penetrable channel partner type for point-of-care platform placement. Target outpatient urology clinics in Bogotá, Medellín, and Santiago for decentralized testing adoption where hospital laboratory capacity constraints create white space. Pursue risk-sharing contracts with Argentine public health systems to establish immunotherapy access precedents. For Investors and Strategic Acquirers: The window for entry favors clinical-stage biopharma with existing ANVISA rapporteur relationships and Brazilian investigator site networks. Long-term viability hinges on portfolio breadth across diagnostic and therapeutic modalities rather than single-asset dependency. Watch for reimbursement policy shifts in Mexico's Seguro Popular framework as the inflection signal for precision oncology market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | ANVISA-aligned technical documentation accelerates parallel approval timelines for therapeutic-diagnostic combinations. |
| Cold Chain Distribution Partnership | Specialized logistics agreements with Brazilian distributors extend checkpoint inhibitor access beyond São Paulo and Rio de Janeiro metropolitan hubs. |
| Outpatient Clinic Platform Deployment | Point-of-care molecular systems in Colombian urban centers reduce sample referral delays and capture surveillance protocol volumes. |
| Public-Private Risk Sharing Arrangement | Argentina's oncology infrastructure investments enable outcome-based contracts for high-cost immunotherapy access through national health system negotiations. |
| Molecular Pathology Workforce Training | Collaboration with Brazilian and Mexican academic medical centers builds genomic test interpretation capacity to support diagnostic scale-up. |
Research Methodology
Multi-period observation of immunotherapy procurement volumes, diagnostic platform installations, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with oncology department heads, hospital pharmacy directors, molecular pathology laboratory managers, and ANVISA regulatory consultants. Secondary validation drew from ANVISA registration databases, COFEPRIS approval records, ClinicalTrials.gov investigator site listings, and public hospital tender documentation. Bottom-up patient-flow modeling and top-down pharmaceutical sales data triangulation ensured cross-verification of market sizing assumptions.
Input-output matrices mapped treatment-line progression rates, biomarker testing penetration by hospital tier, and reimbursement policy shifts across the projection horizon. Segmentation dimensions included product type, application setting, end-user specialty, and technology platform. CAGRs were derived from fitted growth curves applied to base-year estimates, with sensitivity testing around immunotherapy displacement timelines and liquid biopsy adoption rates.
Caveats apply where ANVISA regulatory delays, COFEPRIS bridging study requirements, or cold chain infrastructure gaps could materially shift the outlook. Deviation in national health system reimbursement decisions for biomarker-driven therapies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Global Allergy Vaccine Market