
 Benign Positional Vertigo Market | 2026-2036
Benign Positional Vertigo Market Size, Share, and Industry Trends Forecast 2026-2036
Benign Positional Vertigo Market Analysis
Diagnostic-grade device certification is bifurcating the competitive landscape between established pharmaceutical manufacturers and emerging therapy device developers. Pfizer Inc. leverages its neurology portfolio breadth to sustain institutional prescribing relationships across hospital formularies. Teva Pharmaceutical Industries Ltd. competes through generic antihistamine availability, anchoring cost-sensitive treatment protocols. Dr. Reddy's Laboratories Ltd. specializes in export-oriented production, occupying price-accessible segments in emerging markets.
Benign positional vertigo constitutes a mechanical disorder of the inner ear wherein otoconia dislodge from the utricle and migrate into semicircular canals, triggering brief episodes of rotational dizziness upon specific head position changes; diagnostic confirmation relies on the Dix-Hallpike maneuver observing characteristic nystagmus patterns with latency and fatigability parameters. Medication segments address acute symptom suppression through vestibular suppressants and antiemetics, though margin pools increasingly shift toward Therapy Devices as canalith repositioning procedures gain protocol standardization. Diagnostic Tools command premium positioning where videonystagmography and digital head impulse testing integrate with electronic health record systems, while Surgical Solutions remain confined to refractory cases with established posterior semicircular canal occlusion or singular neurectomy indications.
FDA 510(k) pathways govern repositioning device approvals, requiring biomechanical efficacy demonstrations that shape product development timelines and clinical trial investments. The EU MDR transition imposes stricter post-market surveillance obligations on diagnostic tool manufacturers, redistributing compliance costs toward larger portfolio holders. WHO inclusion of vestibular disorders within rehabilitation strategy frameworks elevates national program prioritization in health system planning. Stakeholders must monitor whether telemedicine delivery modes achieve parity reimbursement with in-person canalith repositioning procedures.
Market Dynamics
Protocol standardization for canalith repositioning procedures is compressing pharmaceutical margins while elevating device-based therapy segments, as hospital formularies prioritize mechanical interventions with documented biomechanical efficacy over vestibular suppressants.
Growth Catalysts
- Geriatric Population Expansion:Aging demographics in the United States, Germany, and Japan are amplifying diagnostic volumes as vestibular dysfunction prevalence rises with advancing age.
- EU MDR Post-Market Surveillance:Stricter vigilance obligations on diagnostic tool manufacturers are consolidating compliance capabilities among larger portfolio holders, filtering out marginal competitors.
- Videonystagmography Integration:Digital head impulse testing systems with electronic health record connectivity are streamlining diagnostic confirmation protocols in tertiary care centers.
Market Restraints
- Biomechanical Efficacy Documentation:FDA 510(k) pathways demand extensive clinical trial investments that extend product development timelines for repositioning device developers.
- Generic Antihistamine Availability:Cost-sensitive treatment protocols in emerging markets anchor pharmaceutical margins at compressed levels, limiting branded therapy penetration.
- Refractory Case Surgical Confinement:Posterior semicircular canal occlusion and singular neurectomy indications apply only to narrow patient subsets, capping surgical solution addressable markets.
Strategic Opportunities
- Telemedicine Parity Reimbursement:Remote canalith repositioning procedure delivery modes await coding recognition that would unlock rural and home-based therapy markets.
- WHO Rehabilitation Framework Inclusion:Vestibular disorder prioritization in national health system planning is elevating program funding accessibility across member states.
- Sensor-Embedded Repositioning Devices:Convergence of motion tracking technology with mechanical therapy platforms enables real-time procedure guidance and outcome documentation.
Industry Challenges
- Vestibular Rehabilitation Specialist Scarcity:Trained physical therapists capable of executing Dix-Hallpike maneuvers and interpreting nystagmus patterns remain concentrated around major metropolitan medical centers.
- Legacy EHR Integration Complexity:Diagnostic-grade videonystagmography systems require custom interface development to achieve seamless data flow with institutional electronic health record architectures.
- Canalith Repositioning Certification Timelines:Clinician credentialing programs for particle repositioning maneuver administration vary across hospital networks, creating protocol inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benign Positional Vertigo Market |
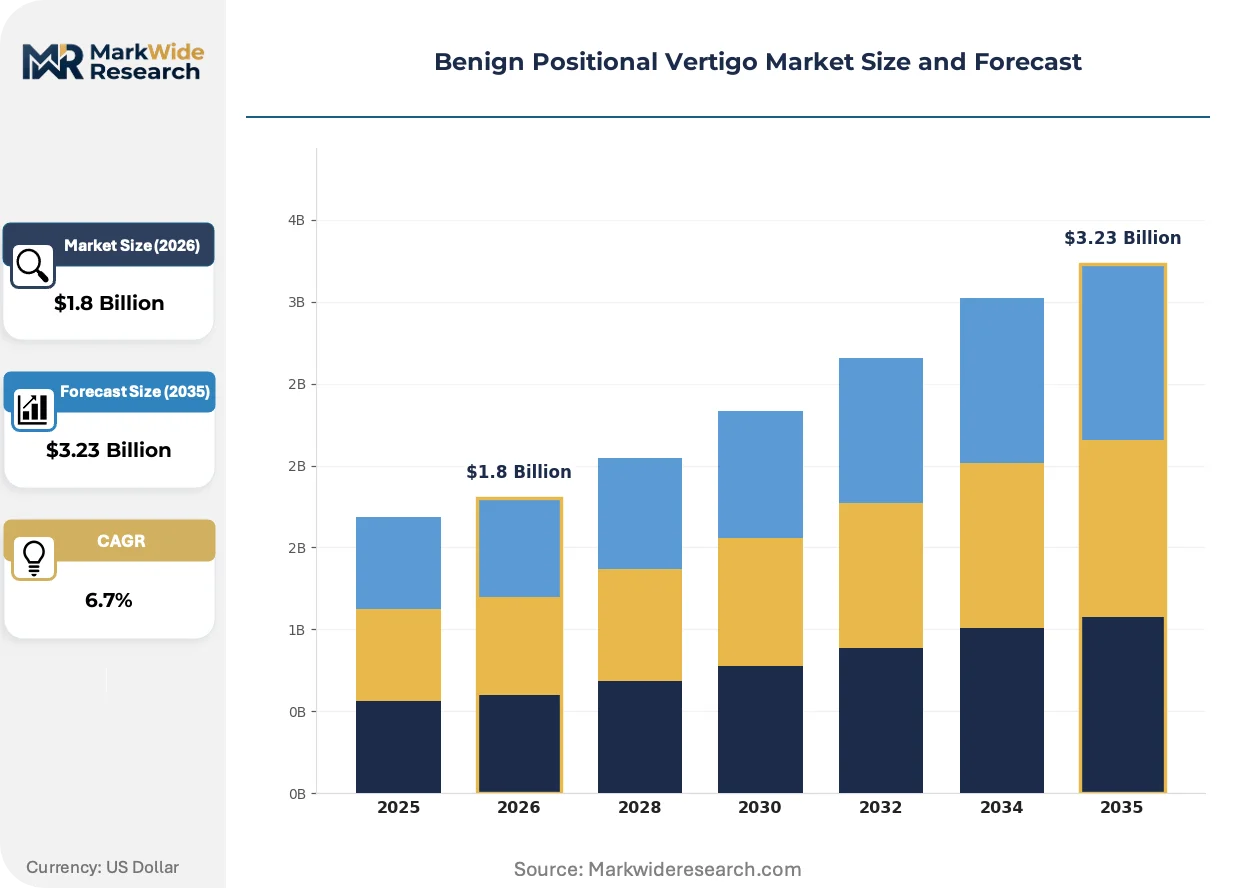
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Therapy Devices, Diagnostic Tools, Surgical Solutions Customer Type: Patients, Healthcare Providers, Hospitals, Rehabilitation Centers Delivery Mode: In-person Treatment, Telemedicine, Home Care, Hospitalization End User: Individuals, Geriatric Population, Professionals, Caregivers |
| Companies Covered | Pfizer Inc., Novartis AG, Sanofi S.A., AstraZeneca plc, GSK plc, Johnson & Johnson, Viatris Inc., Dr. Reddy’s Laboratories Ltd., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benign Positional Vertigo Market Emerging Trajectories
Digital diagnostic modalities and remote care delivery architectures are restructuring how vestibular dysfunction is confirmed and treated, shifting value capture from pharmaceutical incumbents toward device developers and platform-enabled service providers.
Sensor-augmented repositioning chairs with integrated accelerometry and gyroscopic tracking are displacing manual canalith repositioning maneuvers in high-volume vestibular clinics. Tertiary care centers in the United States and Germany are adopting these systems to standardize procedure execution and reduce clinician-dependent variability. This displacement is compressing training-intensive manual therapy revenue pools while expanding capital equipment leasing and software subscription markets.
The EU MDR transition imposes stricter post-market surveillance obligations on diagnostic tool manufacturers, redistributing compliance costs toward larger portfolio holders capable of sustaining expanded quality management systems. Manufacturers of videonystagmography and head impulse test devices must now maintain active vigilance databases and periodic safety update reporting that smaller developers cannot resource. This regulatory density is accelerating market consolidation across European diagnostic equipment supply bases.
Hospital procurement committees are unbundling after-sales service contracts from diagnostic device capital purchases, forcing manufacturers to compete on discrete maintenance and calibration pricing. Vestibular rehabilitation clinics in metropolitan United States medical centers are driving this disintermediation, preferring third-party biomedical service providers or in-house technical staff for equipment upkeep. This pattern is most visible in California and New York health systems where procurement autonomy has devolved to departmental level decision-making.
Benign Positional Vertigo Market Segmentation
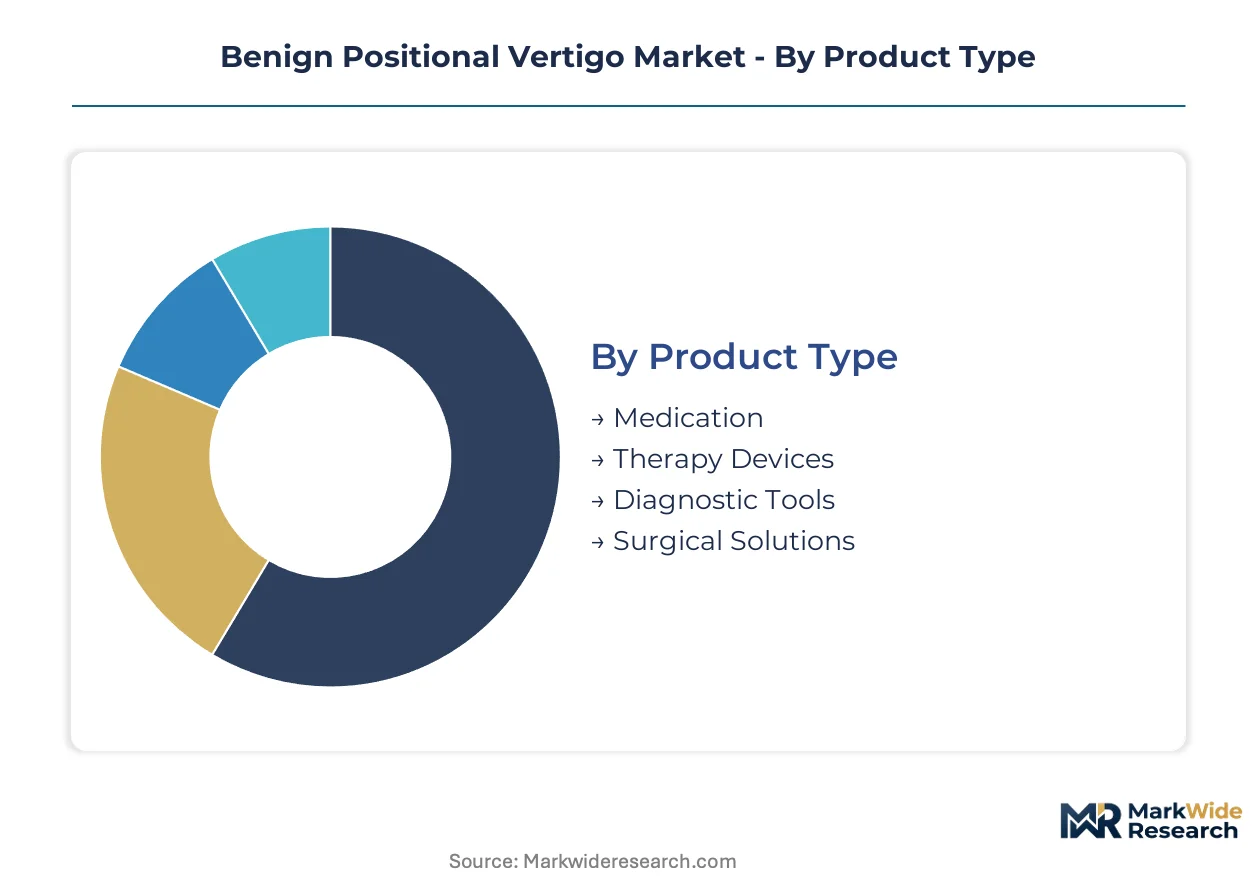
Segmentation in the benign positional vertigo market reveals divergent margin structures across mechanical versus pharmaceutical interventions. Understanding these divides enables targeted resource allocation across hospital procurement committees, rehabilitation clinic networks, and emerging telemedicine platforms.
Product Type:
Medication segments anchor cost-sensitive protocols in domestic hospital formularies, while therapy devices and diagnostic tools increasingly ship to export markets seeking FDA-cleared or CE-marked certification.
- Medication:Vestibular suppressants and antiemetics deliver acute symptom relief through oral or parenteral administration. Demand concentrates in generic antihistamine protocols across cost-constrained health systems, with branded formulations retreating to premium institutional accounts.
- Therapy Devices:Canalith repositioning chairs and sensor-embedded mechanical platforms execute particle repositioning maneuvers with standardized biomechanical force. Adoption accelerates in German and Japanese tertiary care centers seeking procedure reproducibility and reduced clinician-dependent variability.
- Diagnostic Tools:Videonystagmography systems and digital head impulse testing equipment enable Dix-Hallpike maneuver confirmation with electronic health record integration.
- Surgical Solutions:Posterior semicircular canal occlusion and singular neurectomy instruments address refractory cases failing conservative management.
Medication commands the established base. The steepest expansion runs through Therapy Devices.
Customer Type:
Procurement authority fragments across individual patients paying out-of-pocket, healthcare providers managing formularies, hospitals controlling capital budgets, and rehabilitation centers leasing equipment.
- Patients:Direct consumers access over-the-counter vestibular suppressants and home-based repositioning instruction materials. Self-directed care concentrates in United States metropolitan markets with high health literacy and disposable income.
- Healthcare Providers:Neurologists and otolaryngologists prescribe branded therapies and refer to specialized vestibular rehabilitation. Prescription volume clusters around academic medical centers with fellowship-trained specialists.
- Hospitals:Integrated delivery networks negotiate device procurement through value-analysis committees prioritizing total cost of ownership metrics.
- Rehabilitation Centers:Outpatient physical therapy clinics deliver canalith repositioning through trained vestibular specialists.
Hospitals anchor volume procurement. Rehabilitation Centers are climbing the fastest as site-of-care shifts outpatient.
Delivery Mode:
Service reimbursement patterns determine whether care flows through facility-based encounters, remote synchronous platforms, residential settings, or acute inpatient admissions.
- In-person Treatment:Clinician-administered Dix-Hallpike maneuvers and manual repositioning procedures occur in office-based settings. Capacity constraints limit throughput in vestibular specialist practices concentrated in urban medical centers.
- Telemedicine:Remote guidance platforms deliver asynchronous or synchronous repositioning instruction through video consultation. Regulatory parity for reimbursement coding remains unresolved in United States federal and state programs.
- Home Care:Self-administered Brandt-Daroff exercises and patient-directed particle repositioning reduce facility dependency. Adoption spreads among mobility-limited geriatric patients in Japan and Germany with established home health infrastructure.
- Hospitalization:Acute admission for severe vertigo with dehydration or falls occurs in emergency department observation protocols.
In-person Treatment retains the dominant share. Telemedicine holds the steepest expansion trajectory pending reimbursement clarity.
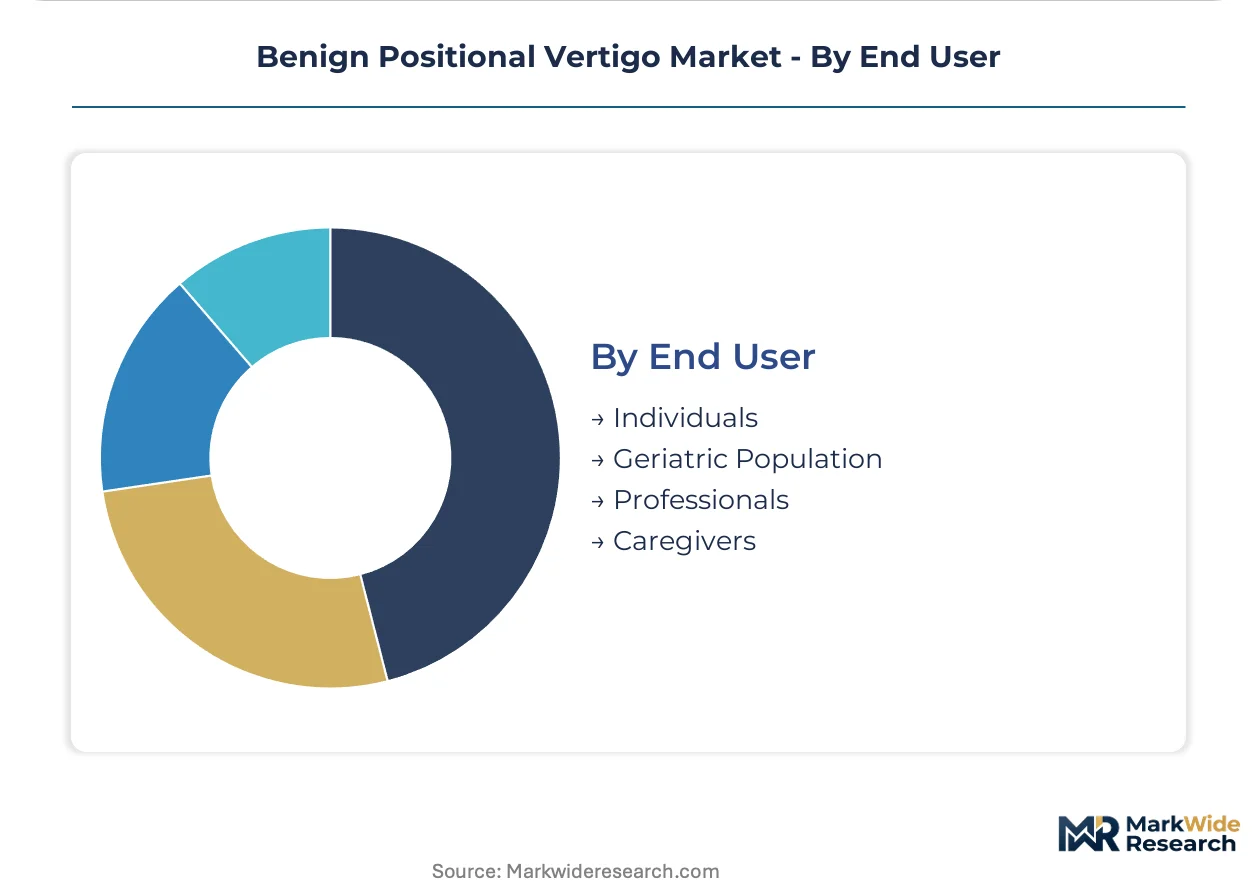
End User:
Demographic targeting separates individual sufferers seeking discrete episode resolution from population health approaches addressing age-related vestibular decline.
- Individuals:Acute episode sufferers pursue rapid symptom resolution through urgent care or emergency department pathways. Episode frequency drives repeat engagement in vestibular rehabilitation programs.
- Geriatric Population:Age-related otoconial degeneration elevates recurrence risk and fall-related morbidity. Screening protocols in United States Medicare Advantage plans and Japanese long-term care insurance programs expand diagnostic capture.
- Professionals:Pilots, surgeons, and other occupational groups requiring intact vestibular function demand expedited return-to-duty certification.
- Caregivers:Family members and home health aides assist maneuver execution for patients with limited mobility or cognitive impairment.
Geriatric Population represents the fastest-growing addressable cohort as aging demographics amplify prevalence. Individuals retain the largest absolute volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters in the United States, Germany, and Japan concentrate supply for diagnostic and therapeutic equipment serving vestibular dysfunction protocols. These three markets anchor production capacity for repositioning chairs and videonystagmography systems while shaping regulatory standards adopted elsewhere.
United States
Medicare Advantage vestibular screening programs drive diagnostic volume growth among adults over sixty-five. FDA 510(k) clearance requirements for repositioning devices impose extensive biomechanical efficacy documentation burdens on developers. Vestibular rehabilitation clinics cluster around major metropolitan medical centers in California, New York, and Massachusetts, concentrating specialist capacity in coastal health systems.
Germany
Statutory health insurance inclusion of canalith repositioning procedures sustains reimbursement stability for device-based therapy. EU MDR post-market surveillance obligations redistribute compliance costs toward larger diagnostic equipment portfolio holders. Tertiary care centers in Bavaria and North Rhine-Westphalia lead adoption of sensor-embedded repositioning chairs with integrated motion tracking.
Japan
Long-term care insurance expansion elevates national program prioritization for age-related vestibular disorders. PMDA regulatory pathways for therapeutic devices require clinical trial investments that extend market entry timelines. Rehabilitation infrastructure in the Kanto and Kansai regions supports home-based Brandt-Daroff exercise programs for mobility-limited geriatric patients.
United Kingdom
NHS England vestibular pathway standardization compresses pharmaceutical margins while elevating mechanical intervention protocols. MHRA convergence with EU MDR vigilance requirements imposes expanded quality management obligations on diagnostic tool suppliers. London and Southeast England academic medical centers concentrate fellowship-trained otolaryngology specialists capable of Dix-Hallpike maneuver interpretation.
India
Export-oriented pharmaceutical production anchors cost-sensitive antihistamine supply for emerging market treatment protocols. CDSCO regulatory frameworks for medical devices remain less stringent than FDA or EU pathways, attracting repositioning equipment assembly operations. Manufacturing clusters in Maharashtra and Gujarat supply generic vestibular suppressants to price-accessible segments across South Asia and Africa.
Benign Positional Vertigo Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the benign positional vertigo market, with established pharmaceutical manufacturers sustaining institutional prescribing relationships while emerging device developers capture margin pools shifting toward mechanical interventions. The competitive structure fragments across four distinct tiers: multinational neurology portfolio holders anchoring hospital formularies, generic manufacturers supplying cost-sensitive protocols, diagnostic equipment specialists integrating with electronic health record systems, and therapy device developers pursuing FDA 510(k) clearance pathways. Dominant competitive moves include portfolio diversification into adjacent vestibular disorder indications and strategic partnerships with rehabilitation clinic networks to secure procedure volume commitments.
Within the pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify multinational incumbents leveraging neurology portfolio breadth to sustain institutional relationships across hospital formularies. Teva Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. occupy positions among generic and export-oriented manufacturers, anchoring cost-sensitive treatment protocols in emerging markets and price-accessible segments. These four companies represent the dominant archetypes—branded portfolio holders, generic suppliers, and emerging market specialists—that structure competitive dynamics across medication and device segments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Sanofi S.A. |
| AstraZeneca plc |
| GSK plc |
| Johnson & Johnson |
| Viatris Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term equipment leasing contracts with embedded maintenance provisions lock in supply access for repositioning chairs and videonystagmography systems while anchoring price visibility across German and Japanese tertiary care centers. These arrangements insulate buyers from spot-market volatility in motion-sensor components while compressing margins for device developers unable to secure volume commitments.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across repositioning device segments, separating premium-certified platforms from economy-grade alternatives lacking biomechanical efficacy documentation. Price differentiation hinges on certification grade and after-sales service bundling, with hospital procurement committees demanding discrete maintenance pricing. Cost compression in the generic antihistamine segment is intensifying because of export-oriented production from Indian manufacturers. Emerging market healthcare providers exhibit the highest price sensitivity, while United States academic medical centers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for motion-sensor components sourced from Taiwanese and South Korean semiconductor foundries. Manufacturing concentration in the United States, Germany, and Japan draws from precision-machined frames, piezoelectric sensors, and medical-grade upholstery textiles. Single-source vulnerability in accelerometer supply creates exposure to allocation constraints. Distribution runs through hospital value-analysis committees and rehabilitation clinic leasing networks rather than direct manufacturer-to-provider sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as FDA 510(k) clearance timelines and EU MDR post-market surveillance obligations create structural barriers that marginal competitors cannot resource.
For Market Incumbents: Secure canalith repositioning procedure volume commitments through exclusive partnerships with metropolitan vestibular rehabilitation clinic networks. Deepen backward integration into motion-sensor component supply to insulate against Taiwanese foundry allocation constraints. The threat of sensor-embedded repositioning chairs displacing manual therapy platforms demands accelerated R&D investment in real-time procedure guidance software. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for repositioning devices with predicate-device equivalence offer the most penetrable regulatory entry point. Target rural United States markets awaiting telemedicine parity reimbursement coding, where incumbent presence remains thin. A software-as-a-service companion platform for home-based Brandt-Daroff exercise guidance provides a capital-light go-to-market angle bypassing capital equipment procurement cycles. For Investors and Strategic Acquirers: Device developers with cleared repositioning platforms and established hospital system pilot programs represent the highest-probability acquisition targets for portfolio diversification into mechanical therapy segments. Long-term viability over the next decade rests on whether telemedicine delivery achieves reimbursement parity with in-person procedures. The signal to monitor is CMS coding recognition for remote canalith repositioning, which would inflect addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance obligations favor larger portfolio holders with quality management infrastructure. |
| Hospital System Partnership | Exclusive volume commitments with German statutory insurance networks secure procedure reimbursement stability. |
| Software Companion Development | Real-time motion tracking integration with repositioning chairs reduces clinician-dependent variability in Japan. |
| Reimbursement Strategy | Telemedicine parity coding advocacy unlocks rural United States markets currently constrained by in-person capacity. |
| FDA Submission | Biomechanical efficacy documentation requirements extend timelines but create regulatory entrenchment against marginal entrants. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vestibular rehabilitation specialists, hospital biomedical engineers, GPO contracts managers, and otolaryngology department heads. Secondary validation drew from FDA 510(k) clearance databases, EU MDR vigilance reports, CMS Medicare reimbursement coding updates, and hospital procurement committee minutes. Bottom-up procedure volume estimates and top-down equipment shipment data were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, delivery mode, end-user demographic, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and capital equipment replacement cycles. Industry-specific inputs included Medicare Advantage vestibular screening penetration rates and Japanese long-term care insurance expansion timelines.
Decision-makers should treat outputs as directional under assumptions of stable FDA clearance timelines and sustained statutory insurance reimbursement; material deviation in either would warrant model refresh. Specific risks include EU MDR enforcement intensity variations and telemedicine coding recognition delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market