
 Bronchiectasis Therapeutic Market | 2026-2036
Bronchiectasis Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchiectasis Therapeutic Market Outlook
Respiratory therapist specialization in airway clearance techniques is reorganizing how bronchiectasis care gets delivered across acute and chronic settings. Insmed leverages its deep focus on inhaled liposomal amikacin to anchor the rare disease segment for treatment-refractory patients. AstraZeneca competes through its established respiratory portfolio, while Gilead Sciences sustains clinical development momentum with antiviral and anti-inflammatory programs that extend into chronic lung infections.
Bronchiectasis therapeutics encompass pharmacological agents designed to manage chronic bacterial infection, reduce inflammation, improve mucus clearance, and preserve lung function in patients with irreversibly dilated airways; inhaled formulations must achieve particle sizes of 1–5 microns to reach peripheral bronchi effectively. The antibiotics segment dominates current prescribing, particularly long-term suppressive regimens against Pseudomonas aeruginosa, while the inhalation delivery mode captures the fastest growth trajectory due to targeted lung deposition and reduced systemic exposure. Homecare settings represent an emerging margin pool as payors push for outpatient chronic disease management.
FDA orphan drug incentives and EMA's parallel designation framework shape development economics by extending market exclusivity for novel bronchiectasis therapies. The EPA regulates manufacturing emissions for active pharmaceutical ingredient synthesis, adding compliance cost layers to antibiotic production. GSK and Boehringer Ingelheim navigate these dual regulatory environments while positioning nebulized and dry-powder platforms. Stakeholders must monitor how CMS reimbursement rules for home nebulization reshape patient access and manufacturer channel strategy.
Market Dynamics
Hospital pulmonology departments are consolidating chronic airway disease protocols around inhaled liposomal formulations, creating a structural pull toward nebulized delivery platforms that reduce systemic antibiotic exposure while targeting peripheral bronchi.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates novel inhaled antibiotic development by extending market exclusivity for therapies addressing treatment-refractory bronchiectasis populations.
- Homecare Nebulization:CMS reimbursement rules for outpatient chronic disease management are expanding patient access to home-based airway clearance and antibiotic delivery systems.
- Cystic Fibrosis-Related Demand:Specialist prescribing in the United States concentrates around Pseudomonas aeruginosa suppressive regimens, anchoring volume for long-term antibiotic maintenance therapy.
Market Restraints
- API Manufacturing Compliance:EPA emissions regulations for active pharmaceutical ingredient synthesis add cost layers to antibiotic production, compressing margins for generic manufacturers.
- Particle Engineering Complexity:Inhaled formulations require precise 1–5 micron particle sizing to reach peripheral bronchi, limiting formulation options and creating technical barriers to bioequivalence.
- Specialist Concentration:Prescribing authority concentrates in academic medical center pulmonology departments, restricting market access for therapies lacking KOL advocacy networks.
Strategic Opportunities
- Respiratory Therapist Specialization:Certification programs in airway clearance techniques are creating a new clinical workforce capable of managing bronchiectasis across acute-to-chronic care transitions.
- Dry-Powder Inhaler Platforms:Nebulized delivery is converging with portable dry-powder devices, enabling patient mobility while maintaining peripheral lung deposition targets.
- EMA Parallel Designation:The European framework mirrors FDA orphan incentives, opening development economics for therapies targeting non-CF bronchiectasis subpopulations.
Industry Challenges
- Clinical Trial Endpoint Standardization:Regulatory acceptance of exacerbation frequency versus quality-of-life measures remains inconsistent across FDA and EMA review divisions, prolonging Phase III design negotiations.
- Inhaler Device Integration:Nebulization systems must interface with electronic health record platforms for adherence monitoring, requiring cross-functional engineering teams with scarce combined competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchiectasis Therapeutic Market |
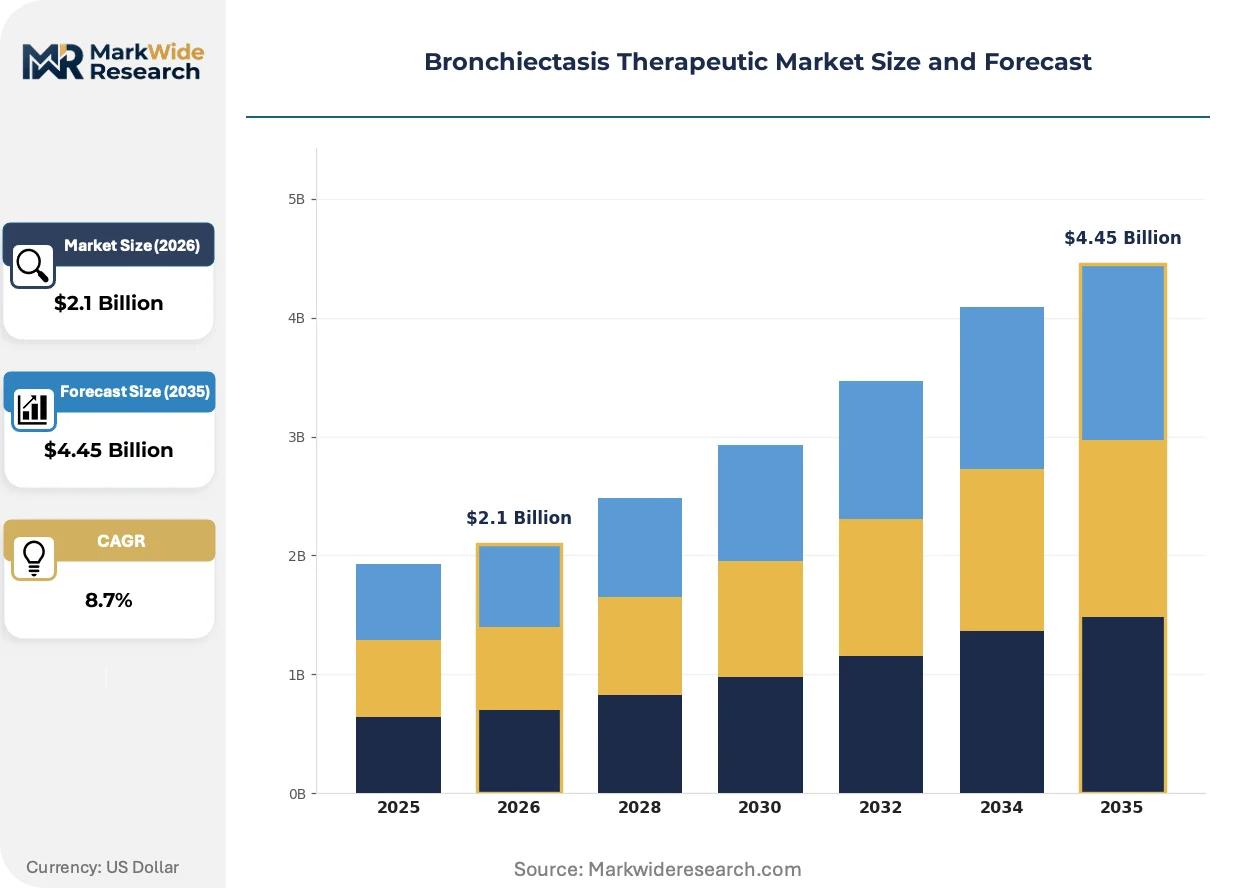
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Bronchodilators, Corticosteroids, Mucolytics End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Delivery Mode: Inhalation, Oral, Intravenous, Nebulization Application: Pediatric, Adult, Acute Management, Chronic Care |
| Companies Covered | Insmed, AstraZeneca, Gilead Sciences, Boehringer Ingelheim, Sanofi, Zambon, Chiesi Farmaceutici, Pfizer, GSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchiectasis Therapeutic Market Strategic Shifts
Liposomal encapsulation technology is actively restructuring how aminoglycosides achieve therapeutic lung concentrations without nephrotoxic systemic exposure, forcing incumbent formulation strategies toward particle engineering investments.
Nebulized liposomal amikacin is decomposing the traditional intravenous-to-oral antibiotic ladder for Pseudomonas-colonized patients. Academic medical centers in the United States are adopting this platform for treatment-refractory cases within 18-month implementation windows. The technology is compressing hospital length-of-stay metrics while expanding the addressable chronic suppressive therapy population.
EMA's parallel orphan designation framework is harmonizing with FDA incentives to reduce regulatory friction for cross-border therapy development. Manufacturers now face consolidated clinical data requirements rather than duplicative pediatric investigation plans. Non-CF bronchiectasis indications in Europe are responding with accelerated protocol designs that leverage US-generated safety databases.
Specialist prescribing patterns are rotating toward value-based contract structures that tie reimbursement to exacerbation reduction rather than drug volume. Hospital systems in the United States are unbundling pharmacy benefits from bundled payment arrangements for chronic airway diseases. Pulmonology departments in academic centers are most visibly adopting risk-sharing arrangements with manufacturers for inhaled antibiotic formularies.
Bronchiectasis Therapeutic Market Segmentation
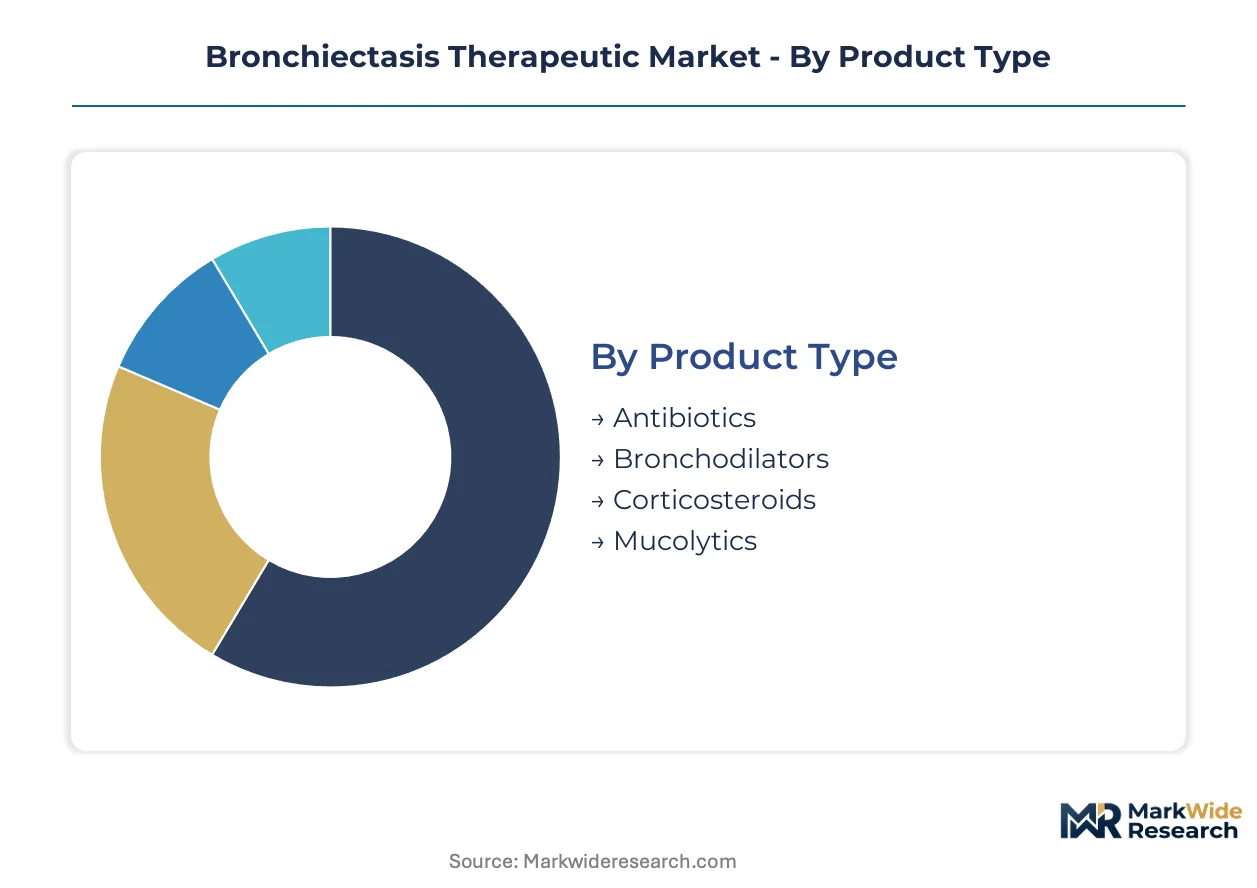
Therapeutic segmentation in bronchiectasis reveals distinct procurement patterns across acute and chronic care settings. Product type and delivery mode configurations determine reimbursement pathways and manufacturing investment priorities.
Product Type:
Antibiotics dominate domestic prescribing volumes in the United States, while mucolytic demand concentrates in European outpatient protocols where airway clearance reimbursement differs.
- Antibiotics:Long-term suppressive regimens target Pseudomonas aeruginosa colonization in cystic fibrosis-related bronchiectasis. Hospital pulmonology departments in the United States anchor volume for inhaled liposomal formulations with orphan drug designation.
- Mucolytics:Agents like hypertonic saline and dornase alfa modify mucus rheology to improve clearance. European homecare reimbursement frameworks in Germany and France accelerate adoption of nebulized mucolytic maintenance therapy.
- Bronchodilators:Beta-agonist and anticholinergic therapy provides symptomatic relief for reversible airway obstruction.
- Corticosteroids:Inhaled and oral formulations manage inflammatory exacerbations in non-CF bronchiectasis subpopulations.
Antibiotics holds the largest share; momentum sits with mucolytics as homecare protocols expand.
End User:
Cost tier stratification separates acute intervention sites from chronic management venues, with reimbursement rates determining formulary access for inhaled therapies.
- Hospitals:Academic medical center pulmonology departments consolidate chronic airway disease protocols around nebulized liposomal platforms. FDA orphan drug incentives drive specialist prescribing concentration in United States tertiary care centers.
- Homecare:CMS reimbursement rules for outpatient nebulization reshape patient access and manufacturer channel strategy. Portable delivery devices enable chronic suppressive therapy outside institutional settings.
- Clinics:Community pulmonology practices manage stable patients between exacerbation events.
- Long-term Care Facilities:Skilled nursing settings address bronchiectasis in elderly populations with comorbid respiratory conditions.
Hospitals capture the highest acuity cases; homecare is climbing the fastest as payors shift chronic disease management downstream.
Delivery Mode:
Volume concentration follows particle engineering capabilities, with 1–5 micron sizing requirements limiting formulation options for peripheral lung deposition.
- Inhalation:Dry-powder and metered-dose devices target portable chronic therapy. Patient mobility requirements in the United States and United Kingdom drive convergence toward handheld platforms that maintain peripheral deposition targets.
- Nebulization:Jet and mesh systems deliver liposomal encapsulations for treatment-refractory cases. EPA emissions regulations for active pharmaceutical ingredient synthesis add compliance cost layers to nebulized antibiotic production.
- Oral:Systemic antibiotics and corticosteroids serve initial exacerbation management and maintenance suppression.
- Intravenous:Reserved for acute exacerbations requiring hospital admission and intensive monitoring.
Inhalation holds the largest share; momentum sits with nebulization as liposomal formulations penetrate treatment-refractory populations.
Application:
Customer type segmentation separates pediatric cystic fibrosis protocols from adult non-CF bronchiectasis management, with distinct clinical trial endpoints shaping development economics.
- Chronic Care:Long-term suppressive therapy preserves lung function in irreversibly dilated airways. EMA parallel orphan designation frameworks in Europe harmonize with FDA incentives to reduce regulatory friction for cross-border therapy development.
- Acute Management:Exacerbation treatment requires rapid antibiotic escalation and airway clearance intervention. Hospital length-of-stay metrics compress with nebulized liposomal amikacin adoption in United States academic centers.
- Pediatric:Cystic fibrosis-related bronchiectasis drives specialist prescribing with distinct growth and development considerations.
- Adult:Non-CF bronchiectasis subpopulations expand the addressable market as aging demographics and prior infection sequelae accumulate.
Chronic care holds the largest share; acute management is expanding most quickly as exacerbation reduction becomes the reimbursement metric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives anchor the United States as the dominant geography, with specialist prescribing concentrating in academic medical center pulmonology departments. EMA parallel frameworks in Europe and expanding homecare reimbursement in Asia-Pacific create differentiated growth vectors across national healthcare systems.
United States
Cystic fibrosis-related bronchiectasis drives specialist prescribing volume for Pseudomonas aeruginosa suppressive regimens. CMS reimbursement rules for outpatient nebulization reshape patient access and manufacturer channel strategy. Boston and Baltimore academic medical centers adopt nebulized liposomal platforms within 18-month implementation windows.
Germany
European homecare reimbursement frameworks accelerate adoption of nebulized mucolytic maintenance therapy in outpatient protocols. EMA parallel orphan designation harmonizes with FDA incentives to reduce regulatory friction for cross-border therapy development. The Rhine-Ruhr metropolitan region concentrates respiratory specialist practices managing non-CF bronchiectasis subpopulations.
United Kingdom
Patient mobility requirements drive convergence toward handheld dry-powder platforms that maintain peripheral lung deposition targets. NICE technology appraisals influence formulary access for inhaled antibiotic therapies across NHS trusts. London and Manchester academic centers anchor clinical trial recruitment for novel bronchiectasis indications.
Japan
Aging demographics and prior infection sequelae expand the addressable non-CF bronchiectasis population in adult respiratory clinics. PMDA review pathways for orphan respiratory indications align with international regulatory convergence trends. The Kanto region around Tokyo concentrates specialist pulmonology capacity and pharmaceutical development partnerships.
Australia
TGA regulatory acceptance of US-generated safety databases enables accelerated protocol designs for non-CF bronchiectasis therapies. Remote patient monitoring infrastructure supports homecare nebulization adoption in dispersed populations. Sydney and Melbourne medical research institutes collaborate on airway clearance technique certification programs.
Bronchiectasis Therapeutic Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the bronchiectasis therapeutic market. Large-cap pharmaceutical companies with established respiratory portfolios compete against rare-disease specialists focused on inhaled formulation technologies. Three archetypes dominate: liposomal encapsulation specialists, broad respiratory portfolio holders, and antiviral-anti-inflammatory program developers. Competitive moves concentrate on nebulized delivery platform partnerships and orphan drug designation acquisitions.
Within the rare-disease specialist tier, Insmed anchors liposomal amikacin development for treatment-refractory populations. AstraZeneca and Gilead Sciences represent the integrated pharmaceutical archetype, with the former leveraging established respiratory infrastructure and the latter extending antiviral development momentum into chronic lung infection management.
| Leading Market Players |
|---|
| Insmed |
| AstraZeneca |
| Gilead Sciences |
| Boehringer Ingelheim |
| Sanofi |
| Zambon |
| Chiesi Farmaceutici |
| Pfizer |
| GSK |
| Others |
Value Chain & Pricing Dynamics
Liposomal encapsulation technology displacing conventional aminoglycoside formulations is redrawing manufacturing footprints toward FDA-inspected sterile facilities in the United States and Ireland while compressing margins for generic intravenous antibiotic producers in India and China.
Pricing Analysis
Long-term offtake agreements between hospital systems and liposomal amikacin manufacturers anchor pricing stability for orphan-designated therapies, while spot purchasing for generic nebulized antibiotics exposes community clinics to API cost volatility. Price differentiation hinges on FDA orphan exclusivity status and respiratory therapist certification requirements bundled with device training. Cost compression in the generic antibiotic tier intensifies as EPA emissions compliance raises API synthesis expenses. Academic medical centers show lowest price sensitivity due to bundled payment structures; skilled nursing facilities face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of liposomal formulations by United States hospital systems contrasts with just-in-time inventory practices for European mucolytic homecare deliveries. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with sterile finished-dose manufacturing anchored in Ireland, the United States, and Italy. Supply chains draw from amikacin base compounds, phospholipid excipients, and specialized nebulizer mesh components. Single-source vulnerability sits with liposome manufacturing capacity for orphan-designated products. Distribution runs through hospital-specialty pharmacy channels in the United States and direct-to-patient homecare logistics in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Homecare nebulization adoption represents an early-cycle expansion opportunity as CMS reimbursement rules and respiratory therapist certification programs extend chronic suppressive therapy beyond hospital walls.
For Market Incumbents: Fortify formulary position through backward integration into liposome manufacturing capacity and captive respiratory therapist training academies. Generic antibiotic price erosion and emerging dry-powder inhaler platforms threaten nebulized market share. Priority investment in EMA parallel orphan designation pathways secures European exclusivity buffers. For New Entrants and Emerging Players: Differentiate on portable dry-powder device engineering for non-CF bronchiectasis populations underserved by current nebulization burden. Adult non-CF subpopulations in Japan and Australia present the most penetrable expansion geography. Go-to-market through pulmonology telehealth platforms bypasses academic medical center gatekeeping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed respiratory device manufacturers possessing nebulizer-drug combination product expertise but lacking pipeline depth. Five-to-ten year viability frames around exacerbation-reduction reimbursement metrics and homecare channel control. Watch FDA breakthrough therapy designation velocity for non-CF indications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Acquisition | FDA exclusivity extension secures pricing power for liposomal antibiotic platforms. |
| Respiratory Therapist Certification Program | Training infrastructure creates sticky hospital system relationships and device lock-in. |
| Dry-Powder Inhaler Platform Development | Patient mobility requirements in United Kingdom and United States drive handheld adoption. |
| EMA Parallel Designation Filing | Harmonized regulatory pathway reduces duplicative clinical costs for European entry. |
| Homecare Nebulization Partnership | CMS reimbursement alignment expands addressable chronic suppressive therapy population. |
Study Parameters
A standing panel of pulmonology department directors, respiratory therapy program leads, hospital formulary managers, and orphan drug regulatory specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA orphan drug designations, EMA parallel designation frameworks, ClinicalTrials.gov bronchiectasis protocols, and CMS Medicare reimbursement databases. Bottom-up prescribing volume estimates triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from patient population epidemiology, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated respiratory therapist workforce expansion rates and homecare reimbursement policy shifts.
The analysis sits within stated boundaries; outcomes outside stable FDA orphan incentive structures and CMS outpatient nebulization coverage would require recalibration. Forecasts reflect documented assumptions regarding liposomal formulation adoption velocity and exacerbation-reduction reimbursement metric adoption. Revision becomes warranted when EPA API manufacturing compliance costs cross thresholds that trigger generic antibiotic supply discontinuation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Hypothyroidism Market