
 Vertigo Market | 2026-2036
Vertigo Market Size, Share, and Industry Trends Forecast 2026-2036
Vertigo Market Intelligence
MDR compliance is hardening the cost-of-entry calculus for diagnostic device entrants targeting European reimbursement. Pfizer Inc. leverages its neurology franchise to sustain formulary positioning across major hospital systems. Novartis AG anchors its presence through specialized otology partnerships in tertiary care networks. Sanofi competes on primary care channel density, where betahistine access remains concentrated.
Vertigo encompasses pathological sensations of rotational or positional imbalance arising from peripheral vestibular, central neurological, or systemic vascular dysfunction, typically quantified through videonystagmography gain values and caloric response asymmetry ratios exceeding 25%. The condition drives clinical intervention to restore postural stability, prevent fall-related trauma, and preserve occupational function in affected populations. Medications retain the largest revenue footprint due to chronic prescription patterns in Meniere's Disease management, while Virtual Reality segments capture the fastest expansion as immersive balance training protocols migrate from rehabilitation centers into home care settings. Diagnostic Devices command premium pricing where vestibular evoked myogenic potential testing differentiates central from peripheral etiologies.
FDA digital health guidance, MDR technical documentation requirements, and ISO 13485 quality management standards collectively shape product development timelines and market access conditions for device manufacturers. The EPA and OSHA indirectly influence occupational vertigo claims through workplace fall-protection mandates that drive employer-funded diagnostic screening. Stakeholders must weigh regulatory capital requirements against the margin compression that follows commoditized pharmacotherapy genericization.
Market Dynamics
The FDA's evolving guidance on digital therapeutics is compressing reimbursement timelines for VR-based balance training systems while simultaneously raising clinical evidence thresholds for market entry.
Growth Catalysts
- Expanded Medicare Coverage:Fall-risk assessment reimbursement codes in the United States are channeling capital toward outpatient diagnostic devices and vestibular rehabilitation protocols.
- ISO 13485 Alignment:Quality management standardization is accelerating device manufacturer readiness for MDR technical documentation in European markets.
- Vestibular Evoked Myogenic Potential Testing:This diagnostic modality differentiates central from peripheral vertigo etiologies, commanding premium pricing in tertiary care networks.
Market Restraints
- MDR Compliance Burden:European technical documentation requirements harden cost-of-entry calculus for diagnostic device entrants targeting reimbursement pathways.
- Generic Substitution Pressure:Commoditized betahistine formulations compress margin structures in primary care channels where chronic Meniere's Disease prescriptions concentrate.
- Workforce Training Gaps:Specialized otology expertise scarcity limits vestibular rehabilitation protocol deployment velocity across hospital systems.
Strategic Opportunities
- Home Care Migration:Immersive balance training protocols are electrifying the shift from rehabilitation centers into residential settings, opening direct-to-patient revenue streams.
- German Hospital Adoption:Vestibular rehabilitation protocol expansion across German tertiary networks creates anchor demand for integrated diagnostic-therapeutic platforms.
- Digital Therapeutic Pathways:FDA guidance clarity on software-as-medical-device classification is enabling reimbursement codes for remote patient monitoring applications.
Industry Challenges
- Clinical Evidence Generation:Randomized controlled trial requirements for digital therapeutic submissions extend development timelines and inflate capital requirements.
- Legacy Device Interoperability:Videonystagmography systems with proprietary data formats resist integration with cloud-based analytics platforms, fragmenting patient record continuity.
- Calibration Standardization:Caloric response asymmetry ratio measurement variance across equipment manufacturers complicates multi-site clinical trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertigo Market |
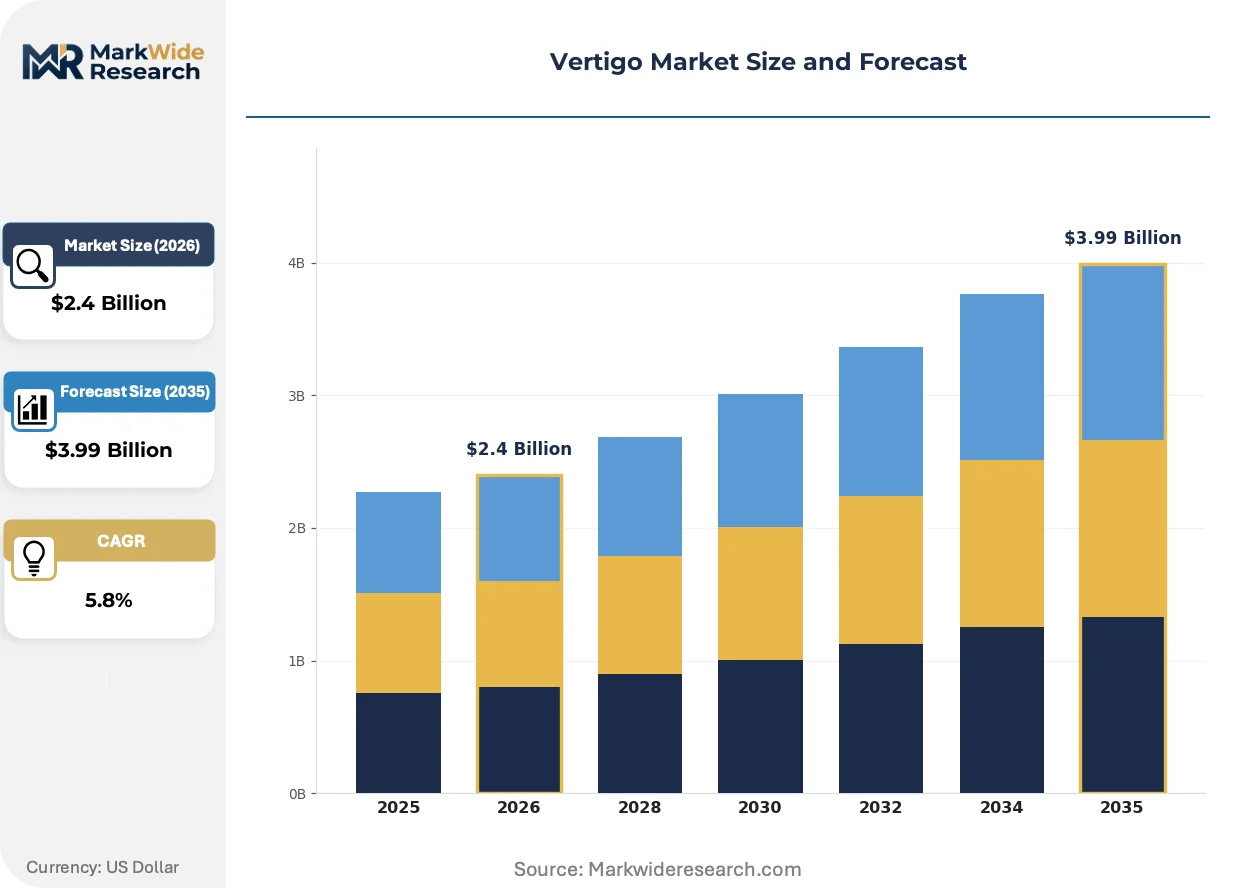
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physical Therapy, Surgical Treatments, Diagnostic Devices Technology: Vestibular Rehabilitation, Virtual Reality, Telemedicine, Wearable Devices End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Application: Meniere's Disease, Benign Paroxysmal Positional Vertigo, Vestibular Neuritis, Others |
| Companies Covered | Pfizer Inc., Viatris Inc., Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc., AstraZeneca plc., Sun Pharmaceutical Industries Ltd., Epic Pharma, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertigo Market Strategic Shifts & Innovations
Immersive computing platforms are restructuring where vestibular rehabilitation occurs, while regulatory clarity on software-based interventions redefines competitive moats for device and pharmaceutical developers alike.
Virtual Reality balance training systems are electrifying the therapeutic landscape by delivering customizable, intensity-modulated vestibular stimulation protocols previously confined to specialized rehabilitation centers. Hospital systems in Japan and the United States are piloting these platforms for post-acute care discharge protocols, compressing length-of-stay metrics while extending therapeutic touchpoints into patient homes. This modality shift is enabling outcome-based contracting structures that tie reimbursement to measurable fall-reduction metrics rather than device rental fees.
MDR technical documentation requirements are reshaping European market access conditions for vestibular diagnostic manufacturers, mandating clinical performance studies that exceed predecessor Medical Device Directive standards. The regulation forces device developers to generate prospective data on sensitivity and specificity metrics for central versus peripheral vertigo differentiation. German and French notified bodies are applying these standards most stringently, creating a two-tier market where MDR-certified devices command pricing premiums over legacy-cleared competitors.
Employer-funded diagnostic screening is gaining traction as OSHA workplace fall-protection mandates intersect with aging workforce demographics in manufacturing and logistics sectors. Third-party occupational health providers are bundling vestibular function assessments with existing hearing conservation programs, displacing reactive post-incident evaluation models. This procurement pattern is most visible in the United States, where workers' compensation cost containment incentives align with Medicare preventive service expansion for Medicare-eligible employees.
Vertigo Market Segmentation
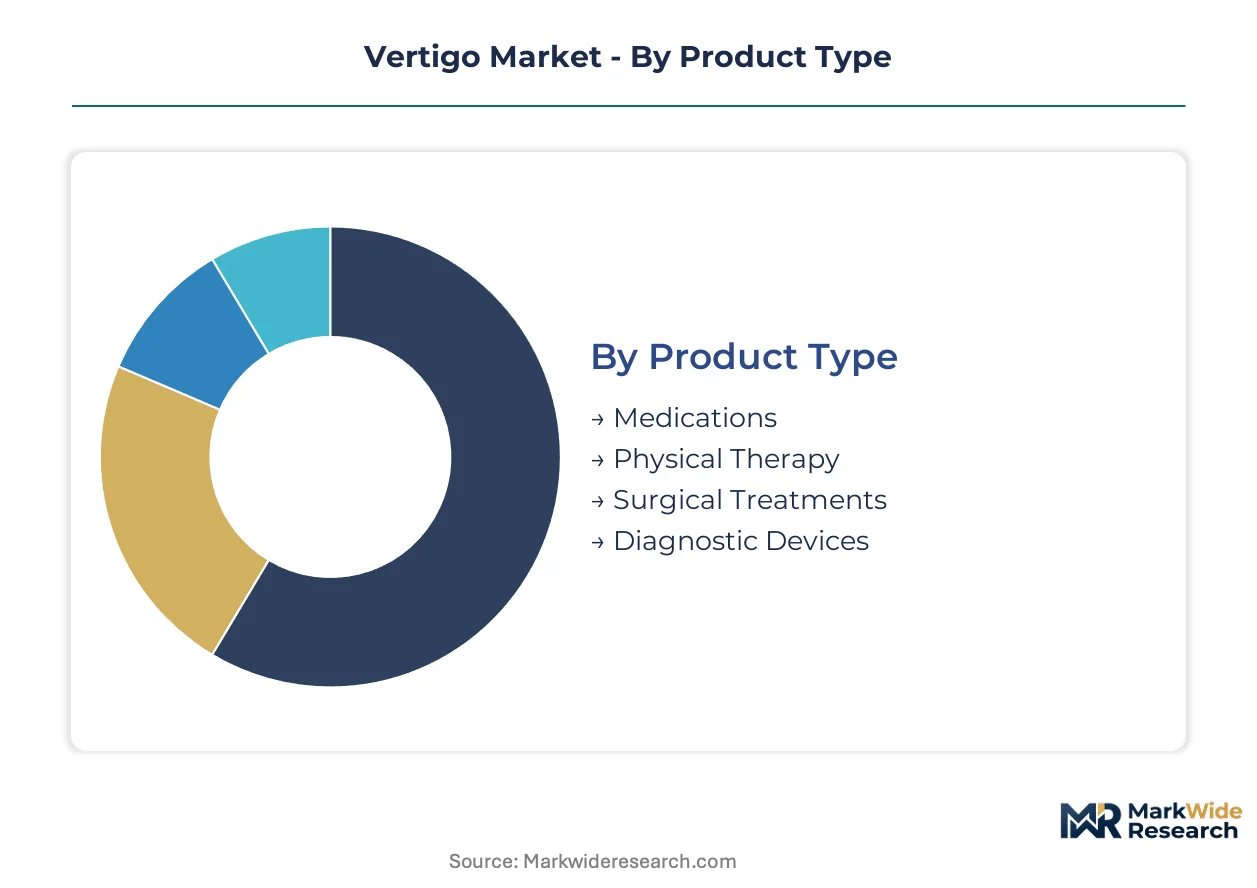
Segmentation in the vertigo market reveals distinct procurement patterns across acute intervention, chronic management, and diagnostic workflows. Each dimension—product type, technology, end user, and application—carries unique reimbursement codes, regulatory pathways, and margin structures that shape vendor positioning.
Product Type:
Standalone pharmaceutical interventions operate through established formulary channels, while embedded diagnostic-therapeutic platforms require integrated purchasing committees.
- Medications:Chronic prescription patterns for betahistine and antiemetic protocols dominate Meniere's Disease maintenance. Demand concentrates in primary care networks across the United States and Germany, where formulary positioning determines market access.
- Physical Therapy:Vestibular rehabilitation protocols deliver customized habituation exercises through specialist-led sessions. Hospital systems in Japan and the United States are expanding outpatient PT capacity to reduce acute readmission rates.
- Surgical Treatments:Labyrinthectomy and vestibular nerve section procedures address refractory cases. Tertiary otology centers perform these interventions.
- Diagnostic Devices:Videonystagmography and vestibular evoked myogenic potential systems differentiate central from peripheral etiologies. MDR certification requirements in Europe are compressing vendor margins.
Medications lead volumes today; Diagnostic Devices are gaining share fastest.
Technology:
Cost tiers separate capital-intensive hardware installations from software-enabled remote delivery models.
- Vestibular Rehabilitation:Specialist-directed balance training protocols utilize habituation exercises and gaze stabilization drills. Rehabilitation centers in German hospital networks anchor demand for certified protocol delivery.
- Virtual Reality:Immersive platforms modulate visual-vestibular conflict through customizable intensity parameters. FDA digital therapeutic guidance is accelerating reimbursement pathway development for home-based deployment.
- Telemedicine:Remote consultation platforms extend specialist reach into underserved regions. Rural health systems in the United States leverage these tools.
- Wearable Devices:Ambulatory balance monitors capture real-time postural sway data. Medicare preventive service expansion is creating procurement incentives.
Vestibular Rehabilitation commands premium pricing today; Virtual Reality is climbing the fastest.
End User:
Customer type determines procurement authority—hospital purchasing committees versus individual patient acquisition.
- Hospitals:Integrated health systems deploy comprehensive diagnostic-therapeutic platforms across otology and neurology departments. Tertiary networks in Germany and Japan are standardizing vestibular rehabilitation protocols.
- Clinics:Outpatient facilities concentrate on diagnostic workup and initial therapeutic intervention. United States Medicare reimbursement codes for fall-risk assessment are channeling investment here.
- Rehabilitation Centers:Dedicated facilities deliver intensive balance training protocols. These centers are migrating toward VR-enabled home discharge models.
- Home Care:Residential settings are adopting telemedicine and wearable monitoring for chronic condition management. Direct-to-patient revenue streams are emerging.
Hospitals lead volumes today; Home Care is expanding most quickly.
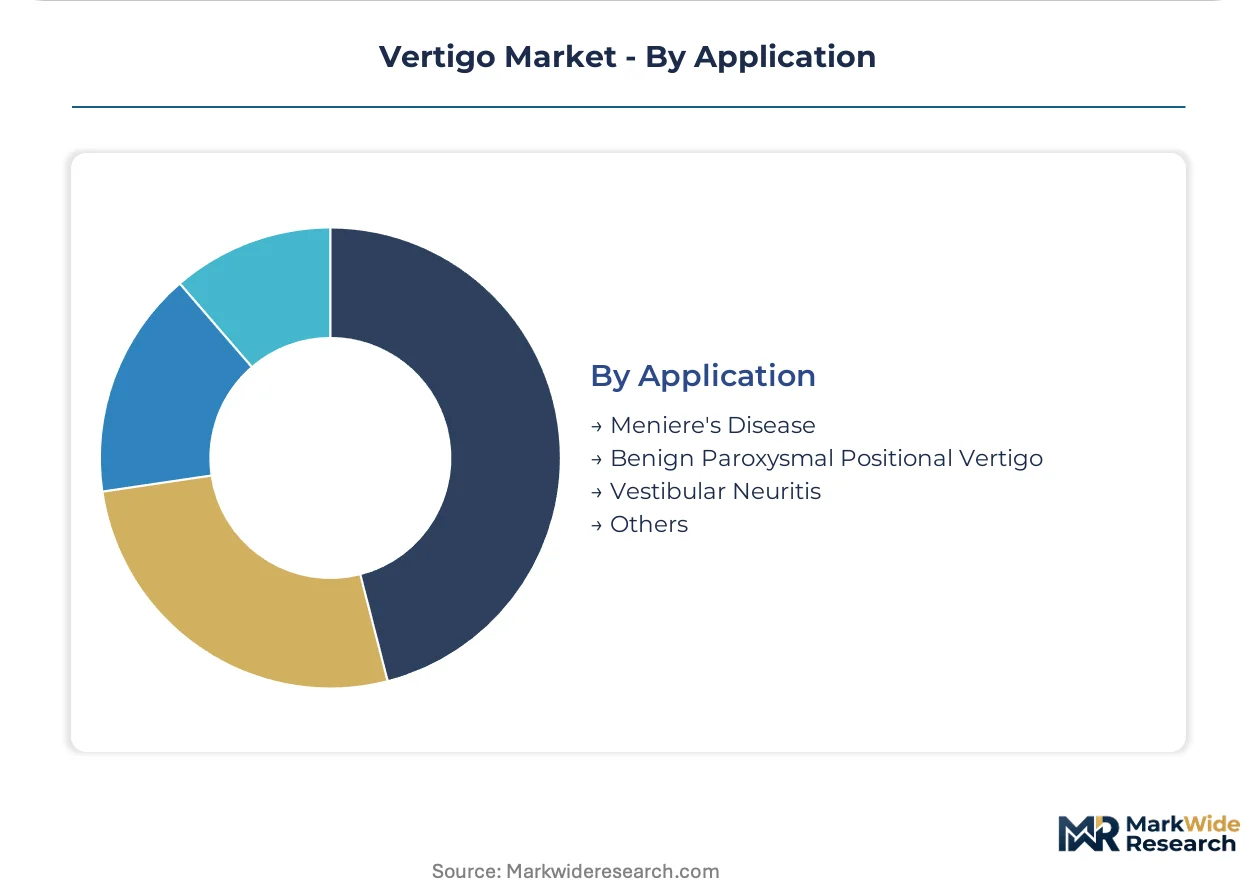
Application:
Disease-specific pathways dictate diagnostic intensity and therapeutic duration, creating distinct margin profiles.
- Meniere's Disease:Chronic endolymphatic hydrops requires long-term pharmaceutical management and intermittent surgical intervention. Prescription volumes concentrate in primary care channels where generic betahistine availability shapes pricing.
- Benign Paroxysmal Positional Vertigo:Canalith repositioning maneuvers deliver rapid symptomatic resolution. Outpatient clinics in the United States perform these procedures at high volume with minimal capital requirements.
- Vestibular Neuritis:Acute viral or ischemic insult to the vestibular nerve demands urgent diagnostic differentiation from central stroke. Hospital emergency departments drive demand for rapid VNG assessment.
- Others:Vestibular migraine, superior canal dehiscence, and psychogenic vertigo complete the diagnostic spectrum. Specialized otology centers manage these heterogeneous presentations.
Meniere's Disease leads volumes today; Benign Paroxysmal Positional Vertigo shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized otology expertise concentrates in German university hospitals, Japanese tertiary networks, and United States academic medical centers, anchoring demand for advanced vestibular diagnostics and rehabilitation protocols across these markets.
United States
Medicare reimbursement expansion for fall-risk assessments drives outpatient diagnostic device procurement. FDA digital therapeutic guidance accelerates reimbursement pathway development for VR-based balance training. The Mayo Clinic and Johns Hopkins anchor vestibular rehabilitation protocol standardization.
Germany
Hospital-based vestibular rehabilitation adoption expands across Charité Berlin and Munich university networks. MDR technical documentation requirements harden cost-of-entry for diagnostic device manufacturers. Baden-Württemberg medical device clusters concentrate MDR certification expertise.
Japan
Aging demographics channel investment toward home-care balance training systems. PMDA regulatory frameworks shape software-as-medical-device classification timelines. Tokyo and Osaka metropolitan hospitals pilot VR-enabled post-acute discharge protocols.
United Kingdom
NHS England vestibular service specifications concentrate diagnostic referrals into specialized centers. MHRA post-Brexit regulatory alignment creates transitional uncertainty for device market access. London and Manchester anchor tertiary otology networks.
France
ANSM oversight of digital health applications influences reimbursement code development for remote monitoring. Paris and Lyon hospital systems integrate vestibular evoked myogenic potential testing into stroke differentiation pathways.
Vertigo Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across pharmaceutical, device, and digital therapeutic segments. The market structure tiers into multinational pharmaceutical incumbents with neurology franchises, specialized otology device manufacturers, and emerging software-based intervention developers. Strategic moves concentrate on formulary positioning for chronic Meniere's Disease management, MDR certification acquisition for European device access, and clinical evidence generation for digital therapeutic reimbursement.
Among diversified pharmaceutical incumbents, Pfizer Inc. and Novartis AG occupy positions anchoring hospital formulary access, while Sanofi sits within primary care channel density where chronic prescription patterns concentrate. These companies exemplify the multinational archetype leveraging existing neurology infrastructure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Viatris Inc. |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc. |
| AstraZeneca plc. |
| Sun Pharmaceutical Industries Ltd. |
| Epic Pharma, LLC |
| Others |
Cost & Logistics Intelligence
Optical-grade polymer feedstock pricing indices in Germany and Japan cascade through diagnostic device manufacturing tiers, compressing margins on entry-level videonystagmography systems while preserving premium pricing for MDR-certified vestibular evoked myogenic potential platforms.
Pricing Analysis
Bundled diagnostic-therapeutic service contracts dominate hospital procurement, while unbundled device-only transactions concentrate in outpatient clinics. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified European systems from legacy-cleared competitors and refurbished secondary-market equipment. Cost compression in the generic betahistine segment intensifies because of formulary substitution pressure in United States primary care channels. Price sensitivity peaks among Medicare-dependent outpatient clinics; tertiary hospital systems exhibit lowest sensitivity due to bundled outcome-based contracting.
Supply Chain Analysis
Reverse-logistics flows for recalibrated videonystagmography equipment and refurbished vestibular rehabilitation platforms concentrate refurbishment activity in Baden-Württemberg medical device clusters and Tokyo metropolitan service hubs. Component manufacturing concentrates in Germany, Japan, and the United States. Precision sensor arrays and optical-grade polymers feed from specialized chemical suppliers in the Rhine-Ruhr industrial corridor. Single-source vulnerability in rare-earth magnet supply for vestibular stimulation hardware creates exposure to export restriction shocks. Distribution runs through hospital purchasing committees and specialized otology device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertigo market reads as a late-cycle quality story as Medicare reimbursement expansion channels demand toward FDA-cleared digital therapeutics with validated fall-reduction outcomes.
For Market Incumbents: Hedge against generic substitution pressure by securing backward integration into active pharmaceutical ingredient supply for betahistine formulations. Deepen vertical integration into software companion development for vestibular rehabilitation platforms to defend against pure-play digital therapeutic entrants. Priority rests on MDR certification maintenance for European device access. For New Entrants and Emerging Players: Launch via direct-to-patient subscription models targeting home-care balance training systems in United States Medicare Advantage networks. White-space concentrates in rural health system telemedicine integration and employer-funded occupational screening programs. Go-to-market angle: outcome-based contracting tied to measurable fall-incident reduction metrics. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance burdens exceed standalone device manufacturer capital capacity. Long-term viability favors platforms combining diagnostic hardware with recurring software revenue streams. Acquisition target archetype: MDR-certified vestibular diagnostic developers with proprietary data analytics layers. Signal to watch: FDA digital therapeutic guidance expansion into remote patient monitoring reimbursement codes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Therapeutic Submission | Secures reimbursement pathway for VR-based balance training systems in Medicare networks. |
| CE Marking Pathway Acceleration | Compresses time-to-market for vestibular diagnostic platforms in German hospital systems. |
| Hospital System Partnership | Locks in formulary positioning for integrated diagnostic-therapeutic platforms across tertiary networks. |
| Software Companion Development | Enables recurring revenue streams and outcome-based contracting structures for device manufacturers. |
| Reimbursement Strategy | Aligns product positioning with expanded Medicare fall-risk assessment codes in United States outpatient channels. |
Research Approach
Coverage spans the United States, Germany, Japan, the United Kingdom, and France, with primary inputs from each market combining structured interviews with otology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation from FDA filings, PMDA submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up and top-down triangulation reconciles device shipment data with pharmaceutical prescription volumes across the analysis window.
Granularity-level framing models product type, technology platform, end-user facility type, and application-specific disease pathway at the country level, with regional regulatory clusters treated as distinct forecast strata. CAGRs derive from multivariate regression against aging demographic projections and reimbursement code expansion schedules. Industry-specific inputs include vestibular rehabilitation protocol adoption velocity and MDR certification completion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA digital therapeutic guidance delays or MDR notified body capacity constraints. Forecasts reflect assumptions regarding Medicare reimbursement continuity and generic substitution rates. Practitioners should monitor FDA software-as-medical-device classification rulings and German hospital system procurement standardization initiatives for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Bacteriophages Therapy Market