
 Global Endometriosis Treatment Market | 2026-2036
Global Endometriosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endometriosis Treatment Market Foresight
Software-defined patient monitoring and digital adherence tracking is shifting how pharmaceutical companies bundle chronic endometriosis therapies. AbbVie leverages its established gynecology franchise to sustain high-touch patient support programs that improve therapy persistence. Bayer anchors its position through deep manufacturing scale in hormonal active pharmaceutical ingredients. Pfizer competes by extending its distribution reach into ambulatory surgery centers across North America and Western Europe.
Endometriosis treatment encompasses pharmacological interventions, surgical procedures, and emerging immunomodulatory approaches designed to suppress ectopic endometrial tissue growth, alleviate chronic pelvic pain, and preserve fertility in reproductive-age patients. Hormonal therapy formulations typically contain progestins, GnRH analogues, or combined estrogen-progestin compounds that induce pseudopregnancy or pseudo-menopause states to arrest lesion progression. Laparoscopic devices represent the mature surgical segment where margin pools have compressed due to commoditized electrosurgical and laser platforms, while immune modulators constitute the fastest-growing category as developers target novel anti-inflammatory and anti-angiogenic pathways. Injectable formulations dominate delivery mode revenue due to long-acting depot preparations that improve compliance, though subcutaneous implants are gaining traction among patients seeking discrete, provider-administered alternatives to daily oral regimens.
The FDA maintains stringent oversight of GnRH agonist labeling and risk evaluation mitigation strategies for bone density loss, while the European Medicines Agency enforces post-market surveillance through periodic safety update reports that directly influence prescriber behavior and formulary placement across EU member states. Health Canada and the Pharmaceutical and Medical Devices Agency in Japan apply additional country-specific efficacy benchmarks that manufacturers must satisfy for market authorization. Stakeholders must monitor how evolving regulatory divergence on long-term hormonal safety will reshape clinical trial design, geographic launch sequencing, and portfolio prioritization decisions across the development pipeline.
Market Dynamics
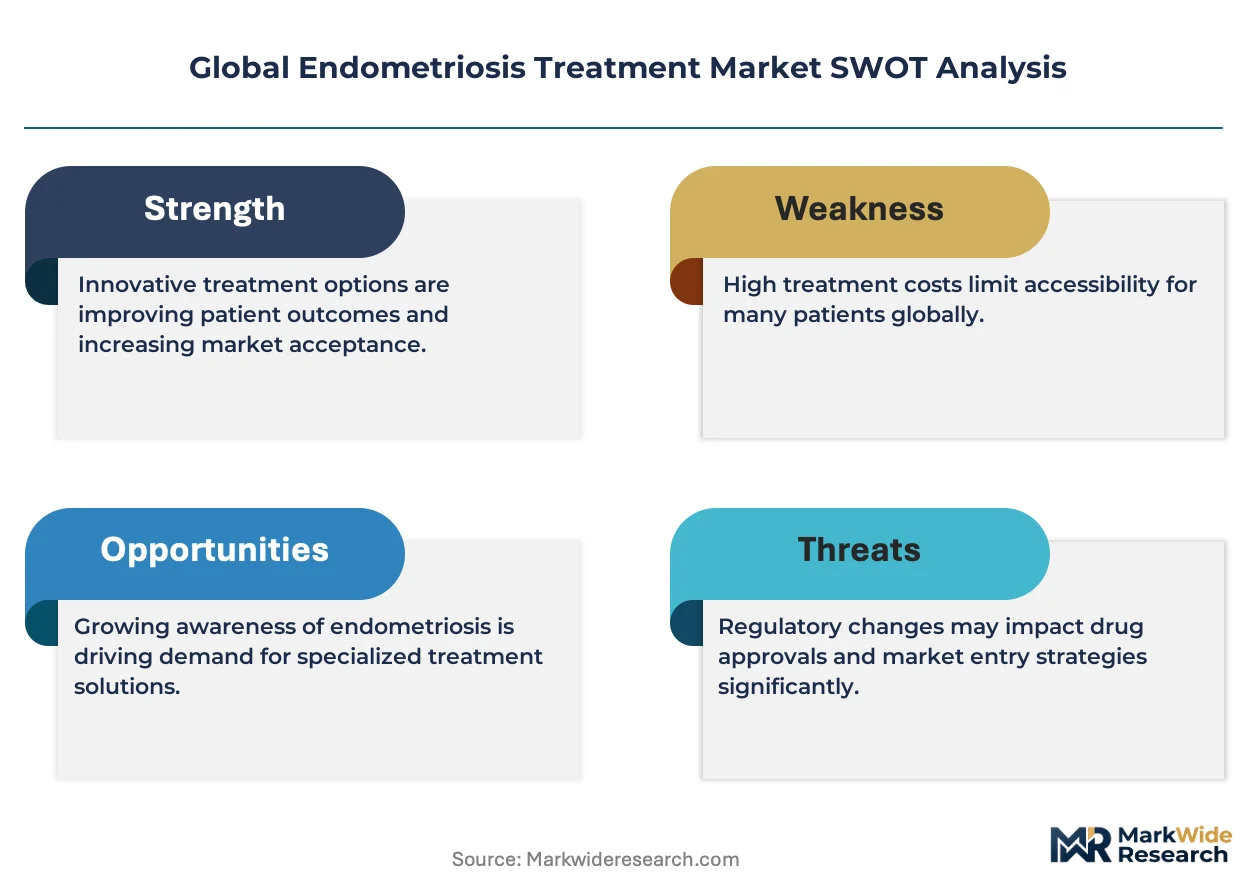
Regulatory divergence between the FDA's risk evaluation mitigation strategies for GnRH agonists and the European Medicines Agency's strengthened pharmacovigilance requirements is forcing pharmaceutical developers to redesign clinical trial protocols and geographic launch sequencing simultaneously.
Growth Catalysts
- Fertility Center Expansion:Specialized reproductive clinics across Germany, Japan, and the United States are building dedicated endometriosis surgical suites and hormonal therapy management programs.
- Software-Defined Monitoring:Digital adherence tracking platforms bundled with chronic therapy regimens are improving patient persistence rates through real-time symptom logging and automated dosing reminders.
- Integrated Health System Consolidation:Large hospital networks in the United States are standardizing laparoscopic surgical protocols, creating volume-driven procurement efficiencies for electrosurgical devices.
Market Restraints
- Bone Density Surveillance Burden:The FDA's mandatory REMS programs for long-term GnRH agonist therapy require costly dual-energy X-ray absorptiometry monitoring infrastructure that limits prescriber adoption.
- Commoditized Surgical Platforms:Electrosurgical and laser device margins have compressed as manufacturing concentrates among contract producers in China and Malaysia.
- Oral Therapy Substitution:Daily progestin regimens face erosion from patient preference for long-acting depot injections that reduce dosing frequency.
Strategic Opportunities
- Immunomodulatory Pipeline:Novel anti-inflammatory and anti-angiogenic compounds targeting ectopic lesion vascularization represent the fastest-expanding therapeutic category in late-stage development.
- Subcutaneous Implant Delivery:Discrete, provider-administered hormonal implants are capturing demand from patients rejecting visible injection schedules.
- Health Canada's Accelerated Review Pathway:The regulator's priority review designation for therapies addressing unmet gynecological needs offers faster market entry for qualifying hormonal formulations.
Industry Challenges
- Multinational Trial Coordination:Divergent efficacy benchmarks between the Pharmaceutical and Medical Devices Agency in Japan and EU member state regulators require parallel study designs that extend development timelines.
- Laparoscopic Specialist Shortage:Advanced minimally invasive surgical training programs are not producing sufficient gynecological surgeons to match fertility center expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endometriosis Treatment Market |
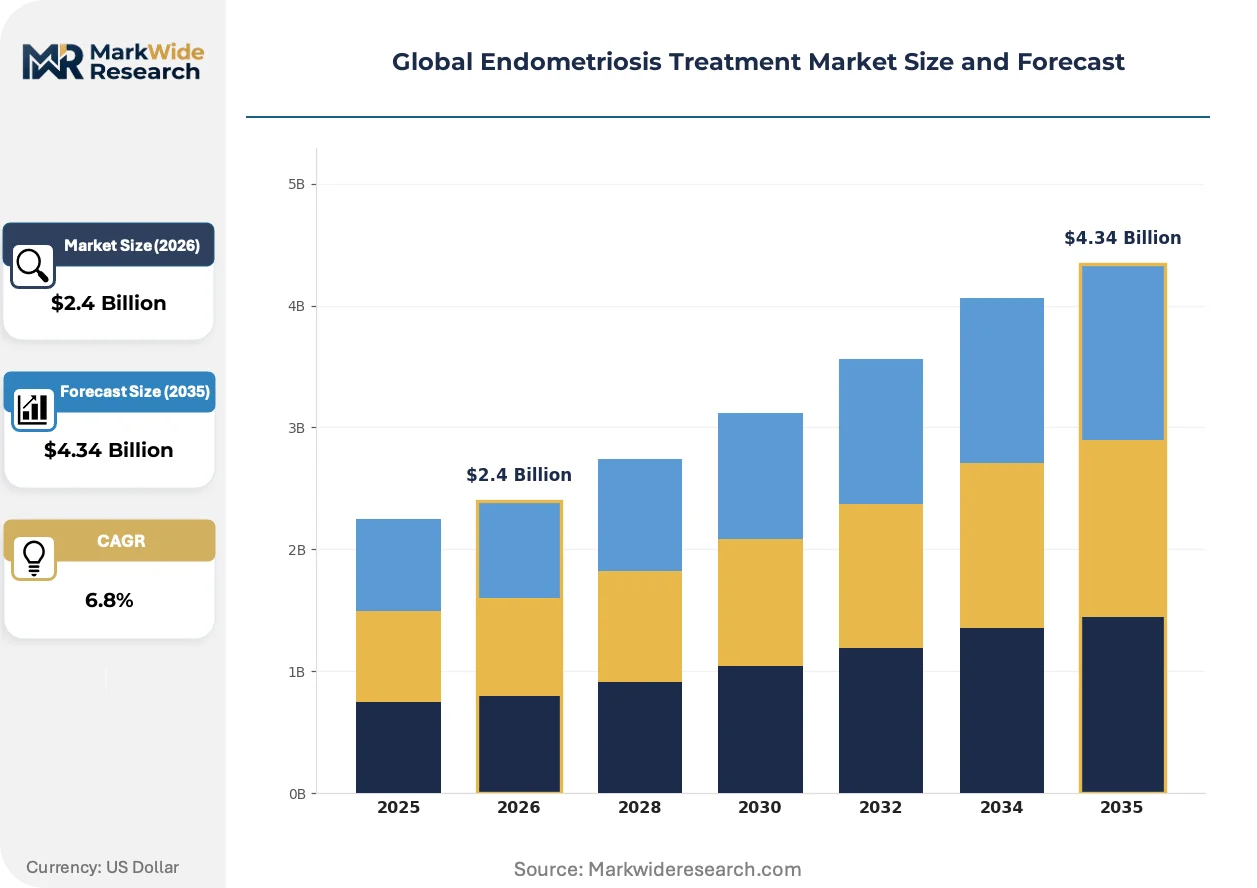
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Pain Relievers, Gonadotropin-Releasing Hormone Agonists, Laparoscopic Devices, Immune Modulators Therapy Area: Chronic Pelvic Pain, Infertility Management, Dysmenorrhea Relief, Adenomyosis Treatment, Ovarian Endometrioma End User: Specialty Clinics, Fertility Centers, Ambulatory Surgery Centers, Gynecologist Practices, Research Institutes Delivery Mode: Oral Medication, Injectable Formulations, Subcutaneous Implants, Laparoscopic Surgery, Transdermal Patches |
| Companies Covered | AbbVie, Bayer, Pfizer, AstraZeneca, Teva Pharmaceutical Industries, Gedeon Richter, ObsEva, Lupin, Organon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endometriosis Treatment Market Shifts & Advancements
Biologic mechanism understanding and patient-administered delivery formats are converging to reshape how chronic endometriosis therapy is prescribed, monitored, and reimbursed across ambulatory and surgical settings.
Long-acting subcutaneous implants containing progestin analogues are electrifying chronic pain management by eliminating daily adherence burdens. Reproductive endocrinology practices in the United States and Western Europe are adopting these devices at twice the pace of traditional injectable depots. The technology is compressing pharmacy benefit management complexity while shifting site-of-care revenue toward physician-administered reimbursement codes.
The European Medicines Agency's periodic safety update report requirements for hormonal therapies are tightening post-market surveillance obligations across all GnRH analogue formulations. Manufacturers must now submit comprehensive bone health and cardiovascular outcome data annually, directly influencing prescriber confidence and formulary tier placement. The surgical device segment faces minimal impact, while pharmaceutical developers are reallocating resources to real-world evidence collection infrastructure.
Patient-driven demand for discrete therapy administration is fragmenting traditional distribution channels. Fertility centers and gynecology practices are bypassing retail pharmacy networks to procure hormonal implants directly through specialty distributors, capturing margin that previously flowed to outpatient pharmacy benefit managers. This channel disintermediation is most pronounced in Germany and the United States, where integrated delivery networks negotiate direct purchasing agreements with manufacturers.
Global Endometriosis Treatment Market Segmentation
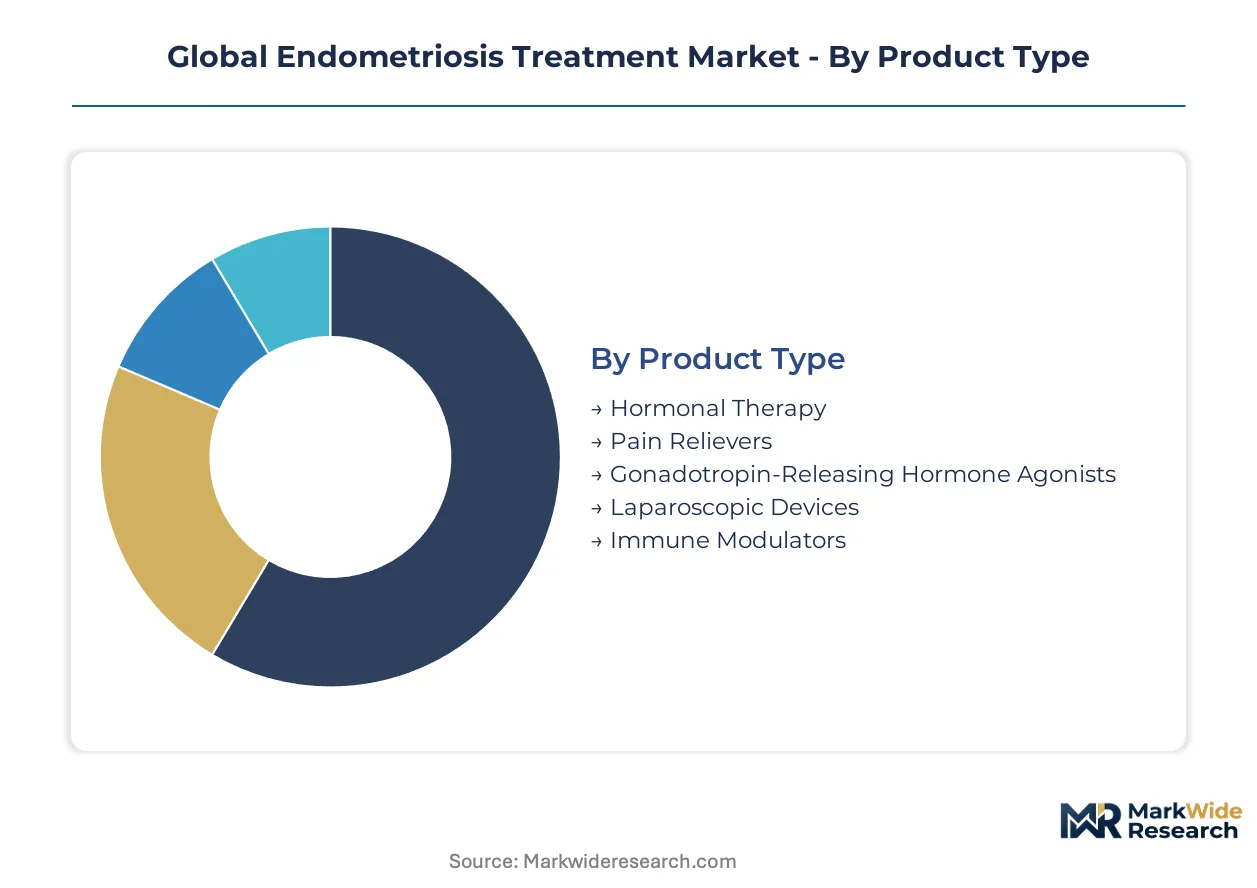
Endometriosis treatment markets fragment across therapeutic modality, clinical setting, and patient administration preference. Understanding these intersections reveals where pharmaceutical developers concentrate R&D investment versus where surgical device manufacturers defend margin pools.
Product Type:
Hormonal therapy formulations operate as standalone chronic disease management platforms, while laparoscopic devices embed into integrated surgical workflows requiring capital equipment compatibility.
- Hormonal Therapy:Progestin, combined estrogen-progestin, and selective progesterone receptor modulator formulations induce pseudopregnancy states to arrest ectopic lesion progression. Demand concentrates in United States integrated health systems where protocol standardization drives formulary consolidation toward long-acting depot preparations.
- Gonadotropin-Releasing Hormone Agonists:Synthetic peptide analogues suppress ovarian steroidogenesis through pituitary desensitization, creating reversible pseudo-menopause. Germany and Japan fertility centers are expanding GnRH agonist capacity despite FDA REMS requirements for bone density surveillance infrastructure.
- Pain Relievers:NSAID and opioid analgesics address breakthrough symptoms without hormonal manipulation.
- Laparoscopic Devices:Electrosurgical generators, laser platforms, and morcellation systems enable minimally invasive lesion excision.
- Immune Modulators:Novel anti-inflammatory and anti-angiogenic compounds target ectopic tissue vascularization and macrophage recruitment.
Hormonal therapy leads volumes today; immune modulators are gaining share fastest.
Therapy Area:
Chronic pelvic pain management commands the highest patient volume, while infertility-focused interventions capture premium reimbursement tiers across German, Japanese, and United States fertility networks.
- Chronic Pelvic Pain:Persistent inflammatory and neuropathic pain syndromes drive long-term pharmaceutical adherence. United States specialty clinics are standardizing multimodal pain protocols combining hormonal suppression with neuromodulatory agents.
- Infertility Management:Surgical restoration of tubo-ovarian anatomy and pre-IVF hormonal optimization to improve oocyte quality. Japanese fertility centers are building dedicated endometriosis surgical suites faster than Western European counterparts.
- Dysmenorrhea Relief:Cyclic pain suppression through hormonal cycle manipulation or acute analgesic intervention.
- Adenomyosis Treatment:Uterine-sparing hormonal therapy or hysterectomy for diffuse endometrial tissue invasion.
- Ovarian Endometrioma:Cystectomy or drainage procedures preserving ovarian reserve in reproductive-age patients.
Chronic pelvic pain dominates prescription volumes; infertility management commands the steepest expansion trajectory.
End User:
Site-of-care economics differentiate procurement patterns, with fertility centers and ambulatory surgery centers bypassing traditional hospital purchasing committees.
- Fertility Centers:Specialized reproductive endocrinology practices combining diagnostic laparoscopy with hormonal therapy management. Germany, Japan, and United States networks are consolidating gynecological specialty care through direct manufacturer agreements.
- Ambulatory Surgery Centers:Freestanding facilities performing diagnostic and operative laparoscopy with reduced infection risk versus inpatient settings. United States Medicare reimbursement shifts are accelerating site-of-care migration.
- Specialty Clinics:Dedicated pelvic pain and endometriosis centers offering integrated medical-surgical management.
- Gynecologist Practices:Community-based providers managing stable patients on maintenance hormonal therapy.
- Research Institutes:Academic medical centers conducting immunomodulatory clinical trials with EMA and FDA-aligned protocols.
Fertility centers lead procedural volumes today; ambulatory surgery centers are expanding capacity fastest.
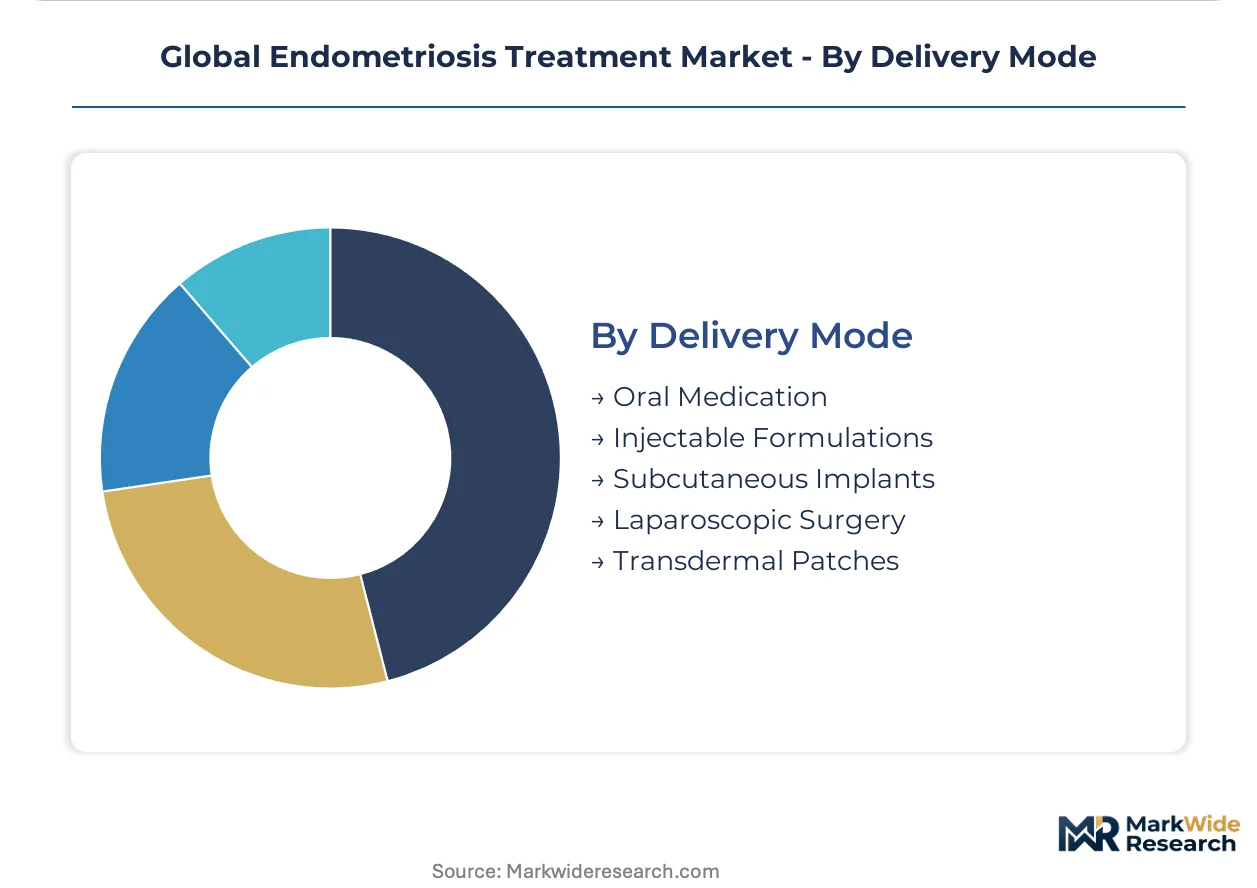
Delivery Mode:
Patient-administered formats compete with provider-administered alternatives on adherence, discretion, and reimbursement complexity.
- Injectable Formulations:Long-acting depot preparations of GnRH agonists and progestins administered monthly to quarterly. United States pharmacy benefit managers favor these formulations for compliance metrics, though bone density monitoring requirements limit prescriber adoption.
- Subcutaneous Implants:Discrete, provider-administered hormonal rods eliminating visible injection schedules. Western European reproductive endocrinology practices are adopting implants at twice the pace of traditional depots.
- Oral Medication:Daily progestin or combined hormonal regimens requiring patient adherence discipline.
- Laparoscopic Surgery:Minimally invasive lesion excision, adhesiolysis, and ovarian cystectomy performed under general anesthesia.
- Transdermal Patches:Estrogen-progestin combinations avoiding first-pass hepatic metabolism.
Injectable formulations lead revenue today; subcutaneous implants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan fertility centers are outpacing United States expansion in dedicated surgical capacity, while regulatory divergence between FDA REMS requirements and EMA pharmacovigilance protocols is fragmenting clinical trial design across major markets.
United States
Integrated health systems in Texas and California are consolidating gynecological specialty care through direct purchasing agreements with hormonal implant manufacturers. FDA risk evaluation mitigation strategies for GnRH agonists mandate dual-energy X-ray absorptiometry infrastructure that limits prescriber adoption in rural markets. Boston and New York Metro academic medical centers anchor immunomodulatory clinical trial recruitment for late-stage pipeline candidates.
Germany
Fertility centers in Bavaria and North Rhine-Westphalia are building dedicated endometriosis surgical suites faster than Western European counterparts. EMA periodic safety update report requirements for hormonal therapies enforce annual bone health and cardiovascular outcome submissions that reshape prescriber confidence. Frankfurt and Munich reproductive endocrinology networks negotiate direct manufacturer agreements bypassing retail pharmacy channels.
Japan
Specialized clinics in Tokyo and Osaka are expanding pre-IVF hormonal optimization programs for endometriosis-related infertility. Pharmaceutical and Medical Devices Agency efficacy benchmarks require parallel study designs that extend development timelines for multinational sponsors. Kanto region fertility networks are adopting subcutaneous implants at twice the pace of traditional injectable depot preparations.
United Kingdom
London and Southeast England pelvic pain centers are standardizing multimodal protocols combining hormonal suppression with neuromodulatory agents. MHRA alignment with EMA post-market surveillance obligations influences formulary tier placement across NHS integrated care systems. Midlands research institutes coordinate real-world evidence collection infrastructure for bone density outcomes in long-acting therapy cohorts.
Canada
Health Canada's accelerated review pathway for unmet gynecological needs offers faster market entry for qualifying hormonal formulations. Ontario and Quebec fertility clinics are migrating diagnostic laparoscopy toward ambulatory surgery centers with reduced infection protocols. Toronto academic hospitals anchor immunomodulatory clinical trial networks aligned with FDA and EMA protocols simultaneously.
Global Endometriosis Treatment Market Competitive Landscape
Top-tier vendors anchor hormonal therapy and surgical device segments, while mid-scale specialists concentrate on immunomodulatory pipeline candidates and regional distribution networks. Market structure consolidates around three strategic archetypes: integrated pharmaceutical conglomerates with gynecology franchises, contract manufacturers of hormonal active pharmaceutical ingredients, and emerging biotech developers targeting anti-angiogenic pathways. Competitive positioning depends on M&A activity capturing fertility center direct purchasing relationships and geographic expansion into Japanese and German reproductive health networks.
Among established pharmaceutical conglomerates, AbbVie, Bayer, and Pfizer occupy positions exemplifying divergent strategic vectors. AbbVie represents the patient support program archetype, leveraging high-touch chronic disease management infrastructure. Bayer anchors manufacturing scale positioning in hormonal active pharmaceutical ingredients. Pfizer exemplifies distribution reach expansion into ambulatory surgery centers across North American and Western European markets.
| Leading Market Players |
|---|
| AbbVie |
| Bayer |
| Pfizer |
| AstraZeneca |
| Teva Pharmaceutical Industries |
| Gedeon Richter |
| ObsEva |
| Lupin |
| Organon |
| Others |
Supply & Pricing Matrix
United States integrated health systems concentrate procurement volume for hormonal implants, driving three-tier pricing structure across premium, standard, and economy levels based on formulation complexity and bone density monitoring bundling. German fertility centers negotiate direct manufacturer agreements that bypass retail pharmacy markups, compressing net prices while capturing margin through physician-administered reimbursement codes.
Pricing Analysis
Capacity additions in China and Malaysia for electrosurgical device components are reshaping price floors for laparoscopic platforms, intensifying cost compression in the surgical segment. Pricing stratifies across premium, standard, and economy tiers based on FDA REMS compliance infrastructure, brand recognition in GnRH agonists, and after-sales training support. Margins are tightening due to contract manufacturing concentration in Asian production hubs. Ambulatory surgery centers exhibit highest price sensitivity, while fertility centers prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Device refurbishment and remanufacturing flows for electrosurgical generators create secondary supply channels that extend equipment lifecycle and dampen new-unit demand. Active pharmaceutical ingredient production draws from India, China, and Italy for hormonal compounds, with peptide synthesis for GnRH analogues concentrated in European contract manufacturing organizations. Supply chain risk centers on single-source vulnerability for long-acting depot formulations. Distribution runs through specialty distributors serving fertility centers and integrated delivery networks, bypassing traditional hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Endometriosis Treatment Market compounds steadily through chronic disease management expansion, with fertility center infrastructure buildouts across Germany, Japan, and the United States anchoring durable revenue streams for hormonal and surgical modalities.
For Market Incumbents: Lock in direct purchasing relationships with expanding fertility center networks in Bavaria and North Rhine-Westphalia before channel disintermediation accelerates. Prioritize backward integration into progestin active pharmaceutical ingredient production to defend margin position against Indian and Chinese contract manufacturers. Secure FDA REMS-compliant bone density monitoring infrastructure partnerships to reduce prescriber adoption friction for GnRH agonists. For New Entrants and Emerging Players: Specialty telehealth platforms for endometriosis symptom tracking represent the most penetrable white-space target, enabling digital adherence bundling without legacy pharmaceutical infrastructure. Japanese pre-IVF hormonal optimization programs offer geographic entry with less formulary consolidation than United States integrated health systems. Pursue Health Canada accelerated review pathway submissions to establish regulatory credibility before FDA or EMA filings. For Investors and Strategic Acquirers: Large pharmaceutical conglomerates with underdeveloped gynecology franchises are the most active acquirer in this space, seeking patient support program infrastructure and fertility center direct purchasing relationships. Target immunomodulatory developers with late-stage anti-angiogenic compounds addressing ectopic lesion vascularization. Monitor EMA periodic safety update report enforcement intensity as signal for hormonal therapy portfolio repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Immunomodulatory pipeline candidates require EMA-aligned bone health outcome protocols to secure formulary placement. |
| Regulatory Approval Pathway | Health Canada accelerated review designation offers faster market entry for qualifying hormonal formulations addressing unmet gynecological needs. |
| Manufacturing Scale-Up | Long-acting depot injection capacity expansion in European contract manufacturing organizations serves German fertility center demand growth. |
| Hospital System Partnership | Direct purchasing agreements with United States integrated health systems bypass pharmacy benefit manager margin extraction. |
| Software Companion Development | Digital adherence tracking platforms bundled with chronic therapy improve patient persistence metrics for pharmacy benefit manager contracting. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reproductive endocrinologists, formulary directors at United States integrated health systems, regulatory affairs leads, and hospital procurement managers with secondary validation through FDA filings, EMA periodic safety update reports, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Historical reference periods spanning pre-pandemic baseline through recent fertility center expansion waves established trajectory anchors for projection modeling across the analysis window. Segmentation dimensions included therapeutic modality, delivery mode, clinical setting, and regional regulatory cluster. CAGRs were derived from patient population growth, therapy persistence rate improvements, and surgical procedure volume trends. Immunomodulatory pipeline advancement timelines and EMA pharmacovigilance enforcement intensity served as scenario-weighting inputs.
Regulatory divergence between FDA REMS requirements and EMA post-market surveillance obligations, fertility center expansion rate variability, and immunomodulatory clinical trial success rates are the dominant revision risks that could alter trajectory assumptions. Practitioners should monitor EMA periodic safety update report enforcement patterns and Japanese PMDA efficacy benchmark evolution for early signals of forecast revision necessity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market