
 Complex Regional Pain Syndrome (CRPS) Market | 2026-2036
Complex Regional Pain Syndrome (CRPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Complex Regional Pain Syndrome (CRPS) Market Outlook
Implantable device servicing revenue is reshaping profitability models across the CRPS therapeutic landscape. Boston Scientific leverages its spinal cord stimulation platform to sustain recurring revenue from battery replacements and programming adjustments. Medtronic anchors its market position through deep integration with hospital electrophysiology departments, while Nevro differentiates with proprietary high-frequency waveform technology that competes on paresthesia-free outcomes.
Complex Regional Pain Syndrome constitutes a chronic neuropathic pain disorder characterized by autonomic dysfunction, allodynia, and trophic skin changes following limb trauma or surgery, with diagnostic criteria requiring persistent regional pain disproportionate to inciting events. Its primary commercial purpose centers on restoring functional mobility and reducing long-term disability costs across workers' compensation and private payer systems. Neuromodulation Devices command premium pricing due to implant complexity and specialist dependency, while Medications remain the volume gateway for newly diagnosed cases. Pain Management Programs are gaining structural importance as payers demand bundled episode-of-care reimbursement.
FDA breakthrough device pathways and CMS national coverage determinations for spinal cord stimulation shape market access timelines and clinical trial investment priorities. EMA medical device regulation and Health Technology Assessment frameworks in Germany and France govern European commercialization feasibility. Stakeholders must monitor evolving FDA guidance on patient-reported outcome measures for chronic pain trials, as these endpoints will determine which neuromodulation platforms secure favorable coverage.
Market Dynamics
Neuromodulation device manufacturers face mounting pressure from CMS reimbursement pathway expansions that compress commercialization timelines while elevating clinical evidence requirements for spinal cord stimulation platforms.
Growth Catalysts
- FDA Breakthrough Device Designations:Accelerated review timelines for novel neuromodulation platforms compress time-to-market for high-frequency waveform technologies targeting paresthesia-free outcomes.
- Specialized Treatment Center Clustering:Academic medical institutions in the United States, Germany, and Japan concentrate patient volume and specialist expertise, creating referral density that sustains implant procedure volumes.
- Workers' Compensation Cost Containment:Private payer and public disability systems prioritize functional restoration therapies that reduce long-term disability expenditures across chronic neuropathic pain populations.
Market Restraints
- Implant Hardware Cost Concentration:Battery and electrode component supply chains concentrate among limited specialty manufacturers, exposing pricing volatility to rare earth material fluctuations.
- Specialist Dependency Bottleneck:Qualified pain medicine physicians and electrophysiology technicians cluster disproportionately in urban academic centers, constraining rural and suburban market access.
- Reimbursement Fragmentation:Inconsistent national coverage determinations across Medicare administrative contractors create geographic reimbursement variability that dampens hospital capital commitment.
Strategic Opportunities
- Underpenetrated Japanese Outpatient Settings:Ambulatory surgical center reimbursement reforms open procedural volume expansion beyond traditional hospital-based implantation.
- Closed-Loop Sensing Convergence:Integration of evoked compound action potential monitoring with automated stimulus adjustment creates next-generation platform differentiation.
- Bundled Episode-of-Care Contracts:Payer willingness to delegate total cost accountability to integrated delivery networks rewards comprehensive pain management program investments.
Industry Challenges
- Electrophysiology Talent Scarcity:Cross-training requirements for device programming and troubleshooting exceed available certified clinical specialist pipeline capacity.
- Legacy EMR Integration Friction:Proprietary device data formats resist seamless incorporation into hospital electronic health record workflows, complicating longitudinal outcome tracking.
- Patient-Reported Outcome Standardization Delays:Absence of harmonized endpoint definitions across FDA guidance documents prolongs clinical trial design negotiations and protocol amendments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complex Regional Pain Syndrome (CRPS) Market |
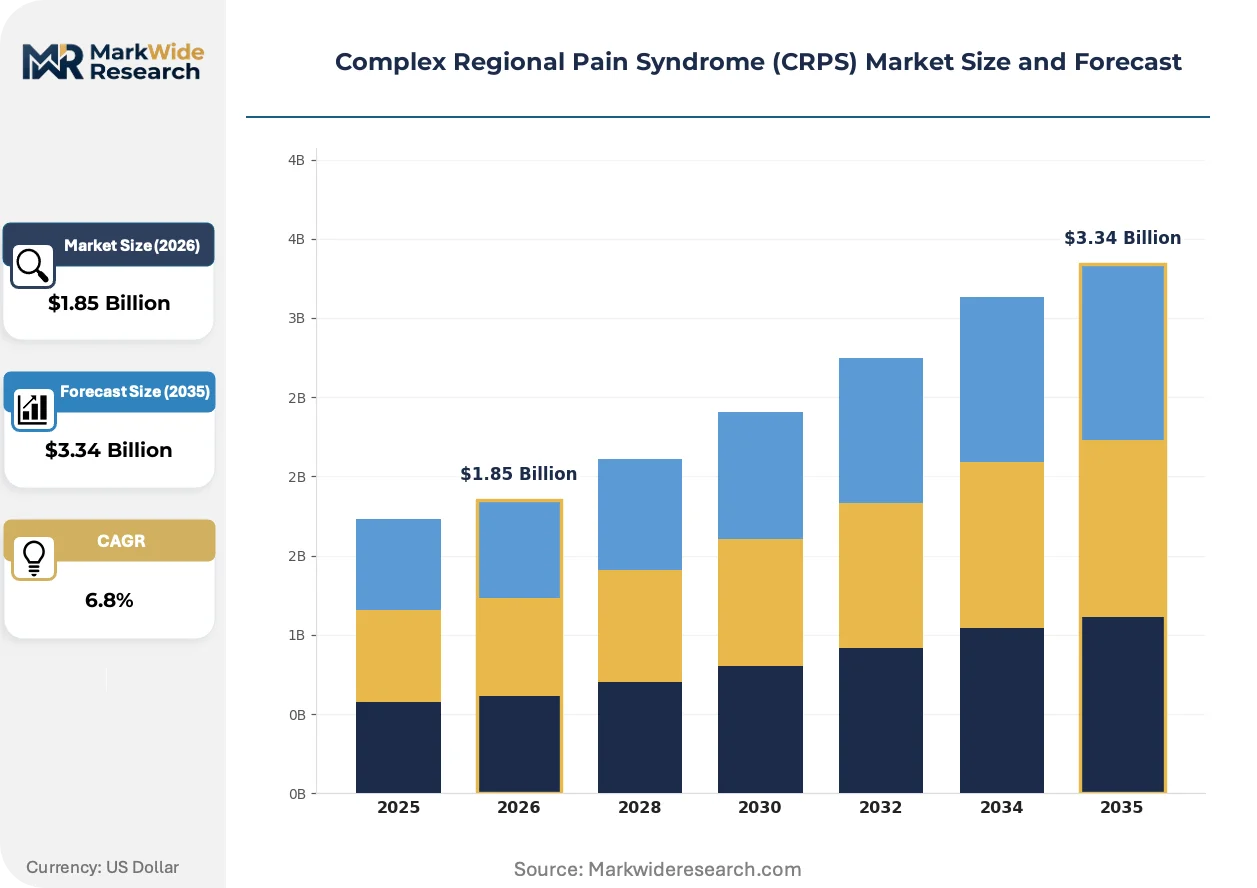
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physiotherapy, Neuromodulation Devices, Pain Management Programs Delivery Mode: Intravenous, Oral, Topical, Implantable End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Homecare Therapy Area: Neurology, Pain Medicine, Orthopedics, Rehabilitation |
| Companies Covered | Boston Scientific, Medtronic, Abbott Laboratories, Nevro, Johnson & Johnson, AbbVie, Pfizer, Eli Lilly and Company, GSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complex Regional Pain Syndrome (CRPS) Market Strategic Shifts
Neuromodulation technology trajectories center on eliminating paresthesia side effects while embedding artificial intelligence for automated therapy optimization, fundamentally altering how implantable devices interact with patient physiology.
High-frequency spinal cord stimulation at kilohertz-range frequencies delivers analgesia without the tingling sensations that plague conventional tonic stimulation. Pain management departments at academic medical centers in Germany and the United States are prioritizing these platforms for patient populations reporting paresthesia intolerance. Conventional tonic stimulation hardware is rendering obsolete as hospitals consolidate vendor relationships around next-generation waveform capabilities.
The European Union's Medical Device Regulation imposes stricter clinical evidence requirements for implantable neuromodulation systems seeking CE marking renewal. Manufacturers must now submit post-market surveillance data and updated risk-benefit analyses that extend regulatory affairs timelines. German and French notified bodies are applying these standards most stringently, forcing portfolio prioritization decisions that delay lower-revenue device line extensions.
Hospital purchasing committees are consolidating implantable device contracts into single-source agreements that bundle hardware, programming services, and battery replacement procedures. Integrated delivery networks in the United States are displacing traditional physician preference item procurement through centralized value analysis committees that standardize across multiple facilities. This concentration is most visible in California and Texas health systems where scale economies override individual practitioner brand loyalty.
Complex Regional Pain Syndrome (CRPS) Market Segmentation
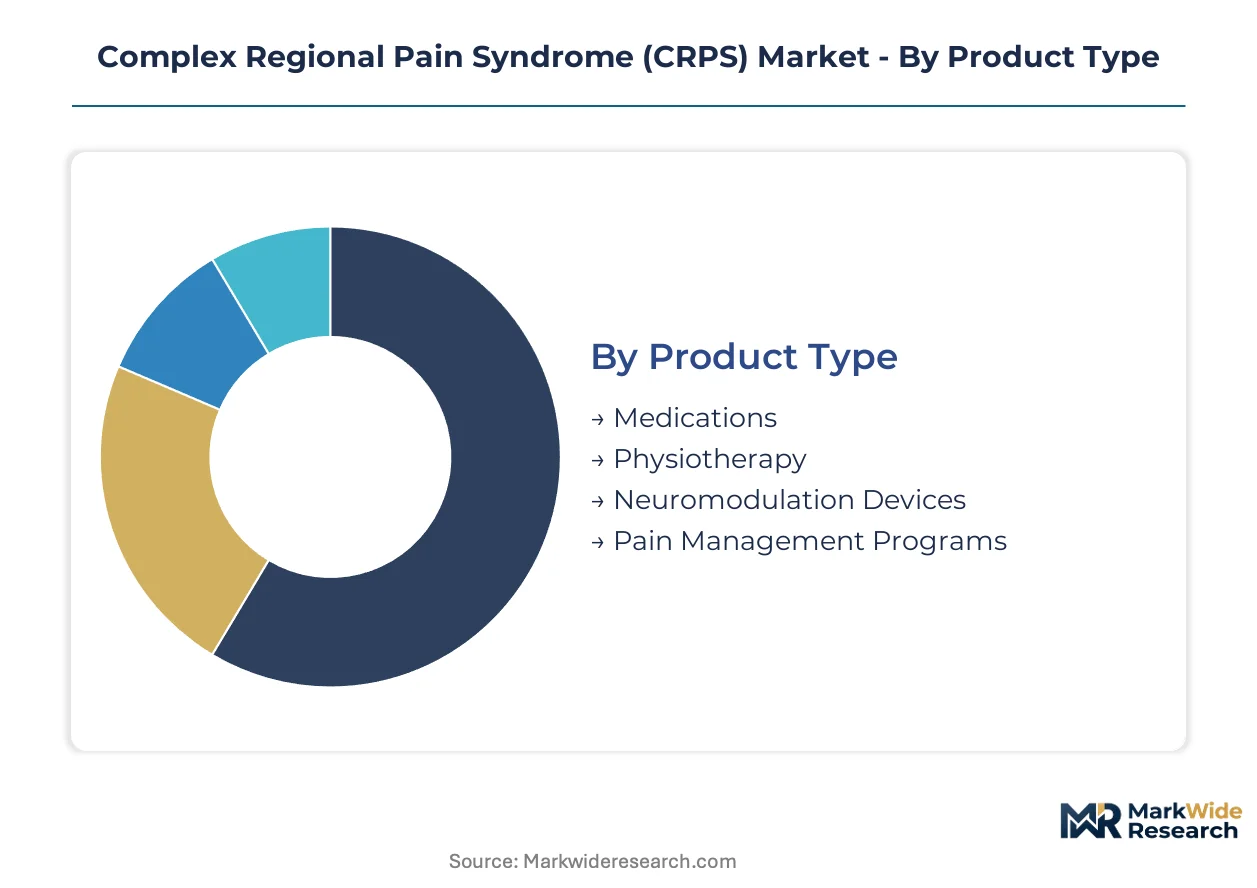
CRPS treatment pathways diverge sharply by intervention intensity and reimbursement tier. Segment boundaries reflect how payers stratify coverage across acute symptom management versus long-term functional restoration.
Product Type:
Cycle times vary dramatically: medication refills turn over monthly, implantable neuromodulation hardware persists seven to ten years, physiotherapy programs run twelve to sixteen weeks, and pain management programs extend across bundled multi-year episodes.
- Neuromodulation Devices:Implantable pulse generators with percutaneous leads deliver electrical modulation to dorsal column or dorsal root ganglion targets. Demand clusters at academic medical centers in the United States and Germany where electrophysiology specialists concentrate. FDA breakthrough device designations and CMS national coverage determinations compress commercialization timelines while elevating clinical evidence requirements.
- Medications:Oral and intravenous formulations span gabapentinoids, tricyclic antidepressants, bisphosphonates, and topical analgesics. Volume concentrates in outpatient prescribing across Japan and the United States where primary care physicians manage early-stage cases. Payer step-therapy protocols mandate medication failure before device authorization.
- Physiotherapy:Graded motor imagery, mirror therapy, and desensitization protocols address cortical reorganization and limb dysfunction. German rehabilitation centers and United States workers' compensation systems drive adoption where functional restoration reduces long-term disability expenditures.
- Pain Management Programs:Multidisciplinary coordinated care combining psychological intervention, occupational therapy, and medical management. United States integrated delivery networks and German statutory health insurance pilot bundled episode-of-care reimbursement models.
Medications anchor the volume base while neuromodulation devices gain share at the steepest rate.
Delivery Mode:
Cost tiers stratify sharply: oral generics occupy the economy position, topical formulations command mid-tier pricing, intravenous infusions require facility fees that elevate reimbursement, and implantable hardware with surgical placement sits at the premium extreme.
- Implantable:Surgical placement of spinal cord stimulators or dorsal root ganglion stimulators with subcutaneous pulse generators. United States hospital outpatient departments and Japanese ambulatory surgical centers concentrate procedural volume where specialist density supports complex implantation.
- Oral:Systemic administration of neuropathic pain agents and anti-inflammatory compounds. Primary care networks across Germany and the United States generate prescription volume where diagnostic delay extends medication trial periods.
- Intravenous:Hospital or infusion center administration of bisphosphonates, ketamine, or regional anesthetic blocks. German university hospitals and United States academic medical centers dominate where inpatient monitoring capabilities manage adverse event risk.
- Topical:Localized delivery of lidocaine, capsaicin, or compounded formulations to affected limbs. Homecare settings in Japan and outpatient clinics in the United States drive demand where patient self-administration reduces facility dependency.
Oral delivery anchors the volume base while implantable modes expand most quickly.
End User:
Customer types fragment by care intensity and capital commitment: homecare operates with minimal infrastructure, outpatient clinics deploy limited diagnostic equipment, rehabilitation centers invest in specialized therapeutic apparatus, and hospitals absorb the full capital burden of surgical suites and electrophysiology labs.
- Hospitals:Tertiary and quaternary centers performing implantation procedures and managing refractory cases. United States academic medical centers and German university hospitals concentrate volume where electrophysiology departments support device programming and troubleshooting.
- Outpatient Clinics:Pain medicine and neurology practices delivering diagnosis, medication management, and trial stimulation. United States metropolitan markets and Japanese urban centers generate visit density where specialist availability exceeds rural catchment areas.
- Rehabilitation Centers:Dedicated facilities providing graded motor imagery, desensitization, and functional restoration. German statutory health insurance contracts and United States workers' compensation carve-outs sustain census where long-term disability reduction justifies intensive intervention.
- Homecare:Self-administered topical therapies and remote monitoring of implantable device function. Japanese reimbursement reforms expanding ambulatory surgical center eligibility and United States telehealth integration support decentralized care models.
Outpatient clinics anchor the volume base while homecare gains share at the steepest rate.
Therapy Area:
Maturity stages diverge: orthopedics retains the longest clinical history with post-traumatic pain recognition, neurology commands the deepest mechanistic research investment, pain medicine consolidates cross-disciplinary coordination, and rehabilitation represents the newest formal specialization with evolving credentialing standards.
- Pain Medicine:Dedicated specialty integrating pharmacological, interventional, and neuromodulatory approaches. United States fellowship programs and German pain society certification pathways concentrate expertise where multidisciplinary coordination optimizes outcomes.
- Neurology:Mechanistic focus on central sensitization, autonomic dysfunction, and cortical reorganization. Academic research centers in Germany and the United States drive clinical trial enrollment where biomarker development supports patient stratification.
- Orthopedics:Original site of CRPS recognition following fracture and surgical trauma. Post-operative surveillance protocols in Japanese orthopedic departments and United States trauma centers sustain diagnostic volume where early identification improves prognosis.
- Rehabilitation:Functional restoration emphasis addressing limb disuse, contracture prevention, and vocational reintegration. German rehabilitation hospital networks and United States occupational therapy programs lead where return-to-work metrics satisfy payer accountability requirements.
Orthopedics anchors the volume base while pain medicine gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies: German statutory health insurance demands rigorous cost-effectiveness evidence before device authorization, while United States commercial payers tolerate premium implant pricing when workers' compensation liability reduction justifies expenditure. Japanese reimbursement reforms are compressing margins in ambulatory settings even as procedure volumes expand.
United States
Academic medical centers in Boston, Cleveland, and Houston concentrate electrophysiology specialists who drive spinal cord stimulator implant volumes. FDA breakthrough device designations for high-frequency platforms accelerate commercialization timelines while CMS national coverage determinations establish reimbursement certainty. Hospital purchasing committees in California and Texas health systems are consolidating vendor contracts into single-source agreements that bundle hardware, programming, and battery replacement services.
Germany
University hospitals in Berlin, Heidelberg, and Munich anchor European clinical trial enrollment for neuromodulation platforms seeking CE marking renewal under tightened EMA Medical Device Regulation standards. The Federal Joint Committee's health technology assessment protocols mandate comparative effectiveness evidence before statutory health insurance coverage. Pain management specialization pathways certified by the German Pain Society concentrate expertise in Bavaria and North Rhine-Westphalia.
Japan
Metropolitan Tokyo and Osaka clusters concentrate orthopedic surgeons who diagnose post-traumatic CRPS through post-operative surveillance protocols. METI reimbursement reforms expanding ambulatory surgical center eligibility are shifting implant procedures away from traditional hospital settings. PMDA regulatory timelines for novel neuromodulation platforms lag FDA and EMA pathways by eighteen to twenty-four months.
United Kingdom
London teaching hospitals and the Oxford-Cambridge corridor host specialized pain medicine fellowship programs that generate qualified implanter pipelines. NICE technology appraisals for spinal cord stimulation require demonstration of superiority over conventional medical management before NHS commissioning. Regional pain networks in Greater Manchester and the West Midlands are piloting bundled episode-of-care contracts with integrated delivery networks.
France
Parisian university hospital centers and Lyon-based rehabilitation institutes concentrate multidisciplinary pain management program capacity. ANSM post-market surveillance requirements for implantable devices extend regulatory affairs timelines beyond German notified body pathways. The Haute Autorité de Santé's transparency committee evaluates neuromodulation platforms for inclusion in statutory reimbursement lists with growing emphasis on patient-reported outcome measures.
Complex Regional Pain Syndrome (CRPS) Market Competitive Environment
Diversified medical technology conglomerates and specialized neuromodulation pure-plays split the market between scale-driven platform consolidation and waveform technology differentiation. The vendor base concentrates around implantable device manufacturers with electrophysiology service capabilities and pharmaceutical firms with neuropathic pain portfolios. Two strategic archetypes dominate: integrated device-service ecosystems that capture recurring revenue from battery replacements and programming, and high-frequency waveform specialists competing on paresthesia-free outcomes. Competitive moves center on hospital contract consolidation into single-source agreements and regulatory pathway acceleration through FDA breakthrough designations.
Among diversified medical technology conglomerates, Boston Scientific and Medtronic occupy positions anchoring integrated device-service ecosystems through spinal cord stimulation platforms and deep hospital electrophysiology department integration. Nevro represents the high-frequency waveform specialist archetype, differentiating on paresthesia-free therapeutic outcomes that compete with conventional tonic stimulation approaches. Abbott Laboratories and Johnson & Johnson sit within the diversified health technology tier with pain management portfolios spanning pharmaceuticals and interventional devices. Pharmaceutical specialists including AbbVie, Pfizer, Eli Lilly and Company, and GSK concentrate on oral and injectable neuropathic pain agents that serve as gateway therapies before device authorization.
| Leading Market Players |
|---|
| Boston Scientific |
| Medtronic |
| Abbott Laboratories |
| Nevro |
| Johnson & Johnson |
| AbbVie |
| Pfizer |
| Eli Lilly and Company |
| GSK |
| Others |
Value Chain & Pricing Dynamics
Minneapolis-St. Paul anchors North American neuromodulation device manufacturing capacity, where Medtronic's electrophysiology campus and Boston Scientific's spinal cord stimulation production lines concentrate specialized battery and electrode assembly. This geographic density grants incumbent manufacturers pricing power over hospital purchasing committees that lack alternative domestic suppliers for implantable pulse generators. Premium hardware pricing persists because component supply chains resist rapid replication.
Pricing Analysis
After-sales revenue from battery replacements and reprogramming services drives lifetime value across neuromodulation platforms. Three-tier pricing structure across premium high-frequency systems, standard tonic stimulation hardware, and economy-tier legacy devices stratifies hospital procurement options. Cost compression in the economy tier intensifies because German statutory health insurance demands rigorous cost-effectiveness evidence before device authorization. Outpatient clinics exhibit highest price sensitivity due to thin reimbursement margins, while academic medical centers absorb premium pricing when workers' compensation liability reduction justifies expenditure.
Supply Chain Analysis
Export-control regimes governing advanced medical electronics limit cross-border flows of programmable implantable components between the United States, Germany, and Japan. Rare earth element processing concentrates in China, while precision battery cell manufacturing anchors in South Korea and Japan. Single-source vulnerability haunts electrode lead production where specialty polymer suppliers in Germany and Switzerland feed constrained capacity. Distribution runs through hospital value analysis committees that consolidate multi-facility contracts into single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive neuromodulation technologies threaten to displace implantable hardware if clinical equivalence achieves regulatory recognition. Incumbents must defend procedural volume through outcome differentiation and service bundling.
For Market Incumbents: Build switching-cost moats through electrophysiology talent capture and EMR integration depth. Anchor hospital relationships with bundled episode-of-care contracts that delegate total cost accountability to integrated delivery networks. Counter high-frequency waveform specialists by acquiring closed-loop sensing capabilities or licensing evoked compound action potential monitoring technology. Deepen vertical integration into battery cell manufacturing to offset rare earth price volatility.
For New Entrants and Emerging Players: Establish a beachhead in Japanese ambulatory surgical centers where METI reimbursement reforms expand procedural volume beyond traditional hospital settings. Target pain management programs in United States workers' compensation carve-outs where functional restoration metrics satisfy payer accountability requirements. Penetrate German rehabilitation centers through graded motor imagery protocol integration that addresses cortical reorganization without implantable hardware. Deploy direct-to-payer contracting that bypasses hospital purchasing committee consolidation.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because implantable device servicing creates annuity-like cash flows from battery replacements and programming adjustments. Acquisition targets should display electrophysiology service capabilities and hospital GPO contract penetration. Watch FDA guidance on patient-reported outcome measures for chronic pain trials as the inflection signal determining which neuromodulation platforms secure favorable coverage.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates commercialization timelines for high-frequency waveform platforms targeting paresthesia-free outcomes. |
| Hospital System Partnership | Secures single-source agreements bundling hardware, programming services, and battery replacement procedures. |
| CE Marking Renewal Investment | Addresses tightened EMA Medical Device Regulation standards requiring post-market surveillance data submission. |
| Software Companion Development | Enables automated stimulus adjustment through evoked compound action potential monitoring integration. |
| Reimbursement Strategy | Navigates CMS national coverage determinations and Medicare administrative contractor variability. |
Study Parameters
A standing panel of pain medicine physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration throughout the analysis. Primary interviews with these stakeholders combined with secondary validation against FDA filings, CMS Medicare data, hospital procurement databases, and ClinicalTrials.gov enrollment records. Bottom-up procedure volume estimates triangulated against top-down neuromodulation device revenue disclosures across the analysis window.
Scenario-bracketing framed optimistic, baseline, and conservative trajectories across the projection horizon. Segmentation dimensions modeled included product type, delivery mode, end user, therapy area, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to procedural volume and average selling price assumptions. Forecast inputs incorporated electrophysiology specialist pipeline capacity, reimbursement pathway expansion timelines, and FDA breakthrough designation velocity.
Stress conditions across rare earth material price volatility, Medicare administrative contractor reimbursement variability, and electrophysiology talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and hospital consolidation patterns. Material shifts in FDA guidance on patient-reported outcome measures or CMS national coverage determinations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market