
 Pulmonary Arterial Hypertension (PAH) Market | 2026-2036
Pulmonary Arterial Hypertension (PAH) Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Arterial Hypertension (PAH) Market Analytics
Specialty-grade prostacyclin formulations is collapsing the gap between hospital-based infusion and homecare self-administration. United Therapeutics Corporation dominates the parenteral prostacyclin segment through its integrated care delivery infrastructure. Johnson & Johnson leverages its Janssen subsidiary's endothelin receptor antagonist portfolio to anchor oral therapy market presence. Bayer competes on soluble guanylate cyclase stimulation with a differentiated cardiovascular safety profile.
Pulmonary Arterial Hypertension denotes a progressive vasculopathy characterized by elevated mean pulmonary arterial pressure exceeding 20 mmHg at rest, driven by endothelial dysfunction, smooth muscle proliferation, and in-situ thrombosis in distal pulmonary arterioles. The condition necessitates continuous hemodynamic modulation to prevent right ventricular failure and premature mortality. Prostacyclin analogues retain the largest revenue pool due to their irreplaceable efficacy in WHO Functional Class III-IV patients, while oral endothelin receptor antagonists capture the highest prescription volume among incident cases. Intravenous delivery maintains premium pricing despite infection risk, whereas subcutaneous infusion systems are gaining traction among patients transitioning from hospital to homecare settings.
The FDA's orphan drug exclusivity framework shapes development economics by granting seven-year market protection for novel PAH indications. EMA's centralized pediatric investigation plans mandate juvenile toxicity studies that extend timelines for adult-focused sponsors. WHO's essential medicines list inclusion for epoprostenol influences procurement patterns across national health systems. Stakeholders must monitor how CMS reimbursement adjustments for home infusion nursing affect site-of-care migration trends.
Market Dynamics
The migration of prostacyclin therapy from hospital infusion centers to home-based self-administration is compressing site-of-care economics and forcing infrastructure reinvestment across the delivery chain. This shift demands coordinated payer policy, nursing network expansion, and device interoperability standards.
Growth Catalysts
- Orphan Drug Exclusivity:The FDA's seven-year market protection framework accelerates development timelines for novel PAH indications by de-risking investment in small-population therapeutics.
- Specialty Clinic Networks:Mature referral systems in the United States are expanding treatment capacity and reducing time-to-diagnosis for WHO Functional Class II-III patients.
- Combination Protocol Coverage:Broadening reimbursement for dual and triple therapy regimens enables more aggressive hemodynamic management earlier in disease progression.
Market Restraints
- Prostacyclin Input Concentration:Active pharmaceutical ingredient supply for epoprostenol analogues concentrates among a limited set of contract manufacturers, creating vulnerability to batch contamination or capacity constraints.
- Reimbursement Complexity:CMS nursing reimbursement adjustments for home infusion create friction in site-of-care migration and delay patient transitions from hospital-based care.
- Diagnostic Underpenetration:Right heart catheterization requirements for definitive PAH diagnosis limit incident case identification in health systems without specialized pulmonary hypertension centers.
Strategic Opportunities
- Subcutaneous Delivery Innovation:Next-generation infusion pump miniaturization enables broader patient eligibility for prostacyclin therapy outside institutional settings.
- Pediatric Investigation Plans:EMA-mandated juvenile toxicity studies, though timeline-extending, create first-mover advantage for sponsors establishing pediatric dosing paradigms.
- WHO Essential Medicines Procurement:Epoprostenol inclusion on the WHO essential medicines list opens national health system tender opportunities in middle-income markets.
Industry Challenges
- Hemodynamic Monitoring Integration:Wearable right ventricular pressure sensors require FDA clearance pathways that lag behind therapeutic device approvals, complicating closed-loop dosing systems.
- Specialty Nursing Scarcity:Home infusion nursing workforce gaps in rural United States regions constrain patient enrollment in self-administration programs despite device readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Arterial Hypertension (PAH) Market |
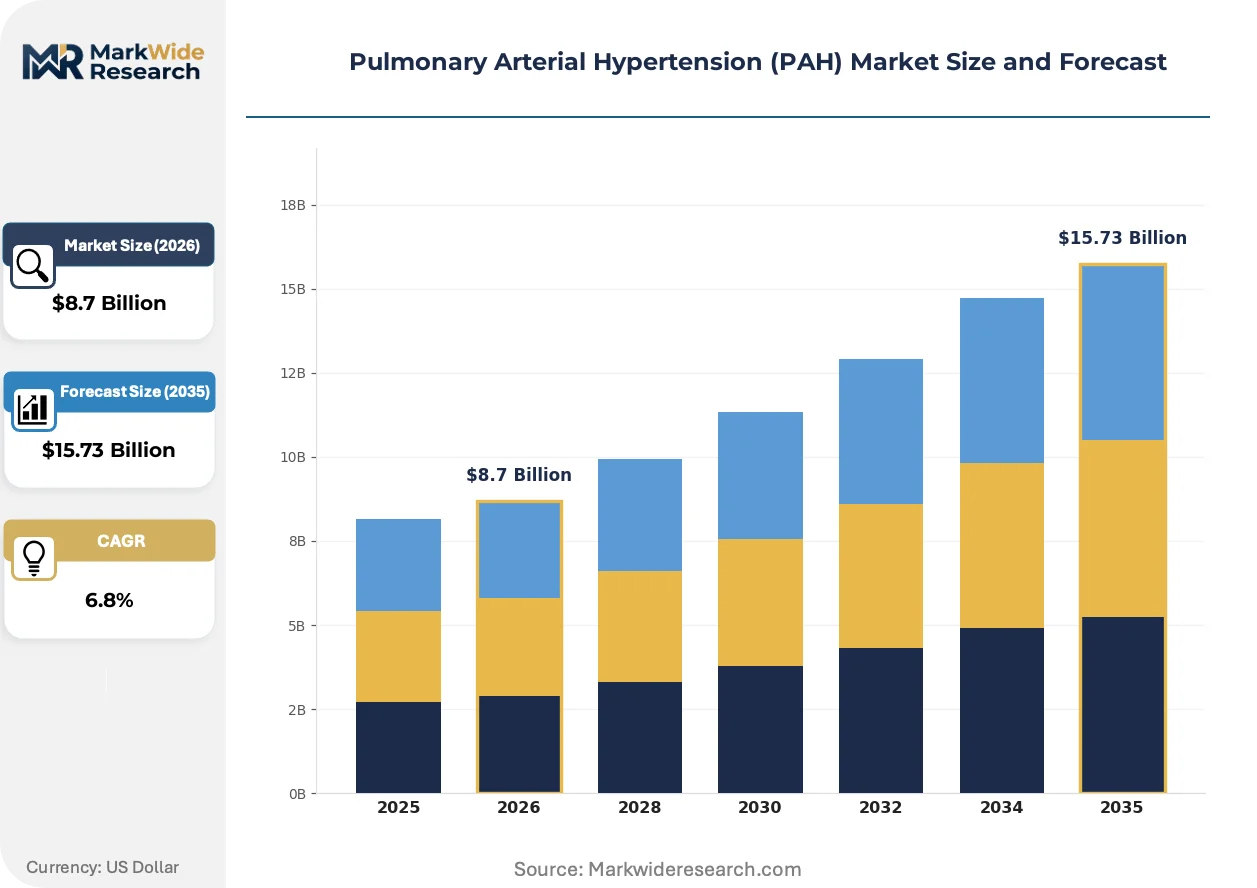
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endothelin Receptor Antagonists, Phosphodiesterase 5 Inhibitors, Prostacyclin Analogues, Soluble Guanylate Cyclase Stimulators Delivery Mode: Oral, Intravenous, Inhalation, Subcutaneous Care Setting: Hospitals, Specialty Clinics, Homecare, Outpatient Facilities Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Johnson & Johnson, Pfizer, United Therapeutics Corporation, Actelion Pharmaceuticals, Novartis, Bayer, GlaxoSmithKline, Merck & Co., Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Arterial Hypertension (PAH) Market Evolving Landscape
Prostacyclin delivery modalities are diversifying rapidly, with device miniaturization and connected health integration creating new competitive battlegrounds beyond molecule efficacy. These shifts are compressing traditional site-of-care boundaries and redefining value capture across the therapy lifecycle.
Implantable intravenous delivery systems are fragmenting the parenteral prostacyclin landscape by eliminating external pump dependency and reducing infection risk. High-acuity patients in WHO Functional Class IV are transitioning to these devices within twelve months of diagnosis. The technology is fragmenting historical loyalty to external infusion platforms and forcing device manufacturers to develop explant-compatible ecosystem architectures.
EMA's centralized pediatric investigation plans now mandate juvenile toxicity studies for all novel endothelin receptor antagonists seeking European approval. This regulatory requirement extends development timelines by eighteen to twenty-four months for adult-focused sponsors. Smaller biotechnology developers are responding by partnering with academic pediatric centers to share study costs and access specialized hemodynamic assessment capabilities.
Site-of-care economics now drive formulary positioning decisions for oral combination therapies in United States managed care organizations. Pharmacy benefit managers are unbundling medical and pharmacy benefit coordination for prostacyclin products, creating new prior authorization complexity. This restructuring is most visible in Medicare Advantage plans, where capitated risk arrangements incentivize earlier transitions to lower-intensity care settings.
Pulmonary Arterial Hypertension (PAH) Market Segmentation
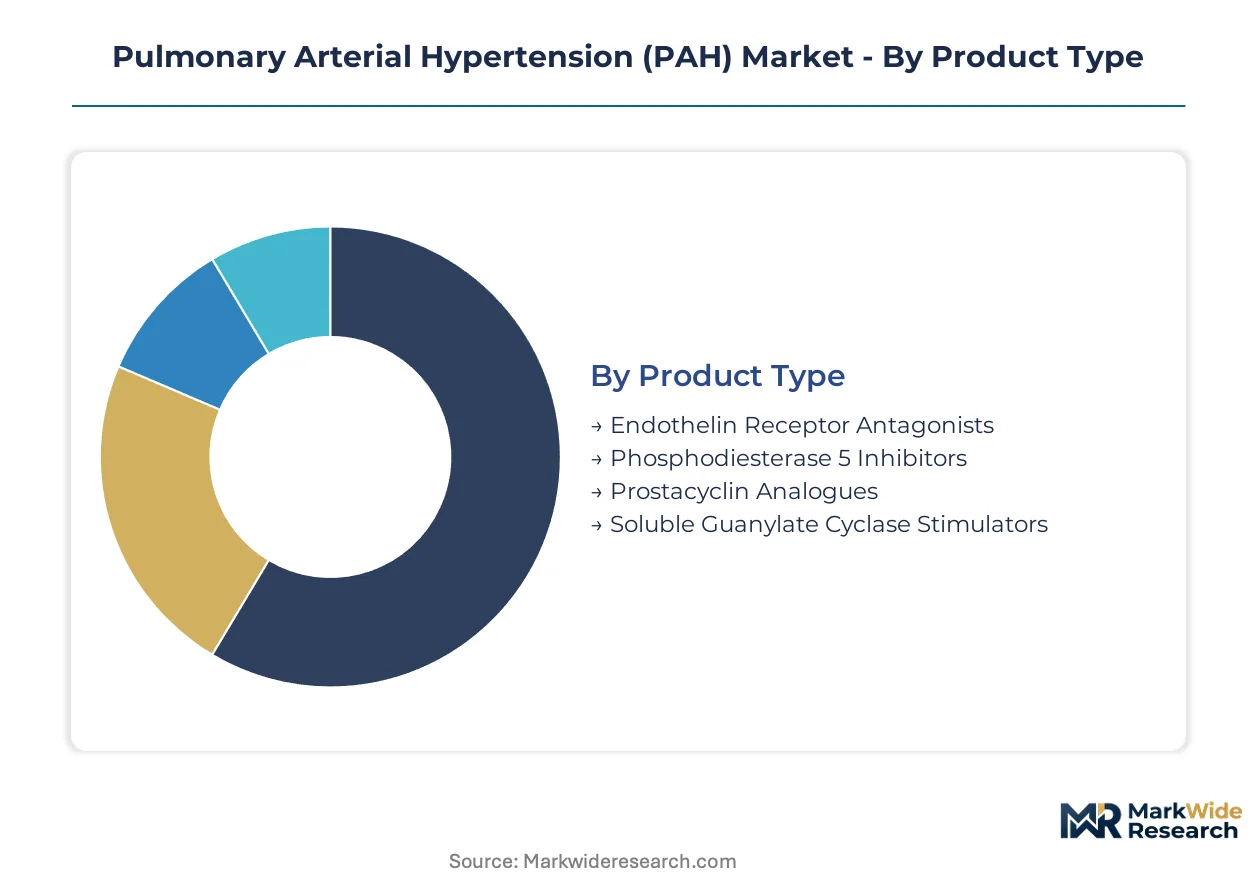
PAH therapeutic segmentation reveals distinct channel economics across product classes and care settings. Each dimension carries implications for reimbursement pathways, nursing infrastructure requirements, and patient adherence monitoring.
Product Type:
Channel mix varies sharply by mechanism of action, with oral agents flowing through retail pharmacy benefit managers while parenteral formulations require medical benefit coordination and specialty distribution networks.
- Prostacyclin Analogues:Synthetic derivatives of prostaglandin I2 with potent vasodilatory and platelet-inhibitory properties. Demand concentrates among WHO Functional Class III-IV patients in the United States, where Medicare Advantage plans increasingly require site-of-care transition to home infusion before authorizing continued therapy.
- Endothelin Receptor Antagonists:Dual ETA/ETB receptor blockers that interrupt vasoconstrictive signaling pathways. Prescription volume clusters among incident cases in specialty clinic networks, driven by oral bioavailability enabling patient self-management without nursing dependency.
- Phosphodiesterase 5 Inhibitors:Oral agents amplifying nitric oxide-mediated vasodilation through cGMP pathway potentiation.
- Soluble Guanylate Cyclase Stimulators:Small-molecule activators targeting the NO-sGC-cGMP axis with a distinct cardiovascular safety profile.
Prostacyclin analogues dominate revenue concentration. Endothelin receptor antagonists represent where prescription volume expansion concentrates.
Delivery Mode:
Cost tier stratification follows delivery complexity, with implantable and infusion-based modalities commanding premium reimbursement against generic-exposed oral tablets.
- Intravenous:Continuous central venous catheter delivery of epoprostenol requiring sterile compounding and infection prophylaxis protocols. Demand localizes in hospital-based initiation protocols and high-acuity patients with right ventricular failure.
- Subcutaneous:Microinfusion pump systems enabling ambulatory prostacyclin administration through interstitial tissue. Adoption is climbing the fastest among patients transitioning from hospital to homecare settings, supported by pump miniaturization and connected health integration.
- Oral:Tablet and capsule formulations of endothelin antagonists and PDE5 inhibitors for first-line and combination maintenance therapy.
- Inhalation:Nebulized prostacyclin analogues for acute vasodilatory effect with reduced systemic exposure.
Intravenous delivery anchors the premium pricing tier. Subcutaneous systems are gaining share fastest as site-of-care economics shift toward home-based administration.
Care Setting:
Patient acuity and reimbursement mechanics determine site selection, with risk-bearing entities incentivizing earlier discharge to lower-intensity settings.
- Homecare:Self-administered therapy with remote nursing oversight and telemedicine-based hemodynamic monitoring. Volume is expanding most quickly in United States Medicare Advantage markets where capitated arrangements reward reduced institutional utilization.
- Specialty Clinics:Referral centers with right heart catheterization capability and multidisciplinary pulmonary hypertension teams. These facilities concentrate diagnostic case identification and complex therapeutic escalation decisions.
- Hospitals:Acute care institutions managing decompensated right heart failure and prostacyclin initiation protocols.
- Outpatient Facilities:Ambulatory infusion centers for patients requiring supervised parenteral administration without hospital admission.
Specialty clinics dominate diagnostic throughput. Homecare is where patient-month expansion concentrates.
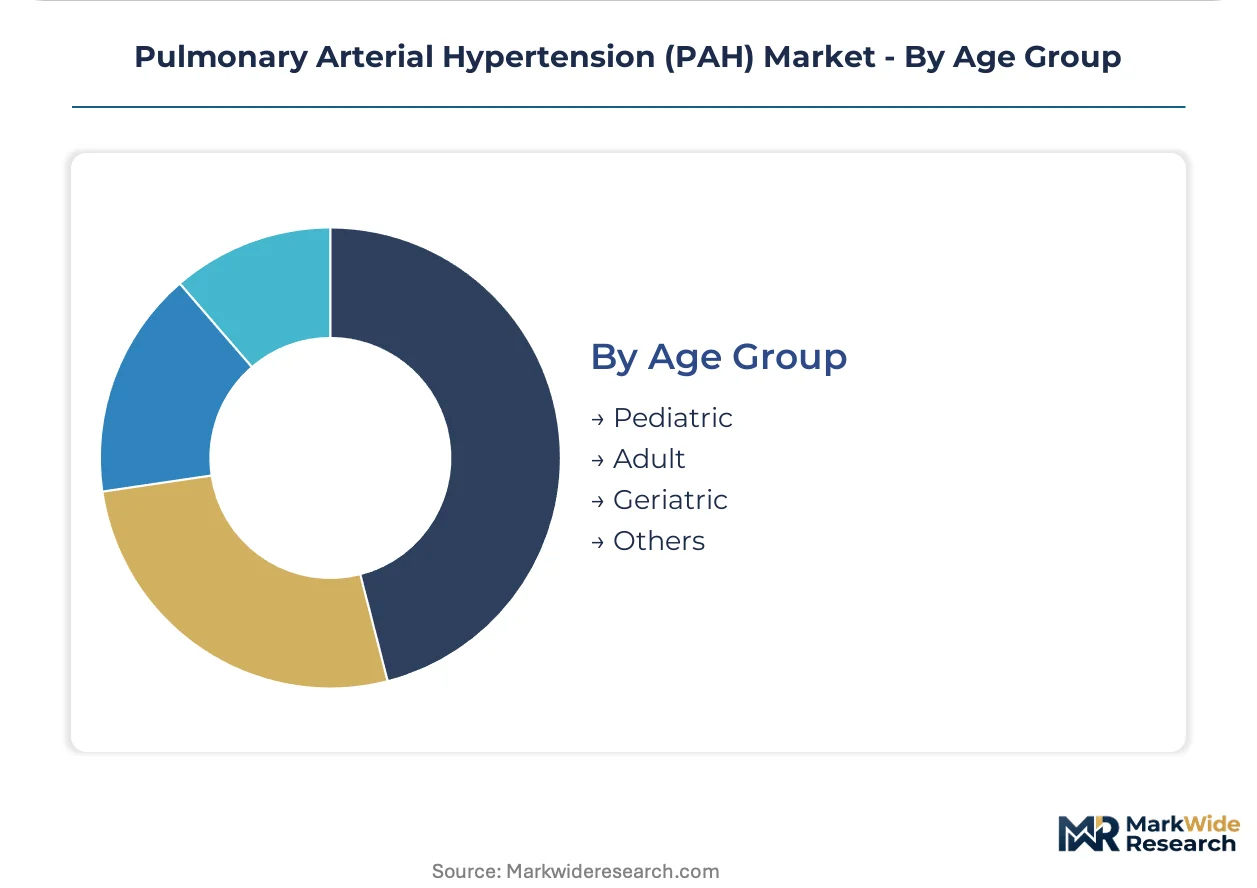
Age Group:
Regulatory mandates and developmental pharmacology create distinct trial and labeling requirements across age strata.
- Adult:Patients aged 18-64 years comprising the historical trial population for all approved PAH therapies. This segment anchors current prescribing patterns and formulary positioning.
- Pediatric:Juvenile patients requiring EMA-mandated pediatric investigation plans and weight-based dosing paradigms. Sponsors pursuing European approval must extend development timelines for juvenile toxicity studies.
- Geriatric:Patients over 65 years with comorbid cardiopulmonary conditions and polypharmacy considerations.
- Others:Pregnant patients and other special populations with limited safety data requiring individualized risk-benefit assessment.
Adult patients dominate the treated population. Pediatric indications represent where label expansion investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for prostacyclin analogues clusters in Switzerland and the United States, while clinical trial density and regulatory submission volume concentrate in Germany and Japan. This geographic separation between supply origination and development activity shapes cross-border licensing patterns and reimbursement negotiation timelines.
United States
Medicare Advantage capitation models accelerate site-of-care migration toward home infusion, with specialty pharmacy networks in Philadelphia and Boston expanding nursing capacity for prostacyclin self-administration. The FDA's orphan drug exclusivity framework grants seven-year market protection, de-risking investment in small-population therapeutics. United Therapeutics Corporation anchors parenteral prostacyclin infrastructure through integrated care delivery platforms concentrated in the Mid-Atlantic and Southeast.
Germany
EMA centralized pediatric investigation plans mandate juvenile toxicity studies that extend development timelines for adult-focused sponsors seeking European approval. The country's statutory health insurance system maintains broad reimbursement for combination therapy protocols, supporting earlier therapeutic escalation. Heidelberg and Munich host specialized pulmonary hypertension centers that concentrate diagnostic case identification and right heart catheterization capacity.
Switzerland
Contract manufacturing organizations in Basel and Zurich dominate active pharmaceutical ingredient supply for epoprostenol analogues, creating concentration risk for batch contamination or capacity constraints. Swissmedic maintains alignment with EMA pediatric requirements while offering expedited review pathways for orphan-designated therapies. The country's precision chemistry cluster supports high-potency prostacyclin synthesis with containment infrastructure exceeding standard pharmaceutical manufacturing specifications.
Japan
PMDA's Sakigake designation system accelerates review timelines for novel PAH therapeutics addressing unmet medical need in WHO Functional Class IV patients. Tokyo and Osaka pulmonary hypertension referral networks concentrate diagnostic expertise and hemodynamic assessment capabilities. Domestic sponsors partner with academic medical centers to generate Japan-specific efficacy data supporting reimbursement negotiations with Chuikyo, the Central Social Insurance Medical Council.
United Kingdom
NICE technology appraisals for oral endothelin receptor antagonists influence formulary positioning across NHS England specialized commissioning frameworks. London and Manchester maintain national pulmonary hypertension centers with right heart catheterization capacity and multidisciplinary team infrastructure. The MHRA's post-Brexit regulatory autonomy enables divergence from EMA pediatric investigation timelines for sponsors prioritizing adult-only indications.
Pulmonary Arterial Hypertension (PAH) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PAH therapeutic landscape. Integrated biopharmaceutical companies with parenteral infrastructure dominate high-acuity segments requiring nursing coordination and device interoperability, while oral therapy specialists compete on prescription volume and pharmacy benefit manager access. The market structure rewards vertical control over care delivery logistics rather than molecule differentiation alone. Dominant competitive moves include strategic partnerships with home infusion nursing networks and portfolio diversification into implantable delivery systems.
Among integrated parenteral therapy providers, United Therapeutics Corporation anchors infrastructure-heavy positioning through coordinated specialty pharmacy and nursing networks. Johnson & Johnson occupies oral therapy market presence through its Janssen subsidiary's endothelin receptor antagonist portfolio. Bayer represents soluble guanylate cyclase stimulation with cardiovascular safety differentiation. These three exemplify how competitive advantage in PAH increasingly derives from site-of-care control rather than clinical efficacy alone.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| United Therapeutics Corporation |
| Actelion Pharmaceuticals |
| Novartis |
| Bayer |
| GlaxoSmithKline |
| Merck & Co. |
| Gilead Sciences |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between United States Medicare Advantage plans and specialty pharmacy networks lock in prostacyclin supply access while anchoring price visibility across multi-year patient episodes. These contracts bundle device procurement, nursing coordination, and pharmaceutical reimbursement into single per-member-per-month rates that compress margin transparency for manufacturers.
Pricing Analysis
CMS reimbursement adjustments dictate the pricing tier structure across prostacyclin delivery modalities, with intravenous formulations commanding premium medical benefit rates against subcutaneous systems on pharmacy benefits. Price differentiation stems from site-of-care intensity and infection risk mitigation protocols, with implantable devices capturing the highest tier. Cost compression in subcutaneous infusion pumps is intensifying as pump commoditization accelerates. Medicare Advantage plans exhibit the highest price sensitivity, while commercial payers in employer-sponsored plans show greater flexibility for combination therapy premiums.
Supply Chain Analysis
Container availability on transatlantic trade lanes from Basel and Zurich to East Coast distribution hubs constrains epoprostenol API shipment scheduling during quarterly production cycles. Active pharmaceutical ingredient manufacturing clusters in Switzerland, the United States, and India, with high-potency containment facilities in Basel feeding global formulation sites. Raw material dependencies center on specialized prostaglandin precursors, sterile filtration membranes, and medical-grade silicone pump components. Single-source vulnerability concentrates in Swiss contract manufacturing organizations handling epoprostenol sodium synthesis. Distribution runs through cold-chain specialty distributors with DEA-controlled substance licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across site-of-care models creates multiple viable competitive positions as home infusion nursing networks mature and payer risk arrangements diversify. Each operational archetype—hospital-based, specialty clinic, and home self-administration—supports distinct margin structures and capability requirements.
For Market Incumbents: Secure exclusive nursing network contracts in United States Medicare Advantage markets before capitated arrangements fully consolidate site-of-care decisions. Incumbents must anchor backward integration into implantable pump manufacturing to defend against device commoditization threatening external infusion platform margins. United Therapeutics Corporation's integrated care delivery infrastructure demonstrates how vertical control over logistics and clinical support sustains pricing power despite therapeutic equivalence. For New Entrants and Emerging Players: Differentiate on pediatric dosing paradigms by partnering with academic medical centers to share EMA-mandated juvenile toxicity study costs. The most penetrable white-space sits in subcutaneous delivery miniaturization for WHO Functional Class II patients transitioning from oral combination therapy. A direct-to-specialty-clinic go-to-market model bypasses entrenched payer formulary barriers by capturing prescriber preference before prior authorization protocols activate. For Investors and Strategic Acquirers: Device-pump specialists with FDA-cleared interoperability architectures represent the highest-conviction acquisition archetype as closed-loop hemodynamic monitoring systems mature. Long-term viability hinges on five-to-ten year site-of-care migration completion and whether implantable systems displace external pumps entirely. The signal to watch is CMS nursing reimbursement parity between hospital-based and home infusion settings as an inflection indicator for self-administration program economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Partnership | EMA-mandated juvenile studies extend timelines but create exclusivity moats for first movers in European pediatric labeling. |
| Implantable Delivery System Development | FDA-cleared implantable pumps eliminate external device dependency and reduce sepsis risk in WHO Functional Class IV patients. |
| Home Infusion Nursing Network Expansion | Specialty nursing scarcity in rural United States regions constrains patient enrollment despite device readiness for self-administration. |
| Closed-Loop Hemodynamic Monitoring Integration | Wearable right ventricular pressure sensors lag FDA clearance timelines behind therapeutic device approvals. |
| WHO Essential Medicines Tender Positioning | Epoprostenol inclusion opens national health system procurement opportunities in middle-income markets with centralized purchasing. |
Research Methodology
A spread of perspectives from formulary directors at United States payers, regulatory affairs leads at EMA-focused sponsors, specialty clinic medical directors, home infusion nursing coordinators, and biomedical engineers at pump manufacturers converged on the working assumptions underlying this analysis. Primary interview findings were validated against FDA orphan drug designation filings, EMA centralized pediatric investigation plan submissions, CMS Medicare Advantage rate-setting documentation, ClinicalTrials.gov protocol registrations, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down revenue triangulation were cross-checked for consistency.
Segmentation dimensions modeled include prostacyclin mechanism of action, delivery route complexity, care setting intensity, patient functional class, and regional regulatory cluster across the analysis window. CAGRs were derived from epidemiological incidence projections, therapy penetration curves by functional class, and site-of-care shift elasticities to payer incentives. Forecast inputs incorporated right heart catheterization capacity expansion rates, Medicare Advantage enrollment growth, and implantable device adoption velocity in high-acuity populations.
Decision-makers should treat outputs as directional under assumptions of stable orphan drug exclusivity frameworks and continued CMS reimbursement for combination therapy protocols; material deviation would warrant model refresh. Specific risk factors include batch contamination events at Swiss API manufacturers, abrupt nursing reimbursement cuts affecting home infusion economics, and diagnostic underpenetration limiting incident case identification. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Malignant Pleural Effusion Market