
 Optoelectronics Market | 2026-2036
Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Optoelectronics Market Intelligence
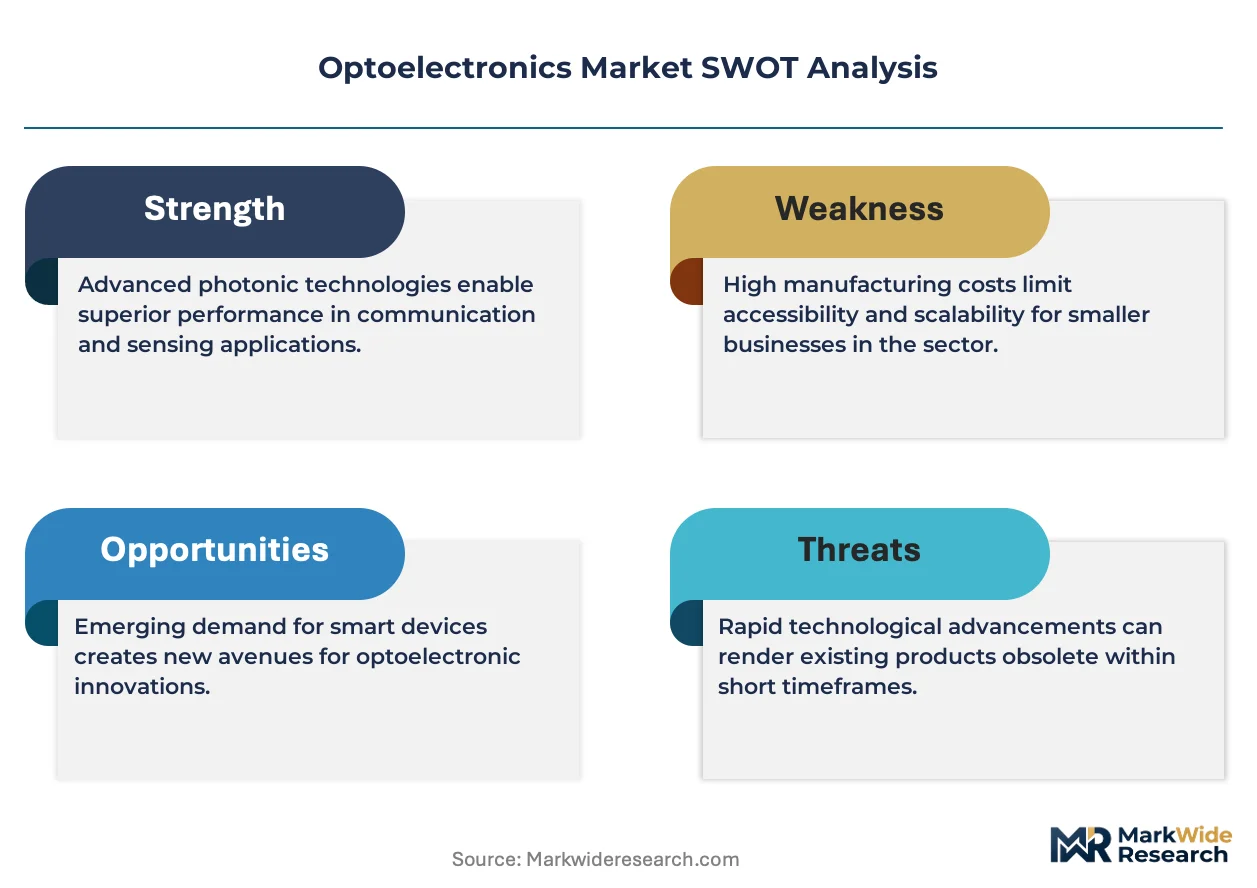
IEC 60825 laser safety certification is rotating as a gatekeeping standard for suppliers targeting industrial and defense-grade optoelectronic modules. Broadcom Inc. leverages its vertical integration in optical interconnects to sustain pricing power in data center transceivers. Samsung Electronics Co., Ltd. anchors display panel output through captive OLED production lines. Nichia Corporation dominates high-brightness LED epitaxy, giving it upstream control over phosphor and chip architectures.
Optoelectronics encompasses devices that convert electrical signals into light and vice versa, typically operating across ultraviolet to infrared wavelengths with response times measured in nanoseconds; these components enable optical communication, sensing, and display functions in precision industrial and consumer systems. Fiber optics infrastructure underpins long-haul telecommunication backbones where margin pools concentrate in coherent transmission modules. CMOS image sensors displace legacy CCD architectures across automotive and mobile vision systems due to lower power draw and on-chip integration. OLED technology captures premium display segments while LCD sustains volume in cost-sensitive panels.
REACH restrictions on hazardous substances and RoHS substance limits constrain material choices for LED phosphors and laser diode substrates in European-bound products. The EPA regulates mercury content in certain lamp-based optoelectronic systems, while FDA laser product performance standards govern medical and cosmetic device classifications. Stakeholders must monitor how evolving efficiency mandates and substance restrictions reshape supplier qualification timelines and component sourcing strategies.
Market Dynamics
Automotive LiDAR qualification timelines and China's GB efficiency mandates are compressing supplier certification cycles while concentrating procurement authority among vertically integrated module assemblers in East Asian manufacturing clusters.
Growth Catalysts
- Automotive LiDAR adoption:Tier-1 suppliers are qualifying solid-state scanning modules for Level 3 autonomy programs, pulling demand for 1550nm laser diodes and SPAD arrays.
- REACH substance restrictions:European RoHS limits on cadmium and lead in LED phosphors are accelerating conversion to quantum dot and perovskite alternatives.
- Data center coherent transmission:Cloud operators in Ashburn, Frankfurt, and Singapore are deploying 800G ZR+ transceivers, expanding addressable volume for indium phosphide modulators.
Market Restraints
- Epitaxial wafer concentration:High-brightness LED and laser diode substrates depend on MOCVD capacity concentrated in South Korean and Taiwanese foundries, creating single-source vulnerability.
- Raw material volatility:Indium and gallium prices fluctuate with photovoltaic and magnet alloy demand, squeezing margins on InGaN and InGaAsP device fabrication.
- Thermal management limits:Power dissipation in high-brightness emitters constrains package density in automotive headlamp and projection applications.
Strategic Opportunities
- Underpenetrated industrial sensing:German and Japanese machine builders are retrofitting production lines with VCSEL-based 3D vision for defect detection.
- Regulatory tailwind from dual carbon goals:China's GB 30255 and GB 37478 efficiency standards mandate minimum luminous efficacy for commercial lighting, forcing LED upgrades.
- Silicon photonics convergence:Integration of CMOS electronics with photonic waveguides is collapsing cost structures for datacom transceivers.
Industry Challenges
- IEC 60825 certification timelines:Laser safety documentation for Class 3B and Class 4 industrial modules requires 9-14 month validation cycles, delaying revenue recognition.
- Compound semiconductor talent scarcity:MOCVD operation and III-V epitaxy engineering expertise concentrates among aging specialists in Japan and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optoelectronics Market |
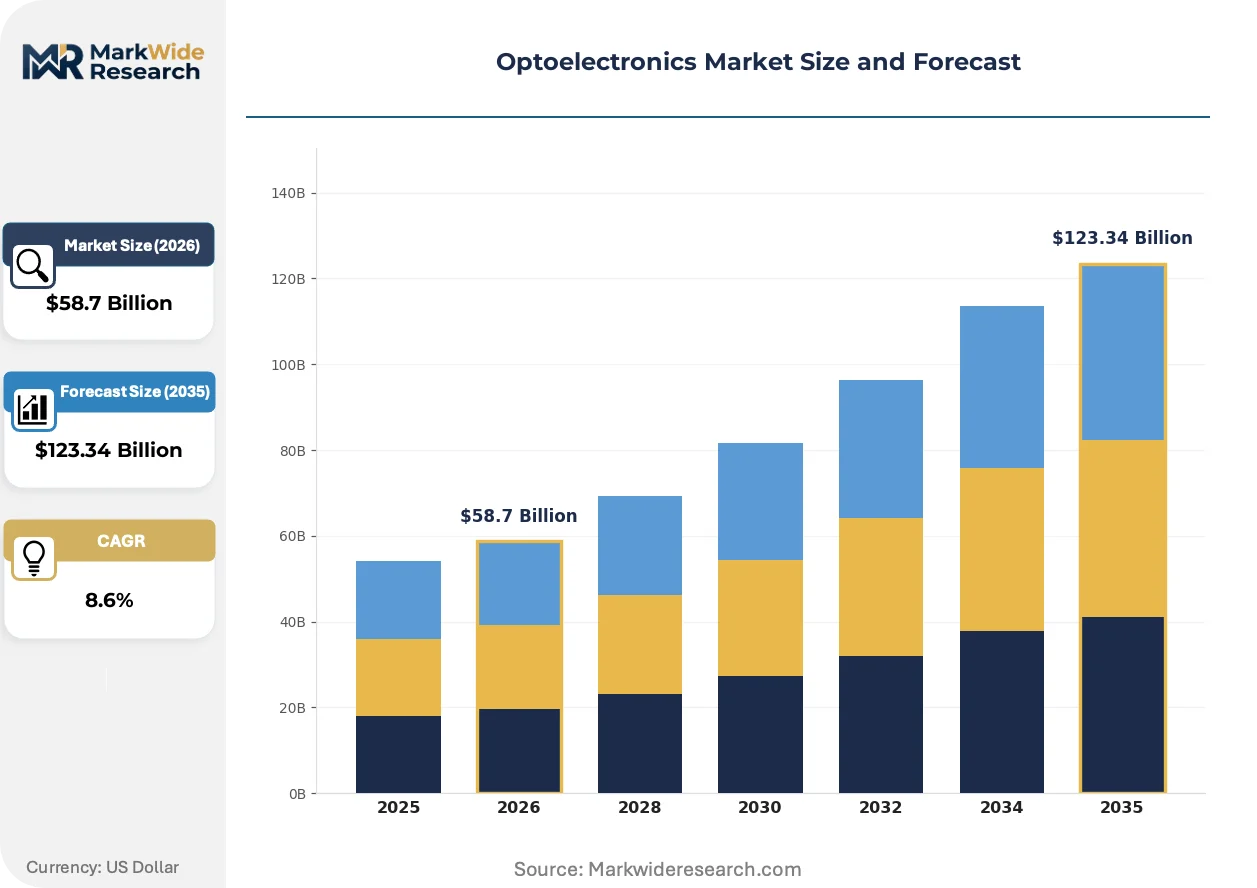
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $123.34 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Light Emitting Diodes, Laser Diodes, Optical Sensors, Phototransistors Technology: Fiber Optics, OLED, LCD, CCD, CMOS Image Sensors Application: Telecommunication, Consumer Electronics, Defense & Aerospace, Industrial Automation, Data Storage End User: Manufacturers, Telecommunication Service Providers, Defense Agencies, Research Institutes |
| Companies Covered | Intel Corporation, Panasonic Corporation, Broadcom Inc., Sharp Corporation, Sony Corporation, OmniVision Technologies Inc., Texas Instruments Incorporated, Nichia Corporation, Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optoelectronics Market Strategic Shifts & Innovations
Photonic integration and regulatory efficiency mandates are restructuring competitive advantage around materials science capabilities and certification velocity rather than scale economics alone.
Micro-LED display technology is bifurcating between sub-10 micron chips for augmented reality near-eye displays and 20-50 micron devices for premium television backlighting. Apple and Meta are accelerating micro-LED roadmaps for headset and smartwatch applications. The technology is bifurcating supply chains between gallium nitride-on-silicon and sapphire-based epitaxy approaches, fragmenting equipment vendor relationships.
China's GB standards for solid-state lighting efficiency are tightening luminous efficacy minimums for commercial and residential fixtures. MIIT enforcement of GB 30255-2019 and GB 37478-2019 is disqualifying legacy LED architectures from government procurement tenders. Domestic LED packagers in Shenzhen and Xiamen are accelerating phosphor-converted and chip-on-board designs to maintain eligibility.
Buyer consolidation among hyperscale cloud operators is compressing transceiver qualification cycles and unbundling after-sales service from hardware contracts. Amazon Web Services, Microsoft Azure, and Google Cloud are demanding 5-year reliability guarantees with penalty clauses, shifting risk to optical module suppliers. This procurement compression is most visible in Singapore and Dublin data center clusters where co-location density is highest.
Optoelectronics Market Segmentation
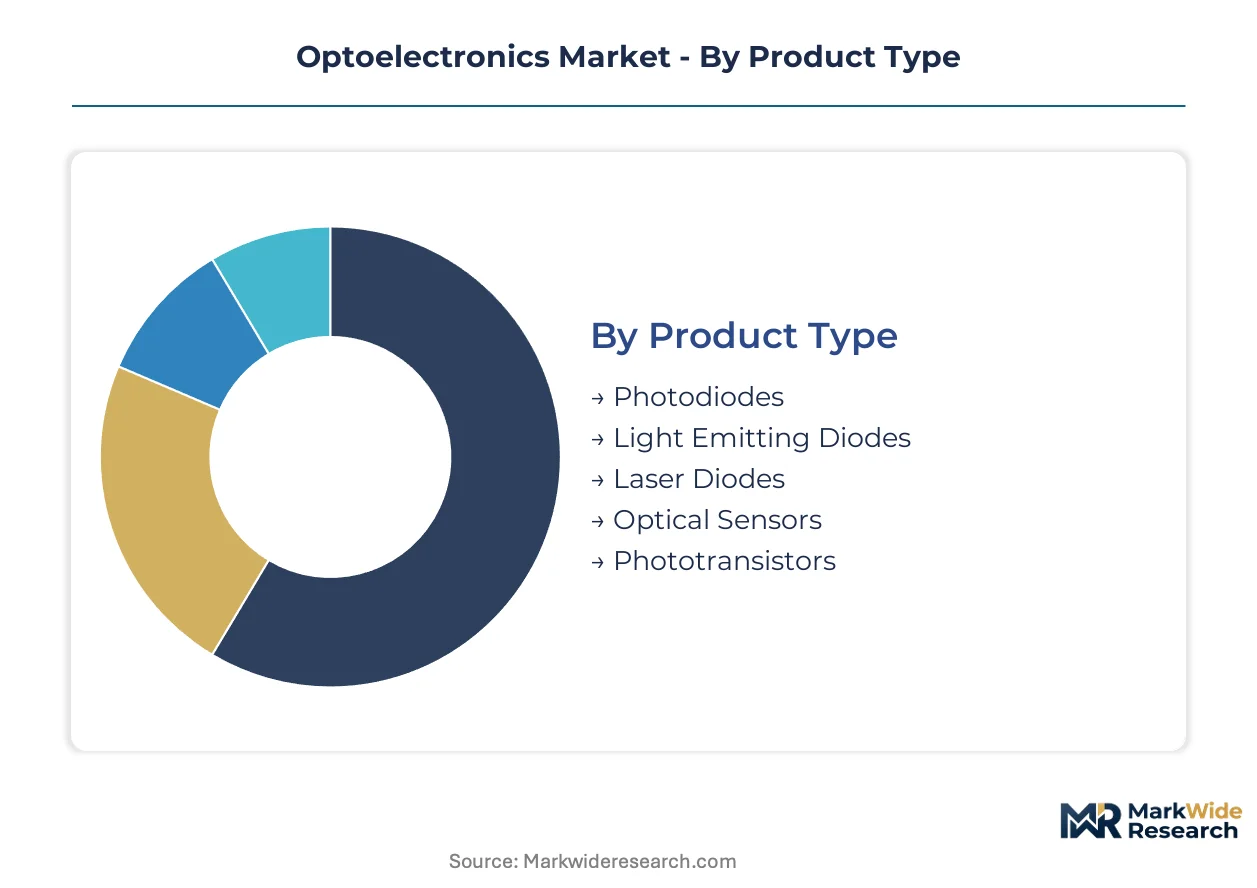
Optoelectronics segmentation reveals how regulatory frameworks and application requirements fragment procurement specifications across product categories. Component qualification standards vary sharply by end-use, creating distinct margin pools that resist commoditization.
Product Type:
REACH substance restrictions and IEC 60825 laser safety classifications impose divergent compliance burdens across component families, reshaping supplier qualification timelines.
- Photodiodes:These p-n junction devices convert incident photons into electrical current with responsivity peaking in silicon at 900nm or InGaAs at 1550nm. Automotive LiDAR receivers and fiber optic receivers in Frankfurt and Singapore data centers drive specification tightening for bandwidth and dark current performance.
- Light Emitting Diodes:Solid-state emitters spanning visible to infrared wavelengths with efficacy governed by China's GB 30255 and GB 37478 mandates. Commercial retrofit programs in Shenzhen and Xiamen are accelerating demand for phosphor-converted white packages that meet procurement tender thresholds.
- Laser Diodes:Coherent emitters operating from 405nm violet through 1550nm eye-safe automotive wavelengths. FDA performance standards and IEC Class 3B documentation requirements extend validation cycles.
- Optical Sensors:Ambient light, proximity, and spectral detection modules integrating photodiodes with signal conditioning. Mobile device manufacturers specify sub-milliwatt standby consumption.
- Phototransistors:Bipolar junction devices offering internal current gain for switching applications. Industrial encoder manufacturers in Germany and Japan specify response time uniformity.
Light Emitting Diodes handles the majority of throughput; Laser Diodes is expanding most quickly on share.
Technology:
Cost structures bifurcate between mature display backplanes and emerging photonic integration platforms that collapse packaging overhead.
- Fiber Optics:Glass or plastic waveguides transmitting modulated light across telecommunication and sensing applications. Cloud operators deploying 800G coherent links in Ashburn and Dublin are pulling demand for low-loss single-mode fiber and indium phosphide modulators.
- OLED:Organic electroluminescent stacks deposited on flexible or rigid substrates with self-emissive pixels. South Korean display ecosystems anchor volume production for premium mobile and television panels.
- LCD:Liquid crystal cells with backlight units sustaining cost-sensitive display segments. Volume concentrates in television and monitor applications where GB efficiency mandates drive LED backlight upgrades.
- CCD:Charge-coupled device image sensors with high uniformity but elevated power draw. Scientific instrumentation and legacy machine vision retain residual demand.
- CMOS Image Sensors:Active pixel arrays with on-chip analog-to-digital conversion enabling low-power integration. Automotive surround-view and mobile multi-camera arrays are displacing CCD architectures.
CMOS Image Sensors is climbing the fastest; LCD retains the largest installed base despite share erosion.
Application:
Customer procurement authority concentrates in sectors where safety certification or national security classification creates vendor stickiness.
- Telecommunication:Long-haul, metro, and access network infrastructure spanning submarine cables to 5G fronthaul. Coherent transmission modules in the 400G-800G range command premium pricing in Frankfurt and Singapore clusters.
- Consumer Electronics:Smartphones, wearables, and display devices with annual refresh cycles. VCSEL-based facial recognition and under-display optical sensors are specification priorities for flagship tier launches.
- Defense & Aerospace:Ruggedized LiDAR, targeting systems, and secure free-space optical links. ITAR and EAR export controls restrict supplier pools for classified programs.
- Industrial Automation:Machine vision, barcode scanning, and precision measurement on production lines. German and Japanese equipment builders are retrofitting VCSEL-based 3D inspection for defect detection.
- Data Storage:Optical disc drives and holographic storage with declining volume but persistent archival demand. Enterprise cold storage retains niche specifications.
Telecommunication commands the highest absolute spend; Industrial Automation is gaining share fastest on retrofit cycles.
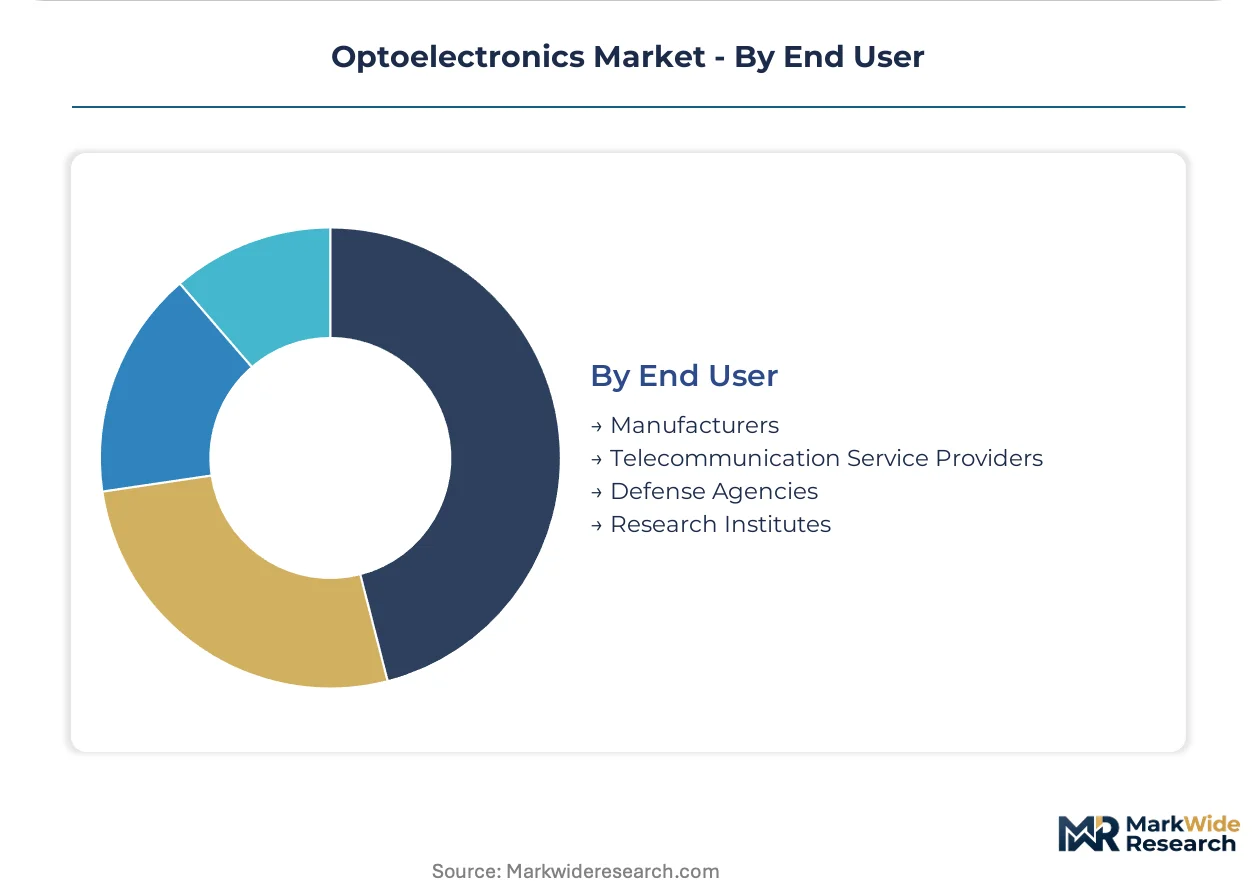
End User:
Contract structures vary from spot purchasing among component distributors to multi-year reliability guarantees with penalty clauses.
- Manufacturers:Tier-1 and Tier-2 integrators assembling modules for downstream equipment. Automotive LiDAR qualification timelines are compressing supplier onboarding.
- Telecommunication Service Providers:Network operators specifying transceiver performance for backbone and data center interconnect. Five-year reliability guarantees with penalty clauses are shifting risk to optical module vendors.
- Defense Agencies:National procurement bodies with security-cleared supplier requirements. IEC 60825 documentation and ITAR compliance extend sales cycles.
- Research Institutes:Academic and government laboratories procuring specialized emitters and detectors. Custom wavelength and packaging specifications dominate purchasing.
Telecommunication Service Providers directs the largest procurement volume; Defense Agencies maintains the steepest expansion trajectory on LiDAR and sensing modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunication service providers and automotive Tier-1 integrators concentrate procurement authority in East Asian manufacturing clusters, German industrial automation corridors, and North American data center hubs. Buyer power is compressing supplier margins while accelerating qualification timelines for LiDAR and coherent transmission modules.
China
MIIT enforcement of GB 30255-2019 and GB 37478-2019 efficiency standards is disqualifying legacy LED architectures from government procurement tenders. Domestic LED packagers in Shenzhen and Xiamen are accelerating phosphor-converted and chip-on-board designs to maintain eligibility for commercial lighting retrofits.
South Korea
Samsung Electronics anchors display panel output through captive OLED production lines in Gyeonggi Province. The Seoul Capital Area concentrates MOCVD capacity for high-brightness LED epitaxy, creating upstream chokepoints for laser diode and image sensor substrate supply.
United States
FDA laser product performance standards govern medical and cosmetic device classifications, extending documentation cycles for Class 3B and Class 4 industrial modules. Cloud operators in Ashburn, Virginia are deploying 800G ZR+ transceivers, pulling demand for indium phosphide modulators and coherent transmission components.
Germany
REACH restrictions on hazardous substances and RoHS substance limits constrain material choices for LED phosphors and laser diode substrates in European-bound products. Machine builders in Bavaria and Baden-Württemberg are retrofitting production lines with VCSEL-based 3D vision systems for defect detection.
Japan
Nichia Corporation dominates high-brightness LED epitaxy from its Anan operations, giving it upstream control over phosphor and chip architectures. METI efficiency guidelines and JIS standards shape qualification requirements for automotive and industrial optoelectronic modules exported to ASEAN markets.
Optoelectronics Market Key Industry Players
Player mix skews toward diversified electronics conglomerates with captive semiconductor fabrication capabilities, alongside specialized compound semiconductor foundries and optical component specialists. Three archetypes dominate: vertically integrated module assemblers controlling epitaxy through packaging, fabless design houses licensing silicon photonics IP, and materials-science-led substrate suppliers commanding phosphor and laser diode architectures. Competitive moves concentrate on MOCVD capacity expansion in East Asian clusters and strategic partnerships collapsing CMOS-photonic integration costs.
Within the diversified electronics tier, Intel Corporation, Broadcom Inc., and Samsung Electronics Co., Ltd. represent scale-driven positions spanning data center interconnects, consumer imaging, and display ecosystems. These entities exemplify how backward integration into compound semiconductor fabrication and captive OLED production lines sustains pricing power against fabless competitors. Nichia Corporation occupies a specialist position upstream in LED epitaxy, while Panasonic Corporation and Sony Corporation anchor diversified portfolios across industrial sensing and image sensor applications.
| Leading Market Players |
|---|
| Intel Corporation |
| Panasonic Corporation |
| Broadcom Inc. |
| Sharp Corporation |
| Sony Corporation |
| OmniVision Technologies Inc. |
| Texas Instruments Incorporated |
| Nichia Corporation |
| Samsung Electronics Co., Ltd. |
| Others |
Cost & Logistics Intelligence
IEC 60825 laser safety certification gates both supplier qualification timelines and price differentiation across industrial and defense-grade optoelectronic modules, compressing procurement cycles for Class 3B and Class 4 devices while stratifying margins between certified and uncertified tiers.
Pricing Analysis
Cost-plus contracts with indium and gallium price indexation dominate raw material pass-through structures for InGaN and InGaAsP device fabrication. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical emitters from industrial-grade alternatives and unqualified spot-market components. Price differentiation hinges on certification grade and volume scale, with hyperscale cloud operators extracting five-year reliability guarantees. Cost compression in standard-tier LED packages is intensifying because MIIT enforcement of GB efficiency mandates forces phosphor-converted redesigns. Automotive LiDAR integrators show least price sensitivity; commercial lighting retrofitters exhibit highest.
Supply Chain Analysis
Inventory buffers for MOCVD-grown epitaxial wafers stretch lead times to 14-18 weeks during capacity tightness in South Korean and Taiwanese foundries. Geographic supply concentration centers on South Korea for OLED display backplanes, Taiwan for CMOS image sensor foundry services, and Japan for high-brightness LED epitaxy. Raw material dependencies draw from indium for InGaN emitters, gallium for photovoltaic-magnet alloy competition, and sapphire substrates for micro-LED development. Single-source vulnerability in MOCVD capacity creates supply chain risk. Distribution runs through vertically integrated module assemblers in East Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mastery of III-V epitaxy engineering and MOCVD operation concentrates among aging specialists in Japan and the United States, creating a bottleneck that reshapes competitive viability around talent acquisition and knowledge transfer systems.
For Market Incumbents: Fortify MOCVD capacity positions in Gyeonggi Province and Hsinchu Science Park to preempt substrate supply constraints. Deepen backward integration into phosphor and laser diode architectures to offset pricing pressure from fabless silicon photonics competitors. Accelerate IEC 60825 documentation capabilities to compress 9-14 month validation cycles threatening revenue recognition timelines. For New Entrants and Emerging Players: Lead with VCSEL-based 3D vision modules targeting German and Japanese machine builder retrofit programs for defect detection. Underpenetrated industrial sensing offers lowest qualification barriers compared to automotive LiDAR or data center transceiver segments. Partner with Shenzhen LED packagers to access GB standards-compliant phosphor-converted designs for commercial lighting tenders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compound semiconductor foundries in South Korea and Taiwan holding captive MOCVD capacity but lacking photonic integration roadmaps. Long-term viability across the projection horizon favors substrate suppliers with upstream control over gallium nitride epitaxy. Watch indium price volatility as inflection indicator for InGaN device margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| MOCVD Capacity Expansion | South Korean foundries adding reactors secures substrate supply for automotive LiDAR programs. |
| Silicon Photonics Integration | CMOS-photonic convergence collapses packaging costs for 800G datacom transceivers in Ashburn clusters. |
| GB Standards Compliance Investment | Shenzhen packagers adopting phosphor-converted designs maintain government procurement eligibility. |
| Laser Safety Certification Acceleration | Reduced IEC 60825 validation cycles unlock faster revenue recognition for industrial module suppliers. |
| III-V Epitaxy Talent Acquisition | Recruiting aging Japanese specialists addresses compound semiconductor engineering scarcity constraining output. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with MOCVD equipment engineers, LED packaging procurement managers, automotive LiDAR platform architects, and datacenter transceiver qualification leads. Secondary validation drew from SEC filings of diversified electronics conglomerates, MIIT GB standards documentation, IEC 60825 certification registries, and hyperscaler capex disclosures for coherent transmission deployment. Bottom-up and top-down triangulation reconciled component shipment data with end-use equipment production volumes.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, technology platform, application sector, and end-user contract structure. CAGRs derived from regression analysis against historical capacity utilization, regulatory enforcement timelines, and substitution elasticity between OLED and LCD display architectures. Industry-specific inputs included MOCVD reactor installation forecasts and MIIT tender eligibility patterns for solid-state lighting retrofits.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement of GB efficiency mandates or abrupt indium supply disruption would require recalibration. Forecasts reflect assumptions regarding automotive autonomy program timelines and cloud operator transceiver refresh cycles. Revision becomes warranted when silicon photonics yield rates cross thresholds enabling cost-parity with indium phosphide modulators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Light Projector Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Quantum Cascade Lasers Market