
 Middle East and Africa Marine Communication Systems Market | 2026-2036
Middle East and Africa Marine Communication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Marine Communication Systems Market Foresight
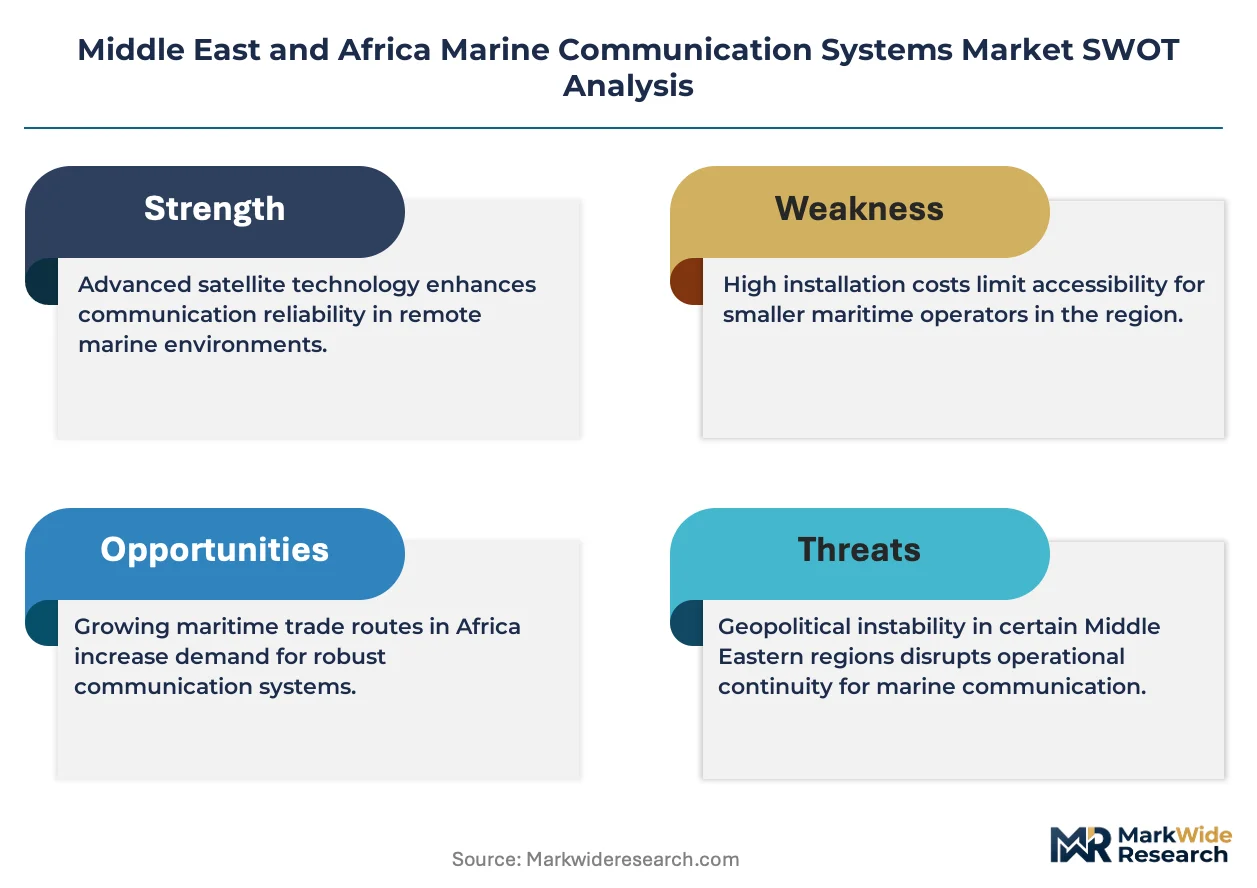
Leasing-based satellite terminal deployment is rewriting capital allocation for vessel operators across the Middle East and Africa. Inmarsat leverages its L-band constellation dominance to anchor long-term service contracts with major shipping lines traversing Gulf of Aden routes. Iridium Communications competes through low-Earth-orbit coverage advantages that sustain connectivity in high-latitude fishing zones off Morocco and Namibia. KVH Industries specializes in hybrid VSAT solutions that differentiate its portfolio for superyacht and offshore supply vessel segments.
Marine communication systems encompass integrated hardware and software platforms enabling voice, data, and distress signaling between vessels, shore stations, and satellites across maritime operational environments. These systems typically operate across VHF (156-174 MHz), MF/HF (2-30 MHz), and satellite L/Ku/Ka-band frequencies to ensure continuous connectivity beyond terrestrial network reach. Satellite communication solutions command the widest margin pools as offshore platforms and commercial shipping fleets prioritize broadband data throughput over legacy narrowband services. Digital technology architectures represent the fastest-expanding segment as analog equipment phases out under IMO-mandated modernization timelines. Integrated systems spanning GMDSS, AIS, and VSAT are capturing preference among naval forces seeking unified command-and-control interfaces.
IMO GMDSS modernization requirements and regional adoption of IEC 61097 standards are reshaping product certification requirements for equipment suppliers targeting Middle East and Africa markets. The UAE's Telecommunications and Digital Government Regulatory Authority and South Africa's ICASA enforce spectrum coordination rules that dictate terminal approval timelines and operational parameters for satellite service providers. National maritime authorities in Saudi Arabia and Egypt are implementing port-state control inspections that verify GMDSS compliance, directly conditioning market access for non-certified systems. Stakeholders must monitor evolving flag-state implementation schedules for next-generation satellite distress alerting as these timelines will determine replacement demand intensity across the region's heterogeneous fleet base.
Market Dynamics
The International Maritime Organization's GMDSS modernization mandate is compressing equipment replacement cycles across Middle East and Africa maritime fleets, forcing simultaneous upgrades to satellite distress terminals, VHF data exchange systems, and integrated bridge electronics.
Growth Catalysts
- Offshore Energy Expansion:Oil and gas platform operators in Saudi Arabia and the UAE are deploying broadband VSAT terminals to support remote drilling operations and crew welfare connectivity.
- IEC 61097 Standardization:Regional adoption of harmonized equipment certification protocols is reducing terminal approval timelines and accelerating supplier market entry.
- Port-State Control Intensification:Egyptian and South African maritime authorities are expanding inspection regimes that verify GMDSS compliance, creating replacement demand for non-certified legacy systems.
Market Restraints
- Satellite Bandwidth Cost Volatility:Ku-band and Ka-band capacity pricing fluctuations constrain operating budget predictability for commercial shipping operators.
- Terminal Supply Concentration:L-band constellation dependency creates vulnerability for fleets traversing Gulf of Aden routes where service provider options remain limited.
- High-Latitude Coverage Gaps:Geostationary satellite architectures fail to sustain reliable links in Moroccan and Namibian fishing zones, forcing costly dual-terminal configurations.
Strategic Opportunities
- Namibian Fisheries Modernization:Industrial trawler fleets operating in Benguela Current zones present untapped demand for low-Earth-orbit connectivity solutions.
- Integrated Bridge Convergence:Unified command-and-control interfaces combining GMDSS, AIS, and VSAT functions are capturing preference among naval procurement programs.
- Leasing Model Penetration:Satellite terminal-as-a-service offerings are rewriting capital allocation for mid-size vessel operators previously excluded from broadband adoption.
Industry Challenges
- Certification Timeline Compression:UAE Telecommunications and Digital Government Regulatory Authority approval processes create bottlenecks for equipment suppliers targeting concurrent IMO deadline compliance.
- Legacy System Integration Complexity:Analog-to-digital bridge electronics migration demands specialized marine electronics technicians scarce across East African port clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Marine Communication Systems Market |
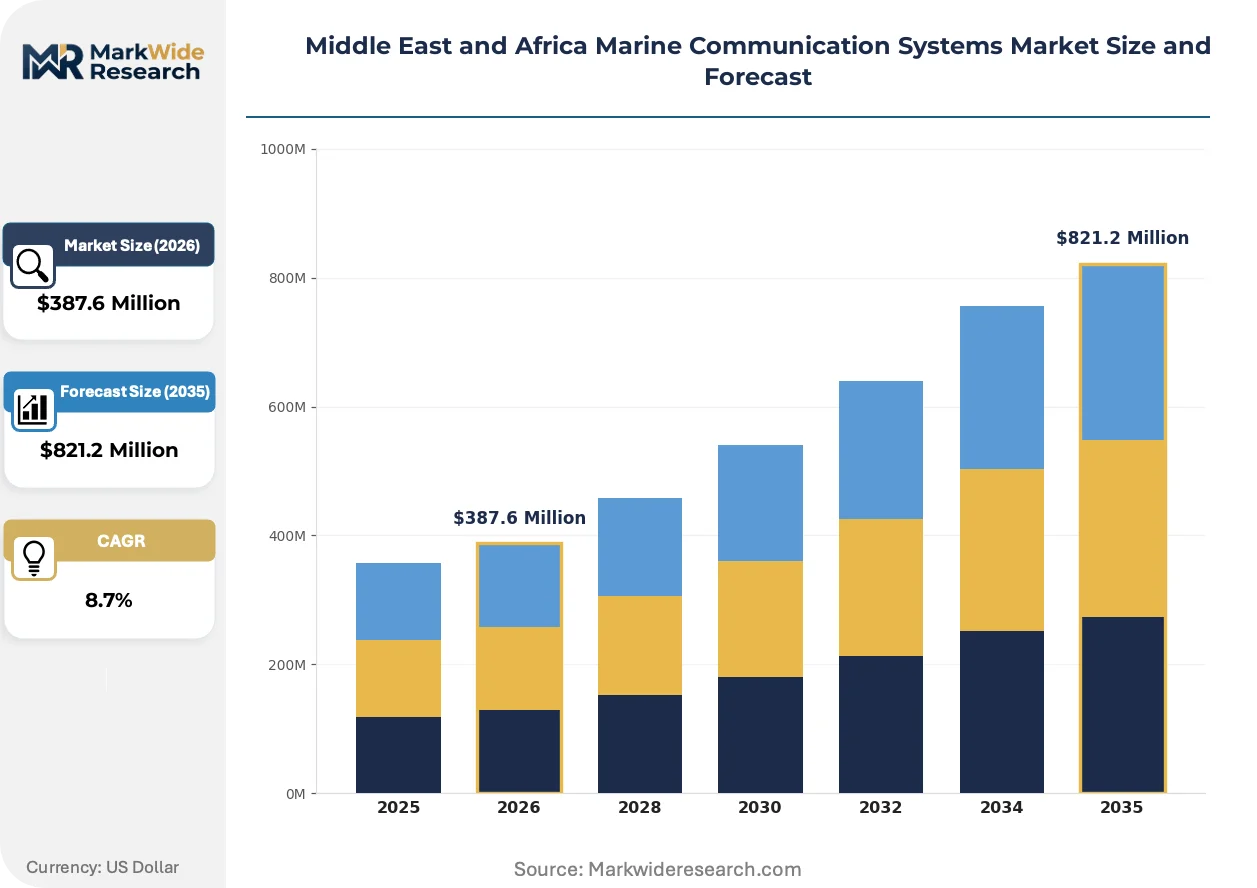
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VHF Radio, Satellite Communication, AIS, GMDSS Technology: Analog, Digital, Satellite, Integrated Systems End User: Commercial Shipping, Fishing Vessels, Naval Forces, Offshore Platforms Installation: Onboard, Shore-Based, Integrated, Retrofits |
| Companies Covered | Inmarsat, Iridium Communications, KVH Industries, Cobham, Thuraya Telecommunications Company, Intellian Technologies, ORBCOMM, Navarino, Speedcast, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Marine Communication Systems Market Shifts & Advancements
Digital technology architectures are displacing analog marine communication equipment across Middle East and Africa fleets, with regulatory deadlines and operational efficiency demands converging to accelerate adoption curves.
Software-defined radio platforms are migrating from narrowband voice-centric configurations to broadband data-enabled architectures. Offshore supply vessel operators and superyacht managers are adopting these flexible systems to consolidate multiple communication functions on single hardware stacks. This migration from purpose-built analog equipment is compressing supplier margins while expanding addressable market volume through reduced per-vessel installation costs.
South Africa's ICASA spectrum coordination rules are tightening operational parameters for satellite service providers, mandating interference mitigation protocols that increase terminal engineering complexity. The industrial consequence is extended product development cycles for equipment targeting Southern African waters. Fishing fleet operators and coastal patrol services are responding by prioritizing pre-certified terminal configurations that bypass lengthy national approval processes.
Service contract unbundling is fragmenting traditional bundled connectivity offerings across Middle East shipping corridors. Major shipping lines traversing Suez Canal routes are separating hardware procurement from bandwidth subscription, forcing terminal manufacturers to compete on equipment performance rather than service lock-in. This pattern is most visible among UAE-flagged container fleets where procurement departments now negotiate satellite capacity independently of terminal supply agreements.
Middle East and Africa Marine Communication Systems Market Segmentation
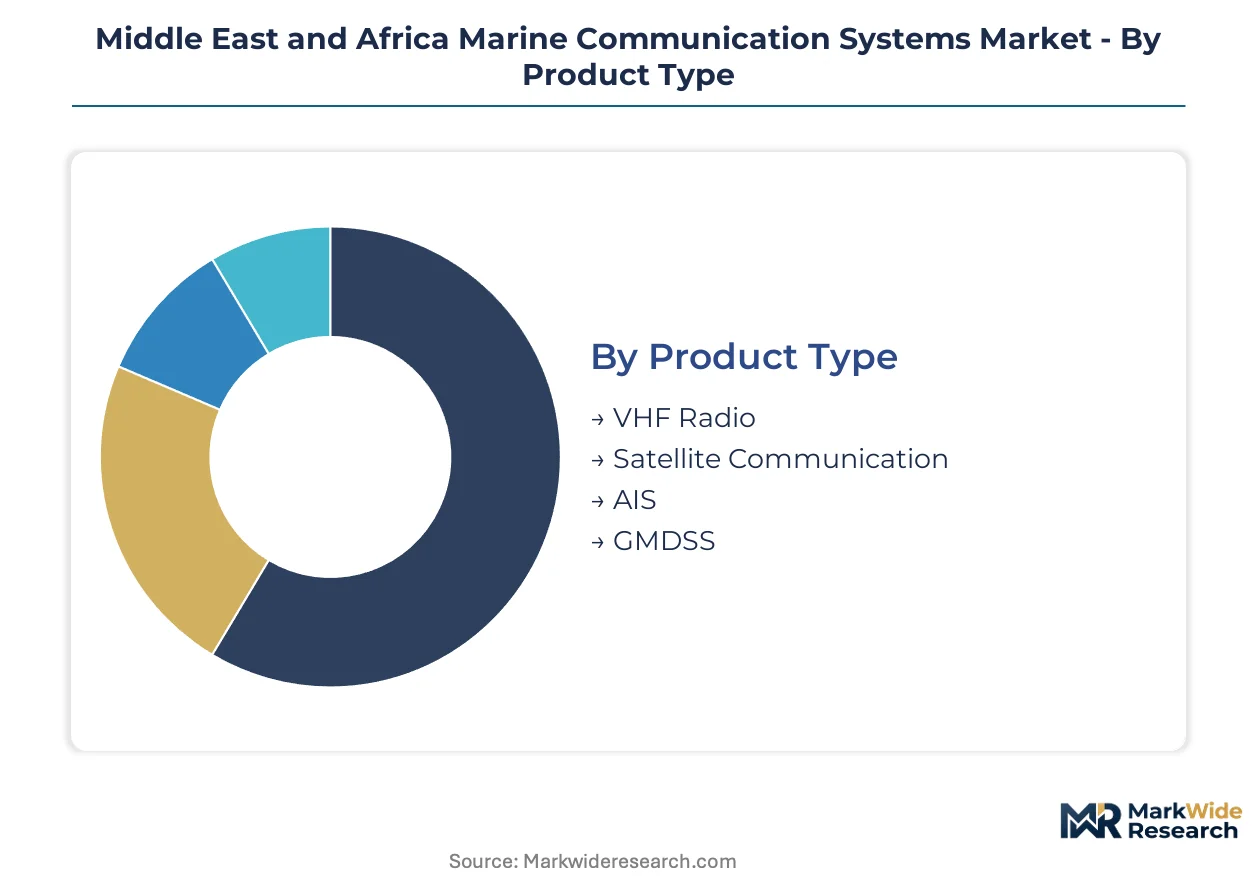
Segmentation across the Middle East and Africa marine communication systems market reveals distinct procurement patterns tied to vessel type, operational environment, and regulatory compliance timelines. Equipment specifications diverge sharply between offshore energy infrastructure and coastal fishing fleets, while technology migration paths vary by fleet modernization budgets.
Product Type:
Use-case spectrum spans from mandatory safety equipment to discretionary broadband connectivity, with commercial shipping operators prioritizing integrated suites and fishing fleets selecting modular point solutions.
- VHF Radio:Coastal band equipment operating across 156-174 MHz channels remains mandatory for port-state control compliance in Egyptian and South African waters. Demand concentrates among fishing vessel operators in Moroccan Atlantic zones where coastal coverage suffices and terminal costs must stay minimal.
- Satellite Communication:L-band and Ku-band terminals deliver broadband data beyond terrestrial reach, with offshore platform operators in Saudi Arabia and the UAE driving procurement for remote drilling support and crew welfare applications. VSAT installations on offshore supply vessels are climbing the fastest as charter contracts increasingly specify connectivity minimums.
- AIS:Automatic Identification System transponders provide collision avoidance and fleet tracking across congested Gulf of Aden shipping corridors.
- GMDSS:Global Maritime Distress and Safety System terminals satisfy IMO carriage requirements with integrated satellite distress alerting and EPIRB functionality.
Established volume favors VHF Radio; emerging adoption favors Satellite Communication.
Technology:
Cost tier stratification separates legacy analog replacement cycles from premium digital and integrated system deployments.
- Analog:Legacy voice-centric architectures face phased obsolescence under IMO GMDSS modernization mandates, with replacement demand concentrated among aging fishing fleets and coastal trading vessels operating from East African ports.
- Digital:Software-defined radio platforms consolidate multiple frequency bands and communication protocols on single hardware stacks. Naval procurement programs in the UAE and Saudi Arabia are expanding fastest for digital architectures that enable encrypted command-and-control interfaces.
- Satellite:Purpose-built terminals for L-band, Ku-band, and Ka-band connectivity serve beyond-line-of-sight requirements.
- Integrated Systems:Unified bridge electronics combining GMDSS, AIS, and VSAT functions reduce equipment footprint and training burden.
Replacement cycles favor Digital; capital constraints sustain Analog in secondary fleets.
End User:
Application intensity varies by operational tempo, with commercial shipping and offshore platforms driving equipment refresh rates while naval programs dictate specification complexity.
- Commercial Shipping:Container fleets and bulk carriers traversing Suez Canal routes require redundant connectivity for voyage optimization and regulatory reporting. UAE-flagged operators are expanding fastest as port-state control inspections intensify GMDSS compliance verification.
- Offshore Platforms:Fixed and floating production facilities in Saudi Arabian and Emirati waters deploy high-throughput VSAT for real-time drilling data transmission and telemedicine connectivity. Procurement cycles tie directly to field development timelines and charterer requirements.
- Fishing Vessels:Industrial trawlers and artisanal fleets operating in Moroccan and Namibian waters select cost-optimized terminals.
- Naval Forces:Coastal patrol and blue-water fleets demand hardened equipment with encrypted waveforms and electronic counter-countermeasures.
Procurement volume centers on Commercial Shipping; specification complexity peaks with Naval Forces.
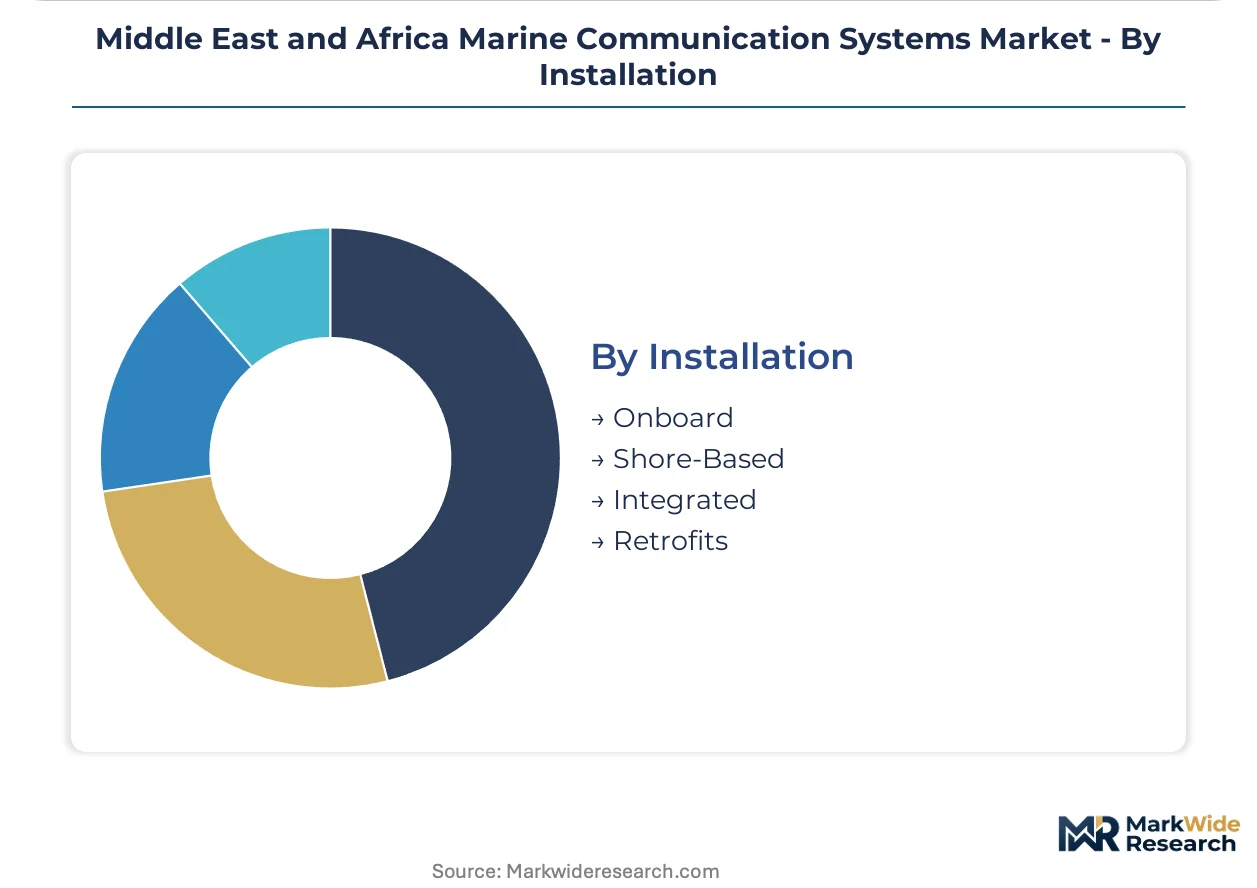
Installation:
Customer type and vessel lifecycle stage determine installation modality, with newbuilds favoring integrated configurations and existing fleets selecting retrofit paths.
- Onboard:Permanent vessel-mounted terminals dominate commercial shipping and offshore platform applications, with antenna placement and cable routing engineering constituting significant project cost. Demand clusters in UAE shipyards where newbuild contracts specify pre-installed VSAT infrastructure.
- Retrofits:Analog-to-digital migration projects on existing vessels require specialized marine electronics technicians and dry-docking coordination. South African and Egyptian port clusters face technician scarcity that extends project timelines.
- Shore-Based:Coastal monitoring stations and port VTS centers deploy fixed installations for fleet oversight.
- Integrated:Bridge console consolidation of multiple communication functions reduces equipment footprint.
Newbuild penetration favors Onboard; fleet modernization sustains Retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabian offshore operators extract pricing premiums unavailable to Moroccan fishing fleet managers, creating a two-tier procurement landscape across the Middle East and Africa marine communication systems market.
Saudi Arabia
Aramco-led offshore platform expansions in the Arabian Gulf drive VSAT terminal procurement for remote drilling operations. The Communications and Information Technology Commission enforces spectrum licensing protocols that delay foreign equipment approvals. Dammam-based shipyards integrate pre-certified GMDSS suites into newbuild offshore supply vessels.
United Arab Emirates
DP World port modernization and coastal security programs sustain equipment refresh cycles across commercial and naval fleets. The Telecommunications and Digital Government Regulatory Authority mandates IEC 61097 certification for all satellite distress terminals. Dubai Maritime City clusters electronics integrators serving superyacht and offshore vessel segments.
South Africa
Industrial trawler fleets in the Benguela Current zone require low-Earth-orbit connectivity solutions beyond geostationary coverage limits. ICASA spectrum coordination rules tighten interference mitigation protocols for satellite service providers. Cape Town port clusters face technician scarcity that extends analog-to-digital retrofit timelines.
Egypt
Suez Canal transit volumes condition redundant connectivity requirements for container fleets traversing the corridor. The National Telecommunications Regulatory Authority aligns terminal approval processes with IMO GMDSS modernization deadlines. Alexandria shipyards concentrate retrofit demand from aging coastal trading vessels.
Morocco
Atlantic fishing fleets operating in high-latitude zones select cost-optimized VHF configurations where coastal coverage suffices. The National Telecommunications Regulatory Agency enforces equipment type-approval requirements for imported marine electronics. Agadir industrial fishing ports anchor artisanal fleet modernization programs.
Middle East and Africa Marine Communication Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying antenna modules, transceivers, and software stacks. The vendor base organizes around three archetypes: L-band constellation operators with service-contract anchoring, VSAT hardware fabricators with hybrid solution portfolios, and regional service integrators with installation and maintenance networks. Competitive moves concentrate on strategic partnerships between satellite operators and terminal manufacturers, plus geographic expansion through local certification acquisitions.
Within the constellation-operator tier, Inmarsat and Iridium Communications occupy positions shaped by orbital architecture differentiation. Thuraya Telecommunications Company anchors regional service provision across Middle Eastern waters. KVH Industries exemplifies the VSAT-hardware archetype through its specialization in maritime-stabilized antenna systems. These three entities represent distinct competitive vectors: Inmarsat through geostationary L-band dominance, Iridium through low-Earth-orbit coverage completeness, and KVH through hybrid connectivity hardware.
| Leading Market Players |
|---|
| Inmarsat |
| Iridium Communications |
| KVH Industries |
| Cobham |
| Thuraya Telecommunications Company |
| Intellian Technologies |
| ORBCOMM |
| Navarino |
| Speedcast |
| Others |
Supply & Pricing Matrix
Ku-band transponder undercapacity in Middle Eastern orbital slots is compressing margins for VSAT service providers while simultaneously elevating pricing leverage for L-band constellation operators serving Gulf of Aden shipping corridors.
Pricing Analysis
Configured-to-order VSAT installations command pricing premiums exceeding standard terminal configurations by margins tied to antenna stabilization specifications and integration complexity with legacy bridge electronics. The dominant pricing structure runs through subscription-based service tiers bundling hardware lease fees with bandwidth commitments, with IMO GMDSS certification grade and vessel size class as primary price differentiation drivers. Cost compression in the fishing vessel segment is intensifying because Moroccan and Namibian fleet operators prioritize minimal viable connectivity over performance specifications. Commercial shipping lines traversing Suez Canal routes exhibit lowest price sensitivity due to charterer-mandated connectivity minimums, while artisanal fishing cooperatives in Atlantic Morocco anchor the economy tier.
Supply Chain Analysis
Contract manufacturing for stabilized antenna systems concentrates among specialized electronics manufacturing services in South Korea, Taiwan, and Germany with marine-grade environmental testing capabilities. Raw material dependencies center on gallium nitride semiconductors for RF power amplification, carbon fiber composites for antenna reflectors, and precision servo motors for stabilization platforms. Single-source vulnerability runs through L-band RF front-end modules sourced from limited qualified suppliers. Distribution runs through regional marine electronics integrators clustered in Dubai Maritime City and Dammam shipyard zones, with direct OEM relationships dominating naval procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among UAE-flagged container fleet operators consolidating procurement across vessel classes, compressing supplier margins while elevating service-level requirements.
For Market Incumbents: Build switching-cost moats through embedded software platforms that integrate GMDSS, AIS, and VSAT functions into unified bridge architectures resistant to modular replacement. Defensive priorities center on securing IEC 61097 pre-certification for next-generation satellite distress terminals ahead of IMO deadline convergence, and anchoring long-term service contracts with Saudi Aramco offshore platform operators through dedicated bandwidth reservations. Low-Earth-orbit entrants threaten geostationary incumbents in high-latitude fishing zones off Morocco and Namibia. For New Entrants and Emerging Players: Build out terminal-as-a-service offerings targeting mid-size vessel operators in Egyptian and South African coastal trades previously excluded from broadband adoption by capital constraints. White-space opportunities concentrate in Namibian industrial trawler fleets requiring low-Earth-orbit connectivity beyond geostationary coverage limits, and in retrofit digital migration projects for aging East African coastal trading vessels. A certification-fast-track go-to-market angle leveraging pre-approved terminal configurations bypasses UAE Telecommunications and Digital Government Regulatory Authority approval bottlenecks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among satellite service providers with L-band spectrum rights and long-term charter contracts with major shipping lines. Long-term viability over the projection horizon favors asset-light platform integrators over hardware-dependent fabricators facing margin compression from software-defined radio commoditization. Acquisition targets should demonstrate installed base density in Saudi Arabian and Emirati waters with upgrade pathway visibility. The signal to watch is port-state control inspection intensity in Egyptian and South African waters as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | IEC 61097 pre-certification accelerates UAE and Saudi market entry ahead of IMO deadlines. |
| Low-Earth-Orbit Partnership | Iridium constellation integration addresses high-latitude coverage gaps in Moroccan and Namibian fishing zones. |
| Terminal-as-a-Service Launch | Leasing models rewrite capital allocation for Egyptian and South African mid-size vessel operators. |
| Integrated Bridge Platform Development | Unified GMDSS-AIS-VSAT interfaces capture preference among UAE and Saudi naval procurement programs. |
| Regional Service Network Expansion | Dubai Maritime City and Dammam clusters anchor installation and maintenance density in high-volume markets. |
Research Methodology
Cross-validation between primary fieldwork with satellite service provider executives and secondary analysis of IMO GMDSS implementation schedules anchors the qualitative findings. Stakeholder interviews encompassed fleet managers at Saudi Aramco offshore operations, procurement directors at UAE-flagged container lines, marine electronics integrators in Dubai Maritime City, and regulatory affairs specialists at national maritime authorities. Secondary sources included IEC certification databases, ITU satellite filings, customs import records for marine electronics, and port-state control inspection statistics. Bottom-up vessel fleet segmentation triangulates against top-down market sizing from service provider revenue disclosures.
Calibration against historical replacement cycle patterns and regulatory deadline enforcement intensity shaped the analytical framework across the analysis window. Segmentation dimensions encompassed product type, technology architecture, end-user category, and installation modality, with vessel age distribution and flag-state compliance history as industry-specific forecast inputs. CAGRs derive from equipment unit economics and service contract pricing trajectories rather than aggregate demand extrapolation.
Sensitivities concentrate around IMO GMDSS modernization deadline extensions, Ku-band capacity pricing volatility, and technician availability constraints in East African port clusters. Forecasts reflect assumptions regarding regulatory enforcement consistency and satellite constellation reliability. Quarterly review of port-state control inspection statistics and national type-approval processing timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Communication Standard Logic IC Market