
 Automotive Diode Market | 2026-2036
Automotive Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Diode Market Analytics
The EU Green Deal is decoupling automotive diode procurement from legacy silicon-only specifications. Infineon Technologies leverages its SiC portfolio to capture premium power management sockets. Vishay Intertechnology anchors rectifier supply across European and Asian OEM programs. ROHM Semiconductors specializes in SiC Schottky devices for traction inverter modules.
An automotive diode is a two-terminal semiconductor device that permits current flow in one direction while blocking reverse voltage, typically rated for 600V to 1.2kV in EV applications and manufactured through epitaxial growth on silicon or wide-bandgap substrates to protect circuits and manage power conversion. Silicon carbide technology leads the technology segment due to thermal efficiency advantages in 800V architectures. Rectifier products dominate the product type category by volume, while transient voltage suppressor demand accelerates fastest alongside battery management system complexity. OEMs command the largest end user value pool through direct qualification programs.
The EPA tailpipe rules and NHTSA CAFE standards tighten thermal and efficiency requirements for power electronics. ECHA REACH compliance constrains material selection in European-sourced devices. China's MIIT dual carbon goals mandate domestic SiC diode adoption targets. Stakeholders must monitor qualification timelines for next-generation wide-bandgap devices as OEMs consolidate supplier bases.
Market Dynamics
Powertrain electrification is compressing diode qualification cycles while fragmenting supplier tiers between legacy silicon rectifier incumbents and wide-bandgap specialists bidding for 800V traction inverter sockets.
Growth Catalysts
- EU Green Deal vehicle emission mandates:OEMs must upgrade power electronics to meet fleet CO2 targets, forcing diode replacement in onboard chargers and DC-DC converters.
- 800V battery architectures:Silicon carbide Schottky diodes enable faster charging and reduced thermal losses in premium EV platforms.
- China's MIIT dual carbon goals:Domestic SiC diode adoption targets accelerate local foundry capacity expansion and OEM sourcing shifts.
Market Restraints
- Substrate supply concentration:High-purity SiC wafer production clusters in limited geographies, creating input bottlenecks for diode manufacturers.
- ECHA REACH material constraints:Restricted substances in European-sourced devices complicate bill-of-materials compliance and supplier qualification.
- Silicon superjunction MOSFET substitution:Cost-sensitive inverter designs in economy EV segments bypass SiC diodes for mature silicon alternatives.
Strategic Opportunities
- India PLI scheme for auto component manufacturing:Incentives attract diode packaging and testing investments serving domestic EV production ramps.
- Bidirectional onboard chargers:Vehicle-to-grid applications create demand for higher-voltage, higher-current diode specifications in residential energy storage integration.
- Japan METI carbon neutrality roadmap:Solid-state battery development programs specify wide-bandgap power management components for next-generation platforms.
Industry Challenges
- AEC-Q101 qualification timelines:Extended stress-testing protocols for automotive-grade diodes delay new supplier entry and product ramp schedules.
- Wide-bandgap device integration complexity:Legacy silicon-based gate driver architectures require redesign to optimize SiC diode switching performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Diode Market |
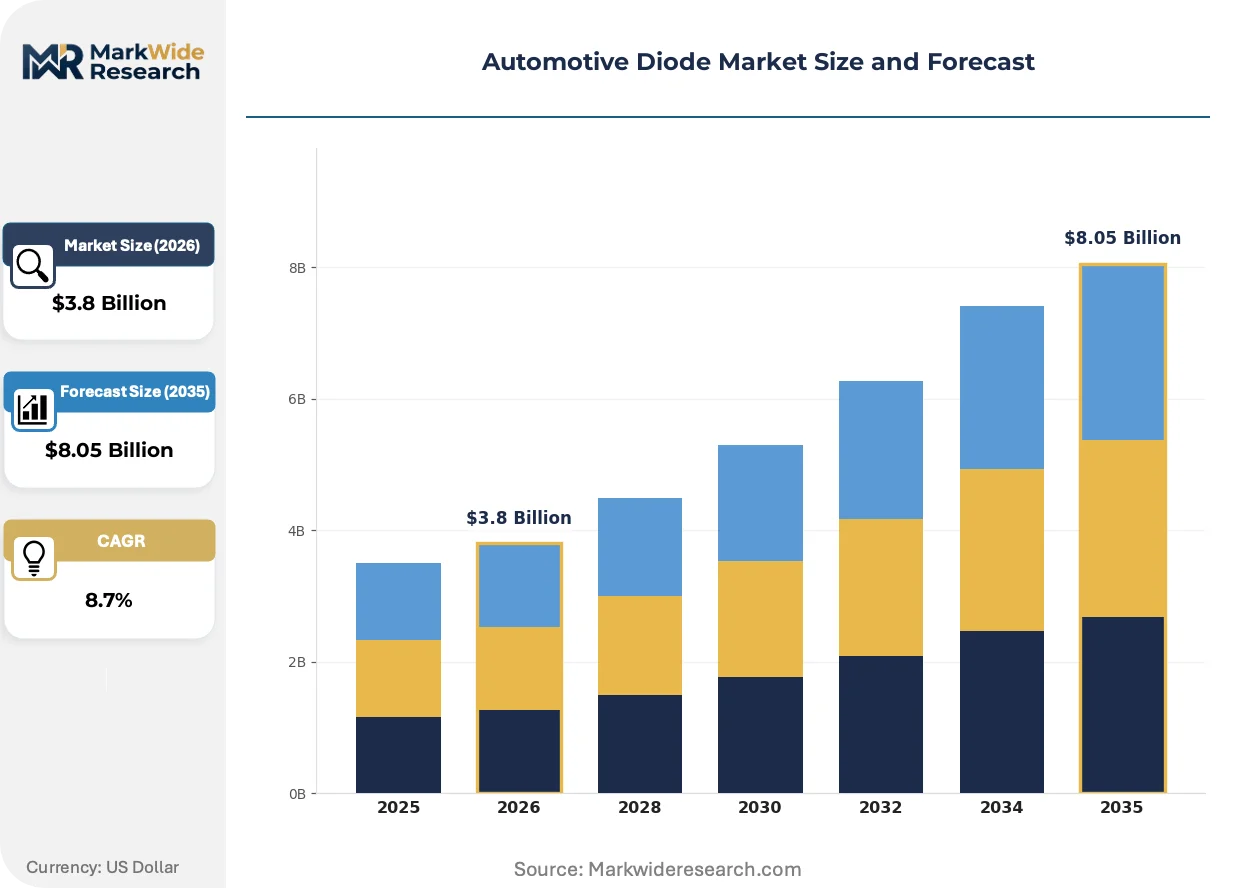
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schottky, Zener, Rectifier, Transient Voltage Suppressor Application: Power Management, LED Drivers, Signal Conditioning, Battery Management End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Component Manufacturers Technology: Silicon, Silicon Carbide, Gallium Nitride, Hybrid |
| Companies Covered | Infineon Technologies, Vishay Intertechnology, Diodes Incorporated, STMicroelectronics, ON Semiconductor, ROHM Semiconductors, Nexperia, Texas Instruments, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Diode Market Evolving Landscape
Module-level integration is collapsing discrete component boundaries, with diode functions merging into intelligent power stages that combine sensing, protection, and thermal management in single packages.
Silicon carbide trench Schottky technology is unifying reverse recovery performance with forward voltage drop specifications previously traded off in planar designs. Tier 1 inverter suppliers are qualifying these devices for 800V traction modules ahead of 2025 platform launches. The convergence is compressing the viable supply base to foundries with epitaxial growth and trench etch capabilities.
EPA tailpipe rules and NHTSA CAFE standards are tightening thermal efficiency mandates for power conversion subsystems. Component suppliers must demonstrate operational lifetimes exceeding 15 years under elevated junction temperatures. US-based OEMs are accelerating qualification of wide-bandgap diodes in integrated power modules to meet combined fleet efficiency targets.
Consolidated supplier programs are displacing multi-source diode procurement strategies as OEMs reduce qualification overhead. Direct partnerships with SiC substrate manufacturers are replacing distributor-mediated component sourcing for high-volume EV platforms. This concentration is most visible in China, where BYD and CATL-affiliated vehicle programs specify captive diode supply chains.
Automotive Diode Market Segmentation
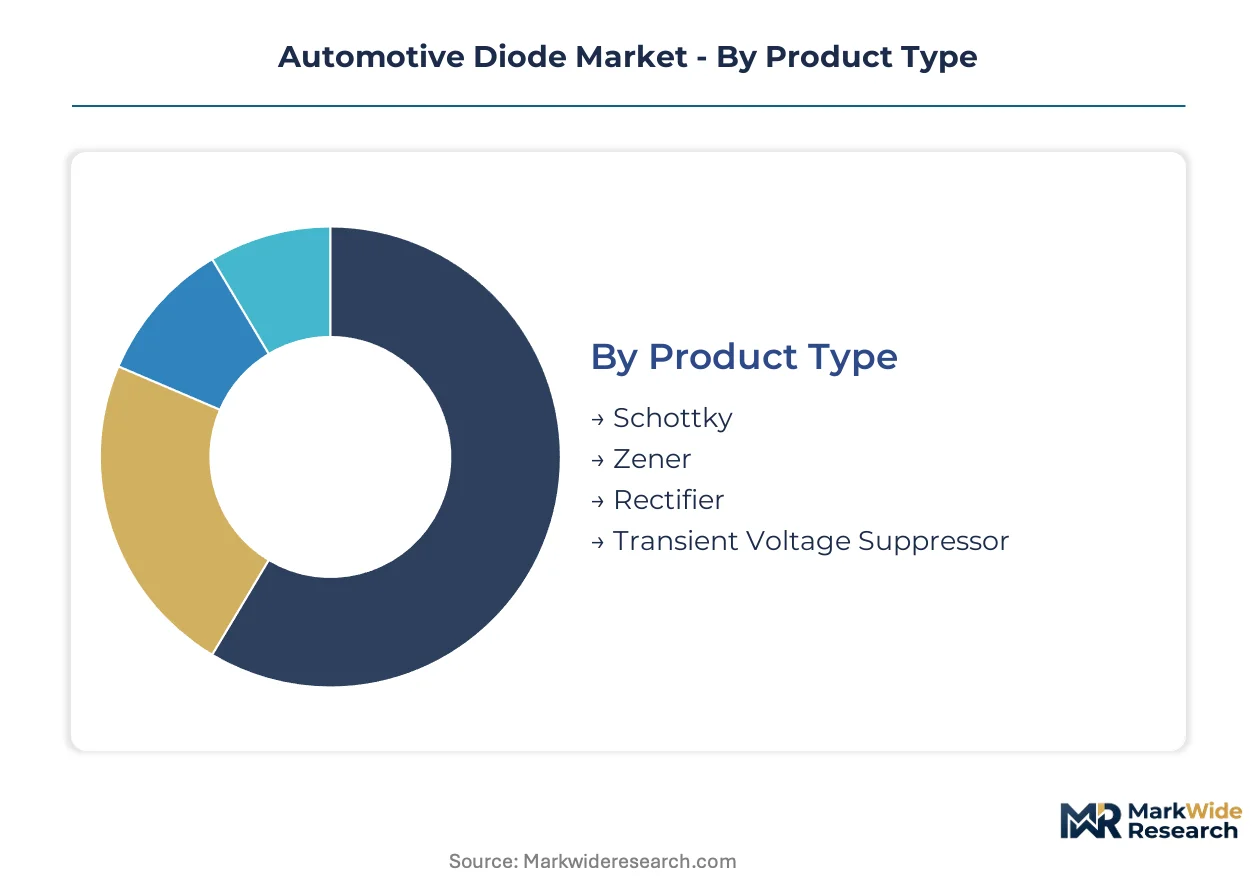
Automotive diode procurement splits across four intersecting axes: power conversion specification, vehicle system integration point, supply chain position, and semiconductor substrate material. Each axis carries distinct margin profiles and qualification barriers that reshape vendor competitive positioning.
Product Type:
Specification requirements diverge sharply between high-frequency switching applications and voltage protection functions, with thermal tolerance and reverse recovery speed driving socket selection.
- Rectifier:Full-bridge and half-bridge configurations dominate onboard charger AC-DC stages and alternator output stages. OEMs in Germany and Japan specify these for 400V and 800V traction inverter input rectification where efficiency thresholds exceed 98.5%.
- Schottky:Metal-semiconductor junction architecture delivers sub-50ns switching speeds for DC-DC converter freewheeling applications. Demand clusters in China's EV manufacturing corridors where local foundries supply BYD and CATL-affiliated vehicle programs with cost-optimized surface-mount packages.
- Zener:Avalanche breakdown regulation protects sensitive gate driver circuits against voltage transients in battery management systems.
- Transient Voltage Suppressor:Bidirectional clamping devices safeguard CAN bus and Ethernet backbone communications from load dump events.
Rectifier leads on scale; Transient Voltage Suppressor leads on momentum.
Application:
System-level integration depth determines diode specification stringency, with powertrain electrification elevating thermal and reliability requirements above infotainment or body electronics.
- Power Management:DC-DC converters and onboard chargers deploy silicon carbide Schottky diodes to minimize switching losses in 800V architectures. German OEM qualification programs specify these for premium EV platforms targeting 350kW DC fast charging capability.
- Battery Management:Cell balancing and isolation monitoring circuits require high-voltage blocking diodes with AEC-Q101 Grade 0 temperature ratings. Japanese solid-state battery development programs under METI carbon neutrality roadmaps specify wide-bandgap devices for next-generation pack architectures.
- LED Drivers:Automotive lighting modules use rectifier diodes for AC input stages and protection diodes against reverse polarity connection.
- Signal Conditioning:Sensor interface circuits employ small-signal diodes for clamping and level shifting in powertrain and chassis control modules.
Power Management commands the value pool; Battery Management shows the steepest expansion trajectory.
End User:
Procurement authority concentrates at the vehicle platform level, with direct OEM qualification displacing tiered component sourcing for critical power electronics.
- OEMs:Volkswagen, Toyota, and Tesla operate captive diode qualification programs specifying substrate source, epitaxial growth parameters, and package thermal impedance. These programs bypass traditional tier-1 module suppliers for traction inverter and onboard charger sockets.
- Vehicle Assemblers:Contract manufacturers in China and Mexico integrate pre-qualified diode modules into final powertrain assembly, with limited specification influence beyond mechanical integration constraints.
- Aftermarket Suppliers:Independent distributors serve repair networks with replacement rectifiers and protection diodes for legacy internal combustion vehicle electrical systems.
- Component Manufacturers:Tier-2 packaging houses in Malaysia and Thailand perform die attach and wire bonding for fabless diode designers serving regional OEM programs.
OEMs lead on scale; Component Manufacturers lead on momentum.
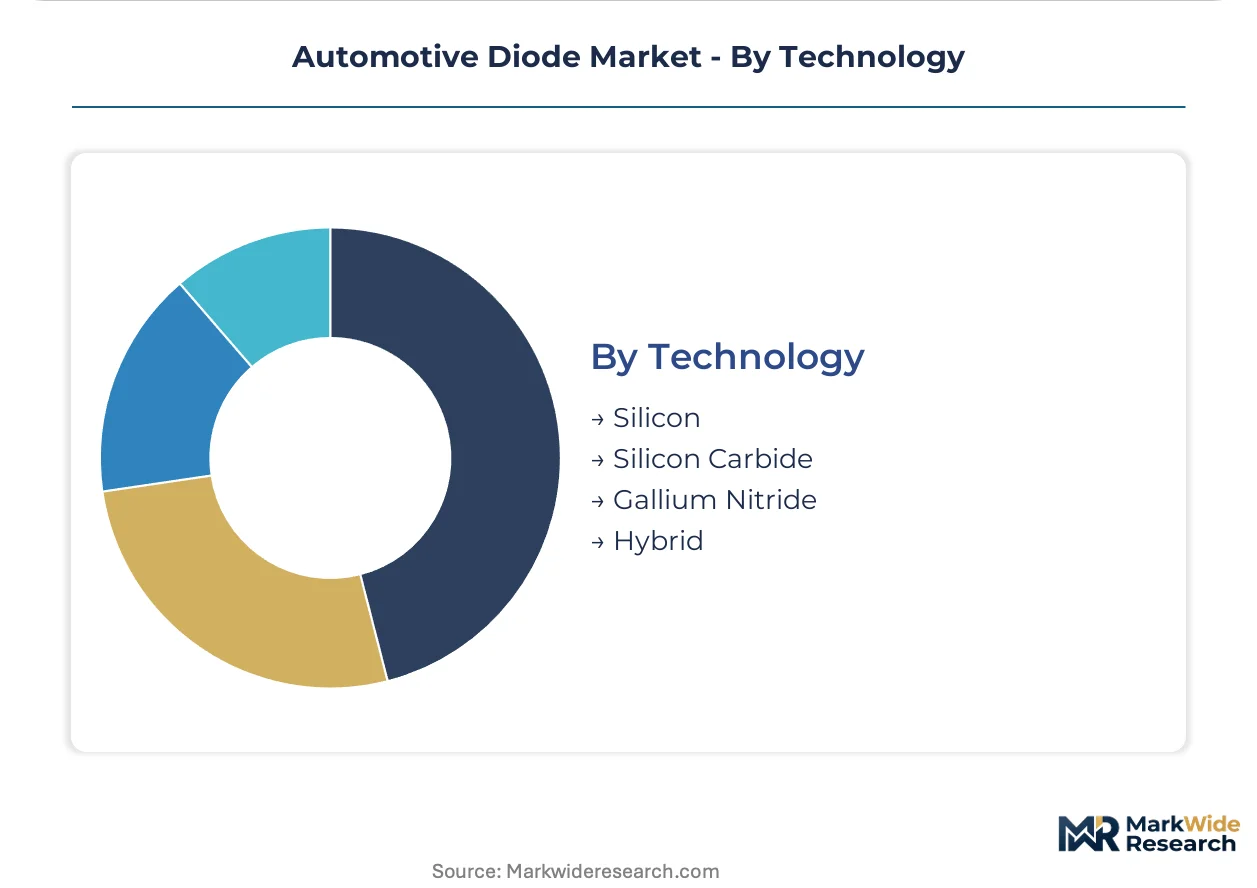
Technology:
Substrate material selection determines thermal efficiency ceiling and switching frequency capability, with wide-bandgap alternatives displacing silicon in high-voltage EV applications despite cost premiums.
- Silicon Carbide:3.26 eV bandgap enables 600V-1.7kV blocking voltage with near-zero reverse recovery charge. Infineon and ROHM supply trench Schottky variants to European and Japanese OEMs for 800V traction inverters, with China's MIIT dual carbon goals mandating domestic foundry capacity expansion.
- Silicon:Mature epitaxial growth and ion implantation processes support cost-sensitive applications in 400V EV platforms and legacy combustion vehicle alternators. Superjunction MOSFET substitution threatens rectifier sockets in economy inverter designs.
- Gallium Nitride:HEMT structures enable megahertz switching frequencies for compact DC-DC converters in space-constrained hybrid vehicle architectures.
- Hybrid:Multi-die packages combine silicon control ICs with SiC or GaN power stages for optimized cost-performance in mid-voltage applications.
Silicon leads on scale; Silicon Carbide leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent clusters in Germany's automotive corridor and China's Yangtze River Delta anchor diode design and manufacturing capabilities. These workforce concentrations shape procurement patterns and qualification timelines across the industry.
China
EV manufacturing scale and battery supply chain integration drive diode procurement volume. MIIT dual carbon goals mandate domestic SiC diode adoption targets for 2025-2030. Shenzhen and Shanghai house foundry expansions serving BYD and CATL-affiliated vehicle programs with captive supply chains.
Germany
Premium OEM electrification programs specify high-efficiency rectifiers for 800V traction inverters. EU Green Deal vehicle emission mandates force component upgrades in onboard chargers and DC-DC converters. Bavaria's semiconductor corridor hosts epitaxial growth facilities supplying Volkswagen and BMW qualification programs.
United States
EPA tailpipe rules and NHTSA CAFE standards tighten thermal efficiency requirements for power electronics. Detroit-based OEMs accelerate wide-bandgap diode qualification in integrated power modules. Michigan and Texas host packaging operations for AEC-Q101 Grade 0 automotive-grade devices.
Japan
Solid-state battery development programs under METI carbon neutrality roadmaps specify wide-bandgap power management components. Toyota and Honda operate captive diode qualification programs for next-generation traction inverter modules. Kyushu and Nagoya regions concentrate SiC Schottky device manufacturing for hybrid and EV platforms.
South Korea
Hyundai-Kia electrification targets drive demand for high-voltage blocking diodes in 800V architectures. Domestic battery cell production integrates vertically with power electronics procurement. Seoul Capital Area and Busan-Ulsan corridor host testing facilities for AEC-Q101 automotive-grade qualification.
Automotive Diode Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across diverging technology roadmaps. Integrated device manufacturers with captive epitaxial growth capabilities capture premium traction inverter sockets, while fabless specialists source substrates through limited-supplier contracts. Three archetypes dominate: silicon carbide substrate-integrated foundries, silicon rectifier incumbents with legacy automotive qualification, and wide-bandgap specialists bidding for 800V platform design wins. Competitive moves concentrate on strategic partnerships with OEM qualification programs and backward integration into SiC wafer supply.
Among European-anchored semiconductor groups, Infineon Technologies and STMicroelectronics occupy positions within the integrated-foundry archetype, leveraging substrate access for premium power management sockets. Vishay Intertechnology exemplifies the silicon rectifier incumbent tier, anchoring supply across established OEM programs with mature qualification portfolios. ROHM Semiconductors sits within the wide-bandgap specialist category, representing Japanese-focused SiC device development for next-generation traction modules.
| Leading Market Players |
|---|
| Infineon Technologies |
| Vishay Intertechnology |
| Diodes Incorporated |
| STMicroelectronics |
| ON Semiconductor |
| ROHM Semiconductors |
| Nexperia |
| Texas Instruments |
| NXP Semiconductors |
| Others |
Value Network & Pricing Analysis
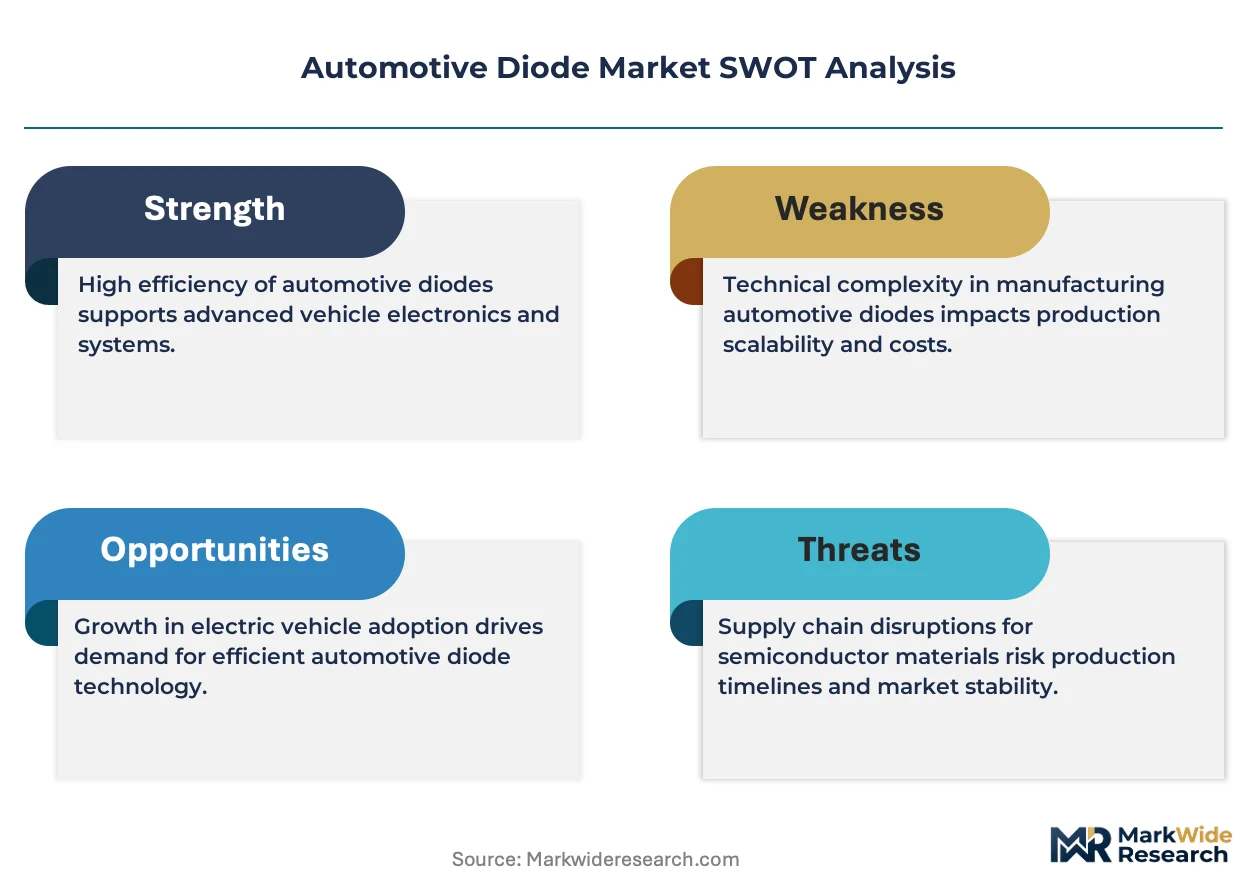
High-purity SiC wafer spot prices cascade through three distinct pricing tiers for automotive diodes, with substrate cost concentration in limited geographies amplifying margin pressure on fabless designers while integrated foundries capture premium sockets in 800V traction inverter programs.
Pricing Analysis
Discrete component sales dominate transactional pricing, while module-level integration commands project-based premiums tied to AEC-Q101 Grade 0 certification and thermal performance guarantees. Price differentiation rests on epitaxial growth quality and trench etch capability, with OEM direct qualification programs showing lowest price sensitivity and aftermarket distributors facing severe cost compression from silicon superjunction alternatives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for traction inverter and onboard charger sockets, bypassing traditional tier-1 module suppliers. Substrate supply concentrates in Japan, Germany, and the United States, with high-purity SiC boules and epitaxial wafers feeding foundry operations. Distribution runs through captive supply chains in China and consolidated qualification programs in Europe, with tariff exposure on wide-bandgap materials creating structural vulnerability for non-integrated diode manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive diode procurement is a geographic-arbitrage play between China's MIIT-mandated domestic SiC adoption targets and Europe's ECHA REACH compliance constraints, with the former accelerating foundry capacity expansion and the latter elevating qualification barriers for imported devices.
For Market Incumbents: Acquire SiC substrate manufacturing assets to secure input supply against wafer production bottlenecks. Expand epitaxial growth capacity in Bavaria and Kyushu to serve Volkswagen and Toyota qualification programs directly. Lock in long-term offtake agreements with high-purity boule suppliers before China's domestic capacity ramps tighten global availability. For New Entrants and Emerging Players: Digital distributor partnerships offer low-friction entry into aftermarket replacement rectifiers for legacy combustion vehicle fleets. Target India's PLI-subsidized auto component manufacturing corridors for packaging and testing investments serving domestic EV production. Pursue fabless design specialization in transient voltage suppressors for battery management system complexity gaps. For Investors and Strategic Acquirers: Asymmetric upside sits with wide-bandgap specialists possessing trench Schottky device portfolios and active OEM qualification pipelines. Five-to-ten year viability hinges on securing design wins in solid-state battery power management architectures. Monitor Japan METI carbon neutrality roadmap implementation as the inflection signal for next-generation platform component specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive wafer sourcing insulates margins against high-purity boule bottlenecks in Japan and Germany. |
| AEC-Q101 Grade 0 Certification Investment | Automotive-grade qualification opens direct OEM procurement for 800V traction inverter sockets. |
| India PLI Manufacturing Footprint Expansion | Domestic packaging capacity captures EV production ramps serving BYD and CATL-affiliated programs. |
| Trench Schottky Technology Licensing | ROHM and Infineon patent positions enable royalty streams from next-generation rectifier designs. |
| Bidirectional Onboard Charger Partnership | Vehicle-to-grid diode specifications integrate residential energy storage with OEM platform roadmaps. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, tier-1 supplier procurement data, and semiconductor foundry capacity announcements — were reconciled through bottom-up and top-down triangulation. Primary interviews with automotive power electronics engineers, SiC substrate procurement leads, and AEC-Q101 testing facility managers were validated against secondary sources including EPA tailpipe rule filings, EU Green Deal implementation documents, and MIIT dual carbon goal policy releases.
Data-stream reconciliation across vehicle production forecasts, battery architecture adoption curves, and wide-bandgap device penetration rates shaped the analytical framework. Segmentation dimensions modeled include product type, application system, semiconductor substrate material, and regional OEM qualification cluster. CAGRs were derived from volume-weighted average growth trajectories, with SiC diode adoption in 800V architectures and rectifier substitution dynamics serving as key forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide trench Schottky designs would alter the outlook if superjunction MOSFET cost-performance improves faster than projected. Forecasts reflect assumptions about ECHA REACH material constraint evolution and China MIIT domestic sourcing mandate implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Electronic Load Market