
 China Optoelectronics Market | 2026-2036
China Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
China Optoelectronics Market Insights
China's dual carbon goals under MEE oversight is hardening efficiency mandates for display and illumination manufacturers. BOE Technology Group Co., Ltd. leverages vertical integration across TFT-LCD and AMOLED panels to dominate domestic display supply. Sanan Optoelectronics Co., Ltd. anchors gallium nitride epitaxy capacity for LED and RF applications. Sunny Optical Technology Group Co., Ltd. specializes in optical imaging modules for automotive and mobile end users.
Optoelectronics encompasses devices that source, detect, and control light through semiconductors, typically operating at wavelengths from ultraviolet through infrared with critical parameters including quantum efficiency, spectral linewidth, and thermal stability; these components enable signal transmission, energy conversion, and optical sensing across industrial and consumer systems. LED product lines retain mature volume positions in general illumination and backlighting, while laser diodes capture expanding margin pools from LiDAR and optical communications deployment. Silicon photonics technology is displacing legacy interconnect architectures in telecommunications as data center operators demand higher bandwidth density at lower energy per bit.
MIIT enforces GB standards for optoelectronic device performance and electromagnetic compatibility, while SAMR administers market access certification that conditions product registration for domestic sale. NMPA regulates medical-grade optoelectronic equipment under device classification rules that constrain design cycles for health care applications. Stakeholders must monitor how China's evolving export control regime for compound semiconductor substrates reshapes supply security decisions for foreign-owned fabs operating within the country.
Market Dynamics
China's dual carbon goals under MEE oversight are hardening efficiency mandates across display and illumination manufacturing, forcing substrate transitions from silicon to gallium nitride and silicon carbide while concentrating procurement in Guangdong Province clusters.
Growth Catalysts
- Automotive LiDAR deployment:Domestic OEM supply chains are absorbing advanced driver-assistance systems at volume, pulling laser diode and optical sensor demand through tiered component contracts.
- MEE carbon efficiency mandates:Factory energy intensity targets are accelerating LED retrofit cycles in industrial lighting and accelerating gallium nitride epitaxy investments.
- Shenzhen-Dongguan cluster integration:Proximity of epitaxy, packaging, and module assembly operations is compressing logistics costs and qualification timelines for export-bound production.
Market Restraints
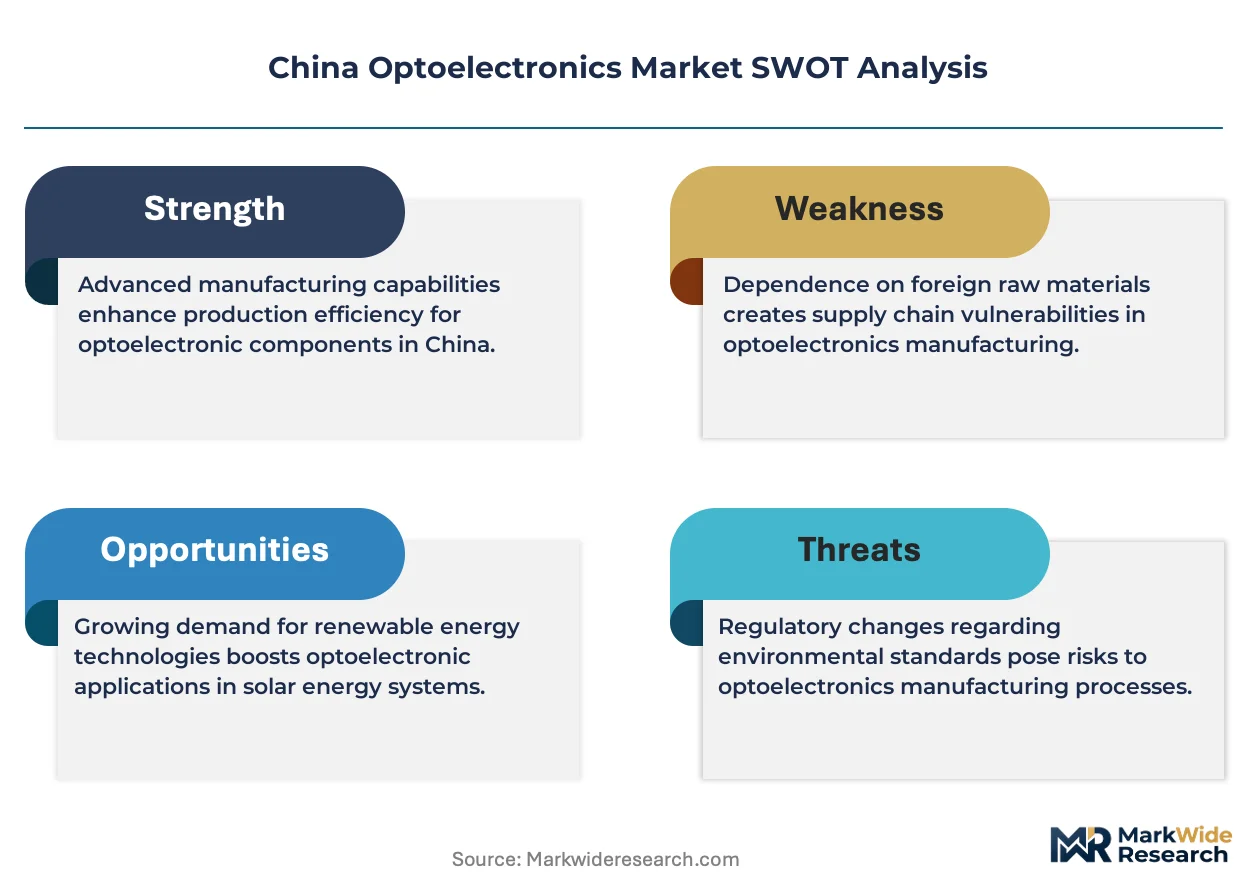
- Compound semiconductor substrate concentration:Domestic supply security for gallium nitride and silicon carbide wafers remains constrained by export control uncertainty and foreign-owned fab dependencies.
- GB standards compliance friction:MIIT electromagnetic compatibility testing and SAMR market access certification extend product registration timelines for new entrants.
- Silicon photonics substitution threat:Data center interconnect architectures are migrating toward co-packaged optical solutions that bypass discrete optoelectronic component layers.
Strategic Opportunities
- Central China manufacturing expansion:Hubei and Sichuan provinces offer land and energy cost advantages for fabs seeking to diversify beyond coastal concentration.
- Medical-grade optoelectronics:NMPA device classification rules create captive demand for certified imaging and diagnostic light sources in domestic healthcare procurement.
- Silicon photonics convergence:Integration of CMOS fabrication with optical functionality is opening foundry service models for telecommunications and sensing applications.
Industry Challenges
- Compound semiconductor process engineering talent:Gallium nitride epitaxy and silicon carbide crystal growth expertise remains concentrated among limited specialist pools.
- NMPA certification cycle duration:Medical-grade optoelectronic equipment faces extended design freeze periods that compress competitive response windows.
- Legacy interconnect integration:Data center operators face forklift upgrade costs when retrofitting silicon photonics into existing copper-based rack architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Optoelectronics Market |
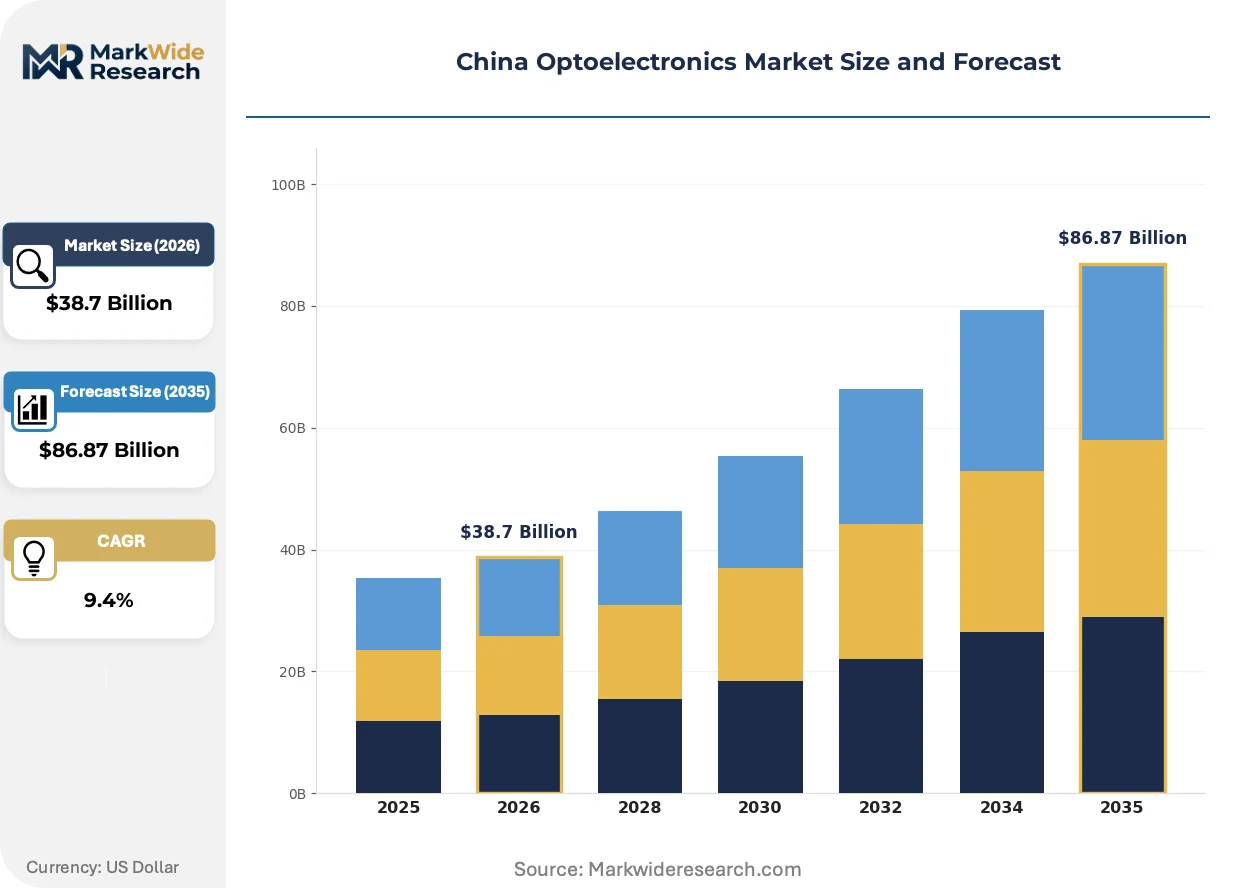
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diodes, Photo Detectors, Photovoltaics Technology: Silicon Photonics, Integrated Optics, Organic Optoelectronics, Quantum Dots Application: Telecommunications, Displays, Lighting, Sensing End User: Consumer Electronics, Automotive, Industrial, Health Care |
| Companies Covered | BOE Technology Group Co., Ltd., Shenzhen China Star Optoelectronics Technology Co., Ltd., Sanan Optoelectronics Co., Ltd., HC Semitek Corporation, Leyard Optoelectronic Co., Ltd., Nationstar Optoelectronics Co., Ltd., Sunny Optical Technology Group Co., Ltd., OFILM Group Co., Ltd., Focuslight Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Optoelectronics Market Trends and Innovations
Technology migration, regulatory tightening, and procurement consolidation are restructuring competitive position across China's optoelectronics value chain.
Gallium nitride power electronics is integrating into automotive traction inverters and on-board chargers, enabling higher switching frequencies and thermal efficiency than silicon alternatives. Domestic EV manufacturers are qualifying these devices at accelerated pace. The technology is integrating vertically from substrate through module assembly within Guangdong-based supply chains.
MEE enforcement of dual carbon targets is tightening factory emissions audits and energy consumption benchmarks for display panel manufacturing. BOE and other domestic panel producers are retrofitting production lines with LED-based process lighting and regenerative thermal oxidizers. Guangdong and Jiangsu provinces face the most immediate compliance deadlines due to concentrated manufacturing load.
Automotive OEMs are consolidating optical component suppliers into single-source or dual-source frameworks for LiDAR and camera module procurement. Tier-1 integrators are absorbing more design responsibility and squeezing component margins. This concentration is most pronounced among domestic EV brands headquartered in Shenzhen and Shanghai.
China Optoelectronics Market Segmentation
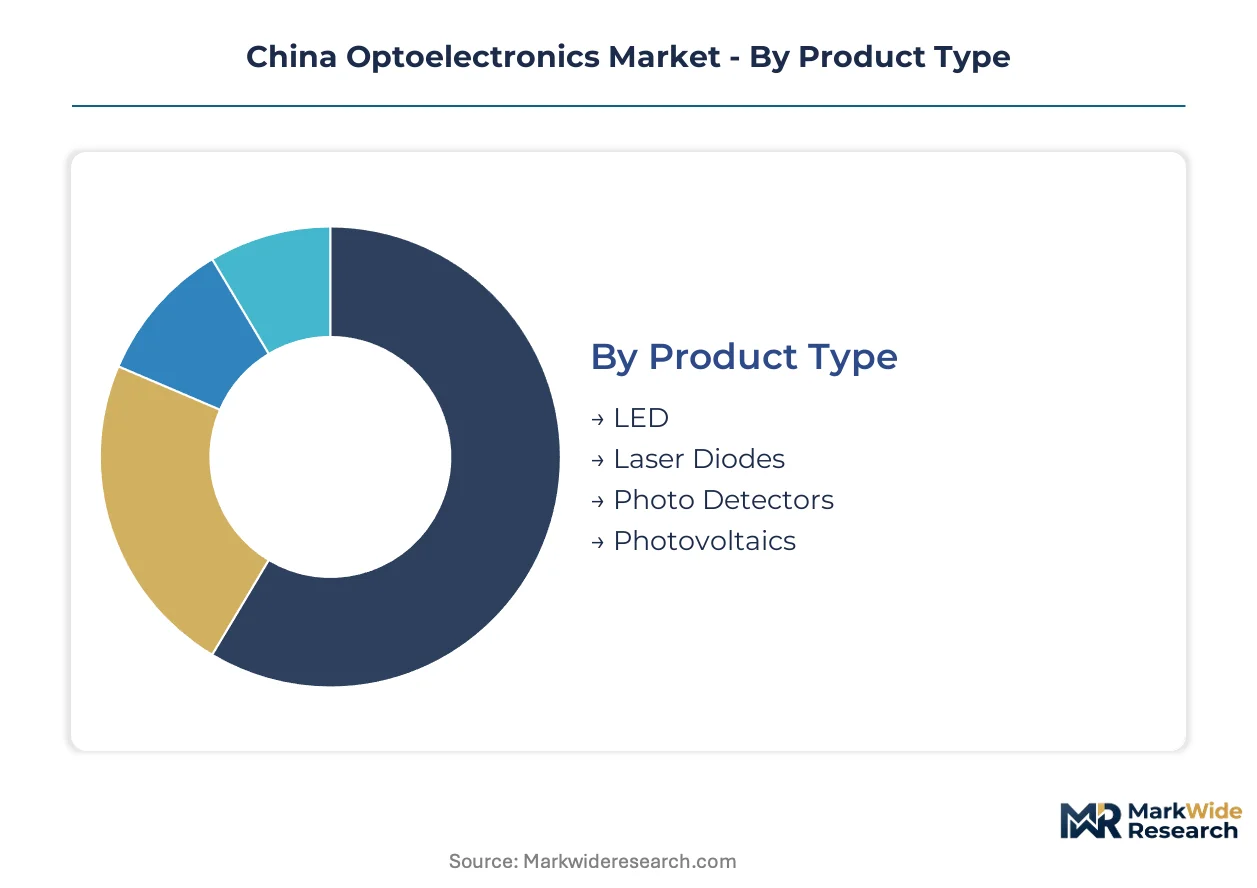
China's optoelectronics market segments reflect divergent maturity curves and margin profiles across product generations. Technology transitions in compound semiconductors and packaging architectures are fragmenting procurement patterns by end-use application.
Product Type:
Standardized commodity formats dominate high-volume applications while specialized configurations command premium positioning in precision sensing and automotive systems.
- LED:General illumination and display backlighting applications absorb the majority of wafer capacity from domestic epitaxy houses. MEE carbon efficiency mandates are accelerating retrofit demand in industrial facilities across Guangdong and Jiangsu provinces.
- Laser Diodes:Coherent light emission at specific wavelengths enables fiber optic communications and LiDAR distance measurement. Domestic EV OEMs in Shenzhen and Shanghai are consolidating supplier frameworks for advanced driver-assistance system integration.
- Photo Detectors:Convert optical signals to electrical current for imaging and sensing applications.
- Photovoltaics:Solar energy conversion cells for power generation and specialized optoelectronic energy harvesting.
Leading the category by volume: LED. Expanding most quickly: Laser Diodes.
Technology:
Cost structures vary dramatically between legacy silicon-based approaches and emerging compound semiconductor platforms requiring specialized fabrication equipment.
- Silicon Photonics:CMOS-compatible optical interconnects integrate waveguides and modulators on silicon substrates. Data center operators in Beijing and Shanghai are demanding higher bandwidth density at reduced energy per bit.
- Integrated Optics:Monolithic combination of multiple optical functions on single chips reduces assembly complexity. Telecommunications infrastructure deployment is pulling demand through state-backed broadband expansion programs.
- Organic Optoelectronics:Carbon-based semiconductors enable flexible form factors for emerging display applications.
- Quantum Dots:Nanocrystal structures enable tunable emission wavelengths for premium display color gamut.
Dominating current revenue: Silicon Photonics. Gaining share fastest: Integrated Optics.
Application:
Volume concentration in mature segments contrasts with margin expansion in precision sensing and specialized illumination.
- Telecommunications:Optical fiber transmission systems and network infrastructure equipment. MIIT GB standards enforcement is conditioning product registration timelines for domestic market access.
- Displays:TFT-LCD and AMOLED panel backlighting and direct emission systems. BOE Technology Group and domestic panel producers are retrofitting production lines under MEE emissions audit pressure.
- Lighting:General and specialized illumination across residential, commercial, and industrial environments.
- Sensing:Distance measurement, environmental monitoring, and biometric detection systems.
Generating highest absolute revenue: Displays. Climbing the fastest: Sensing.
End User:
Procurement patterns diverge between price-sensitive consumer volumes and specification-driven automotive and medical requirements.
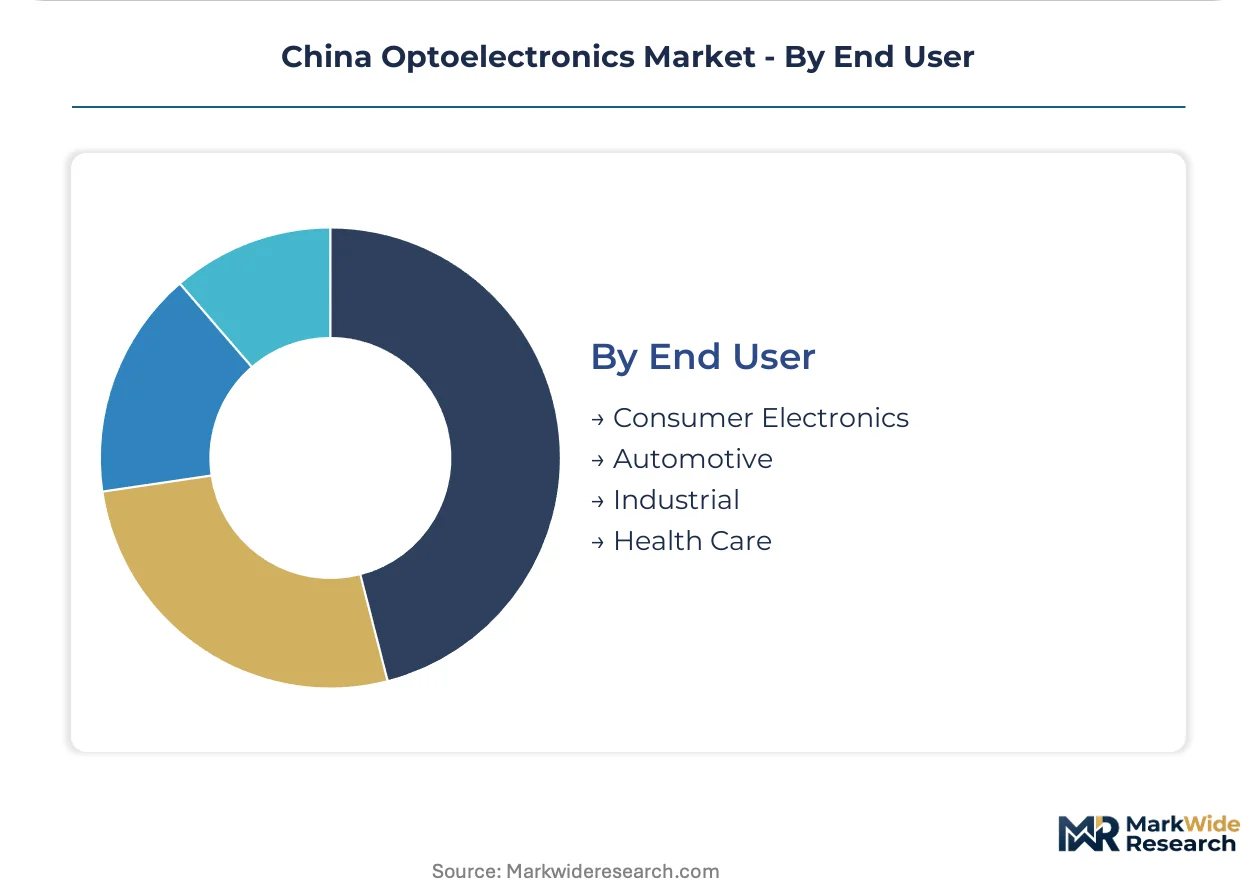
- Consumer Electronics:Smartphones, tablets, and wearable devices absorb standardized optical components at massive scale. Shenzhen-Dongguan cluster integration compresses logistics costs for export-bound production.
- Automotive:LiDAR, camera modules, and interior lighting systems for electric and conventional vehicles. Domestic OEM supply chains are absorbing advanced driver-assistance systems at accelerating qualification pace.
- Industrial:Manufacturing automation, process monitoring, and machine vision applications.
- Health Care:Medical imaging, diagnostic equipment, and therapeutic light sources. NMPA device classification rules constrain design cycles and extend certification timelines.
Commanding largest volume share: Consumer Electronics. Steepest expansion trajectory: Automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors China's optoelectronics manufacturing gravity, with Dongguan and Guangzhou forming the Pearl River Delta cluster that concentrates epitaxy, packaging, and module assembly operations for domestic and export-bound production.
Guangdong Province
Automotive LiDAR and advanced driver-assistance systems pull laser diode demand through tiered supplier contracts to domestic EV manufacturers. MEE dual carbon enforcement tightens factory emissions audits and energy intensity benchmarks for display panel producers. Shenzhen-Dongguan corridor integration compresses logistics costs and qualification timelines for LED and optical component exports.
Jiangsu Province
TFT-LCD and AMOLED panel manufacturing absorbs substantial optoelectronic component volumes for backlighting and direct emission systems. MIIT GB standards compliance extends product registration timelines for new market entrants. Suzhou and Wuxi host concentrated packaging and testing operations serving telecommunications and consumer electronics end users.
Beijing-Tianjin-Hebei
Data center operators demand silicon photonics interconnects at higher bandwidth density and reduced energy per bit. SAMR market access certification conditions domestic product registration for optical communications equipment. Beijing's Zhongguancun technology zone anchors R&D concentration for integrated optics and quantum dot applications.
Sichuan-Chongqing
Western manufacturing expansion targets land and energy cost advantages for fabs diversifying beyond coastal concentration. NMPA medical-grade device classification rules create procurement demand for certified imaging and diagnostic light sources. Chengdu's electronics industrial park attracts gallium nitride epitaxy investments under central government industrial transfer incentives.
Hubei Province
Telecommunications infrastructure deployment pulls demand for optical fiber transmission systems through state-backed broadband expansion programs. Wuhan's optoelectronics industrial cluster integrates chip design, wafer fabrication, and module assembly for domestic network equipment suppliers. Provincial industrial policy supports compound semiconductor substrate development to reduce foreign-owned fab dependencies.
China Optoelectronics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and end-use certification requirements. The vendor base stratifies into three tiers: integrated display panel producers with captive component demand, dedicated LED and laser diode specialists serving external markets, and optical module assemblers focused on automotive and consumer imaging. Dominant competitive moves include backward integration into epitaxy capacity and strategic partnerships with domestic EV OEMs for LiDAR qualification.
Within the integrated display tier, BOE Technology Group Co., Ltd. and Shenzhen China Star Optoelectronics Technology Co., Ltd. occupy positions that exemplify vertical control from substrate through finished panel. Among compound semiconductor specialists, Sanan Optoelectronics Co., Ltd. anchors gallium nitride epitaxy capacity serving LED and RF applications. These three entities represent distinct archetypes: the diversified panel conglomerate, the regional display subsidiary, and the dedicated compound semiconductor fabricator.
| Leading Market Players |
|---|
| BOE Technology Group Co., Ltd. |
| Shenzhen China Star Optoelectronics Technology Co., Ltd. |
| Sanan Optoelectronics Co., Ltd. |
| HC Semitek Corporation |
| Leyard Optoelectronic Co., Ltd. |
| Nationstar Optoelectronics Co., Ltd. |
| Sunny Optical Technology Group Co., Ltd. |
| OFILM Group Co., Ltd. |
| Focuslight Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate costs cascade through epitaxy, packaging, and module assembly tiers, with Shenzhen-Dongguan cluster proximity compressing logistics premiums for export-bound production while MEE carbon audits add compliance premiums to display panel inputs.
Pricing Analysis
Yield-per-wafer throughput anchors value-based pricing for laser diode and LED manufacturers serving automotive LiDAR and advanced driver-assistance system OEMs. Pricing stratifies across premium, standard, and economy tiers based on spectral linewidth precision and MIIT GB standards certification grade. Cost compression in standard-grade LED backlights intensifies as BOE and domestic panel producers consolidate supplier frameworks. Tier-1 automotive integrators exhibit least price sensitivity for qualified LiDAR components, while consumer electronics assemblers drive hardest bargaining on optical imaging modules.
Supply Chain Analysis
Freight cost differentials between coastal Guangdong clusters and inland Hubei-Sichuan expansion zones are reshaping fab location decisions for gallium nitride epitaxy capacity. Domestic supply draws from Japan, South Korea, and domestic crystal growth operations for silicon carbide substrates and specialty gases. Single-source vulnerability concentrates in foreign-owned compound semiconductor wafer fabs subject to export control uncertainty. Distribution runs through tiered component contracts from epitaxy houses to packaging operations, then to module assemblers serving domestic EV OEMs and export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride epitaxy capacity scarcity props pricing for qualified automotive laser diodes, with domestic substrate supply security emerging as the binding constraint across the projection horizon.
For Market Incumbents: Hedge against silicon photonics substitution in data center interconnects by accelerating backward integration into captive gallium nitride epitaxy capacity in Guangdong and Hubei provinces. Defensive consolidation through exclusive supply agreements with Shenzhen-based EV OEMs locks in LiDAR qualification pipelines before tier-1 integrators absorb more design responsibility. For New Entrants and Emerging Players: Capture white-space in medical-grade optoelectronics certified under NMPA device classification rules, where extended design cycles create incumbent vulnerability. Central China manufacturing expansion into Sichuan-Chongqing offers land and energy cost advantages for fabs seeking qualification outside coastal concentration. Go-to-market leverage rests on foundry service models integrating CMOS fabrication with optical functionality for telecommunications applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor compound semiconductor specialists with proven epitaxy yield rates in Chengdu and Wuhan industrial parks, where central government transfer incentives reduce facility cost bases. Long-term viability over the mid-window hinges on substrate supply security positioning ahead of domestic crystal growth capacity scaling. Monitor MIIT enforcement patterns on GB standards compliance timelines as inflection signal for product registration friction affecting new market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy Capacity | Captive gallium nitride supply secures margins against substrate price volatility under MEE oversight. |
| Automotive LiDAR Qualification Partnership | Exclusive tier-1 supplier status with Shenzhen EV OEMs locks in multi-year component offtake commitments. |
| Central China Manufacturing Expansion | Hubei and Sichuan facilities exploit land and energy cost arbitrage versus coastal Guangdong concentration. |
| Silicon Photonics Foundry Service Launch | CMOS-optical integration targets Beijing-Shanghai data center demand for bandwidth density improvements. |
| NMPA Medical-Grade Certification Investment | Certified imaging and diagnostic light sources access captive domestic healthcare procurement channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with epitaxy operations managers, automotive Tier-1 procurement leads, display panel supply planners, and NMPA regulatory affairs specialists. MIIT GB standards documentation, SAMR market access certification records, MEE emissions audit disclosures, and compound semiconductor import statistics supplied validation benchmarks. Bottom-up segment modeling triangulated against top-down macroeconomic indicators across the analysis window.
Product-type granularity distinguished LED, laser diode, and photodetector categories by wafer size, epitaxy platform, and packaging architecture. Technology segmentation separated silicon photonics, integrated optics, and compound semiconductor approaches by fabrication equipment requirements and end-use bandwidth specifications. Application and end-user dimensions captured telecommunications, display, automotive, and medical-grade demand patterns with distinct pricing elasticities and certification burdens. CAGRs derived from installed base growth, replacement cycle acceleration, and content-per-unit expansion in electric vehicle platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control regime evolution for compound semiconductor substrates and MEE dual carbon enforcement intensity. Forecasts reflect documented assumptions on domestic EV adoption curves, data center construction pipelines, and central government industrial transfer incentive durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Laser Projector Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Light Projector Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market