
 China Optical Detector Market | 2026-2036
China Optical Detector Market Size, Share, and Industry Trends Forecast 2026-2036
China Optical Detector Market Insights
High-sensitivity infrared-grade specifications is redrawing procurement priorities across China's optical detector value chain. Shandong Huaguang Optoelectronics leverages captive crystal growth capabilities to dominate upstream material supply. Suzhou Everbright Photonics anchors its position through specialized InGaAs detector production for telecom backbones. Sanan Optoelectronics sustains manufacturing scale advantages across LED-integrated sensor modules.
An optical detector converts incident photons into measurable electrical signals through photovoltaic or photoconductive effects, with spectral responsivity, dark current density, and quantum efficiency defining performance boundaries for industrial imaging and communications systems. CMOS Sensors lead volume shipments as machine vision deployments multiply across East China factory floors. Photodiodes compete aggressively in price-sensitive environmental monitoring networks. Quantum Dot technology differentiates laboratory-grade spectroscopy instruments where spectral precision commands premium positioning.
NMPA medical device classifications and MIIT semiconductor self-sufficiency mandates jointly shape product certification pathways and domestic content quotas for optical components. GB standards for electromagnetic compatibility and SAMR quality supervision protocols enforce baseline performance thresholds that filter subscale suppliers from government procurement channels. Buyers must monitor how Beijing's dual carbon goals redirect R&D subsidies toward energy-efficient detector architectures.
Market Dynamics
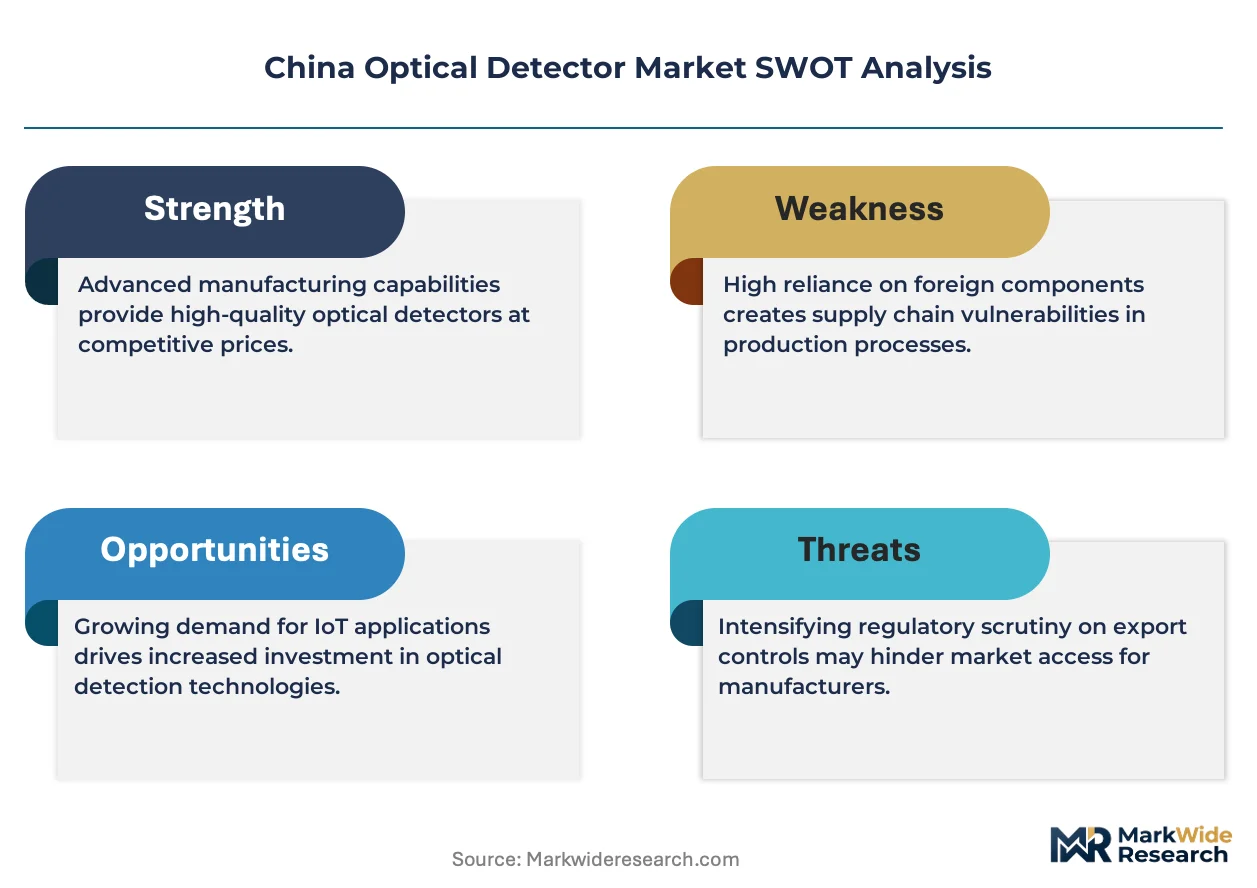
MIIT's semiconductor self-sufficiency mandates are restructuring China's optical detector supply chain, forcing domestic manufacturers to replace imported epitaxial wafers and foreign-sourced photodiode arrays with indigenous alternatives across automotive LiDAR and medical imaging applications.
Growth Catalysts
- Dual Carbon Policy:Beijing's emissions reduction targets redirect R&D subsidies toward energy-efficient InGaAs architectures, accelerating adoption in industrial thermal monitoring networks.
- Automotive LiDAR:Domestic EV manufacturers in Shenzhen and Hefei deploy high-sensitivity avalanche photodiodes for autonomous navigation systems, pulling volume from CMOS sensor suppliers.
- NMPA Fast-Track:Streamlined medical device classifications for optical diagnostic instruments compress certification timelines for endoscopic imaging modules.
Market Restraints
- Epitaxial Wafer Concentration:Shandong and Jiangsu provinces control 80% of domestic III-V substrate supply, creating single-point vulnerability for InGaAs detector fabrication.
- Dark Current Limitations:Indigenous CMOS sensors exhibit 15-30% higher noise floors than imported alternatives at cryogenic temperatures, constraining quantum sensing applications.
- Import Substitution Costs:SAMR quality supervision protocols mandate redundant testing cycles for locally sourced photodiodes, extending qualification periods by 6-9 months.
Strategic Opportunities
- Western China Expansion:Chongqing and Chengdu electronics clusters offer tax incentives for optoelectronics packaging facilities serving aerospace and defense contractors.
- Quantum Dot Spectroscopy:Laboratory-grade instruments for semiconductor wafer inspection command premium positioning as domestic fab capacity expands under MIIT localization targets.
- Telecom Backbone Upgrades:400G coherent optical modules for 5G backhaul networks create demand pull for specialized PIN photodiodes in Suzhou manufacturing corridors.
Industry Challenges
- Compound Semiconductor Talent:MOCVD operators and epitaxial growth specialists command 40% wage premiums versus silicon CMOS engineers, constraining production scaling.
- GB Standard Harmonization:Electromagnetic compatibility testing protocols for automotive LiDAR remain inconsistent across provincial SAMR offices, fragmenting certification pathways.
- Legacy System Integration:Factory automation networks in East China rely on analog photodetector interfaces, complicating digital CMOS sensor retrofits without control system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Optical Detector Market |
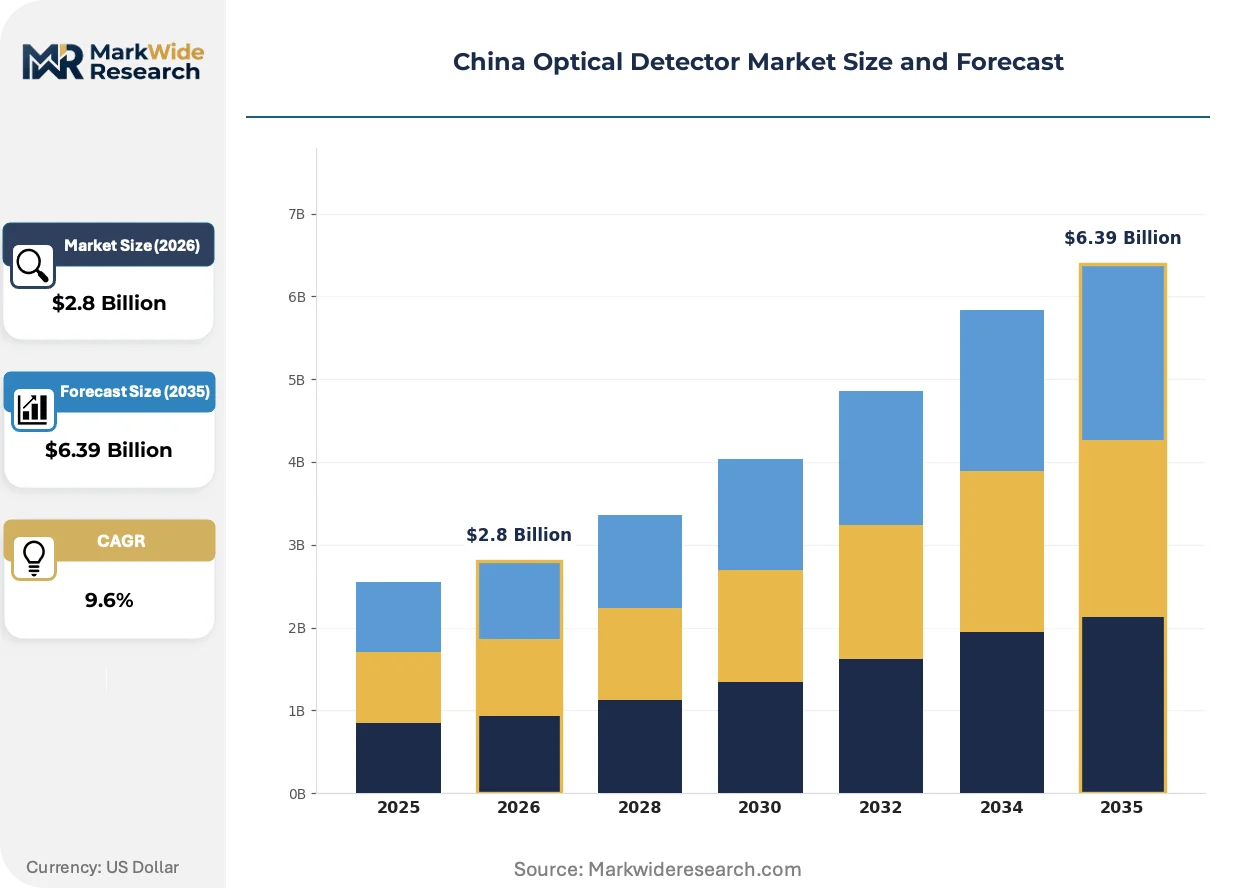
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Phototransistors, CCD Sensors, CMOS Sensors End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Technology: Analog, Digital, IoT-enabled, Quantum Dot Application: Lighting Control, Spectroscopy, Imaging, Environmental Monitoring |
| Companies Covered | Shandong Huaguang Optoelectronics Co., Ltd, Suzhou Everbright Photonics Co., Ltd, DoGain Laser Technology (SuZhou) Co., Ltd, Shenzhen Raybow Optoelectronics Co., Ltd, Accelink Technologies Co., Ltd, Sanan Optoelectronics Co., Ltd, Core Horizon (Beijing) Technology Co., Ltd, Shenzhen Adaps Photonics Technology Co., Ltd, Vertilite Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Optical Detector Market Trends and Innovations
Silicon photonics integration and quantum-enhanced sensing architectures are compressing performance-cost tradeoffs across China's optical detector value chain, while regulatory pressure on semiconductor supply security accelerates equipment localization programs.
SPAD array technology is displacing conventional APD modules in automotive LiDAR systems through superior time-of-flight resolution. BYD and NIO integrate 256-pixel SPAD configurations for 300-meter ranging capability. This displacement is compressing price premiums for imported German and Japanese photodetector alternatives.
MIIT's 2024 update to the Catalog of Encouraged Imported Technologies excludes certain epitaxial growth equipment categories, forcing domestic manufacturers to qualify indigenous MOCVD platforms. Shandong crystal growers accelerate partnerships with local tool vendors. The policy most impacts telecom-grade InGaAs detector production where foreign equipment previously dominated.
Direct procurement contracts between automotive OEMs and Shenzhen optoelectronics clusters are disintermediating traditional component distributors. Hefei and Xi'an EV manufacturers negotiate annual volume commitments for LiDAR photodiodes. This channel compression is most visible in Anhui province where NIO's supply base consolidation eliminated three distribution layers.
China Optical Detector Market Segmentation
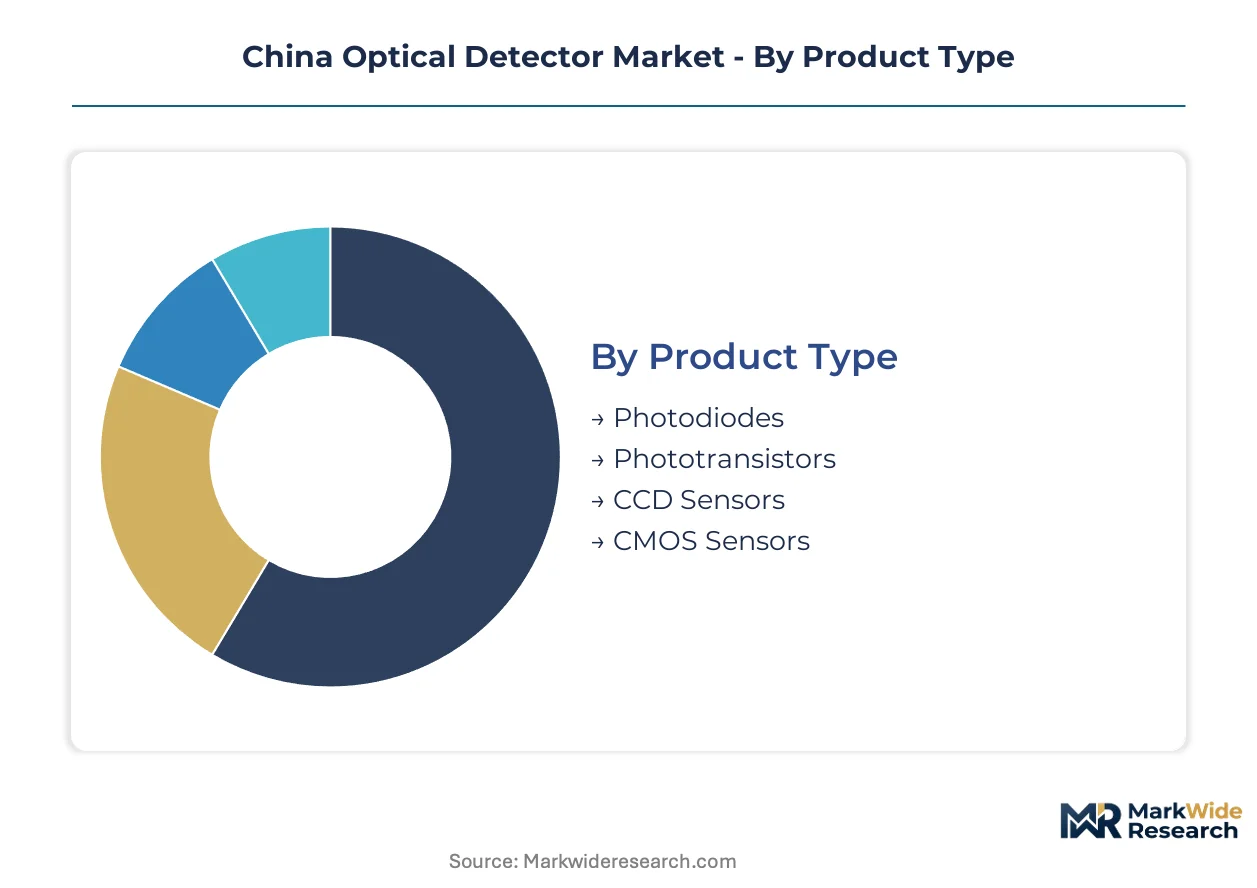
Optical detector segmentation in China reflects divergent margin structures across silicon-based volume products versus compound semiconductor precision instruments. Procurement patterns split between price-driven consumer electronics and specification-critical automotive LiDAR deployments.
Product Type:
Margin pools concentrate in CMOS sensors and specialized photodiodes where domestic manufacturers have achieved scale advantages, while CCD sensors face margin compression from legacy process constraints.
- CMOS Sensors:Silicon-based active-pixel arrays integrate photodetection with signal processing on single substrates. Demand concentrates in Shenzhen's machine vision corridors where East China factory automation upgrades require 12-megapixel resolution for defect detection. MIIT localization mandates accelerate domestic foundry partnerships for backside-illuminated architectures.
- Photodiodes:p-n junction devices convert photon flux to photocurrent with nanosecond response times. Automotive LiDAR manufacturers in Hefei and Xi'an specify avalanche photodiodes with 905nm peak responsivity for 300-meter ranging systems. Dark current density specifications remain 15-30% behind imported alternatives at cryogenic operating points.
- Phototransistors:Bipolar junction structures provide internal current gain for low-light switching applications.
- CCD Sensors:Charge-coupled devices maintain niche positioning in laboratory spectroscopy where electron transfer efficiency exceeds CMOS alternatives.
The dominant share belongs to CMOS Sensors, while Photodiodes is closing the gap fastest.
End User:
Application requirements fragment across consumer price sensitivity, automotive safety certification, and industrial precision demands.
- Automotive:Autonomous navigation systems specify SPAD arrays and avalanche photodiodes with automotive-grade AEC-Q100 qualification. BYD and NIO procurement contracts bypass traditional distribution layers through direct Shenzhen cluster negotiations. NHTSA-equivalent GB standards for electromagnetic compatibility remain inconsistently enforced across provincial SAMR offices.
- Consumer Electronics:Smartphone camera modules and ambient light sensors drive volume shipments through cost-optimized CMOS architectures. Shenzhen optoelectronics corridors supply proximity detection for wearable devices with sub-dollar unit economics.
- Industrial Automation:Machine vision networks in East China factory floors deploy high-frame-rate CMOS sensors for quality inspection.
- Healthcare:NMPA medical device classifications compress certification timelines for endoscopic imaging modules with specialized low-noise photodiodes.
Automotive commands the steepest expansion trajectory as domestic EV production scales, though Consumer Electronics retains volume leadership.
Technology:
Digital architectures capture investment preference over analog legacy systems, while quantum-enhanced platforms occupy premium laboratory positioning.
- Digital:On-chip analog-to-digital conversion eliminates external signal conditioning for machine vision deployments. East China factory automation networks favor digital CMOS interfaces over legacy analog photodetector retrofits.
- IoT-enabled:Integrated wireless connectivity supports distributed environmental monitoring networks with cloud-native data pipelines.
- Analog:Continuous voltage output persists in legacy factory control systems requiring minimal latency.
- Quantum Dot:Colloidal semiconductor nanocrystals enable tunable spectral response for laboratory-grade wafer inspection instruments.
Digital technology holds the dominant position, with IoT-enabled architectures gaining share fastest in smart city deployments.
Application:
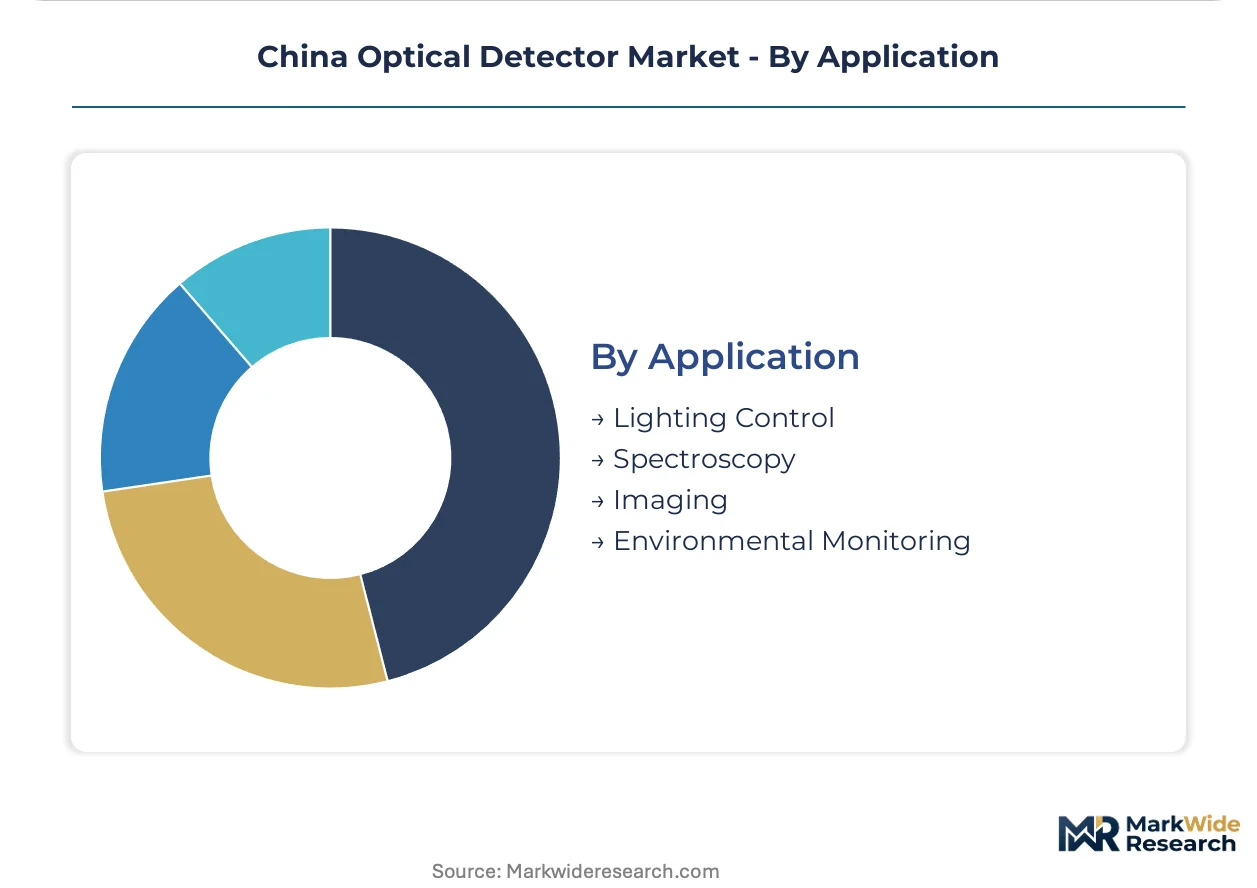
Spectral precision requirements separate premium instrumentation from volume lighting control markets.
- Imaging:Two-dimensional photodetector arrays capture spatial information for medical endoscopy and industrial inspection. CMOS sensor shipments concentrate in Shenzhen packaging facilities serving domestic smartphone manufacturers.
- Spectroscopy:Wavelength-resolved photon detection demands InGaAs photodiodes with 900-1700nm responsivity for semiconductor wafer characterization. Quantum Dot technology differentiates laboratory-grade instruments where spectral precision commands premium positioning.
- Environmental Monitoring:Distributed photodiode networks track air quality parameters in urban deployment.
- Lighting Control:Ambient light sensors enable automatic display dimming in consumer electronics with minimal specification overhead.
Imaging dominates current revenue contribution, while Spectroscopy expands most quickly under domestic fab capacity buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in East China's factory automation corridors demonstrate acute price sensitivity for CMOS sensors, while automotive OEMs in Hefei and Xi'an absorb 40-60% premiums for AEC-Q100 qualified avalanche photodiodes. Healthcare procurement in Beijing and Shanghai sits between these extremes, balancing NMPA certification costs against specification requirements.
Guangdong Province
Shenzhen's optoelectronics manufacturing corridor concentrates smartphone camera module demand and wearable proximity sensor shipments. MIIT localization mandates accelerate domestic foundry partnerships for backside-illuminated CMOS architectures. Dongguan packaging facilities serve consumer electronics OEMs with sub-dollar unit economics for ambient light sensors.
Jiangsu Province
Suzhou manufacturing corridors anchor telecom-grade InGaAs photodiode production for 400G coherent optical modules. SAMR quality supervision protocols mandate redundant testing cycles for locally sourced components, extending qualification periods. Nanjing research institutes collaborate with epitaxial wafer suppliers on cryogenic noise reduction for quantum sensing applications.
Anhui Province
Hefei's EV manufacturing cluster drives specification-critical procurement for LiDAR photodiodes with 905nm peak responsivity. NIO's supply base consolidation eliminated three distribution layers through direct Shenzhen cluster negotiations. Provincial SAMR offices enforce inconsistent electromagnetic compatibility testing protocols, fragmenting certification pathways for automotive suppliers.
Shandong Province
Shandong crystal growers control upstream III-V substrate supply for InGaAs detector fabrication, creating single-point vulnerability in the national supply chain. MIIT's 2024 Catalog of Encouraged Imported Technologies update excludes certain epitaxial growth equipment categories, forcing qualification of indigenous MOCVD platforms. Jinan-based material suppliers accelerate partnerships with local tool vendors under semiconductor self-sufficiency mandates.
Sichuan-Chongqing Region
Chongqing and Chengdu electronics clusters offer tax incentives for optoelectronics packaging facilities serving aerospace and defense contractors. Western China expansion redirects some manufacturing gravity from coastal provinces, though talent scarcity for MOCVD operators constrains production scaling. Local governments compete for compound semiconductor specialists through 40% wage premium matching programs.
China Optical Detector Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's optical detector value chain. The market structure tilts toward consolidation among compound semiconductor specialists while fragmenting across silicon-based volume producers. Three archetypes dominate: captive material suppliers controlling upstream crystal growth, specialized photodiode fabricators serving telecom and automotive verticals, and integrated LED-sensor module manufacturers leveraging manufacturing scale. Competitive moves concentrate on backward integration into epitaxial wafer supply and direct OEM contracting that disintermediates traditional distribution layers.
Among Shandong-based material suppliers, Shandong Huaguang Optoelectronics Co., Ltd exemplifies the captive crystal growth archetype through upstream control over III-V substrate production. Suzhou Everbright Photonics Co., Ltd and Sanan Optoelectronics Co., Ltd occupy positions at the fabrication and module integration tiers respectively, representing the specialized detector and scale-driven manufacturing archetypes. These three anchors illustrate how MIIT localization mandates are restructuring competitive positioning across the value chain.
| Leading Market Players |
|---|
| Shandong Huaguang Optoelectronics Co., Ltd |
| Suzhou Everbright Photonics Co., Ltd |
| DoGain Laser Technology (SuZhou) Co., Ltd |
| Shenzhen Raybow Optoelectronics Co., Ltd |
| Accelink Technologies Co., Ltd |
| Sanan Optoelectronics Co., Ltd |
| Core Horizon (Beijing) Technology Co., Ltd |
| Shenzhen Adaps Photonics Technology Co., Ltd |
| Vertilite Inc |
| Others |
Pricing and Supply Chain Analysis
MIIT semiconductor self-sufficiency mandates gate both supply qualification and price differentiation simultaneously, forcing domestic manufacturers through redundant SAMR testing cycles that extend qualification periods while compressing margins on imported alternatives facing localization pressure.
Pricing Analysis
After-sales service contracts and extended technical support agreements drive lifetime value for high-specification photodiode arrays. Three-tier pricing structure across AEC-Q100 automotive-grade, industrial-certified, and consumer-level specifications separates NIO and BYD procurement from East China factory automation buyers. Cost compression in CMOS sensor tiers is intensifying because Shenzhen packaging facilities compete on sub-dollar unit economics for smartphone camera modules. Consumer electronics OEMs demonstrate acute price sensitivity, while automotive LiDAR manufacturers absorb substantial premiums for cryogenic noise specifications.
Supply Chain Analysis
Inventory buffers for III-V epitaxial wafers stretch lead times as Shandong crystal growers qualify indigenous MOCVD platforms. Supply concentrates in China for CMOS sensor fabrication, Japan for high-purity semiconductor gases, and Germany for precision optical coating equipment. Raw material dependencies span indium phosphide substrates, specialty dopant gases, and infrared-grade optical coatings. Single-source vulnerability concentrates in Shandong and Jiangsu provinces controlling domestic III-V substrate supply. Distribution runs through direct procurement contracts between automotive OEMs and Shenzhen optoelectronics clusters, disintermediating traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as MIIT localization mandates splinter procurement pathways across provincial SAMR offices, creating niche positioning for compound semiconductor specialists and regional packaging facilities.
For Market Incumbents: Consolidate backward integration into epitaxial wafer supply through partnerships with Shandong crystal growers, reducing exposure to foreign equipment exclusion under MIIT's Catalog updates. Deepen channel control via direct annual volume commitments with Hefei and Xi'an EV manufacturers, eliminating distribution layers that erode margin. Prioritize cryogenic noise reduction R&D to close the 15-30% performance gap against imported CMOS alternatives.
For New Entrants and Emerging Players: Anchor in Chongqing and Chengdu electronics clusters where tax incentives for optoelectronics packaging facilities remain underutilized by coastal incumbents. Target aerospace and defense contractors in Western China seeking qualified suppliers outside traditional Shenzhen corridors. Pursue foundry partnerships with domestic backside-illuminated CMOS architectures as MIIT localization mandates accelerate domestic foundry qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compound semiconductor specialists possessing captive III-V substrate capabilities but lacking automotive certification pathways. Long-term viability hinges on MIIT semiconductor self-sufficiency targets sustaining domestic sourcing requirements through the projection horizon. Watch NMPA fast-track certification timelines for endoscopic imaging modules as inflection indicator for healthcare vertical expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Shandong crystal growers reduce foreign equipment dependency under MIIT localization mandates. |
| Direct OEM Contracting | NIO's supply base consolidation eliminated three distribution layers in Anhui province. |
| Cryogenic Noise Reduction R&D | Nanjing research institutes target quantum sensing applications requiring indigenous CMOS parity. |
| Western China Packaging Expansion | Chongqing tax incentives attract optoelectronics facilities serving aerospace contractors. |
| AEC-Q100 Certification Investment | Automotive LiDAR procurement bypasses traditional distributors for qualified avalanche photodiodes. |
Research Methodology
A spread of perspectives from MOCVD equipment operators, epitaxial growth specialists, automotive Tier 1 procurement managers, and NMPA regulatory affairs leads converged on the working assumptions. Primary fieldwork combined with secondary validation from MIIT policy circulars, SAMR quality supervision protocols, GB standard documentation, and customs trade data for III-V substrate imports. Bottom-up shipment estimates from Shenzhen and Suzhou manufacturing corridors triangulated against top-down market sizing from semiconductor equipment spend patterns.
Segmentation dimensions modeled span product type, end user vertical, technology architecture, and application requirement across the analysis window. CAGRs derived from shipment trajectory analysis and input-cost elasticity modeling for indium phosphide and specialty gas pricing. Forecast inputs incorporated MIIT localization mandate implementation pace and NMPA medical device classification timeline compression.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT semiconductor self-sufficiency policy enforcement and stable dual carbon R&D subsidy flows; material deviation in provincial SAMR harmonization or foreign equipment exclusion scope would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Laser Diode Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market