
 EPON ONU Market | 2026-2036
EPON ONU Market Size, Share, and Industry Trends Forecast 2026-2036
EPON ONU Market Insights
Residential broadband demand is rebalancing toward multi-dwelling unit deployments as fiber penetration deepens in Asia-Pacific markets. Huawei sustains integrated chipset-to-system capabilities across its ONU portfolio, while ZTE competes aggressively on price-performance metrics in emerging carrier tenders. FiberHome anchors domestic Chinese supply through captive optical component production, and ADTRAN differentiates its North American presence with software-defined access layer integration.
An Ethernet Passive Optical Network Optical Network Unit (EPON ONU) terminates the subscriber-side fiber link in a point-to-multipoint architecture, converting optical signals at 1490 nm downstream and 1310 nm upstream into electrical Ethernet frames for end-user devices. The unit embeds a laser driver, burst-mode receiver, and MAC controller to synchronize with the optical line terminal across a 20 km reach budget. GEPON ONU remains the volume workhorse in cost-sensitive markets, while 10G EPON ONU captures upgrade cycles where carriers require symmetric 10 Gbps delivery. Multi-Service ONU units command margin premiums by integrating VoIP, CATV, and Wi-Fi gateway functions into a single chassis, reducing premises equipment count for operators.
IEEE 802.3ah and ITU-T G.984 standards govern interoperability and optical power budgets, while China's MIIT issues network access licenses that filter non-compliant hardware from carrier procurement. The FCC in the United States and ETSI in Europe enforce electromagnetic compatibility and safety certifications that shape product design cycles. Stakeholders must monitor wavelength-division multiplexing roadmaps and silicon photonics cost curves to time capacity investments against carrier capex cycles.
Market Dynamics
The IEEE 802.3av standardization for 10G-EPON is compressing equipment refresh cycles across carrier networks, forcing incumbent GEPON ONU vendors to accelerate symmetric 10 Gbps roadmaps or cede upgrade contracts to integrated chipset-to-system suppliers.
Growth Catalysts
- MIIT Gigabit Broadband Mandate:China's Ministry of Industry and Information Technology targets universal gigabit coverage, compelling provincial carriers to replace legacy GEPON infrastructure with 10G EPON ONU units in multi-dwelling unit deployments.
- Fiber-to-the-Home Density:Telecom operators in Japan and South Korea are deepening last-mile fiber penetration in apartment complexes, rebalancing procurement volumes toward compact, multi-service ONU form factors.
- Silicon Photonics Cost Curves:Shenzhen and Wuhan manufacturing clusters have achieved scale in optical transceiver production, reducing bill-of-materials costs for burst-mode receivers and laser drivers.
Market Restraints
- PON Chipset Supply Concentration:Advanced MAC controllers and laser drivers depend on a limited set of East Asian foundry capacity, exposing equipment vendors to wafer allocation volatility.
- Copper Infrastructure Inertia:Cost-sensitive markets with entrenched DSL or coaxial deployments delay fiber overbuilds, particularly where subscriber density falls below 30 homes passed per kilometer.
- Wavelength Division Multiplexing Complexity:The 1577 nm downstream and 1270 nm upstream wavelength plan for XGS-PON creates interoperability friction with existing 1490/1310 nm EPON ONU installed bases.
Strategic Opportunities
- Rural Broadband Subsidies:The US Infrastructure Investment and Jobs Act allocates capital expenditure support for fiber overbuilds in underserved counties, opening procurement channels for price-optimized GEPON ONU configurations.
- Multi-Service Integration:Converged ONU units combining Wi-Fi 6E gateway functions with VoIP and CATV RF overlay capture margin premiums by reducing premises equipment count for tier-2 carriers.
- Software-Defined Access Convergence:Integration of NETCONF/YANG management interfaces with optical layer control planes enables remote provisioning and reduces truck-roll costs for distributed network operators.
Industry Challenges
- Burst-Mode Receiver Calibration:Rapid synchronization with optical line terminal ranging protocols demands specialized analog design talent scarce outside Shenzhen, Wuhan, and Tokyo engineering clusters.
- MIIT Network Access Licensing:China's compulsory certification timeline for optical transmission equipment extends product qualification cycles by 8-14 months, compressing window for first-mover advantage in carrier tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPON ONU Market |
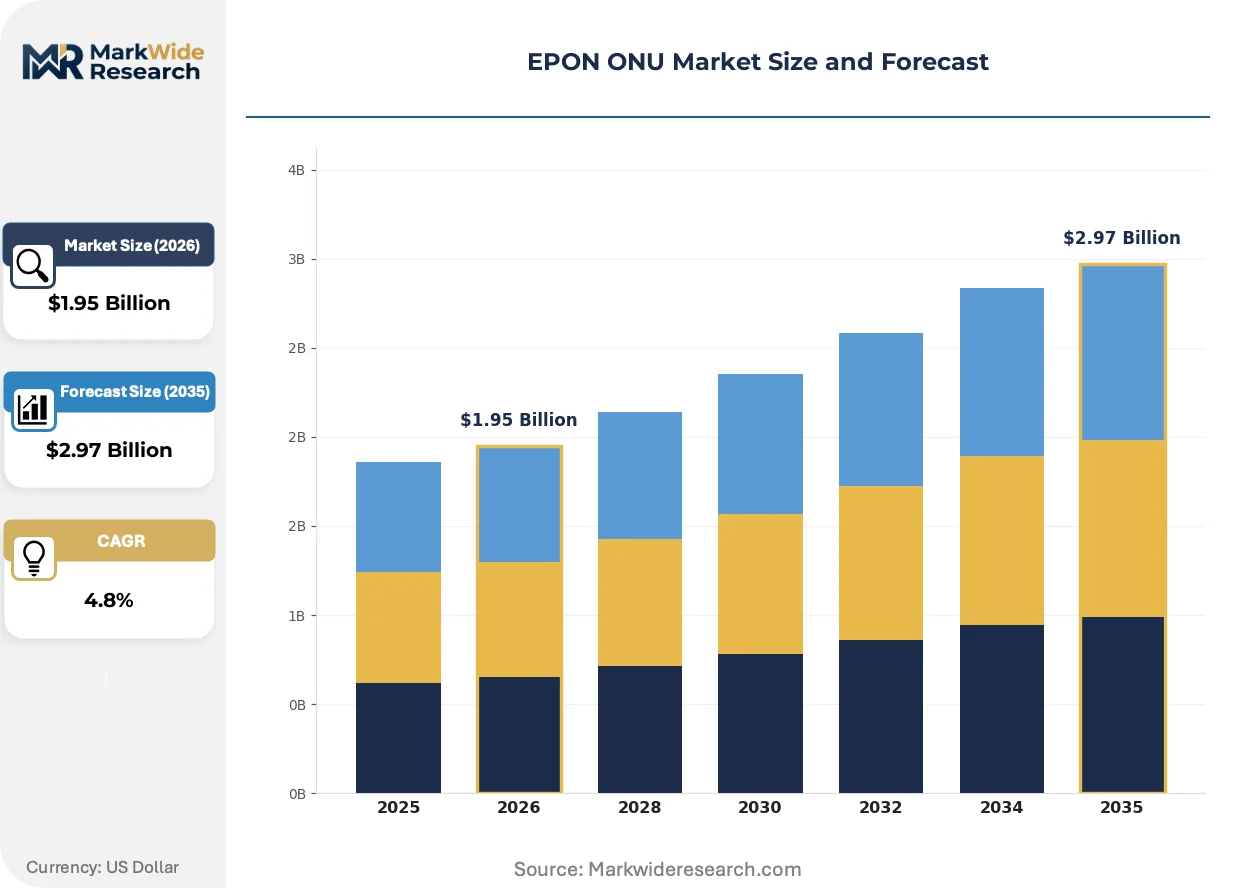
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GEPON ONU, 10G EPON ONU, Triplex ONU, Multi-Service ONU End User: Telecom Operators, Internet Service Providers, Enterprises, Residential Technology: EPON, GPON, Hybrid Fiber Coaxial, Wi-Fi Deployment: Urban, Suburban, Rural, Indoor |
| Companies Covered | VSOL, ADTRAN, Huawei, Sopto, Hitron Technologies, ZTE, Raisecom, Topvision, FiberHome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPON ONU Market Trends and Innovations
Silicon photonics integration and software-defined access architectures are compressing the traditional boundary between optical physical layer and Ethernet service delivery, enabling new entrants to challenge incumbent system vendors.
Silicon photonics is unifying laser driver, modulator, and receiver functions onto single-die implementations. Tier-1 carriers in Japan and South Korea are piloting these transceivers in 10G EPON ONU designs to reduce power consumption below 4 watts per port. The technology is unifying previously discrete component supply chains, compressing vendor margins for standalone optical module suppliers.
China's MIIT has tightened electromagnetic compatibility testing protocols under revised GB standards for telecommunications equipment. The industrial consequence is extended pre-certification validation cycles for ONU vendors targeting provincial carrier tenders. Domestic manufacturers with captive testing laboratories in Shenzhen and Wuhan are absorbing compliance costs faster than import-dependent competitors.
Carrier procurement is consolidating around multi-year framework agreements with integrated chipset-to-system vendors. Tier-2 and tier-3 operators in the United States are abandoning discrete component sourcing in favor of pre-qualified, firmware-complete ONU platforms. This pattern is most visible in Midwest and Southeast regional carrier networks where technical staff density limits in-house integration capacity.
EPON ONU Market Segmentation
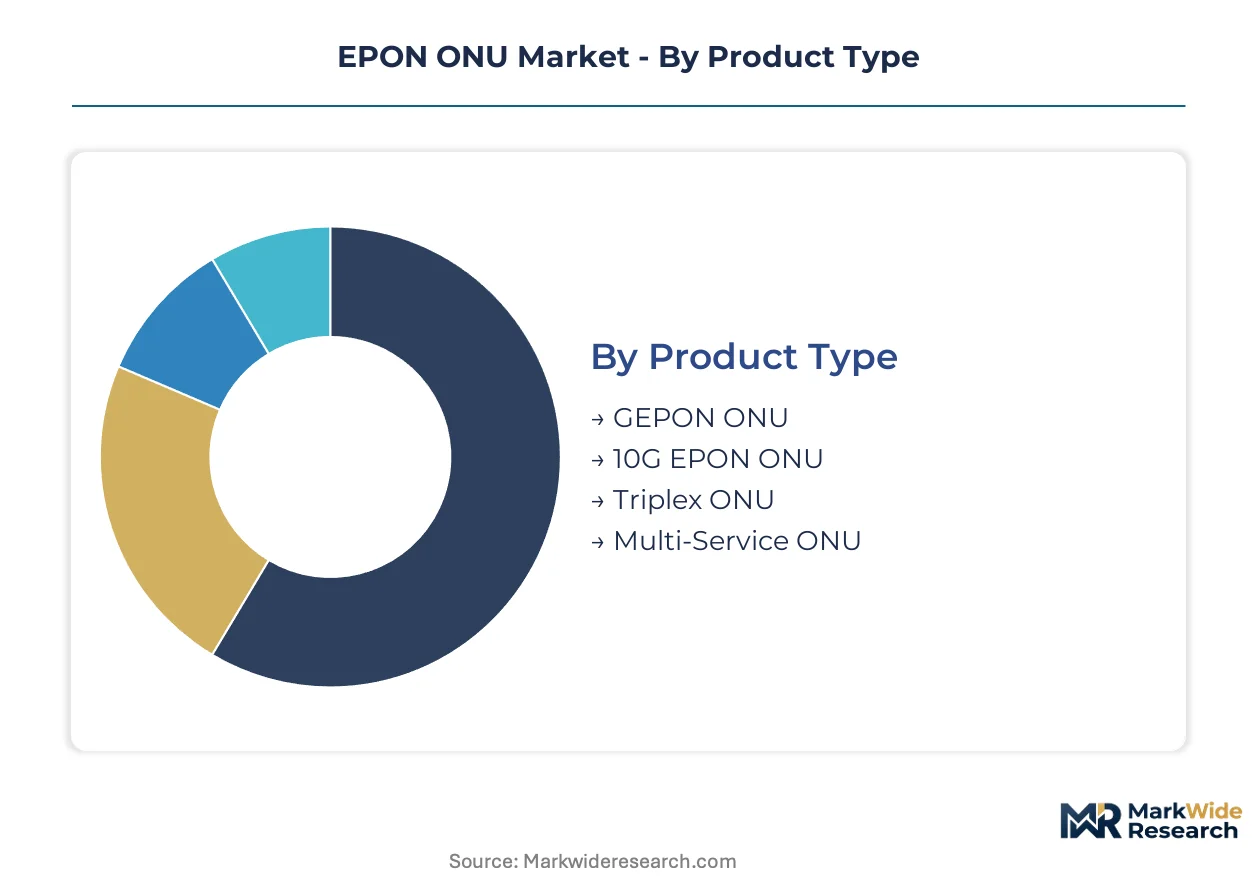
EPON ONU procurement patterns diverge sharply across carrier infrastructure cycles, premises density, and service convergence requirements. Equipment vendors must align product roadmaps with these demand fractures to capture replacement waves and greenfield deployments.
Product Type:
Cost sensitivity and bandwidth requirements separate buyers into legacy maintenance versus upgrade-driven procurement camps.
- GEPON ONU:Asymmetric 1 Gbps downstream/1.25 Gbps upstream units dominate cost-sensitive maintenance contracts and rural subsidy programs. China's provincial carriers still deploy these for sub-100 Mbps service tiers in county-level networks where fiber overbuild budgets remain constrained.
- 10G EPON ONU:Symmetric 10 Gbps capability addresses China's MIIT gigabit mandate and Japan's multi-dwelling unit upgrades. NTT East and China Mobile are consolidating procurement around these units for apartment complex deployments where 1 Gbps residential tiers are now table stakes.
- Triplex ONU:Integrated RF overlay for CATV services reduces premises equipment count for operators maintaining hybrid video-data bundles.
- Multi-Service ONU:Converged Wi-Fi gateway, VoIP, and routing functions command margin premiums by eliminating separate CPE installations.
GEPON ONU leads volumes today; 10G EPON ONU is gaining share fastest.
End User:
Technical integration capacity and procurement scale distinguish these buyer archetypes.
- Telecom Operators:Tier-1 carriers with captive engineering staff drive IEEE 802.3av-compliant, firmware-complete platform requirements. China Mobile, NTT, and KT specify pre-qualified ONU units through multi-year framework agreements that freeze out discrete component vendors.
- Internet Service Providers:Regional fiber overbuilders in the US Midwest and Southeast favor pre-integrated, remotely provisionable units to compensate for limited in-house optical engineering. These buyers prioritize NETCONF/YANG management interfaces over raw port density.
- Enterprises:Campus and industrial deployments demand hardened temperature specifications and redundant power inputs for utility and transportation verticals.
- Residential:Direct-to-consumer channels remain marginal; most residential endpoints flow through carrier-subsidized equipment programs.
Telecom Operators dominate procurement value; Internet Service Providers are expanding most quickly in North American markets.
Technology:
Physical layer standards determine interoperability boundaries and vendor qualification costs.
- EPON:IEEE 802.3ah/802.3av standards govern China's dominant procurement volume and Japan's upgrade cycles. The 1490 nm downstream/1310 nm upstream wavelength plan maintains installed base compatibility across 20 km reach budgets.
- GPON:ITU-T G.984-based deployments concentrate in European carrier networks and Verizon's US footprint. These units are non-interoperable with EPON OLT infrastructure, creating separate supply chain ecosystems.
- Hybrid Fiber Coaxial:DOCSIS 3.1/4.0 cable modems compete for bandwidth in legacy coaxial footprints, delaying fiber overbuilds where subscriber density falls below economic thresholds.
- Wi-Fi:Integrated 802.11ax/802.11be gateway functions in Multi-Service ONU units displace separate residential router purchases.
EPON leads volumes today; Wi-Fi integration is climbing the fastest as convergence accelerates.
Deployment:
Population density and civil infrastructure availability shape equipment form factor and power requirements.
- Urban:High-rise MDU deployments in Seoul, Tokyo, and Shenzhen drive compact, fanless ONU designs with multi-tenant VLAN segmentation. These environments prioritize space efficiency over extended temperature tolerance.
- Suburban:Single-family home clusters in Japan's prefectures and China's tier-2 cities balance cost optimization with aesthetic constraints for outdoor wall-mounted installations.
- Rural:Extended reach budgets and pole-mounted enclosures in US underserved counties and China's western provinces demand hardened temperature specifications and surge protection.
- Indoor:Customer-premise gateway positioning favors consumer-electronics industrial design and integrated Wi-Fi antenna arrays.
Urban deployments lead volumes today; Rural deployments are expanding most quickly under subsidy programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors exploit regulatory-arbitrage opportunities as China's MIIT certification timeline stretches 8-14 months, pushing some procurement toward Japan and South Korea where type-approval cycles compress competitive windows.
China
Provincial carriers under MIIT's gigabit mandate drive 10G EPON ONU replacement waves across multi-dwelling units. GB standards for electromagnetic compatibility extend pre-certification validation, favoring domestic manufacturers with captive Shenzhen and Wuhan testing laboratories. FiberHome anchors supply through vertically integrated optical component production.
Japan
NTT East and regional operators deepen fiber penetration in Tokyo and Osaka apartment complexes, consolidating procurement around IEEE 802.3av-compliant platforms. METI efficiency guidelines shape power consumption specifications below 4 watts per port. Nagoya engineering clusters supply burst-mode receiver calibration talent scarce elsewhere.
South Korea
KT and SK Broadband accelerate symmetric 10 Gbps deployments in Seoul high-rises where 1 Gbps residential tiers are now baseline. National broadband strategy targets universal gigabit coverage by 2026, compressing equipment refresh cycles. Busan manufacturing bases produce compact, fanless ONU designs for space-constrained MDU environments.
United States
Regional fiber overbuilders in Midwest and Southeast states leverage Infrastructure Investment and Jobs Act subsidies for rural county overbuilds. FCC electromagnetic compatibility and safety certifications shape product design cycles distinct from Asian type-approval regimes. Midwestern carriers prioritize NETCONF/YANG management interfaces over raw port density.
Germany
Deutsche Telekom and municipal carriers balance GPON legacy infrastructure against EPON migration timelines. ETSI interoperability standards and CE marking requirements filter non-compliant hardware from procurement. Bavarian industrial zones host system integrators serving Central European carrier consolidation trends.
EPON ONU Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated chipset-to-system vendors scale Shenzhen and Wuhan manufacturing to capture China's replacement wave. The vendor base stratifies across three tiers: captive optical component producers, firmware-complete platform suppliers, and discrete module vendors exposed to silicon photonics consolidation. Two strategic archetypes occupy contested positions—domestic Chinese manufacturers with MIIT certification advantages, and North American specialists with software-defined access integration. Competitive moves concentrate on multi-year framework agreements with tier-1 carriers and backward integration into burst-mode receiver supply.
Within the integrated-platform tier, Huawei and ZTE exemplify the Chinese archetype of chipset-to-system capability spanning ONU portfolios. ADTRAN occupies a position among North American vendors differentiating through access-layer software integration. FiberHome represents the domestic supply-chain anchor with captive optical component production in Wuhan manufacturing clusters.
| Leading Market Players |
|---|
| VSOL |
| ADTRAN |
| Huawei |
| Sopto |
| Hitron Technologies |
| ZTE |
| Raisecom |
| Topvision |
| FiberHome |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China's optical component sector anchor supply discipline through MIIT certification timelines that extend 8-14 months, compressing competitive windows for import-dependent vendors and concentrating pricing power among domestic manufacturers with captive testing laboratories in Shenzhen and Wuhan.
Pricing Analysis
Distributor margins compress as tier-1 carriers consolidate procurement around multi-year framework agreements with integrated chipset-to-system vendors. Pricing stratifies across premium 10G EPON ONU units with symmetric throughput, standard GEPON configurations for rural subsidy programs, and economy triplex designs for cost-sensitive maintenance contracts. Price differentiation hinges on MIIT network access licensing status and volume scale in provincial carrier tenders. Cost compression in standard-tier units is intensifying because silicon photonics integration reduces burst-mode receiver costs. Rural broadband subsidies in the United States represent the most price-sensitive buyer segment, while Japanese carriers with METI efficiency mandates show least sensitivity to unit premiums.
Supply Chain Analysis
MIIT electromagnetic compatibility certification under revised GB standards gates market access, extending pre-qualification validation cycles that favor domestic manufacturers with captive testing infrastructure. Manufacturing concentrates in China, Japan, and South Korea, with Shenzhen and Wuhan clusters supplying optical transceivers and PON chipsets at scale. Raw material dependencies center on indium phosphide substrates, burst-mode receiver photodiodes, and MAC controller silicon from East Asian foundry capacity. Single-source vulnerability in advanced laser driver supply exposes equipment vendors to wafer allocation volatility. Distribution runs through carrier-direct procurement channels and regional system integrators serving tier-2 operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's gigabit broadband mandate and IEEE 802.3av standardization compress equipment refresh cycles, forcing continuous capacity alignment with carrier capex waves.
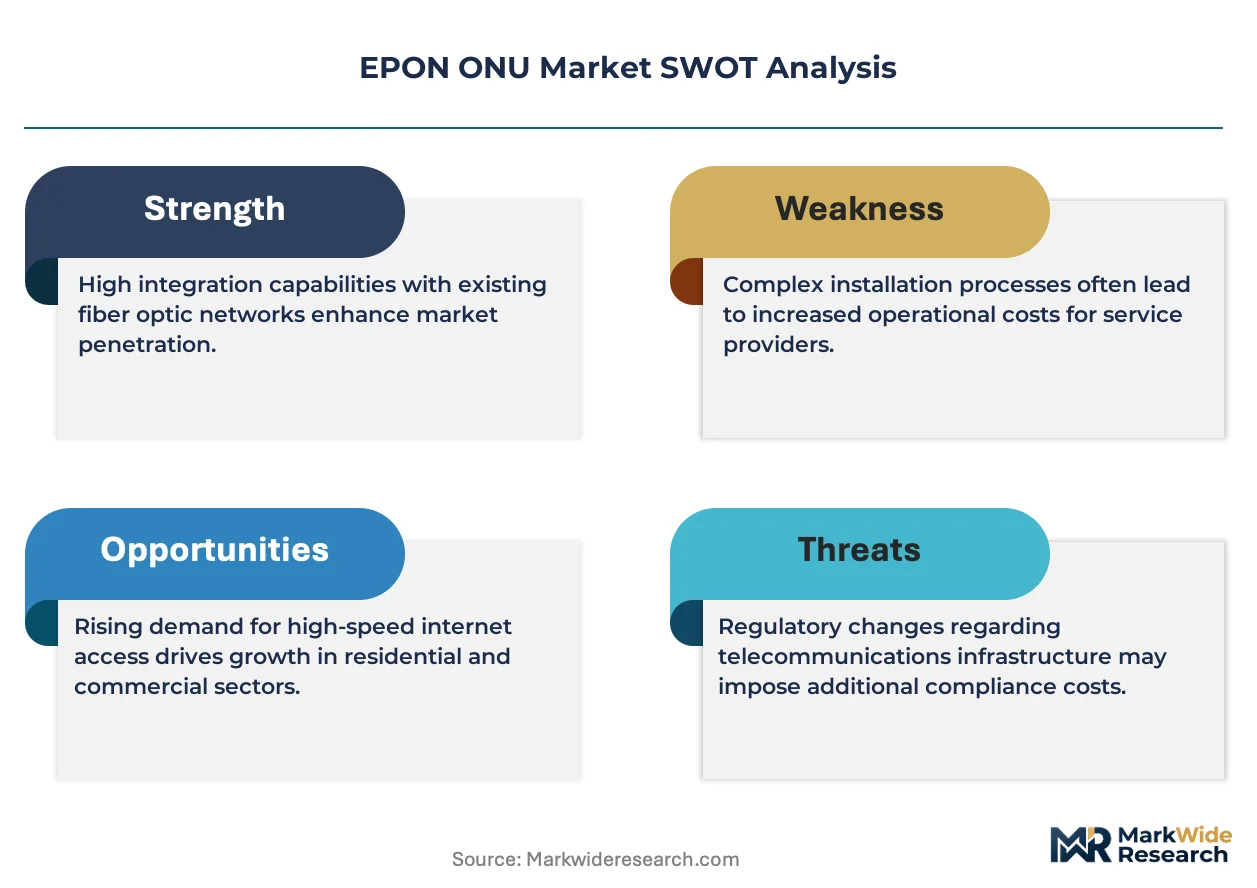
For Market Incumbents: Lock in multi-year framework agreements with tier-1 carriers before silicon photonics consolidation eliminates standalone optical module suppliers. Prioritize backward integration into burst-mode receiver supply to defend margins against integrated chipset-to-system competitors. Accelerate firmware-complete platform roadmaps to meet IEEE 802.3av compliance windows that freeze out discrete component vendors. For New Entrants and Emerging Players: The price-point gap between premium 10G EPON ONU units and economy GEPON configurations creates entry space for mid-tier specialists with software-defined access integration. Target North American regional fiber overbuilders in Midwest and Southeast states where technical staff density limits in-house integration capacity. Lead with NETCONF/YANG management interfaces that reduce truck-roll costs for distributed network operators. For Investors and Strategic Acquirers: Valuations sit cheapest among firmware-complete platform suppliers without captive optical component production, as silicon photonics integration compresses margins for standalone module vendors. The five-to-ten-year viability window favors acquisition targets with MIIT certification advantages and multi-year carrier framework agreements. Watch for inflection where wavelength-division multiplexing roadmaps trigger next-generation capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Component Supply | Captive burst-mode receiver production insulates Huawei and ZTE from foundry allocation volatility. |
| Software-Defined Access Layer Integration | NETCONF/YANG interfaces enable ADTRAN to capture Midwestern carriers with limited optical engineering staff. |
| MIIT Certification Laboratory Investment | Domestic testing infrastructure in Shenzhen accelerates pre-qualification timelines for provincial carrier tenders. |
| Multi-Service ONU Convergence | Integrated Wi-Fi 6E gateway functions command margin premiums by eliminating separate CPE installations. |
| Rural Broadband Subsidy Positioning | Price-optimized GEPON configurations open procurement channels under US Infrastructure Investment and Jobs Act programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optical network architects at tier-1 carriers, procurement leads at regional ISPs, burst-mode receiver design engineers in Nagoya engineering clusters, and regulatory affairs specialists navigating MIIT certification timelines. Secondary validation drew from IEEE 802.3ah and 802.3av standards documentation, MIIT network access license databases, FCC electromagnetic compatibility filings, and ETSI interoperability specifications. Bottom-up equipment shipment tracking and top-down carrier capex analysis triangulated market sizing across the projection horizon.
Historical reference periods anchored the forecast window to installed base replacement cycles and greenfield deployment waves. Segmentation modeling spanned product type, end-user technical integration capacity, physical layer technology standard, and deployment environment density. CAGRs derived from equipment refresh cycle compression rates and silicon photonics cost curve trajectories. Industry-specific inputs included PON chipset foundry capacity allocation patterns and provincial carrier tender award frequencies.
Caveats apply where wafer allocation volatility at East Asian foundries or shifts in China's gigabit broadband mandate timeline could materially shift the outlook. Forecasts reflect assumptions about IEEE standardization adherence and carrier procurement consolidation patterns. A model refresh is warranted upon material change in wavelength-division multiplexing commercialization timelines or rural subsidy program funding levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Light Projector Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Optoelectronic Development Tools Market