
 Superluminescent Diodes Market | 2026-2036
Superluminescent Diodes Market Size, Share, and Industry Trends Forecast 2026-2036
Superluminescent Diodes Market Analytics
The EU Medical Device Regulation is restructuring procurement criteria for photonic components across European healthcare systems, forcing suppliers to demonstrate traceable optical performance. Thorlabs Inc. leverages its vertically integrated manufacturing footprint to meet these documentation demands. Superlum Diodes Ltd. anchors its position through specialized gallium arsenide epitaxy capabilities. Exalos AG competes by sustaining Swiss precision in wavelength stability for ophthalmic instruments.
Superluminescent diodes emit broadband, low-coherence light from electrically pumped semiconductor structures, typically spanning 700–1700 nm with output powers from milliwatts to tens of milliwatts, serving applications requiring high spatial resolution without speckle noise. The medical diagnostics application commands substantial margin pools as hospitals upgrade optical coherence tomography platforms. Fiber optic sensors represent the fastest-expanding technology segment, driven by structural health monitoring in civil infrastructure. Broadband light source products dominate volume, though high-power diodes capture premium pricing in industrial settings.
The FDA in the United States and the EU MDR in Europe enforce divergent biocompatibility and electromagnetic compatibility standards that shape product development cycles and market access pathways. Japan's PMDA maintains stringent optical safety classifications that filter entry for non-specialized suppliers. China's NMPA has accelerated review timelines for domestically manufactured photonic devices, redirecting investment toward local production. Stakeholders must monitor regulatory harmonization negotiations between major jurisdictions to anticipate shifts in certification burden and competitive positioning.
Market Dynamics
Optical coherence tomography equipment upgrades in hospital networks are compressing supplier qualification timelines and forcing photonic component vendors to synchronize R&D cycles with medical device OEM roadmaps.
Growth Catalysts
- EU MDR documentation mandates:Medical device manufacturers must now submit traceable optical performance data for all photonic subcomponents, creating captive demand for suppliers with metrology capabilities.
- Fiber optic sensor deployment:Civil infrastructure monitoring programs in Germany and Switzerland are specifying broadband light sources for distributed strain sensing on bridges and tunnels.
- Gallium arsenide epitaxy specialization:Precision optics clusters in Jena have concentrated wafer-level expertise that shortens development cycles for custom wavelength specifications.
Market Restraints
- III-V semiconductor wafer supply:Ingot production concentrates among a handful of Japanese and German suppliers, exposing SLD manufacturers to allocation risk during capacity tightness.
- PMDA optical safety classifications:Japan's tiered hazard ratings require separate certification tracks for ophthalmic versus industrial applications, extending time-to-market.
- Supercontinuum laser substitution:Advances in photonic crystal fiber sources threaten SLD positioning in high-resolution spectroscopy applications above 100 mW output.
Strategic Opportunities
- China NMPA domestic manufacturing incentives:Accelerated review timelines for locally produced photonic devices are redirecting foreign investment toward Shanghai and Suzhou production facilities.
- Silicon photonics convergence:Hybrid integration of III-V SLD chips with silicon nitride waveguides enables wafer-scale packaging for consumer health monitoring wearables.
- Direct hospital procurement channels:Large clinic chains in Bavaria are bypassing distributor networks to negotiate volume contracts for OCT system spares and retrofits.
Industry Challenges
- Packaging engineer scarcity:Hermetic sealing of broadband emitters requires specialized fiber-pigtailing expertise that outpaces vocational training output in precision optics regions.
- Multi-jurisdiction certification overlap:Simultaneous FDA 510(k) and EU MDR submissions demand redundant biocompatibility testing protocols that strain mid-tier quality departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superluminescent Diodes Market |
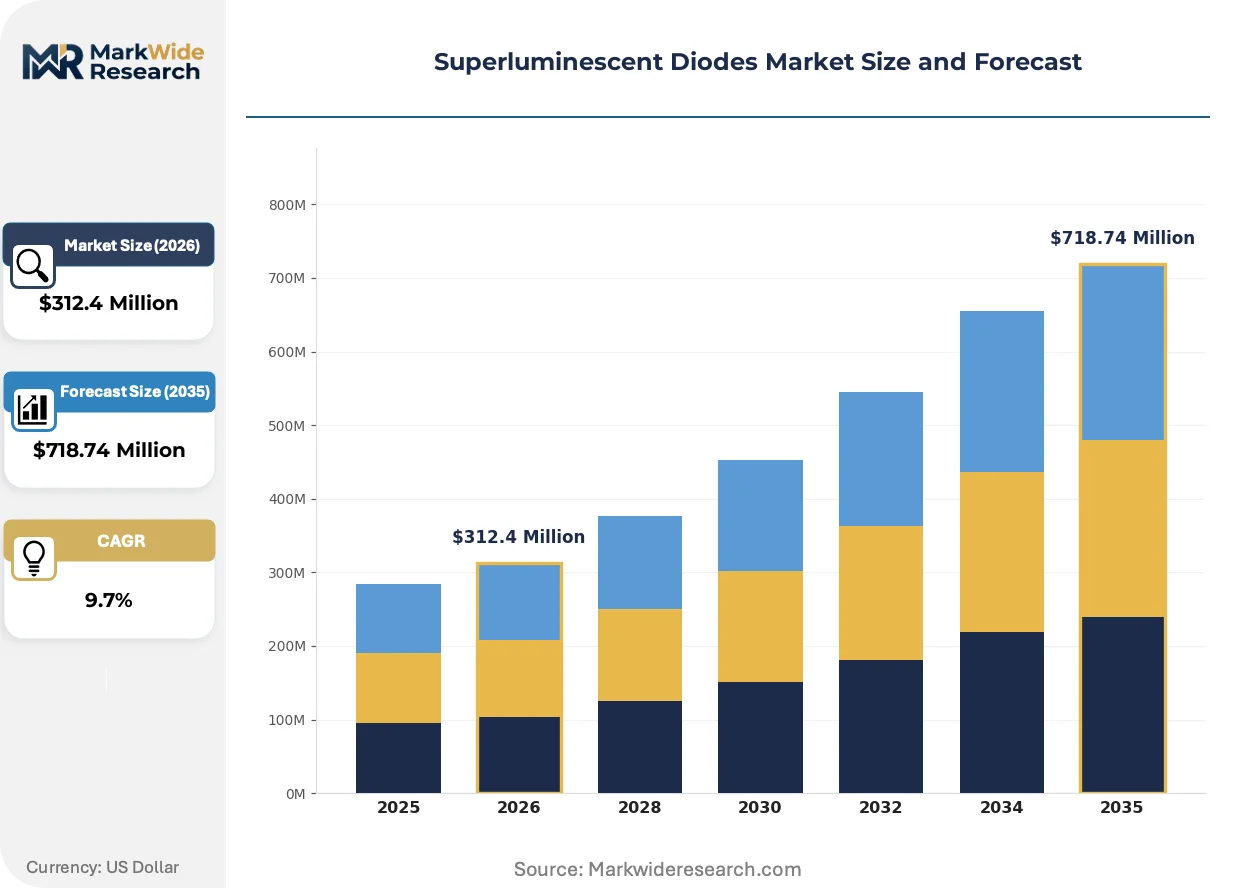
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broadband Light Source, High-Power Diodes, Low-Power Diodes, Specialty Diodes End User: Healthcare, Telecommunications, Automotive, Consumer Electronics Technology: Optical Fiber Communication, Medical Imaging, Sensors, Laser Interferometry Application: Medical Diagnostics, Fiber Optic Sensors, Industrial Automation, Research & Development |
| Companies Covered | Thorlabs Inc., Superlum Diodes Ltd., Exalos AG, QPhotonics LLC, Frankfurt Laser Company, InPhenix Inc., DenseLight Semiconductors Pte. Ltd., Anritsu Corporation, Innolume GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superluminescent Diodes Market Evolving Landscape
Waveguide integration and foundry service expansion are collapsing traditional boundaries between component suppliers and system integrators, enabling new entrants to bypass capital-intensive fabrication.
Chip-scale SLD modules with integrated thermoelectric coolers and monitor photodiodes are decentralizing optical bench assembly from specialized photonics houses to contract manufacturers with standard pick-and-place capability. Medical device OEMs in Baden-Württemberg are qualifying these subassemblies for OCT catheter production at twice the previous annual rate. The shift is compressing supplier tiers and eroding margin pools for discrete component distributors.
REACH substance restrictions on lead-based solders and cadmium-plated heat sinks are forcing redesigns of hermetic packages for implantable sensing applications. German component suppliers have shifted to gold-tin eutectic bonding and copper-molybdenum heat spreaders ahead of enforcement deadlines. Ophthalmic instrument manufacturers face the steepest compliance burden due to extended field service requirements.
Hospital procurement departments are consolidating optical component sourcing through group purchasing organizations that negotiate multi-year service agreements bundling devices, calibration, and replacement cycles. The model displaces spot purchasing of discrete diodes and favors vendors with regional field service presence. Bavarian clinic networks have pioneered this structure, with Swiss and Austrian hospital groups now adopting similar frameworks.
Superluminescent Diodes Market Segmentation
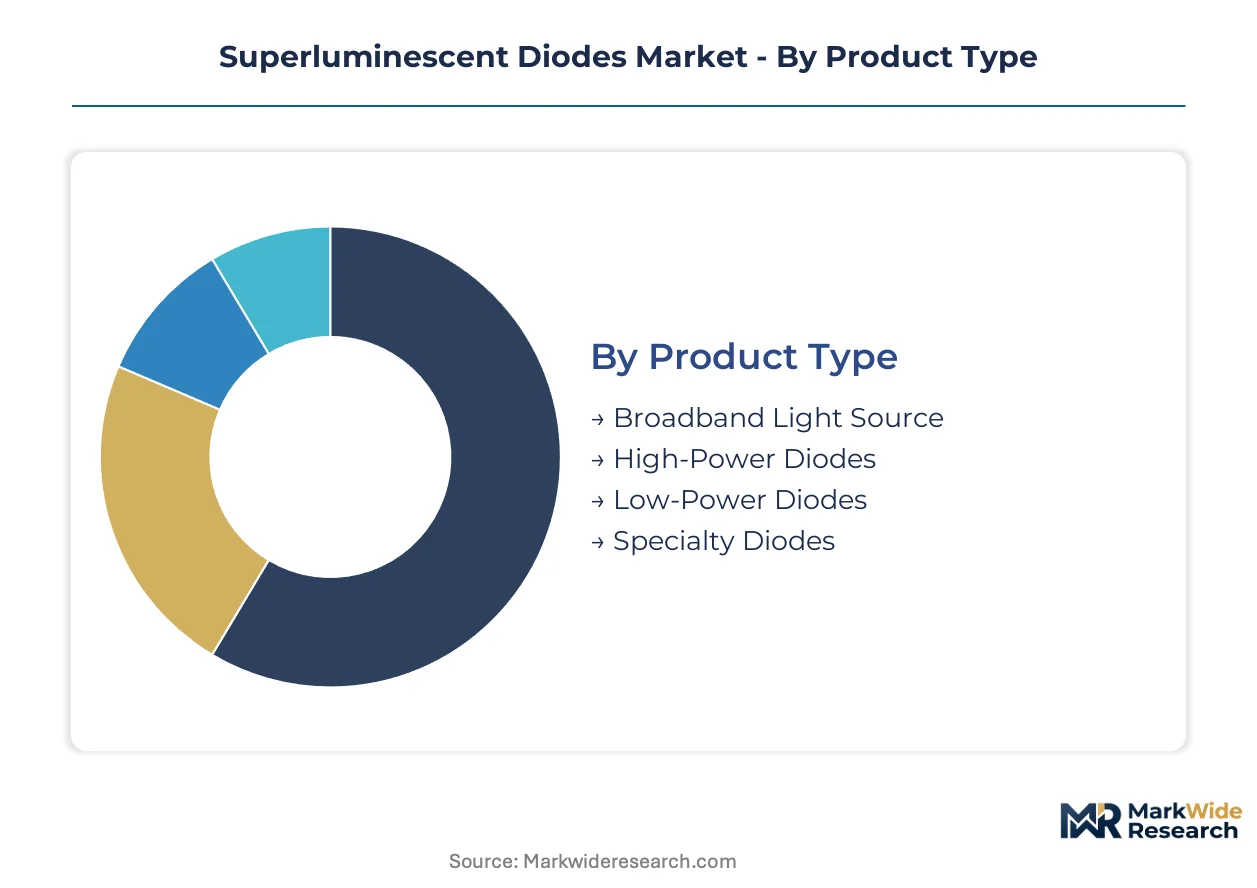
Segmentation in the superluminescent diodes market reveals how capital allocation, regulatory exposure, and application complexity create divergent margin structures across product tiers. Manufacturers must align wafer-level investments with specific end-use certification burdens.
Product Type:
Capital intensity varies sharply across product tiers, with epitaxial growth requirements and packaging complexity driving upfront investment thresholds.
- Broadband Light Source:These devices span 700–1700 nm with milliwatt-scale output, requiring precision gallium arsenide epitaxy and hermetic fiber pigtailing. Demand concentrates in German hospital networks upgrading optical coherence tomography platforms, where EU MDR traceability mandates favor suppliers with integrated metrology. The segment absorbs the highest share of cleanroom capital expenditure.
- High-Power Diodes:Output exceeding tens of milliwatts demands advanced thermal management and strain-engineered quantum wells. Industrial automation lines in Bavaria specify these units for high-speed inspection systems, though supercontinuum laser substitution threatens positioning above 100 mW.
- Low-Power Diodes:Compact emitters for consumer health wearables require minimal heat sinking.
- Specialty Diodes:Custom wavelength specifications serve niche spectroscopy applications.
Most installed capacity flows through broadband light sources. Expansion is steepest in high-power diodes.
End User:
Customer type determines pricing power, with regulated medical channels commanding premium terms against price-sensitive consumer segments.
- Healthcare:Hospitals and clinics drive volume through OCT equipment refresh cycles, with procurement consolidating through Bavarian group purchasing organizations that bundle devices, calibration, and replacement cycles.
- Telecommunications:Optical fiber communication infrastructure demands wavelength stability for dense wavelength division multiplexing.
- Automotive:Structural health monitoring systems in German bridge and tunnel programs specify broadband sources for distributed strain sensing.
- Consumer Electronics:Silicon photonics convergence enables wafer-scale packaging for health monitoring wearables, though margin compression is severe.
Healthcare commands the dominant revenue share. Consumer electronics is climbing the fastest.
Technology:
Technical maturity across application platforms shapes supplier qualification timelines and backward integration incentives.
- Optical Fiber Communication:Telecom-grade devices require precise center wavelength control for DWDM compatibility.
- Medical Imaging:Ophthalmic OCT systems in Swiss and Austrian hospital groups now adopt similar procurement frameworks to Bavarian networks, standardizing on chip-scale modules with integrated thermoelectric coolers.
- Sensors:Civil infrastructure monitoring in Germany and Switzerland drives specification of broadband emitters for fiber Bragg grating interrogation.
- Laser Interferometry:Precision measurement applications demand low coherence length and high spatial coherence.
Medical imaging carries the heaviest regulatory burden. Sensor deployment is gaining share fastest.
Application:
Application focus determines geographic concentration, with medical diagnostics anchored in European precision optics clusters and industrial automation spreading across manufacturing regions.
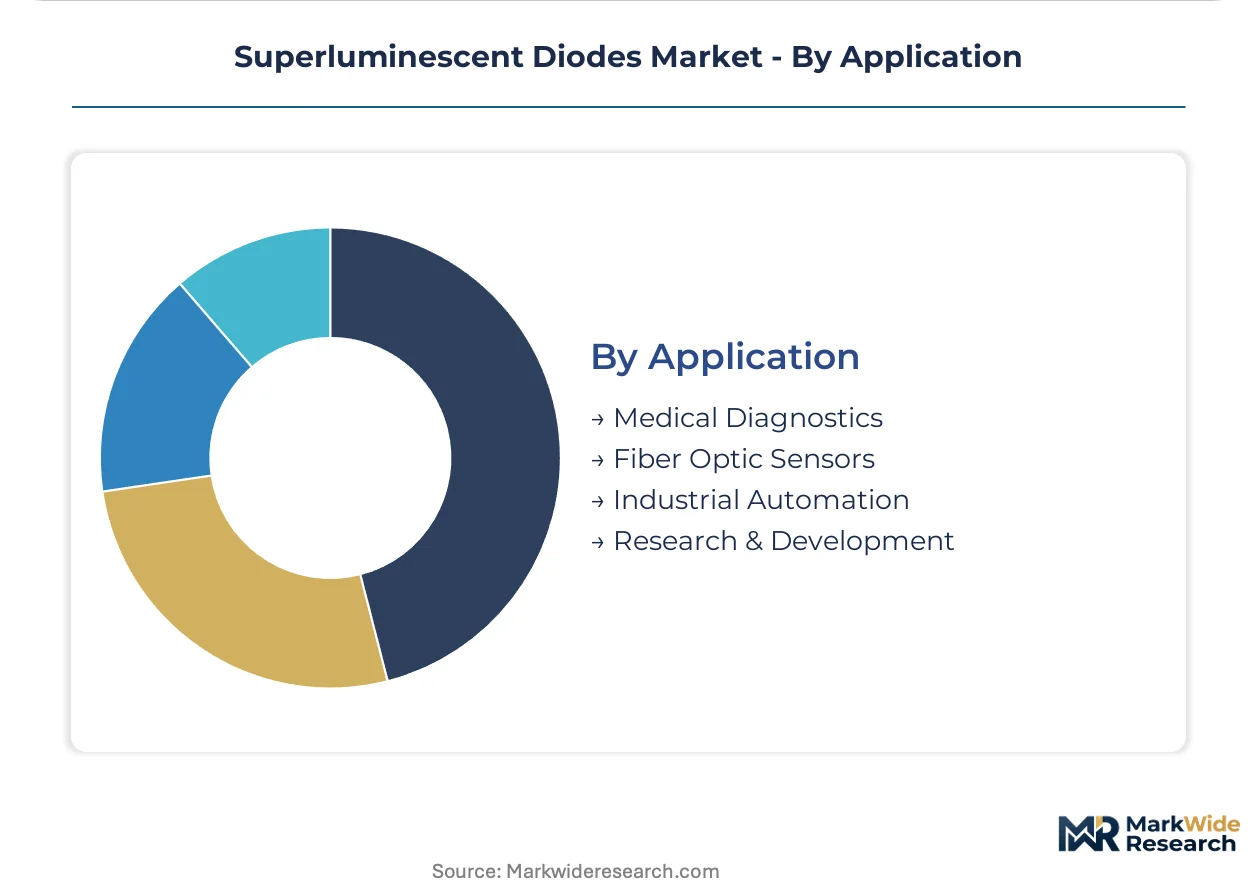
- Medical Diagnostics:Optical coherence tomography dominates hospital procurement, with Jena and Munich optics clusters supplying wafer-level expertise for custom wavelength development.
- Fiber Optic Sensors:Distributed sensing for civil infrastructure concentrates demand in German-speaking markets with active structural monitoring programs.
- Industrial Automation:Machine vision and inspection systems absorb high-power diode output.
- Research & Development:Laboratory instrumentation tolerates higher unit costs and longer lead times.
Medical diagnostics holds the largest installed base. Fiber optic sensors show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The superluminescent diodes industry traces its commercial roots to Soviet-era semiconductor research institutes in Moscow and Leningrad, where broadband emitter concepts first migrated to Western markets through German precision optics channels during the 1990s. This heritage explains why European medical device clusters still dominate high-specification sourcing.
Germany
Hospital networks in Bavaria and Baden-Württemberg drive procurement volume through group purchasing organizations bundling OCT equipment, calibration services, and replacement cycles. The EU MDR mandates traceable optical performance documentation for all photonic subcomponents, favoring suppliers with integrated metrology capabilities. Jena and Munich anchor precision optics clusters where wafer-level gallium arsenide expertise concentrates.
United States
The FDA enforces divergent biocompatibility and electromagnetic compatibility standards that shape product development cycles for medical device OEMs. Hospital procurement departments increasingly consolidate optical component sourcing through multi-year service agreements. Boston and San Francisco Bay Area photonics corridors house qualification laboratories serving domestic OCT manufacturers.
Switzerland
Swissmedic maintains stringent optical safety classifications that filter entry for non-specialized suppliers, particularly in ophthalmic instrument segments. Exalos AG exemplifies precision manufacturing anchored in wavelength stability for diagnostic applications. Zurich and Basel host medical technology headquarters specifying broadband light sources for next-generation imaging platforms.
China
The NMPA has accelerated review timelines for domestically manufactured photonic devices, redirecting foreign investment toward Shanghai and Suzhou production facilities. Structural health monitoring programs in Yangtze River Delta infrastructure projects specify fiber optic sensors with SLD illumination. Local foundry services are collapsing traditional boundaries between component suppliers and system integrators.
Japan
METI and PMDA optical safety classifications require separate certification tracks for ophthalmic versus industrial applications, extending time-to-market for broadband emitters. III-V semiconductor wafer supply concentrates among domestic ingot producers, exposing SLD manufacturers to allocation risk. Tokyo and Osaka anchor precision manufacturing clusters serving domestic medical device OEMs with specialized packaging requirements.
Superluminescent Diodes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification burden and epitaxial specialization tiers. The vendor base organizes into three strata: vertically integrated manufacturers with captive wafer growth, specialized packaging houses with hermetic sealing expertise, and fabless design firms leveraging foundry partnerships. Strategic moves concentrate on silicon photonics convergence for consumer health applications and direct hospital procurement channel development bypassing distributor networks.
Among European precision manufacturers, Thorlabs Inc., Superlum Diodes Ltd., and Exalos AG occupy positions exemplifying distinct competitive archetypes. Thorlabs represents vertically integrated manufacturing with metrology capabilities serving EU MDR documentation mandates. Superlum Diodes Ltd. anchors specialized gallium arsenide epitaxy expertise concentrated in Eastern European heritage facilities. Exalos AG sits within Swiss precision manufacturing tier focused on wavelength stability for ophthalmic instruments. These three firms illustrate how geographic clustering around regulatory expertise and materials specialization creates defendable positioning.
| Leading Market Players |
|---|
| Thorlabs Inc. |
| Superlum Diodes Ltd. |
| Exalos AG |
| QPhotonics LLC |
| Frankfurt Laser Company |
| InPhenix Inc. |
| DenseLight Semiconductors Pte. Ltd. |
| Anritsu Corporation |
| Innolume GmbH |
| Others |
Value Network & Pricing Analysis
Bavarian hospital group purchasing organizations concentrate procurement volume for optical coherence tomography equipment, enabling contract-based long-term offtake agreements that bundle devices, calibration, and replacement cycles. This buyer concentration forces tiered pricing stratification across premium certified, standard commercial, and economy unbranded tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with EU MDR certification grade and volume scale as primary price differentiation drivers. Pricing pressure stems from supercontinuum laser substitution in high-power spectroscopy applications above 100 milliwatts. Healthcare OEMs exhibit lowest price sensitivity due to regulatory compliance requirements, while consumer electronics wearables manufacturers face severe margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German ingot producers for III-V semiconductor wafers. Manufacturing concentrates in Germany, Japan, and China, with raw material dependencies on gallium arsenide substrates, hermetic packaging ceramics, and precision fiber pigtails. Tariff exposure on epitaxial equipment imports threatens cost structures. Distribution runs through specialized photonics distributors and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's NMPA-accelerated domestic manufacturing timelines and Europe's EU MDR documentation burdens, with cost differentials favoring Shanghai and Suzhou production facilities for standard-tier products.
For Market Incumbents: Extend metrology capabilities to capture EU MDR-mandated traceable optical performance documentation, consolidating captive demand from medical device OEMs. Deepen backward integration into gallium arsenide epitaxy to secure wafer allocation during capacity tightness. Counter supercontinuum laser substitution by developing hybrid silicon photonics platforms for consumer health wearables.
For New Entrants and Emerging Players: Mid-tier civil infrastructure monitoring programs in German-speaking markets represent underserved buyer archetypes with less stringent certification requirements than medical channels. Target fiber optic sensor deployments for bridge and tunnel distributed strain sensing. Enter through foundry partnerships offering chip-scale SLD modules with integrated thermoelectric coolers, bypassing capital-intensive fabrication.
For Investors and Strategic Acquirers: Medical device OEMs with captive photonics divisions are the most active acquirer in this space, seeking to internalize component supply for OCT platform roadmaps. Acquisition targets should display specialized gallium arsenide epitaxy capabilities or hermetic packaging expertise. Watch NMPA review timeline differentials between domestic and foreign manufacturing as inflection indicator for production relocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Convergence | Hybrid III-V integration with silicon nitride waveguides enables wafer-scale packaging for wearables. |
| Direct Hospital Procurement Channel Development | Bavarian clinic networks bypass distributors to negotiate volume contracts for OCT system spares. |
| EU MDR Metrology Capability Investment | Traceable optical performance documentation creates captive demand from medical device OEMs. |
| Gallium Arsenide Epitaxy Backward Integration | Captive wafer growth secures supply allocation during Japanese and German ingot tightness. |
| China NMPA Domestic Manufacturing Footprint | Accelerated review timelines for Shanghai and Suzhou facilities redirect foreign investment flows. |
Research Methodology
Coverage spans Germany, United States, Switzerland, China, and Japan, with primary inputs from each. The approach combines structured interviews with photonics component engineers, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at medical device OEMs. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and PMDA optical safety classification registers. Bottom-up segment sizing triangulates against top-down industry expenditure estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, end user, technology platform, and application dimensions alongside regional regulatory cluster variations. CAGRs derive from segment-level growth rate synthesis. Forecast inputs incorporate EU MDR implementation pace, NMPA domestic manufacturing incentive intensity, and supercontinuum laser substitution thresholds in high-power spectroscopy.
Underlying measurement precision varies by segment; broadband light sources for established OCT platforms carry tighter precision than emerging consumer electronics applications. Forecasts reflect documented assumptions about regulatory harmonization progress and wafer supply allocation stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Single-Digit 7 Segment LED Displays Market
LED
Mini LED Market
LED
United States Micro LED Market
LED
LED and OLED Display Market
LED
Pixel Pitch LED Market
LED
LED Lighting Market
LED
Arrow LED Displays Market
LED
Philippines LED Market
LED
Four-Digit 7 Segment LED Displays Market
LED
7 Segment LED Displays Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
LED Services Market
LED
India Indoor LED Lighting Market
LED
East Africa LED Lighting Market
LED
Africa LED Lighting Market
LED
Middle East LED Lighting Market