
 High-Reliability Connectors Market | 2026-2036
High-Reliability Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
High-Reliability Connectors Market Foresight
Market Context
AS9100 qualification cycles for aerospace-grade interconnects is collapsing from twenty-four months to under fourteen months at several tier-one suppliers. TE Connectivity leverages captive metallurgy labs to sustain domestic certification throughput for U.S. defense primes. Amphenol anchors its position through backward integration into precision-machined contact systems for satellite payloads. HiRel Connectors specializes in hermetic sealing technologies that dominate nuclear and space-qualified connector niches.
Technical Definition and Segment Structure
High-reliability connectors are electromechanical interfaces engineered to maintain signal integrity across temperature extremes from minus sixty-five to plus two hundred degrees Celsius, with insulation resistance exceeding five thousand megohms and mating cycles rated above five hundred operations. These components serve mission-critical functions where connector failure risks system loss, including flight controls, patient monitors, and telecommunications backbone infrastructure. Circular connectors lead military-aerospace procurement volumes due to MIL-DTL-38999 specification adherence, while fiber optic connectors represent the fastest-expanding product category as data rates exceed twenty-five gigabits per second in defense and telecom routing. PCB connectors concentrate margin pools in high-density mezzanine configurations for radar signal processing boards, whereas panel mount installation types retain pricing power in ruggedized field equipment applications.
Regulatory Framework and Outlook
FAA airworthiness directives and EASA certification memoranda govern connector qualification paths for commercial aviation, while ITAR controls restrict technology transfer for defense-specific designs. REACH substance restrictions and EU RoHS recast directives compel material transitions away from cadmium plating and certain brominated flame retardants in thermoplastic housings. Stakeholders must monitor evolving MIL-STD-810H test revision timelines and dual-use export classification shifts that could restructure supplier eligibility for cross-border defense contracts.
Market Dynamics
Defense procurement cycles are compressing qualification timelines for AS9100-certified interconnects, forcing tier-one suppliers to collapse metallurgy validation and environmental testing into parallel workflows rather than sequential gates.
Growth Catalysts
- MIL-DTL-38999 specification adherence:NATO member states are expanding connector adoption for mission-critical avionics and radar systems, with circular connectors dominating military-aerospace procurement volumes.
- REACH and RoHS compliance requirements:European regulations are pushing manufacturers toward lead-free plating technologies and halogen-free thermoplastic housings, creating upgrade cycles across installed industrial bases.
- Data rate acceleration:Fiber optic connectors represent the fastest-expanding product category as defense and telecom routing requirements exceed twenty-five gigabits per second.
Market Restraints
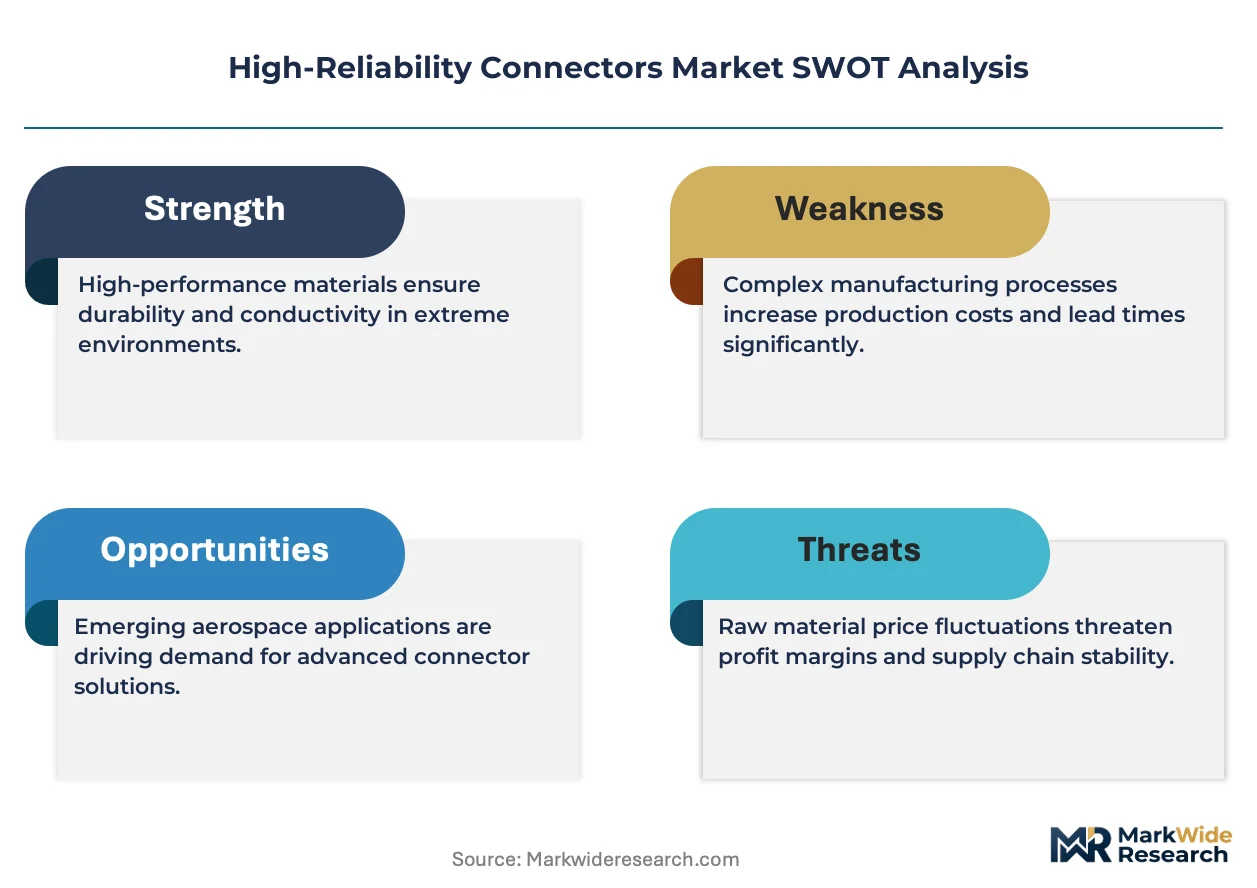
- Palladium-nickel alloy cost volatility:Contact plating materials face price swings tied to precious metal markets, compressing margin pools for mid-tier suppliers without captive metallurgy capabilities.
- German supplier concentration:Harting and other precision manufacturers anchor the industrial automation corridor, creating bottleneck risk for rail infrastructure and manufacturing equipment procurement.
- Hermetic sealing technical ceiling:Nuclear and space-qualified connector niches require vacuum-tight integrity that excludes lower-tier competitors from qualification paths.
Strategic Opportunities
- India industrial corridor expansion:BIS certification pathways for high-reliability interconnects remain underdeveloped relative to automotive electronics, creating first-mover positioning for aerospace-grade suppliers.
- Patient monitor connectivity:Medical device manufacturers are specifying MIL-grade circular connectors for portable diagnostic equipment where failure risks patient safety.
- EU Green Deal material mandates:Halogen-free thermoplastic housing requirements are accelerating substitution timelines for legacy cadmium-plated connector stocks across European defense maintenance depots.
Industry Challenges
- AS9100 certification timeline compression:Twenty-four month qualification cycles are collapsing to under fourteen months, straining environmental testing lab capacity and metallurgy documentation throughput.
- ITAR-controlled technology transfer:Dual-use export classification shifts are restructuring supplier eligibility for cross-border defense contracts, complicating multinational program participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Reliability Connectors Market |
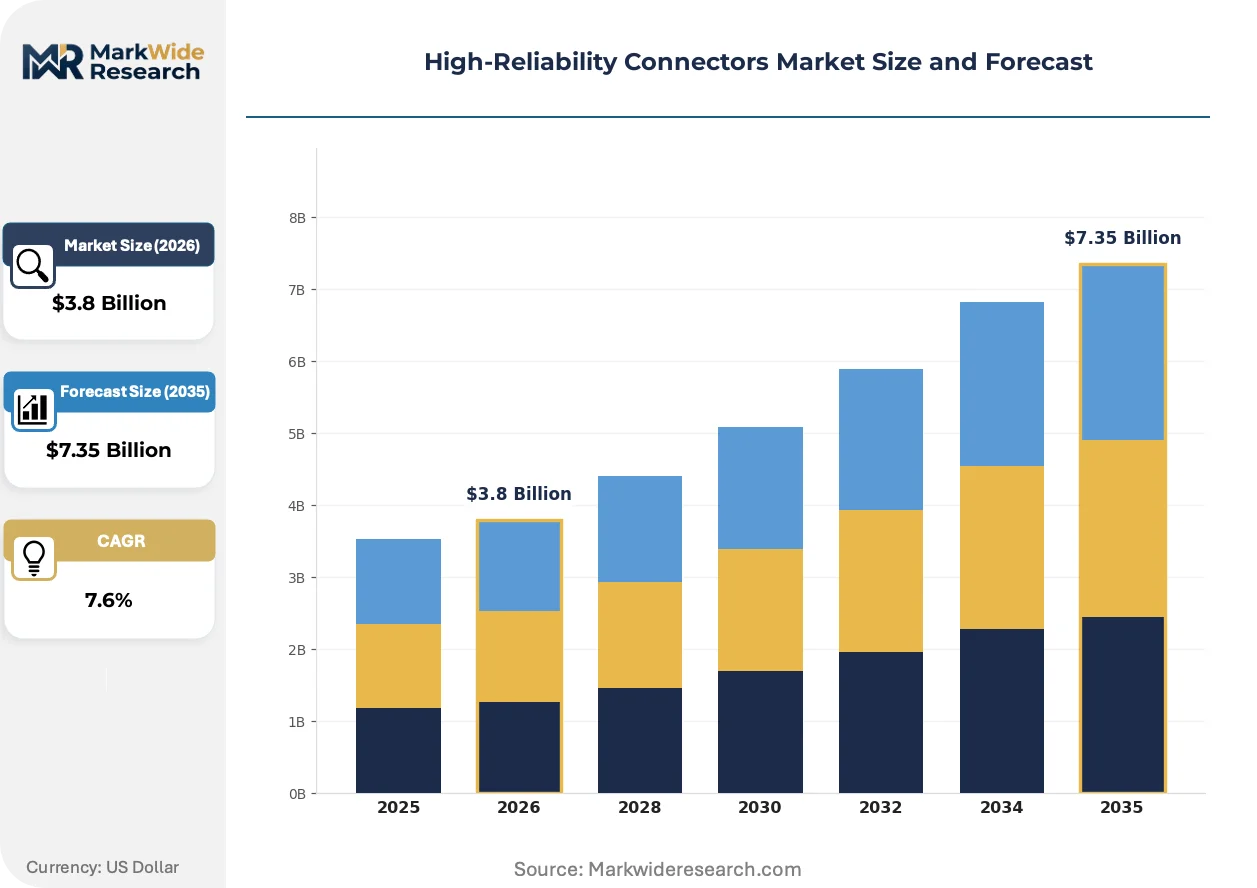
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Connectors, Rectangular Connectors, PCB Connectors, Fiber Optic Connectors Application: Aerospace, Defense, Telecommunications, Industrial Equipment Material: Stainless Steel, Aluminum Alloy, Thermoplastic, Copper Alloy Installation Type: Panel Mount, Inline, Surface Mount, Rack Mount |
| Companies Covered | HiRel Connectors, PEI-Genesis, Amphenol, ITT Cannon, Harting, TE Connectivity, Samtec, Glenair, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Reliability Connectors Market Shifts & Advancements
Signal integrity requirements at temperature extremes are driving material science investments across contact metallurgy and dielectric formulations, with performance differentiation increasingly concentrated in proprietary plating chemistries and thermoplastic compounds.
Miniaturized fiber optic interconnects are fragmenting traditional copper-dominant architectures in satellite payload applications. Constellation operators are specifying expanded-beam connectors for vibration-tolerant optical links. This technology is fragmenting procurement patterns away from legacy MIL-DTL-38999 circular formats toward hybrid electro-optical solutions.
EASA certification memoranda governing connector qualification paths for commercial aviation are tightening documentation requirements for flame retardant outgassing data. Manufacturers must submit augmented test reports under revised CS-25 airworthiness standards. Panel mount installation types in ruggedized field equipment face the steepest compliance cost increases.
Buyer consolidation among U.S. defense primes is compressing vendor approval cycles and unbundling after-sales service contracts from hardware procurement. Primes now negotiate connector maintenance separately from initial system integration. This pattern is most visible in radar signal processing board procurement where TE Connectivity and Amphenol compete on technical service responsiveness rather than unit pricing alone.
High-Reliability Connectors Market Segmentation
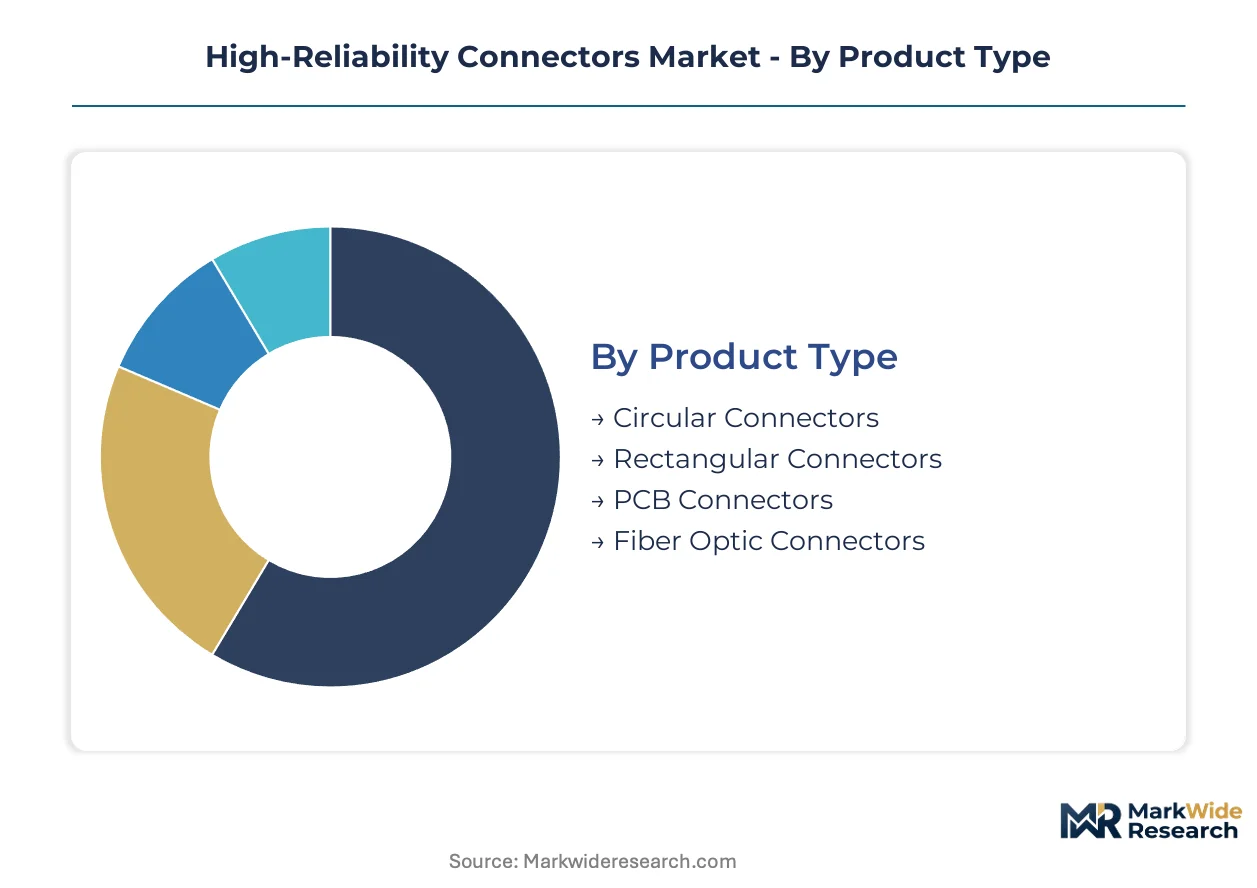
High-reliability connector procurement channels diverge sharply by performance tier. Military-aerospace buyers route through qualified supplier lists with AS9100 mandates, while industrial automation customers leverage distributor networks for faster turnaround on standard configurations.
Product Type:
Channel mix splits between defense primes sourcing MIL-spec circular formats direct from manufacturers, and telecom operators procuring fiber optic variants through systems integrators.
- Circular Connectors:MIL-DTL-38999 specification adherence defines mechanical and electrical performance for harsh-environment applications. NATO member states concentrate procurement volumes in Germany and the United States for mission-critical avionics and radar systems where specification compliance is non-negotiable.
- Fiber Optic Connectors:Expanded-beam and physical contact variants handle data rates exceeding twenty-five gigabits per second in defense routing and telecommunications backbone infrastructure. Satellite constellation operators in the United States and European Union are displacing copper architectures fastest in low-earth orbit payload applications.
- Rectangular Connectors:High-density pin configurations serve rack-mounted signal processing equipment with space-constrained interconnect requirements.
- PCB Connectors:Mezzanine and backplane formats concentrate in radar signal processing board procurement where density and signal integrity tradeoffs dominate.
By volume, circular connectors lead defense procurement. By growth pace, fiber optic variants are climbing the fastest.
Application:
Cost tier stratification separates aerospace-grade qualification costs from industrial equipment's price-sensitive volume purchasing.
- Aerospace:FAA airworthiness directives and EASA certification memoranda govern connector qualification paths for commercial aviation, with flame retardant outgassing documentation requirements tightening under revised CS-25 standards. Panel mount installations in ruggedized field equipment face the steepest compliance cost increases in Germany and France.
- Defense:ITAR controls restrict technology transfer for U.S.-specific designs, while NATO procurement programs expand connector adoption for mission-critical avionics across multiple member states. TE Connectivity and Amphenol compete on technical service responsiveness rather than unit pricing alone in radar signal processing board procurement.
- Telecommunications:Data center and routing infrastructure demand drives fiber optic connector specifications for twenty-five gigabits per second and beyond.
- Industrial Equipment:Germany's automation corridor anchors precision manufacturing and rail infrastructure needs where Harting and comparable suppliers serve established installed bases.
Aerospace commands premium pricing tiers. Defense procurement is expanding most quickly across NATO programs.
Material:
Margin concentration tracks material processing complexity, with hermetic sealing requirements in nuclear and space applications commanding specialized metallurgy capabilities.
- Copper Alloy:Palladium-nickel and gold plating chemistries on beryllium copper or phosphor bronze substrates deliver the contact resistance and wear characteristics required for five hundred-plus mating cycles. REACH and RoHS compliance requirements in Europe are pushing manufacturers toward lead-free plating technologies that alter cost structures.
- Thermoplastic:Halogen-free housing compounds substitute for legacy brominated flame retardants under EU Green Deal material mandates, accelerating replacement timelines across European defense maintenance depots.
- Stainless Steel:Corrosion-resistant shells and hardware withstand salt spray and chemical exposure in marine and offshore applications.
- Aluminum Alloy:Lightweight shell materials reduce mass in aerospace and satellite payload applications where every gram carries launch cost penalties.
Copper alloy contacts dominate by installed volume. Thermoplastic housings are gaining share fastest on regulatory substitution mandates.
Installation Type:
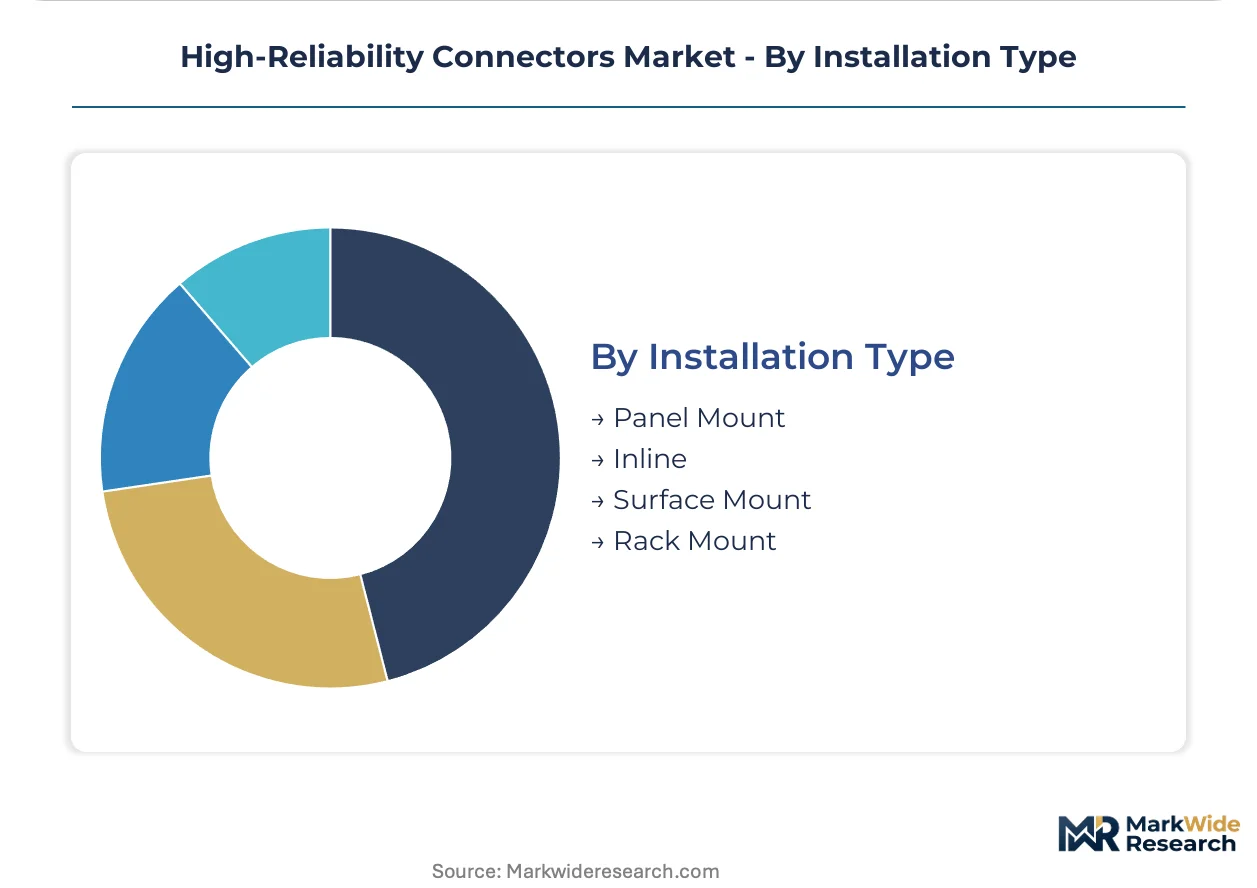
Customer type segmentation separates OEM system integrators specifying panel and rack formats from field maintenance operations requiring inline repairability.
- Panel Mount:Bulkhead-mounted receptacles with threaded coupling mechanisms provide environmental sealing for ruggedized field equipment in defense and industrial applications. EASA certification memoranda tightening flame retardant outgassing documentation requirements impose steepest compliance cost increases on this installation category.
- Rack Mount:Standardized 19-inch chassis integration supports high-density signal processing equipment in radar and telecommunications infrastructure where serviceability and cooling airflow compete for space.
- Inline:Cable-to-cable mating configurations enable field repair and modular system reconfiguration without panel disassembly.
- Surface Mount:PCB attachment without through-hole drilling supports miniaturized electronics packaging in space-constrained avionics and portable diagnostic equipment.
Panel mount leads by revenue concentration. Rack mount is expanding most quickly on data center and signal processing density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and ITAR export controls in the United States are accelerating qualification timelines for defense-grade interconnects, while REACH substance restrictions across Europe are forcing material transitions in established supplier bases.
United States
Defense procurement cycles for mission-critical avionics and radar systems are compressing AS9100 certification timelines from twenty-four months to under fourteen months. ITAR controls restrict technology transfer for U.S.-specific connector designs, restructuring supplier eligibility for cross-border NATO contracts. TE Connectivity leverages captive metallurgy labs in California and Texas to sustain domestic certification throughput for defense primes.
Germany
REACH and RoHS compliance requirements are pushing manufacturers toward lead-free plating technologies and halogen-free thermoplastic housings. Harting anchors the industrial automation corridor serving precision manufacturing and rail infrastructure needs. The country's central bank monitors supply chain disruptions affecting palladium-nickel alloy cost structures for mid-tier fabricators.
France
EASA certification memoranda are tightening documentation requirements for flame retardant outgassing data under revised CS-25 airworthiness standards. Panel mount installations in ruggedized field equipment face the steepest compliance cost increases. The Toulouse aerospace cluster concentrates procurement volumes for circular connectors adhering to MIL-DTL-38999 specifications.
India
BIS certification pathways for high-reliability interconnects remain underdeveloped relative to automotive electronics, creating first-mover positioning for aerospace-grade suppliers. The country's national standards body is drafting performance benchmarks for mission-critical electromechanical interfaces. The Bangalore-Telangana industrial corridor is attracting connector qualification investments from multinational defense contractors.
Japan
METI industrial policy is supporting domestic production of hermetic sealing technologies for nuclear and space-qualified connector niches. JIS standards govern material specifications for high-temperature applications spanning minus sixty-five to plus two hundred degrees Celsius. The Nagoya aerospace manufacturing belt concentrates demand for fiber optic connectors exceeding twenty-five gigabits per second in satellite payload applications.
High-Reliability Connectors Market Competitive Landscape
Listed leaders compete with private specialists across qualification capacity and metallurgy control. The vendor base clusters around three tiers: diversified electrical component conglomerates with captive certification infrastructure, precision-machining specialists with backward integration into contact systems, and niche hermetic sealing experts serving nuclear and space applications. Strategic moves concentrate on collapsing AS9100 validation timelines through parallel environmental testing workflows and securing dual-use export licenses for cross-border defense programs.
Among diversified electrical component conglomerates, TE Connectivity and Amphenol exemplify scale-driven archetypes with in-house metallurgy capabilities. HiRel Connectors occupies a specialist position within the hermetic sealing tier. These three anchors represent distinct competitive vectors: certification throughput speed, precision-machining integration depth, and vacuum-tight integrity technical ceilings.
| Leading Market Players |
|---|
| HiRel Connectors |
| PEI-Genesis |
| Amphenol |
| ITT Cannon |
| Harting |
| TE Connectivity |
| Samtec |
| Glenair |
| Molex |
| Others |
Supply & Pricing Matrix
Captive metallurgy lab capacity at tier-one suppliers compresses AS9100 certification timelines from twenty-four months to under fourteen months, concentrating pricing power among vertically integrated manufacturers while forcing mid-tier fabricators toward commodity contract manufacturing. Scale economies in environmental testing throughput allow TE Connectivity and Amphenol to sustain premium pricing for defense-grade circular connectors, whereas palladium-nickel alloy cost volatility erodes margin pools for suppliers without upstream plating control.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade AS9100-qualified interconnects and industrial-standard configurations. Three-tier pricing structure across mission-critical, commercial-grade, and maintenance-replacement levels tracks qualification investment and mating cycle ratings. Cost compression in mid-tier copper alloy contacts is intensifying because REACH-compliant lead-free plating chemistries alter material cost structures. Defense primes exhibit lowest price sensitivity due to ITAR-controlled sourcing constraints, while industrial automation buyers leverage distributor networks for volume discounts on standard configurations.
Supply Chain Analysis
Inventory lead times for hermetic sealing components stretch longest in nuclear and space-qualified connector niches where vacuum-tight integrity excludes rapid supplier qualification. Manufacturing concentrates in the United States, Germany, and Japan, with beryllium copper contact substrates, halogen-free thermoplastic housings, and precision-machined shell hardware anchoring input dependencies. Single-source vulnerability runs through palladium-nickel alloy suppliers serving European plating operations. Distribution runs through qualified supplier lists for military-aerospace procurement and authorized distributor networks for industrial automation customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent connector manufacturers face substitution pressure from fiber optic interconnects displacing copper-dominant architectures in satellite payload applications, requiring defensive positioning around hybrid electro-optical qualification capacity.
For Market Incumbents: Secure captive metallurgy capabilities to compress AS9100 validation timelines and defend against fiber optic substitution in low-earth orbit applications. Expand parallel environmental testing workflows to sustain certification throughput as defense procurement cycles accelerate. Backward integration into precision-machined contact systems anchors margin retention against mid-tier price competition. For New Entrants and Emerging Players: After-sales service unbundling from hardware procurement creates entry space for technical responsiveness specialists in radar signal processing board segments. Target India's underdeveloped BIS certification pathways for aerospace-grade interconnects where first-mover positioning remains available. Pursue qualification partnerships with multinational defense contractors establishing presence in the Bangalore-Telangana industrial corridor. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hermetic sealing specialists serving nuclear and space-qualified connector niches with decade-long maintenance contracts. Long-term viability hinges on dual-use export license portfolios enabling cross-border NATO program participation. Watch ITAR classification shifts as inflection indicators for supplier eligibility restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Acceleration | Parallel testing workflows collapse qualification timelines for defense prime vendor approval. |
| Hermetic Sealing Capability Buildout | Vacuum-tight integrity expertise captures nuclear and space-qualified connector maintenance contracts. |
| Fiber Optic Hybrid Integration | Expanded-beam connector development addresses satellite constellation vibration-tolerant optical link demand. |
| REACH-Compliant Material Transition | Lead-free plating and halogen-free housing substitution secures European defense depot upgrade cycles. |
| India BIS Qualification Investment | Early certification pathway development captures industrial corridor expansion in aerospace manufacturing. |
Research Methodology
Desk research of MIL-STD-810H test revision timelines, EASA certification memoranda, and defense procurement databases preceded structured interviews with connector program managers at tier-one suppliers, metallurgy lab directors, and procurement leads at U.S. defense primes. Primary fieldwork with Harting's industrial automation corridor distributors and TE Connectivity's certification engineers validated secondary findings from FAA airworthiness directives and REACH substance restriction filings. Bottom-up segment sizing across circular, fiber optic, and PCB connector formats triangulated against top-down defense and aerospace procurement budget allocations.
Variance decomposition across product type, application, material, and installation type dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level shipment volumes and average selling price trajectories incorporated palladium-nickel alloy cost volatility assumptions and AS9100 certification timeline compression rates. Industry-specific inputs included ITAR-controlled technology transfer restrictions and EU Green Deal material mandate implementation schedules.
Underlying assumptions cover sustained NATO defense procurement expansion and REACH recast directive enforcement timelines, with deviation risk concentrated in dual-use export classification shifts and precious metal market volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Filtered Connectors Market
Connectors
Heavy-Duty Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
Circular Connectors Market
Connectors
USB Type-C Market
Connectors
Line Clamp Market
Connectors
Middle East Connector Market
Connectors
Magnetic Connector Market
Connectors
Connector Kits Market
Connectors
Connector Market
Connectors
Automotive Data Connectors Market
Connectors
Relay Sockets Market
Connectors
SATA Connector Market
Connectors
Smart Crimper Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Connector for PV System Market