
 Laser Cutting Machines Market | 2026-2036
Laser Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Cutting Machines Market Intelligence
Aftermarket services and software subscriptions are tilting the profit pool away from one-time hardware sales. Major equipment manufacturers are now focusing on recurring revenue streams from maintenance, upgrades, and digital solutions for industrial IoT integration. Trumpf leverages its technology leadership to offer integrated automation and software packages. Bystronic differentiates through its focus on sheet metal processing solutions for European fabricators, while Hanslaser dominates the Chinese market with its extensive production scale.
A laser cutting machine directs a high-power laser beam through optics to precisely cut or engrave materials. The process utilizes a focused beam, often with an assist gas like nitrogen or oxygen, to melt, burn, or vaporize the material along a programmed path for automated fabrication. Fiber laser systems are displacing older CO2 laser technologies due to superior speed and efficiency on metals. While sheet metal fabrication remains the largest application, electronics manufacturing is a high-growth area due to miniaturization trends.
Compliance with machine safety and electrical standards, such as CE marking in Europe and GB standards in China, is mandatory for market access. Workplace safety regulations, enforced by bodies like the US Occupational Safety and Health Administration (OSHA), dictate system design features like fume extraction and light shielding. Stakeholders must now decide whether to invest in developing higher-wattage fiber lasers or focus on software-defined automation to maintain a competitive edge.
Market Dynamics
The market's central dynamic is the technological displacement of CO2 systems by high-power fiber lasers. This shift fundamentally alters application scopes, processing speeds, and cost structures for metal fabricators, driving new investment cycles across industrial manufacturing.
Growth Catalysts
- High-Power Fiber Lasers:Advancements enable faster processing of thicker metals, expanding applications in heavy industry such as shipbuilding and construction equipment manufacturing.
- Electronics Miniaturization:Demand for high-precision cutting of components for smartphones and semiconductors is escalating, particularly in Asian electronics hubs.
- Industrial Automation Incentives:Government support for Industry 4.0 in China and Germany encourages investment in automated laser cutting systems to boost factory productivity.
Market Restraints
- High Capital Outlay:The significant upfront investment for high-wattage fiber laser systems remains a major barrier for small and medium-sized metal fabricators.
- Component Sourcing:Reliance on a concentrated base of suppliers for critical optical components and high-power laser sources creates supply chain vulnerabilities and pricing pressure.
- Material Reflectivity:Processing highly reflective metals like copper and brass remains inefficient and can damage machine optics, limiting applications in battery manufacturing.
Strategic Opportunities
- Medical Device Manufacturing:The need for intricate, sterile cutting of materials like nitinol for stents and surgical tools presents a high-margin growth area.
- Hybrid Manufacturing Systems:Integrating laser cutting with additive manufacturing offers a new value proposition for rapid prototyping and complex part production in a single workflow.
- Southeast Asian Industrialization:Rapidly industrializing economies in Vietnam and Thailand offer new markets, particularly for automotive and electronics assembly.
Industry Challenges
- Skilled Operator Shortage:A lack of trained technicians to operate, program, and maintain advanced software-integrated systems creates an operational bottleneck for end-users.
- Divergent Compliance Standards:Manufacturers face hurdles ensuring machines comply with a patchwork of regional safety standards like Europe's CE marking and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Cutting Machines Market |
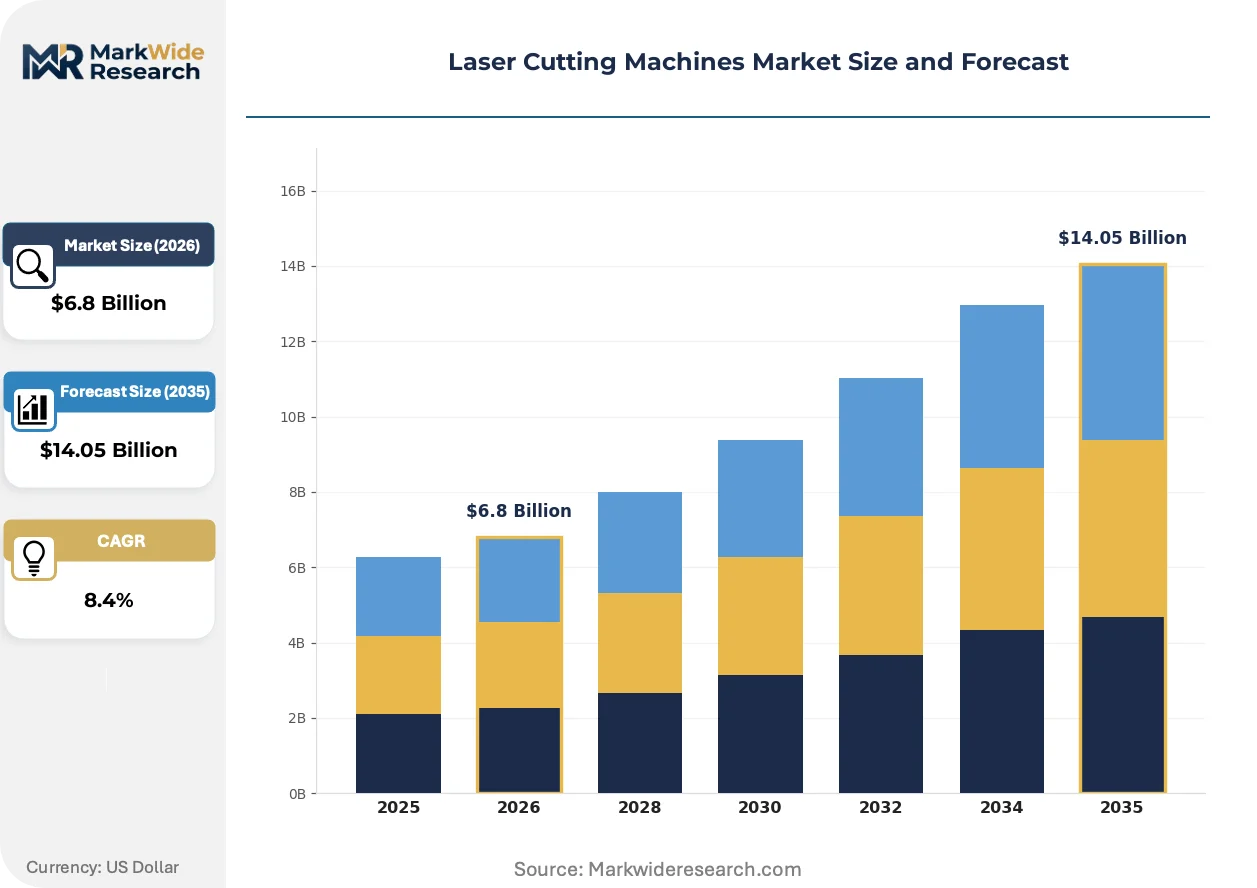
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Fiber Laser, Nd:YAG Laser, Diode Laser, Excimer Laser Technology: Gas Laser, Solid-State Laser, Semiconductor Laser, Free Electron Laser, Dye Laser Application: Sheet Metal Fabrication, Electronics Manufacturing, Jewelry Production, Woodworking, Textile Cutting End User: Metal Fabricators, Electronic Assemblers, Artisans, Furniture Makers, Apparel Manufacturers |
| Companies Covered | Trumpf, Bystronic, Hanslaser, HGTECH, Amada, Salvagnini, Mazak, IPG Photonics, Mitsubishi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Cutting Machines Market Strategic Shifts & Innovations
The market is defined by a dual push toward greater raw power and more intelligent automation. This tension between higher-wattage laser sources for speed and sophisticated software for precision is reshaping equipment capabilities and operational efficiency.
Digital twin software creates a virtual model of the laser cutting machine and its production process. Advanced manufacturers in aerospace and automotive are adopting this for process simulation. This technology is virtualizing offline programming and collision detection, reducing setup times and material waste before a physical cut.
Europe's updated Machinery Regulation places stricter requirements on the safety and cybersecurity of industrial control systems. This mandates that builders incorporate robust safety PLCs and secure remote access protocols. Equipment destined for the European market is most affected, forcing redesigns to meet CE marking criteria.
A shift away from one-time capital equipment purchases toward comprehensive service-level agreements is underway. This disrupts the traditional hardware-focused sales model, replacing it with recurring revenue tied to machine uptime and performance analytics. This trend is most visible among large industrial fabricators in North America and Europe.
Laser Cutting Machines Market Segmentation
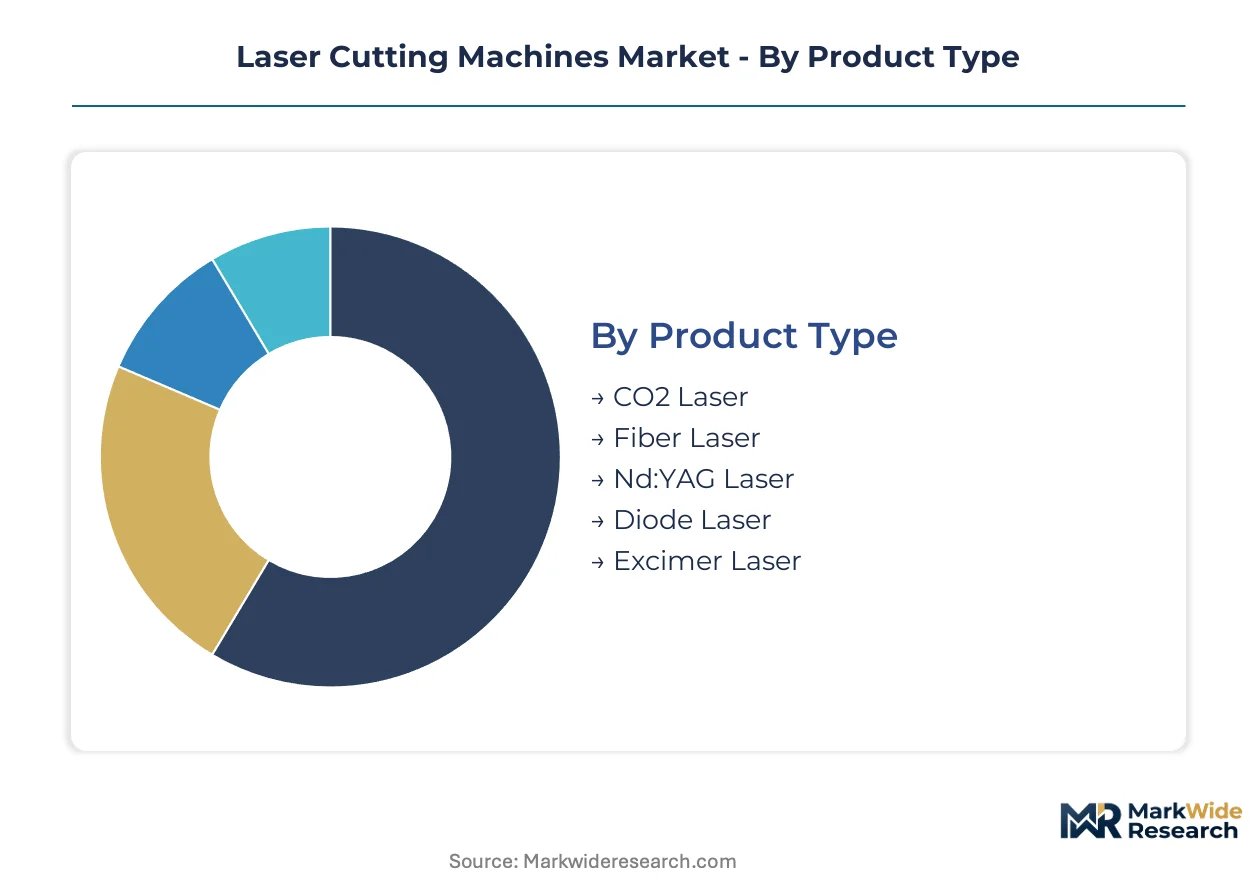
Market segmentation provides a critical framework for understanding the diverse needs and technological preferences across the laser cutting industry. Analyzing these distinct segments helps manufacturers tailor product development, pricing strategies, and market entry initiatives effectively. This granular view reveals specific opportunities and challenges within the broader market landscape.
Product Type:
The use-case spectrum for laser cutting machines dictates the primary product type chosen by end-users for specific material processing tasks.
- Fiber Laser:These systems utilize a solid-state gain medium doped with rare-earth elements, delivering high-power output and excellent beam quality. Demand is concentrating in electronics manufacturing and automotive production across China, driven by the need for faster processing of thinner and thicker metals.
- CO2 Laser:Employing a gas mixture as the active medium, CO2 lasers are versatile and well-suited for cutting non-metallic materials like wood, acrylic, and certain plastics. Established applications in general fabrication and signage continue to drive steady demand in European markets.
- Nd:YAG Laser:Neodymium-doped Yttrium Aluminum Garnet (Nd:YAG) lasers produce a shorter wavelength, making them effective for precision cutting and drilling of metals.
- Diode Laser:Semiconductor-based diode lasers offer compact designs and energy efficiency, finding niche applications in micro-processing and engraving.
- Excimer Laser:These gas lasers produce ultraviolet light, ideal for highly precise material ablation with minimal thermal impact, often used in medical device manufacturing.
Established volume favors CO2 Laser systems; emerging adoption favors Fiber Laser solutions.
Technology:
Cost tier considerations heavily influence the adoption of various laser technologies across different industrial budgets and operational scales.
- Solid-State Laser:This category includes fiber and Nd:YAG lasers, characterized by a solid gain medium that offers high efficiency, compact design, and superior beam quality. Solid-state technology represents the fastest-growing trajectory for laser cutting.
- Gas Laser:Gas lasers, such as CO2 and Excimer types, use a gas mixture as their active medium, providing high power for various materials, particularly non-metals.
- Semiconductor Laser:Also known as diode lasers, these are compact and energy-efficient, suitable for lower power applications and integration into smaller systems.
- Free Electron Laser:These advanced lasers generate high-power, tunable radiation from relativistic electron beams, primarily used in research and highly specialized applications.
- Dye Laser:Dye lasers utilize organic dyes as their gain medium, offering tunability across a broad spectrum but requiring more complex maintenance.
Solid-state technology represents the fastest-growing trajectory for laser cutting.
Application:
The volume of production and material characteristics largely define the suitable application areas for laser cutting systems.
- Sheet Metal Fabrication:This application involves cutting various metal sheets for industries like automotive, construction, and general manufacturing, demanding high-speed and precision. Demand for sheet metal fabrication is particularly strong in industrial clusters across Germany and Japan.
- Electronics Manufacturing:High-precision cutting of miniature components for printed circuit boards, displays, and semiconductor wafers is critical in this sector. Miniaturization trends in South Korea and Taiwan are propelling this segment.
- Jewelry Production:Laser cutting provides intricate designs and clean edges for precious metals and gemstones in the jewelry industry.
- Woodworking:This segment utilizes lasers for cutting, engraving, and marking wood products with high detail and speed.
- Textile Cutting:Lasers offer precise, fray-free cutting for various fabrics, especially in the apparel and technical textiles industries.
Sheet metal fabrication continues to drive the largest demand, while electronics manufacturing expands most quickly.
End User:
Customer type segmentation reveals distinct operational scales and technical requirements across different industrial users of laser cutting machines.
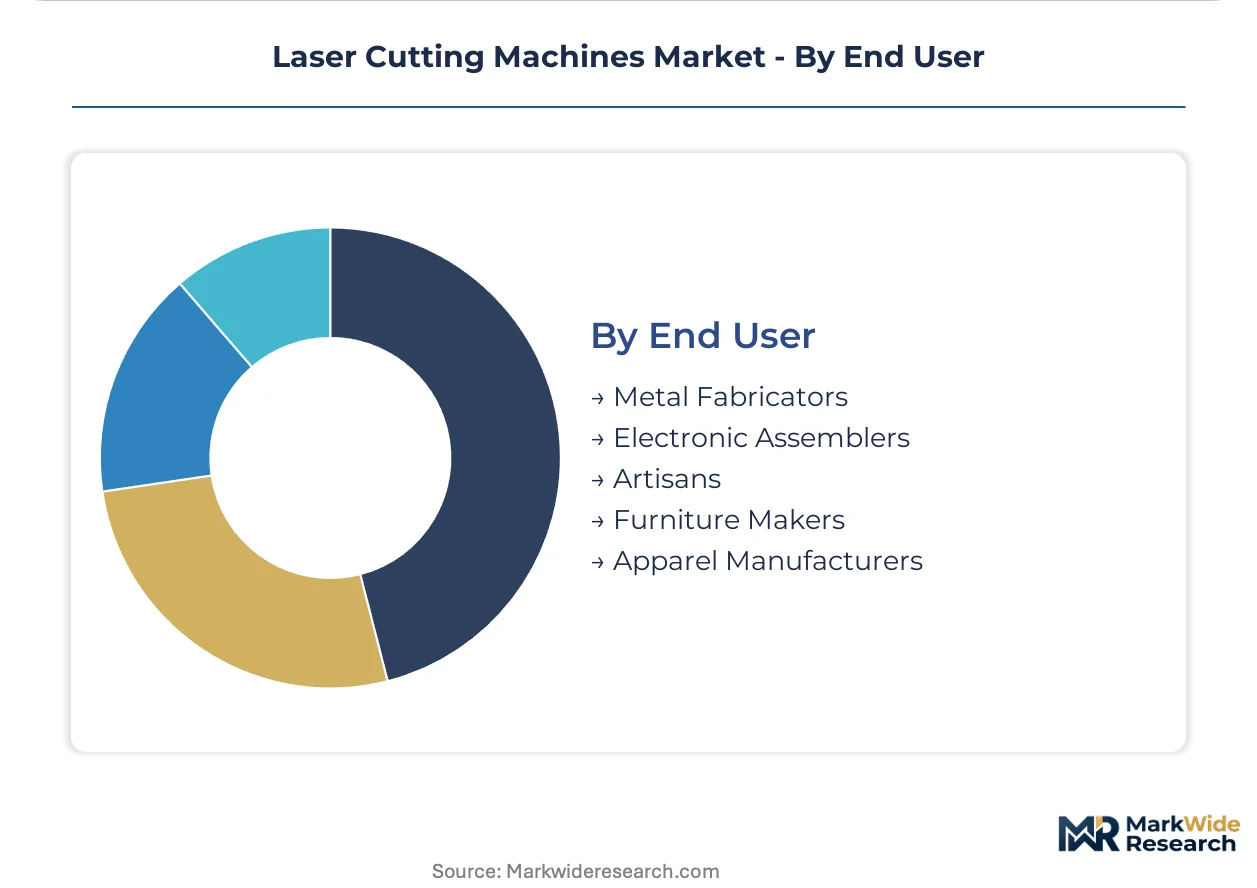
- Metal Fabricators:These users process various metal types and thicknesses for custom parts, structural components, and mass production, requiring robust and high-power systems. Metal fabricators in the United States and Canada are investing in higher-wattage fiber laser systems.
- Electronic Assemblers:Focused on precision cutting of small, delicate components for electronic devices, these users demand high accuracy and minimal material distortion. Electronic assemblers in Malaysia and Vietnam are expanding their capacity.
- Artisans:Individual craftspeople and small businesses use laser cutters for custom designs, prototyping, and small-batch production across various materials.
- Furniture Makers:This segment employs laser technology for cutting intricate shapes in wood, plastics, and composite materials for furniture components.
- Apparel Manufacturers:Textile and garment producers utilize lasers for precise cutting of patterns and materials, improving efficiency and reducing waste.
Metal fabricators remain the largest consumer group, with electronic assemblers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for laser cutting machines varies significantly across global markets. While established industrial economies prioritize high-performance, integrated systems, emerging economies often seek cost-effective solutions for initial industrialization. This differentiation influences product adoption and competitive strategies for manufacturers.
China
Demand for high-power fiber lasers is strong in China due to its vast automotive and electronics manufacturing sectors. Government incentives for Industry 4.0, along with GB standards, encourage investment in automated systems. Industrial clusters in the Yangtze River Delta are driving significant adoption for advanced fabrication processes.
Germany
Sheet metal fabrication continues to drive demand for versatile laser cutting systems in Germany. Compliance with CE marking and the updated Machinery Regulation mandates robust safety features for new equipment. Major automotive and machinery production hubs like Stuttgart and Munich are key areas for technological upgrades.
United States
Metal fabricators in the United States are investing in higher-wattage fiber laser systems to process thicker materials more efficiently. OSHA regulations enforce strict workplace safety standards, influencing system design for fume extraction and light shielding. The manufacturing belt in the Midwest sees substantial investment in advanced laser cutting for heavy industry.
South Korea
Electronics miniaturization trends are propelling demand for high-precision cutting of components in South Korea. The country's national industrial policies support advanced manufacturing technologies, fostering innovation in semiconductor and display production. Key technology hubs like Seoul and Gyeonggi Province are centers for adopting cutting-edge laser solutions.
Laser Cutting Machines Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the laser cutting machines market. The market structure exhibits a tiered consolidation, with a few global leaders offering integrated solutions and numerous regional specialists. Strategic archetypes include technology innovators, volume manufacturers, and niche application providers tailored to specific material or precision needs. Dominant competitive moves involve expanding geographic reach and integrating software-defined automation into product offerings.
Within the technology innovator tier, Trumpf leverages its German engineering heritage to offer integrated automation and software packages, exemplifying a premium solutions provider with a focus on advanced capabilities. Bystronic, a Swiss-based entity, occupies a position focused on comprehensive sheet metal processing solutions, particularly for European fabricators, emphasizing precision and efficiency. Hanslaser, a prominent Chinese manufacturer, anchors the high-volume segment with its extensive production scale, representing a significant player in the Asian market for cost-effective solutions.
| Leading Market Players |
|---|
| Trumpf |
| Bystronic |
| Hanslaser |
| HGTECH |
| Amada |
| Salvagnini |
| Mazak |
| IPG Photonics |
| Mitsubishi |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping routes, facing fluctuating fuel costs, directly influence the landed cost of laser cutting machines and critical optical components, subsequently shaping downstream price differentiation across regional markets.
Pricing Analysis
Aftermarket services and software subscriptions drive lifetime value for laser cutting machine manufacturers. Value-based pricing models dominate, reflecting advanced technology integration and comprehensive service bundles. Price differentiation stems from machine wattage and software capabilities, alongside geographic delivery costs. Pricing pressure stems from component sourcing vulnerabilities, impacting mid-tier manufacturers. Small and medium-sized fabricators exhibit the highest price sensitivity, while aerospace and medical device producers prioritize precision over cost.
Supply Chain Analysis
Single-source vulnerability for high-power laser sources creates a structural risk across the supply chain. Production of critical optical components concentrates in China, Japan, and Germany. Key dependencies include rare-earth elements and specialized optical crystals. Distribution runs through a network of direct sales channels, supported by regional distributors offering localized service. Logistics chokepoints, particularly in Southeast Asian ports, also introduce volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers fragmentation opportunities driven by the increasing demand for specialized material processing. Miniaturization trends in electronics manufacturing create distinct niches for high-precision laser cutting solutions.
For Market Incumbents:Insulate core market share by deepening software-defined automation and expanding comprehensive service-level agreements. Invest in R&D for higher-wattage fiber lasers to counter technological displacement from emerging solutions. Enhance compliance capabilities for CE marking and GB standards to mitigate regulatory threats. Control distribution channels to maintain market access.
For New Entrants and Emerging Players:Pursue white-space opportunities in medical device manufacturing, particularly for intricate nitinol cutting, and hybrid manufacturing systems. Target rapidly industrializing economies in Southeast Asia, such as Vietnam and Thailand, with cost-effective yet reliable fiber laser solutions. A go-to-market angle focused on niche application specialization and localized technical support offers a viable entry point.
For Investors and Strategic Acquirers:Europe's updated Machinery Regulation reshapes the acquisition landscape, emphasizing compliance and cybersecurity. Long-term viability hinges on companies with strong recurring revenue streams and proprietary software platforms. Target mid-cap specialists offering integrated automation solutions or niche application expertise. The signal to watch is the widespread adoption of comprehensive service-level agreements across industrial fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Integration | Enhances machine intelligence and offers recurring revenue streams for manufacturers. |
| High-Power Fiber Laser R&D | Extends application scope for thicker metals in heavy industry. |
| Geographic Expansion into Southeast Asia | Captures new demand from automotive and electronics assembly. |
| Service Model Transformation | Shifts revenue from one-time sales to performance-based contracts. |
| Compliance Certification Investment | Ensures market access in regulated economies like Europe and China. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary insights came from laser cutting machine manufacturers, metal fabricators, electronics assemblers, and optical component suppliers. Secondary validation utilized industry association reports, government manufacturing statistics, and technology journals. This approach enabled robust bottom-up and top-down triangulation of market data.
Forecast inputs considered the market's evolving technological landscape and shifting end-user requirements across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and regional adoption patterns. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key inputs included industrial automation investment and electronics production volumes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology innovators or high-volume manufacturers would shift outcomes. Forecasts reflect assumptions regarding technological advancements and market dynamics. Supply chain disruptions or changes in compliance standards represent key risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Static Crane Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Tower Crane Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Asia-Pacific Completion Equipment Market