
 2D Laser Cutting Machine Market | 2026-2036
2D Laser Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
2D Laser Cutting Machine Market Outlook
Automotive chassis fabrication is restructuring demand patterns across tier-one suppliers as OEMs consolidate multi-material cutting contracts. Trumpf leverages its captive supply of high-power fiber laser sources to dominate European automotive lines. Bystronic competes through software-integrated nesting optimization that reduces raw material scrap rates. Amada sustains manufacturing scale across Japanese and North American facilities, anchoring its position in high-volume sheet metal job shops.
A 2D laser cutting machine directs a focused coherent beam across flat workpiece surfaces to sever metals, polymers, or composites with kerf widths typically below 0.3 millimeters and positioning repeatability within micrometers. The equipment serves primary industrial purpose in precision blanking, hole piercing, and contour profiling for production volumes where die tooling costs prove prohibitive. Fiber laser systems now lead product type penetration due to wall-plug efficiency advantages and reduced maintenance cycles versus CO2 resonator architectures. Computer numerical control technology anchors the technology dimension through multi-axis interpolation that enables complex geometry execution without manual retooling. Metal cutting applications command the largest application share, though electronics-grade micro-cutting represents the fastest-growing margin pool.
EPA industrial emissions guidelines and EU F-Gas Regulation constrain CO2 laser refrigerant use and venting protocols, redirecting capital toward fiber and solid-state platforms that eliminate gas-dependent resonators. CE marking and ISO 11553 machinery safety standards govern beam enclosure interlocks and operator exposure limits, creating compliance cost differentiation between established OEMs and emerging entrants. Stakeholders must monitor wavelength-specific absorption characteristics as new alloy formulations in automotive and aerospace programs force recalibration of cutting parameter databases.
Market Dynamics
Fiber laser sources are systematically displacing CO2 resonator architectures across automotive and aerospace supply chains, compressing equipment replacement cycles and forcing tier-one fabricators to requalify entire parameter databases for high-strength alloy cutting.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants used in CO2 laser cooling systems is accelerating capital migration toward fiber platforms that operate without gas-dependent thermal management.
- Automotive chassis fabrication:OEM consolidation of multi-material cutting contracts is pulling demand toward systems capable of processing aluminum, high-strength steel, and polymer composites within single production cells.
- Wall-plug efficiency gains:Fiber laser architectures now deliver electrical-to-optical conversion rates exceeding thirty percent, slashing operating expenditures for high-volume job shops in Germany and China.
Market Restraints
- High-purity rare-earth dopants:Supply concentration of ytterbium fiber preforms among Chinese and Japanese suppliers creates input cost volatility for resonator manufacturers.
- CE marking compliance:Machinery safety standards under ISO 11553 mandate beam enclosure interlocks and exposure monitoring systems that add fifteen to twenty percent to equipment bill-of-materials for emerging entrants.
- Plasma cutting substitution:Thick-plate applications above twenty-five millimeters retain economic advantage for thermal cutting methods in shipbuilding and heavy structural fabrication.
Strategic Opportunities
- India:PLI scheme incentives for domestic machine tool manufacturing are opening localized assembly opportunities for mid-power fiber systems serving emerging automotive stamping clusters.
- Electronics-grade micro-cutting:Semiconductor substrate dicing and flexible circuit processing require sub-fifty-micron kerf widths that command premium pricing margins unavailable in commodity metal service centers.
- Cloud-native nesting software:Subscription-based CAD/CAM optimization platforms are displacing perpetual-license models, creating recurring revenue streams for equipment vendors.
Industry Challenges
- Laser safety officer certification:IEC 60825-1 compliance requires dedicated personnel training that extends commissioning timelines by four to six weeks for first-time adopters.
- Legacy CO2 asset stranding:Depreciated equipment with remaining useful life blocks replacement demand among price-sensitive job shops reluctant to absorb residual value losses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2D Laser Cutting Machine Market |
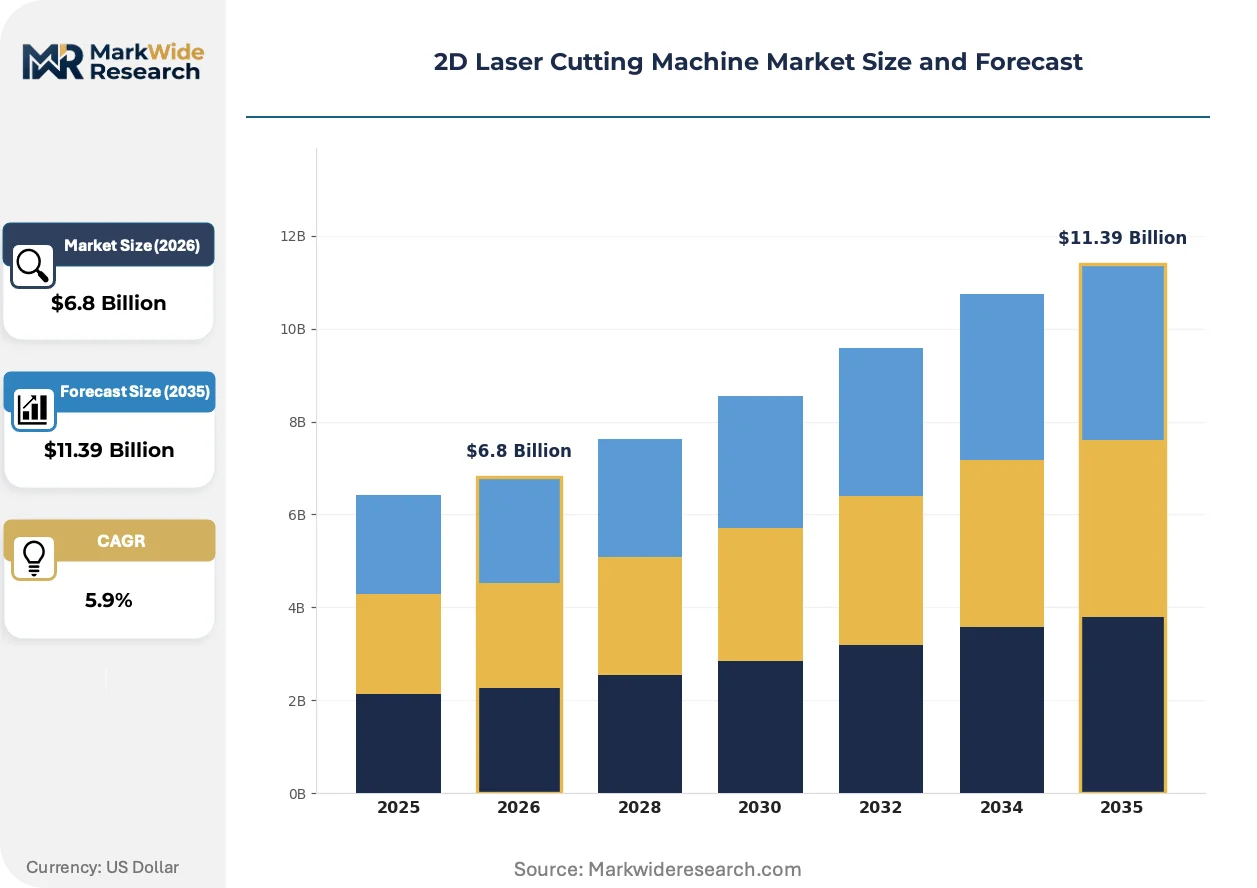
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Fiber Laser, Solid-State Laser, Ultrafast Laser Application: Metal Cutting, Wood Cutting, Textile Cutting, Plastic Cutting End User: Aerospace, Automotive, Electronics, Signage Technology: Computer Numerical Control, Manual Control, Hybrid Systems, Robotics |
| Companies Covered | Han's Laser, Prima Power, Trumpf, IPG Photonics, Coherent, Bystronic, Amada, LVD Company, Mazak Optonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2D Laser Cutting Machine Market Strategic Shifts
Beam delivery architectures and control software are converging to enable autonomous cutting parameter optimization, reducing operator intervention while tightening process windows for aerospace-qualified components.
Multi-kilowatt fiber laser engines with single-module outputs exceeding twelve kilowatts are rewriting productivity benchmarks for thick-section stainless and aluminum processing. Automotive exhaust system manufacturers in Stuttgart and Wolfsburg are adopting these sources to consolidate piercing and cutting operations that previously required staged power ramping. The technology is compressing cycle times by forty to sixty percent on nested chassis components, forcing competitors to match capital intensity or exit high-volume contract tiers.
EPA industrial emissions guidelines now restrict venting protocols for CO2 laser refrigerants and exhaust gases, compelling fabricators in Michigan and Ohio to install closed-loop thermal management systems. The regulation elevates compliance costs for legacy equipment operators while accelerating fiber platform adoption among tier-one suppliers serving Detroit OEMs. Metal service centers with diversified geographic footprints are prioritizing EPA-aligned equipment specifications to maintain eligibility for federal automotive supply chain incentives.
Machine-as-a-service contracts are displacing traditional equipment purchase models among mid-volume fabricators seeking to convert capital expenditure to operating expenditure. German and Japanese vendors now bundle preventive maintenance, consumables, and software updates into per-cut pricing structures. The shift is most visible in North American job shops where credit access constraints and cyclical order volatility favor predictable monthly outlays over lump-sum equipment investment.
2D Laser Cutting Machine Market Segmentation
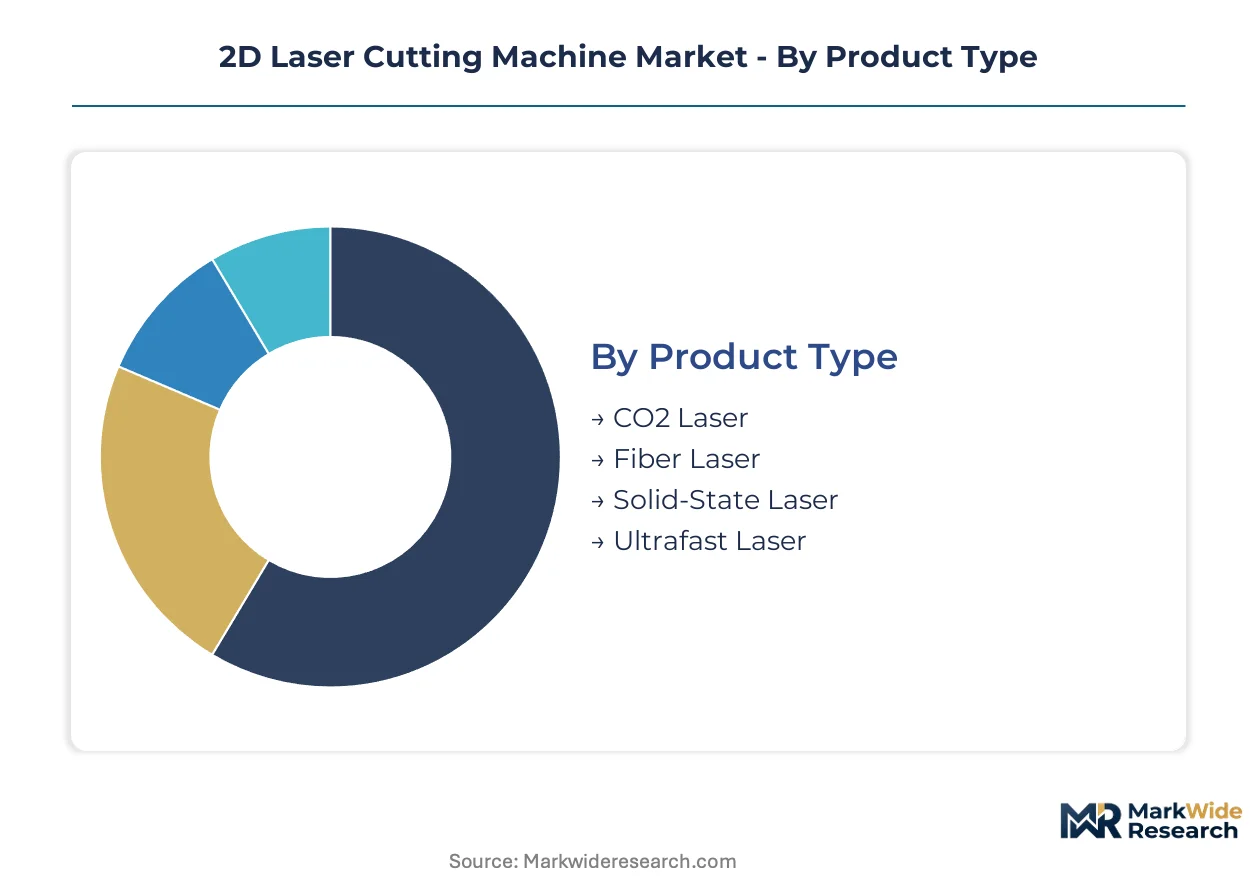
Equipment specification and regulatory alignment vary sharply across segment boundaries in the 2D laser cutting machine market. Buyers match product type to material portfolio, while end-use certification requirements dictate technology selection and compliance architecture.
Product Type:
CE marking under ISO 11553 and EPA emissions protocols impose divergent compliance burdens across laser architectures, with gas-dependent systems facing stricter thermal management and venting standards.
- Fiber Laser:Ytterbium-doped fiber amplifiers generate coherent output with wall-plug efficiency exceeding thirty percent and maintenance intervals measured in years rather than months. Automotive chassis fabricators in Germany and China are consolidating procurement around these platforms to satisfy EU F-Gas refrigerant phase-down mandates while reducing operating expenditure.
- CO2 Laser:Gas discharge resonators operating at 10.6 micrometers wavelength deliver superior edge quality on thick organic materials and coated metals. Tier-one suppliers retain these systems for specialized polymer and wood applications where absorption characteristics favor longer wavelengths, though EPA venting restrictions and F-Gas compliance costs are compressing replacement demand.
- Solid-State Laser:Diode-pumped Nd:YAG or Nd:YVO4 architectures provide nanosecond pulse formats for precision percussion drilling in aerospace turbine components.
- Ultrafast Laser:Femtosecond and picosecond pulse durations enable cold ablation of brittle semiconductors and medical devices without thermal diffusion zones.
Fiber laser sits at the top of the volume ranking, with ultrafast laser climbing the fastest.
Application:
Material-specific absorption spectra and kerf quality requirements create distinct margin tiers, with high-precision applications commanding premium pricing over commodity metal service work.
- Metal Cutting:Ferrous and non-ferrous alloys dominate equipment utilization, with high-strength steel and aluminum processing driving multi-kilowatt fiber laser adoption across automotive stamping clusters in Stuttgart, Wolfsburg, and Detroit. Parameter database requalification for new alloy formulations consumes significant engineering resources at tier-one fabricators.
- Electronics-grade Micro-cutting:Semiconductor substrate dicing and flexible circuit processing demand sub-fifty-micron kerf widths and positioning repeatability within single-digit micrometers. This application commands pricing premiums unavailable in commodity metal service centers, with specialized ultrafast systems penetrating printed circuit board manufacturing in South Korea and Taiwan.
- Wood Cutting:CO2 wavelength compatibility with cellulose absorption peaks sustains demand in furniture and architectural millwork sectors.
- Plastic Cutting:Polymer contouring requires wavelength selection matched to material absorption characteristics to prevent thermal degradation.
Metal cutting holds the largest installed base, though electronics-grade micro-cutting is gaining share fastest.
End User:
Industry-specific quality certification and traceability requirements shape equipment specification, with aerospace and medical applications imposing the most stringent process validation protocols.
- Automotive:OEM consolidation of multi-material cutting contracts is pulling demand toward systems capable of processing aluminum, high-strength steel, and polymer composites within single production cells. Chassis fabricators in Germany, the United States, and China are requalifying entire parameter databases as fiber laser platforms displace legacy CO2 assets.
- Electronics:Miniaturization trends in consumer devices and semiconductor packaging are expanding addressable demand for ultrafast and precision fiber systems. Flexible circuit manufacturers require sub-micron positioning accuracy and automated vision alignment for high-density interconnect processing.
- Aerospace:AS9100 quality management and NADCAP special process accreditation mandate extensive first-article inspection and process capability studies for flight-critical components.
- Signage:Decorative metal and acrylic cutting for commercial displays represents price-sensitive volume demand served by mid-power CO2 and fiber systems.
Automotive leads end-user demand by unit volume, with electronics expanding most quickly.
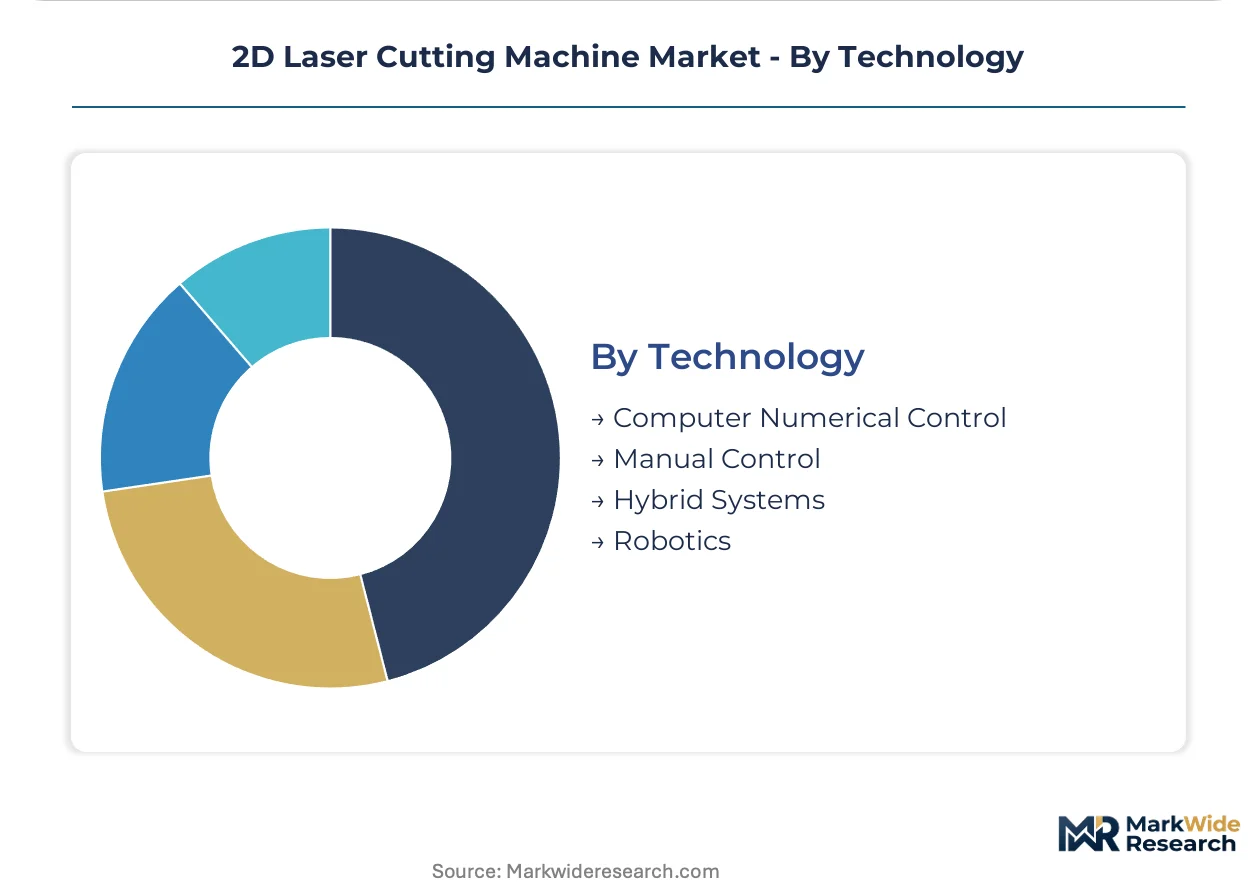
Technology:
Control architecture determines operator skill requirements, throughput consistency, and integration potential with upstream ERP and downstream automation systems.
- Computer Numerical Control:Multi-axis interpolation enables complex geometry execution without manual retooling, with real-time adaptive parameter adjustment based on capacitive height sensing and optical feedback. German and Japanese vendors dominate this segment through proprietary motion control algorithms and embedded safety interlocks compliant with IEC 60825-1.
- Robotics:Articulated arm and gantry-mounted laser heads extend processing envelopes beyond fixed-bed constraints, enabling three-dimensional cutting and welding integration within automotive body-in-white lines. Collaborative robot deployments are reducing fixture costs for low-volume aerospace prototyping.
- Manual Control:Limited to specialty job shops and educational installations where capital constraints override productivity requirements.
- Hybrid Systems:Combined laser and mechanical punching or waterjet modules offer process flexibility for diversified contract manufacturers.
Computer numerical control dominates technology deployment, with robotics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as fabricators migrate capital toward jurisdictions with favorable emissions enforcement timelines and domestic machine tool incentives.
Germany
Automotive chassis requalification for fiber laser platforms is absorbing capital across Stuttgart and Wolfsburg stamping clusters. EU F-Gas Regulation refrigerant phase-down mandates are accelerating CO2 asset retirement timelines. Bavarian and Baden-Württemberg job shops are consolidating multi-material cutting contracts under single-cell fiber systems.
China
Domestic machine tool capacity expansion is concentrating demand in Yangtze River Delta and Pearl River Delta manufacturing corridors. MEE industrial emissions protocols are tightening venting standards for legacy laser operations. Shenzhen and Suzhou fabricators are scaling ytterbium fiber preform supply chains to reduce resonator input cost volatility.
United States
EPA industrial emissions guidelines are redirecting tier-one supplier procurement toward closed-loop thermal management architectures. Michigan and Ohio metal service centers are requalifying parameter databases for high-strength alloy cutting. Detroit-area OEMs are consolidating multi-material contracts with fiber-capable fabricators.
India
PLI scheme incentives for domestic machine tool manufacturing are opening localized assembly opportunities for mid-power fiber systems. BIS machinery safety standards are elevating compliance costs for imported equipment. Maharashtra and Gujarat automotive stamping clusters are absorbing first-mover capacity from Japanese and German vendor partnerships.
Japan
JIS standards and METI energy efficiency guidelines are shaping equipment specification for export-oriented fabricators. Nagoya and Osaka job shops are maintaining CO2 systems for specialized polymer applications while adding fiber capacity for metal portfolios. Ytterbium fiber preform supply concentration among domestic suppliers is creating input cost advantages for resonator manufacturers.
2D Laser Cutting Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium positioning in automotive qualification tiers while independent fabricators compete on job shop turnaround velocity. Market structure concentrates around three strategic archetypes: captive-source laser engine suppliers, software-integrated nesting platform vendors, and scale-driven sheet metal service chains. M&A activity targets CAD/CAM software assets, while capacity expansion focuses on multi-kilowatt fiber module integration.
Among German-integrated fabricators, Trumpf and Bystronic exemplify divergent competitive vectors—one leveraging captive resonator supply, the other emphasizing software-embedded efficiency tools. Amada occupies a position bridging Japanese manufacturing scale with North American job shop penetration. These three anchors represent the premium-tier consolidation pattern visible across automotive supply chain procurement.
| Leading Market Players |
|---|
| Han's Laser |
| Prima Power |
| Trumpf |
| IPG Photonics |
| Coherent |
| Bystronic |
| Amada |
| LVD Company |
| Mazak Optonics |
| Others |
Value Chain & Pricing Dynamics
Ytterbium oxide price indices cascade through fiber laser resonator manufacturing, compressing margins at Chinese and Japanese preform suppliers while tier-one OEMs in Germany and the United States absorb cost pass-through via long-term offtake contracts. This raw material volatility stratifies equipment pricing across three performance tiers tied to wall-plug efficiency ratings and EU F-Gas compliance certification.
Pricing Analysis
Distributor margins on mid-power fiber systems range from twelve to eighteen percent, while direct-to-OEM contracts for automotive chassis lines command volume discounts that compress reseller economics. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-aerospace-certified platforms from CE-marked job shop units and uncertified emerging-market imports. Pricing pressure stems from Chinese domestic manufacturers scaling ytterbium fiber preform capacity in Shenzhen and Suzhou. Price-sensitive independent metal service centers in India and Southeast Asia drive demand for economy-tier equipment, while aerospace-qualified fabricators in Stuttgart and Detroit exhibit minimal sensitivity to premium positioning.
Supply Chain Analysis
Skilled laser optics technicians concentrate in Stuttgart, Nagoya, and Suzhou manufacturing corridors, constraining resonator assembly capacity expansion outside established clusters. Supply draws from ytterbium-doped fiber preforms in China and Japan, high-purity fused silica substrates in Germany, and precision motion control components from Switzerland and Taiwan. Single-source vulnerability sits with Chinese rare-earth processing concentration under MEE emissions protocols. Distribution runs through German and Japanese OEM direct sales forces for automotive tier-one accounts, with independent distributors serving fragmented job shop demand across North America and emerging Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber laser wall-plug efficiency gains above thirty percent are expanding premium-tier margins while compressing operating expenditure differentials that previously justified CO2 asset retention. This cost-down trajectory rewards incumbents with captive preform supply and punishes pure-play equipment assemblers exposed to input volatility.
For Market Incumbents: Acquire CAD/CAM software assets to bundle nesting optimization with equipment sales, converting perpetual licenses to recurring SaaS revenue. Acquire ytterbium fiber preform manufacturing capacity to secure resonator input cost stability against Chinese supply concentration. Plasma cutting substitution in thick-plate shipbuilding threatens fiber laser displacement above twenty-five millimeter applications; defend position by certifying multi-kilowatt single-module systems for aluminum hull processing under DNV maritime standards. For New Entrants and Emerging Players: Begin with electronics-grade micro-cutting applications in South Korea and Taiwan, where sub-fifty-micron kerf requirements command pricing premiums unavailable in commodity metal service. Begin with mid-power fiber system assembly under India's PLI scheme incentives, leveraging localized production to bypass BIS import compliance costs for Maharashtra and Gujarat automotive clusters. Cloud-native nesting software subscriptions offer the most penetrable entry vector, displacing perpetual-license incumbents through per-cut pricing models that convert capital expenditure to operating expenditure for credit-constrained job shops. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated resonator manufacturers possessing captive ytterbium preform supply and automotive OEM qualification status. Long-term viability across the projection horizon favors equipment vendors with software-embedded efficiency tools and machine-as-a-service contract portfolios. Target acquisition archetype: mid-cap fiber laser OEMs with established CE marking and nascent EPA compliance positioning for North American automotive supply chain eligibility. Signal to watch: tier-one fabricator requalification timelines for high-strength alloy parameter databases as fiber platforms displace legacy CO2 assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ytterbium Preform Supply | Captive resonator input sourcing neutralizes Chinese rare-earth price volatility for German and Japanese OEMs. |
| Cloud-Native Nesting Software Launch | Subscription CAD/CAM platforms displace perpetual licenses through per-cut pricing for North American job shops. |
| Machine-as-a-Service Contract Rollout | Preventive maintenance bundling converts capital expenditure to operating expenditure for cyclical fabricators. |
| Multi-Kilowatt Single-Module Certification | Twelve-kilowatt fiber engines qualify for automotive exhaust system consolidation in Stuttgart and Wolfsburg. |
| India PLI Scheme Manufacturing Partnership | Localized assembly bypasses BIS compliance costs for Maharashtra and Gujarat automotive stamping clusters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with laser system procurement directors at automotive tier-one suppliers, plant engineers at German and Chinese metal service centers, aftermarket service heads at Japanese OEM affiliates, and software product managers at nesting platform vendors. Secondary validation drew from SEC filings of listed machine tool manufacturers, EU F-Gas Regulation implementation reports, EPA industrial emissions enforcement databases, and customs trade data for ytterbium-doped fiber preform flows. Bottom-up equipment shipment tallies triangulated against top-down automotive stamping capacity expansion estimates across Stuttgart, Wolfsburg, Detroit, and Yangtze River Delta clusters.
Comparable historical reference periods anchored volume and value projections across the analysis window, with CAGR derivation reflecting segment-specific penetration curves for fiber laser displacement of CO2 architectures. Segmentation dimensions modeled include product type resonator architecture, application material portfolio, end-user industry certification tier, and technology control platform complexity. Industry-specific forecast inputs incorporated EU F-Gas refrigerant phase-down enforcement timelines and EPA closed-loop thermal management compliance cost trajectories for legacy equipment operators.
Several conditions sit outside the modeled scope, including abrupt rare-earth export restrictions under Chinese trade policy, unanticipated breakthroughs in solid-state or ultrafast laser cost-performance ratios, and automotive OEM insourcing decisions that eliminate tier-one fabricator equipment demand. Forecasts reflect assumptions regarding continued wall-plug efficiency improvement trajectories and stable regulatory enforcement timelines across German, Chinese, and American jurisdictions. Material deviation in ytterbium oxide price indices, EU F-Gas implementation acceleration, or tier-one supplier consolidation patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Diamond Hole Saw Market
Tools
Europe Machine Tools Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Stationary Wood Planer Market
Tools
Nut Runner Market
Tools
Collated Screws Market
Tools
Brazing Torch Market
Tools
Pneumatic Marking Machines Market
Tools
Indexable Inserts Market
Tools
Global Cordless Power Tools Market
Tools
Screw Fastener Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Shredder Blades Market
Tools
Europe Paint Spray Guns Market
Tools
Hand Tools and Woodworking Tools Market