
 Engine Driven Welders Market | 2026-2036
Engine Driven Welders Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Driven Welders Market Intelligence
The divergence between premium and commodity tiers in engine driven welders is hardening around fuel efficiency ratings, digital control interfaces, and emissions certification grades. The Lincoln Electric Company leverages extensive distribution networks to sustain aftermarket parts revenue across North American construction corridors. Miller Electric Mfg. LLC anchors its position through advanced inverter technology leadership in multi-process platforms. ESAB competes aggressively on price-performance ratios in emerging market infrastructure projects.
Engine driven welders are self-contained welding power sources integrating an internal combustion engine with a generator to produce welding current, typically delivering outputs from 150 to 600 amps for field operations without grid electricity. These units employ copper-wound alternators or inverter-based generator sets to transform mechanical energy into controlled DC or AC welding output suitable for stick, TIG, MIG, and flux-cored processes. Multi-process welders command the widest application flexibility and corresponding margin premiums across rental fleets and contractor equipment pools. Fuel injected technology segments are displacing carbureted architectures as EPA and EU emissions frameworks tighten particulate and NOx thresholds for non-road engines. Pipeline construction and oilfield maintenance applications concentrate demand in hydrocarbon-producing regions where grid access remains impractical.
EPA Tier 4 Final standards and the EU F-Gas Regulation shape engine architecture decisions and refrigerant choices in auxiliary cooling systems, directly influencing product development timelines and certification costs for manufacturers. OSHA welding fume exposure limits and ISO 15614 welding procedure standards further constrain equipment design and operator training requirements across industrial end users. Stakeholders must monitor evolving emissions compliance deadlines and electrification alternatives to preserve positioning in capital-intensive energy and infrastructure sectors.
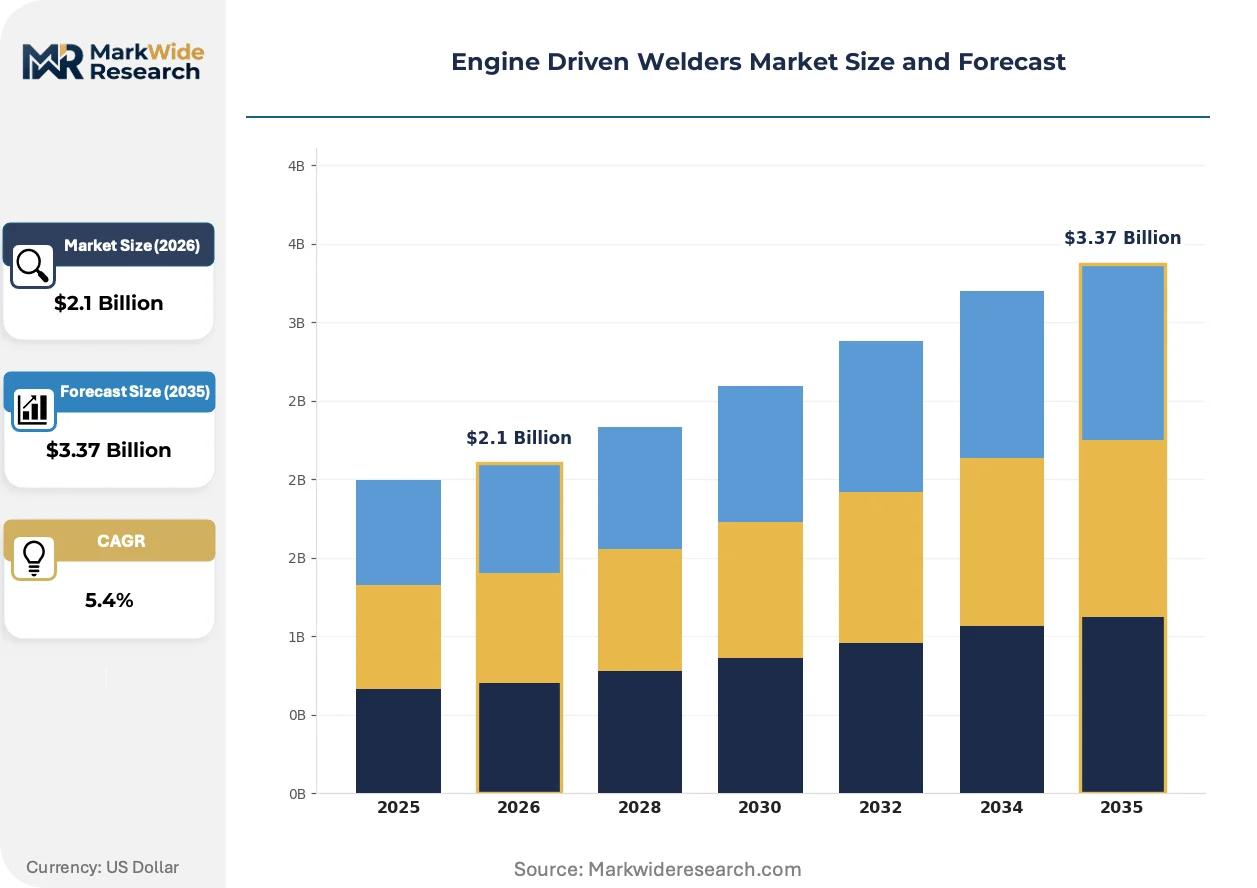
Market Dynamics
EPA Tier 4 Final emissions mandates are forcing fuel-injected architectures to displace carbureted engines across portable welding fleets, compressing product development cycles and raising certification barriers for smaller manufacturers.
Growth Catalysts
- Pipeline Construction Surge:Hydrocarbon infrastructure expansion across Permian Basin corridors and Gulf Coast shipyard clusters drives fleet procurement of multi-process units for remote field operations without grid access.
- EPA Tier 4 Final Compliance:Emissions standards accelerate manufacturer investment in fuel-injected engine architectures with electronic control modules that optimize combustion efficiency and reduce particulate output.
- Inverter Technology Maturation:Advanced IGBT-based power electronics enable lighter chassis designs and broader process compatibility, expanding rental fleet utilization rates across construction and maintenance contractors.
Market Restraints
- Copper and Steel Input Volatility:Alternator winding materials and chassis fabrication metals face commodity price swings that compress margin stability for equipment assemblers.
- Engine Supplier Concentration:Small-displacement industrial gasoline and diesel engine production concentrates among a limited set of powertrain specialists, creating supply bottleneck risks.
- Battery-Electric Substitution Threat:Grid-independent battery welding systems advance in duty-cycle capacity for light fabrication tasks, capturing share in urban construction where emissions restrictions tighten fastest.
Strategic Opportunities
- EU Green Deal Alignment:Renewable hydrogen infrastructure buildout creates demand for portable welding units in offshore wind foundation installation and electrolyzer fabrication sites.
- Rental Channel Digitization:Telematics-enabled fleet management platforms allow equipment lessors to monetize utilization data and predictive maintenance services alongside hourly rental rates.
- Dual-Fuel Engine Convergence:Propane-gasoline flex-fuel architectures address both EPA compliance and field fuel logistics flexibility for contractors operating in remote hydrocarbon production zones.
Industry Challenges
- Certified Welder Technician Scarcity:Multi-process equipment operation demands cross-trained technicians proficient in stick, TIG, MIG, and flux-cored procedures, constraining fleet deployment velocity.
- Emissions Certification Timeline Compression:EPA and EU F-Gas Regulation testing protocols extend product launch cycles by 12-18 months, delaying revenue recognition for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Driven Welders Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arc Welder, TIG Welder, MIG Welder, Multi-Process Welder, Spot Welder Technology: Hydraulic, Pneumatic, Fuel Injected, Carbureted, Pulse Weld Application: Heavy Fabrication, Shipbuilding, Pipeline Construction, Oilfield Maintenance, Agricultural Equipment Repair End User: Manufacturing Plants, Construction Companies, Energy Extraction Firms, Mining Operators, Maintenance Services |
| Companies Covered | The Lincoln Electric Company, Miller Electric Mfg. LLC, ESAB, Denyo Co Ltd., Multiquip Inc., Kemppi, Hobart Welding Products, Generac Power Systems, Wacker Neuson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Driven Welders Market Strategic Shifts & Innovations
Digital control interfaces and connected fleet management capabilities are redefining how contractors specify and operate portable welding assets in dispersed field environments.
Inverter-based generator sets is modularizing power conversion architectures, replacing traditional copper-wound alternators with silicon-based switching systems. Pipeline contractors and oilfield maintenance operators adopt these platforms for weight reduction and process flexibility. The technology is modularizing equipment design, allowing manufacturers to standardize chassis components across amperage ratings while customizing output characteristics through software configuration.
EU F-Gas Regulation refrigerant phase-down mandates are reshaping auxiliary cooling system choices for enclosed-cabinet welder-generator units. Manufacturers face reformulation costs for hydrofluorocarbon-based thermal management fluids while evaluating CO2 or hydrocarbon alternatives. European rental fleets and infrastructure contractors absorb compliance premiums most acutely, accelerating regional preference for air-cooled architectures where duty cycles permit.
Equipment-as-a-service contracting is displacing traditional capital purchase patterns among mid-sized construction enterprises. Rental companies and manufacturer captive finance arms capture recurring revenue streams through bundled maintenance and telematics monitoring. United States Permian Basin oilfield corridors exhibit this shift most prominently, where drilling cycle volatility discourages owned-fleet commitments.
Engine Driven Welders Market Segmentation
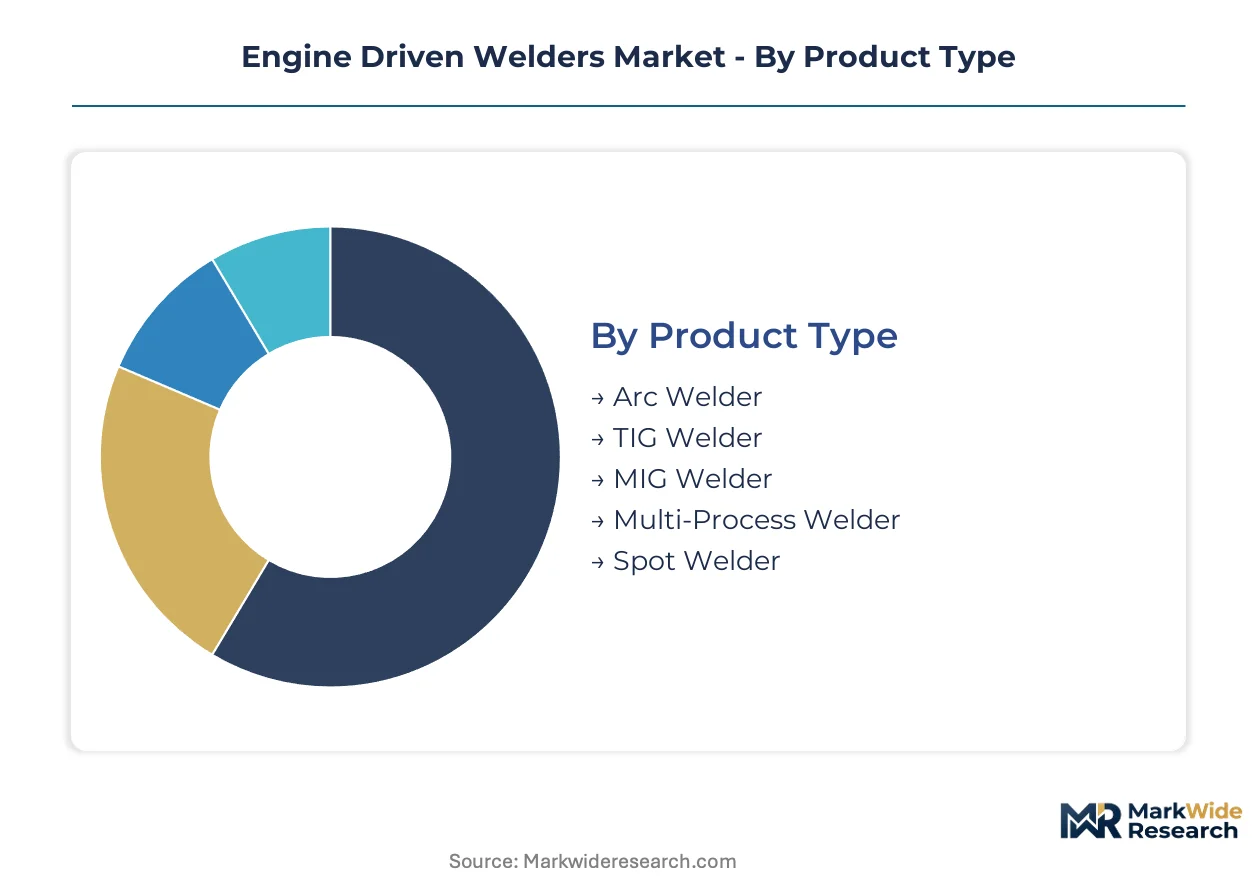
Segmentation in engine driven welders reflects divergent certification burdens across emissions frameworks, process technologies, and end-use environments. Equipment specifications must align with EPA Tier 4 Final, EU F-Gas Regulation, and ISO 15614 welding procedure standards depending on target deployment zones. Manufacturers configure product portfolios around these regulatory boundaries to optimize certification investments and geographic market access.
Product Type:
EPA Tier 4 Final compliance requirements concentrate most heavily on multi-process and high-amperage arc platforms, while smaller TIG and spot welding units navigate lighter certification loads under portable equipment exemptions.
- Arc Welder:Copper-wound alternator systems delivering 200-400 amp DC output dominate pipeline maintenance fleets. Demand clusters in Permian Basin oilfield corridors where stick welding remains the baseline process for structural repairs on drilling equipment.
- Multi-Process Welder:Inverter-based architectures with IGBT power electronics enable software-configurable output for stick, TIG, MIG, and flux-cored procedures. Gulf Coast shipyard contractors specify these units for fabrication flexibility across stainless hull sections and carbon steel superstructures.
- TIG Welder:Precision DC arc control suits aerospace component repair and stainless piping applications requiring low-spatter finishes.
- MIG Welder:Continuous wire feed systems accelerate production rates in heavy equipment manufacturing and structural steel erection.
- Spot Welder:Resistance welding configurations serve automotive panel repair and light fabrication tasks with limited field deployment.
Leading the category by volume: Arc Welder. Growing fastest: Multi-Process Welder.
Technology:
Cost tiers separate fuel-injected electronic control architectures from legacy carbureted systems, with pulse weld and hydraulic platforms occupying premium and niche positions respectively.
- Fuel Injected:Electronic control modules optimize combustion timing and air-fuel ratios to meet EPA Tier 4 Final particulate and NOx thresholds. Pipeline construction contractors in United States hydrocarbon corridors absorb price premiums for compliant fleet eligibility on federal and state infrastructure contracts.
- Carbureted:Mechanical fuel delivery systems persist in price-sensitive emerging market sales and secondary rental fleet rotations. Regulatory phase-out deadlines in California and EU member states compress remaining commercial windows for non-compliant inventory.
- Hydraulic:Engine-driven hydraulic power take-off units integrate with mobile equipment for welding operations on excavators and pipelayers.
- Pneumatic:Compressed-air actuated systems serve specialized underwater and explosive atmosphere applications requiring spark-free ignition.
- Pulse Weld:Advanced waveform control technology reduces heat input and distortion on thin-gauge materials in precision fabrication.
Highest margin tier: Fuel Injected. Fastest displacement trajectory: Carbureted.
Application:
Application segments diverge by duty cycle intensity, environmental exposure, and grid independence requirements, with oilfield and pipeline operations commanding the most specialized equipment specifications.
- Pipeline Construction:Multi-process 300-600 amp units with all-weather enclosures operate across remote terrain without electrical infrastructure. United States midstream expansion projects in Texas and Oklahoma drive fleet procurement for cross-country transmission line installation.
- Oilfield Maintenance:Portable 150-300 amp stick welders perform emergency repairs on drilling rigs, storage tanks, and flowline infrastructure. OSHA welding fume exposure limits mandate ventilation-equipped enclosures for confined space workovers.
- Heavy Fabrication:High-duty-cycle arc systems support bridge construction, pressure vessel manufacturing, and industrial equipment assembly.
- Shipbuilding:Multi-process platforms with stainless steel process libraries serve naval and commercial vessel construction at Gulf Coast and Great Lakes facilities.
- Agricultural Equipment Repair:Light-duty portable units address seasonal maintenance demands for tractors, harvesters, and irrigation systems in rural service territories.
Revenue concentration: Pipeline Construction. Steepest expansion trajectory: Oilfield Maintenance.
End User:
Customer type determines procurement volume, financing structure, and aftermarket service attachment rates, with energy extraction firms and construction companies representing contrasting commercial models.
- Construction Companies:Rental channel dependence and project-based procurement cycles favor telematics-equipped units with predictive maintenance contracts. United States infrastructure contractors increasingly specify equipment-as-a-service arrangements to match fleet capacity with bid pipeline volatility.
- Energy Extraction Firms:Captive maintenance departments in oil and gas operators prioritize ownership models with multi-year parts and service agreements. Permian Basin producers maintain dedicated welding fleets for continuous field repair operations.
- Manufacturing Plants:Fixed-position engine driven units provide backup welding capacity during grid outages and maintenance shutdowns.
- Mining Operators:Severe-duty enclosures and high-altitude engine calibration address open-pit and underground extraction environments.
- Maintenance Services:Independent repair contractors value portability and multi-process flexibility for diversified client portfolios.
Largest procurement volume: Construction Companies. Fastest service attachment growth: Energy Extraction Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin oilfield corridors spanning West Texas and southeastern New Mexico concentrate the highest procurement velocity for portable welding units, with pipeline construction contractors expanding fleets across hydrocarbon infrastructure buildouts.
United States
EPA Tier 4 Final emissions mandates accelerate fuel-injected engine adoption across Gulf Coast shipyard clusters and Permian Basin maintenance operations. OSHA welding fume exposure limits constrain equipment specifications for confined-space oilfield workovers. Houston-Galveston shipyard contractors specify multi-process platforms for naval and commercial vessel fabrication.
Germany
EU F-Gas Regulation refrigerant phase-downs reshape auxiliary cooling system choices for enclosed-cabinet welder-generator units deployed across industrial maintenance fleets. REACH compliance burdens concentrate product development resources at Baden-Württemberg fabrication technology centers. Ruhr Valley heavy equipment manufacturers integrate portable welding capacity into captive maintenance departments.
China
Dual carbon goals and MEE emissions frameworks tighten particulate thresholds for non-road engines in infrastructure construction zones. GB standards compliance separates domestic-market from export-oriented production lines. Yangtze River Delta shipbuilders and Sichuan-Chongqing pipeline contractors drive regional specification for multi-process inverter platforms.
Canada
Health Canada and PMRA oversight of industrial emissions parallels EPA trajectory, compressing commercial windows for carbureted engine inventories in Alberta oil sands maintenance operations. Provincial environmental regulations in British Columbia and Quebec accelerate rental fleet turnover toward compliant architectures. Calgary-based energy service companies expand welding fleet procurement for remote wellsite repair contracts.
Saudi Arabia
NEOM Northwest renewable hydrogen infrastructure buildout creates demand for portable welding units in electrolyzer fabrication and offshore wind foundation installation. The country's national environmental regulator tightens non-road engine emissions frameworks for construction equipment deployed across Red Sea coastal developments. Eastern Province Aramco maintenance contractors specify severe-duty enclosures for continuous field operations in high-temperature desert environments.
Engine Driven Welders Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent certification investment strategies. The market structure concentrates around three tiers: integrated powertrain manufacturers with captive engine supply, specialized welding equipment houses dependent on outsourced powertrain sourcing, and diversified industrial conglomerates with welding divisions. Strategic archetypes include emissions-technology leaders, rental-channel specialists, and emerging-market price competitors. Dominant competitive moves encompass dual-fuel engine platform development and telematics-enabled fleet management service bundling.
Among North American industrial equipment houses, The Lincoln Electric Company and Miller Electric Mfg. LLC exemplify the integrated technology leadership archetype, while ESAB represents the price-performance optimization tier serving infrastructure contractors across diverse geographic markets. These three anchors demonstrate how distribution network depth, inverter technology maturation, and regional pricing flexibility respectively define competitive positioning in capital-intensive energy and construction sectors.
| Leading Market Players |
|---|
| The Lincoln Electric Company |
| Miller Electric Mfg. LLC |
| ESAB |
| Denyo Co Ltd. |
| Multiquip Inc. |
| Kemppi |
| Hobart Welding Products |
| Generac Power Systems |
| Wacker Neuson |
| Others |
Cost & Logistics Intelligence
EPA Tier 4 Final emissions mandates gate qualified supply for premium-tier engine driven welders, restricting manufacturer participation to those with capital for electronic fuel injection certification and forcing price stratification around compliance grades. Carbureted architectures face compressed commercial windows in regulated jurisdictions, concentrating value capture among Tier 4-compliant producers serving federal infrastructure contractors.
Pricing Analysis
Outcome-based pricing anchored to equipment uptime guarantees dominates rental channel contracting, with telematics-enabled fleet management bundling predictive maintenance into hourly rate structures. Price differentiation separates EPA-certified multi-process platforms from carbureted spot-welding units, with Gulf Coast shipyard contractors absorbing premiums for emissions-compliant fleet eligibility. Cost compression in carbureted tiers intensifies because regulatory phase-out deadlines in California and EU member states strand non-compliant inventory. Energy extraction firms in Permian Basin corridors exhibit lowest price sensitivity due to captive maintenance requirements, while independent rental houses face margin pressure from equipment-as-a-service transitions.
Supply Chain Analysis
Freight cost volatility from Asian component sourcing compresses margins for North American equipment assemblers dependent on IGBT power electronics and precision engine control modules. Manufacturing concentration centers on the United States, China, and Germany, with copper-wound alternator production drawing from Chilean and Peruvian mining supply. Single-source vulnerability concentrates in small-displacement industrial engine supply from Japanese and European powertrain specialists. Distribution runs through manufacturer-direct construction equipment dealers and national rental house networks serving pipeline contractors across hydrocarbon corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
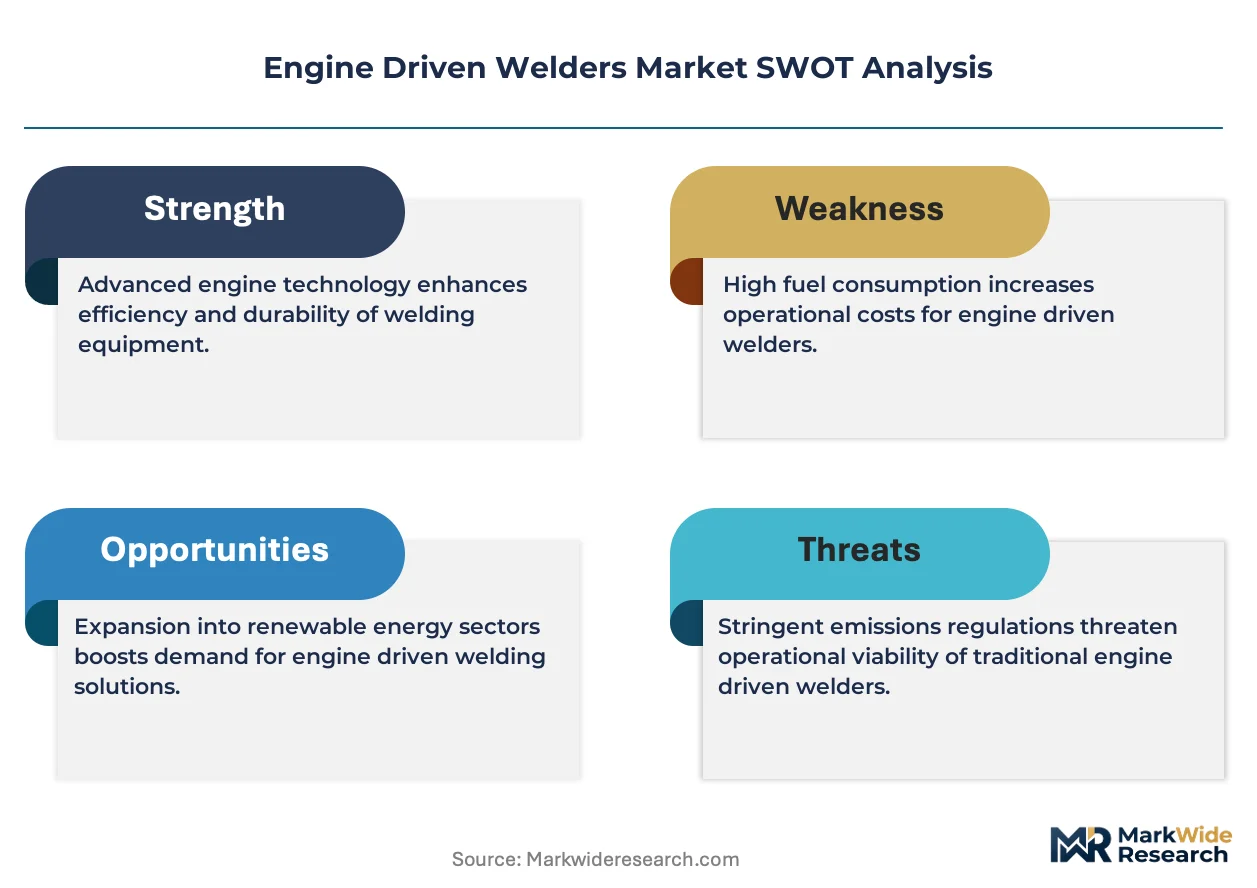
This market functions as a consolidation play where EPA and EU emissions certification burdens force smaller assemblers toward exit or acquisition by integrated powertrain manufacturers.
For Market Incumbents: To counter battery-electric substitution in urban construction zones, Lincoln Electric and Miller Electric must deepen backward integration into fuel-injected engine supply while expanding telematics service bundling to lock in rental channel loyalty. Certification investment in EU F-Gas-compliant cooling architectures preserves access to European renewable hydrogen infrastructure buildouts.
For New Entrants and Emerging Players: The mid-tier price gap between premium inverter platforms and economy carbureted units offers white-space entry for flex-fuel propane-gasoline architectures targeting remote oilfield maintenance. Saudi Aramco contractors and Alberta oil sands operators represent the most penetrable segment due to severe-duty requirements underserved by standardized product lines. Go-to-market execution should anchor on regional service partnerships with energy service companies rather than direct dealer competition.
For Investors and Strategic Acquirers: Rental fleet digitization adoption rates exceeding 40% across Permian Basin equipment pools is the leading indicator that equipment-as-a-service transitions will concentrate market share among telematics-capable producers. Long-term viability favors vertically integrated manufacturers with captive engine supply and aftermarket parts networks. Acquisition targets should emphasize regional welding equipment houses with established energy sector service relationships and pending Tier 4 certification completion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engine Platform Development | Propane-gasoline flexibility addresses EPA compliance and remote field logistics for Permian contractors. |
| Telematics Fleet Management Integration | Predictive maintenance contracts monetize utilization data beyond hourly rental rates for construction lessors. |
| EU F-Gas Cooling System Reformulation | CO2-based thermal management preserves market access as hydrofluorocarbon refrigerants face phase-down mandates. |
| Inverter Technology Modularization | IGBT platform standardization reduces chassis complexity while enabling software-configurable output customization. |
| Rental Channel Captive Finance Expansion | Manufacturer finance arms capture recurring revenue streams from mid-sized contractors avoiding owned-fleet commitments. |
Research Approach
Document review covered EPA certification filings, EU F-Gas Regulation compliance databases, and OSHA welding exposure standard updates, complemented by interviews with pipeline construction procurement directors, oilfield maintenance fleet managers, welding equipment rental channel heads, and industrial engine supplier technical leads. Secondary validation drew from customs trade data for copper alternator components, SEC equipment manufacturer disclosures, and energy sector capital expenditure tracking. Bottom-up equipment unit economics and top-down infrastructure investment flows were triangulated to establish market sizing.
Historical shipment data from United States, Germany, and China production clusters were cross-referenced against panel input from distributor inventory managers and rental fleet operators. Segmentation modeling spanned product type, fuel injection technology tier, application intensity, and end-user procurement structure across the projection horizon. CAGRs were derived from regression analysis against hydrocarbon infrastructure investment cycles and emissions compliance deadline impacts. Industry-specific forecast inputs included Permian Basin drilling permit velocity and Gulf Coast shipyard backlog duration.
Inputs from EPA engine certification records and EU member state equipment registration databases were available through the study window; gaps in emerging market customs data for carbureted unit flows introduce uncertainty bands around price-tier volume splits. Forecasts reflect documented assumptions regarding regulatory deadline adherence and battery-electric substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Powered Screed Market
Construction Equipment
Assembly Machine Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Spray Washer Market