
 Mexico Heavy Construction Equipment Rental Market | 2026-2036
Mexico Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Heavy Construction Equipment Rental Market Insights
Telematics integration into fleet management is tilting the competitive calculus toward data-driven asset utilization models. United Rentals, Inc. leverages its North American platform architecture to extend digital fleet tracking into Mexican operations. TRACSA Group anchors its position through Caterpillar dealership exclusivity and dense service center coverage across central Mexico. Herc Rentals Inc. differentiates through specialized aerial work platform segments that command premium day rates in urban vertical construction.
Mexico heavy construction equipment rental encompasses the temporary provision of machinery exceeding 15 metric tons operating weight, including hydraulic excavators with bucket capacities from 0.5 to 5 cubic meters and all-terrain cranes with load-moment ratings above 100 tonne-meters, primarily serving contractors seeking capital flexibility and maintenance outsourcing. Excavators and cranes together constitute the dominant equipment categories, with excavators absorbing the largest share of rental days due to their versatility across civil earthworks and building foundation phases. Short-term rental arrangements are expanding fastest among mid-tier contractors responding to project-specific T-MEC-linked industrial construction timelines, while long-term rental contracts retain margin concentration among established fleet operators serving Pemex and CFE infrastructure programs.
SEMARNAT environmental enforcement and NOM-085-SEMARNAT-2011 emission standards for diesel machinery constrain fleet eligibility for public works contracts, compelling rental providers to absorb compliance costs or forfeit government agency revenue streams. PROFECO consumer protection oversight and ASME B30 crane safety standards additionally shape equipment inspection protocols and operator certification requirements that rental houses must integrate into service bundles. Stakeholders must weigh the capital intensity of Tier 4 Final fleet transitions against the contracting risk of exclusion from federally funded infrastructure projects as emission thresholds tighten.
Market Dynamics
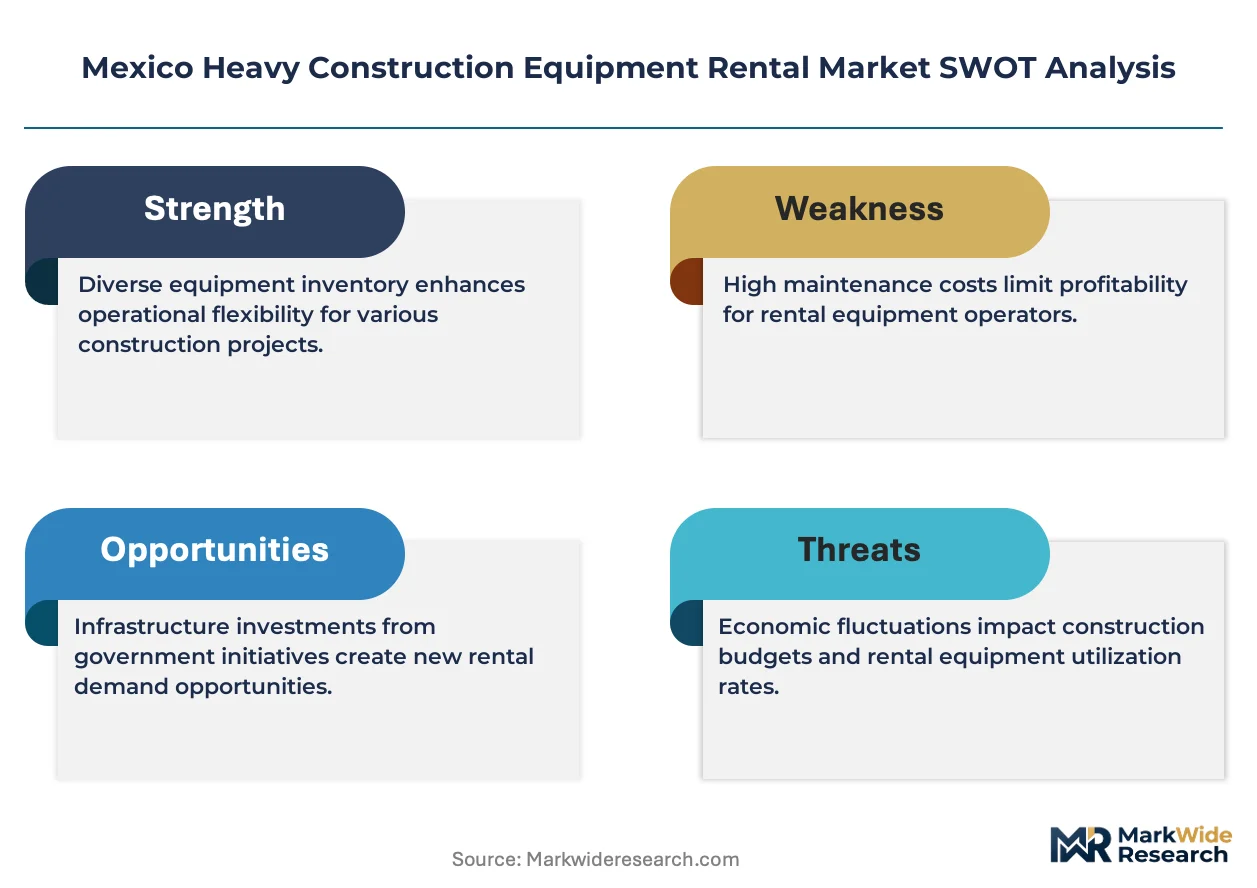
SEMARNAT emission enforcement is collapsing the operational lifespan of pre-Tier 4 diesel fleets, forcing rental providers into accelerated capital redeployment cycles that favor asset-light contractors over equipment owners.
Growth Catalysts
- T-MEC Industrial Construction:Nearshoring-driven manufacturing facilities along the Mexico-United States-Canada corridor are generating surge demand for mobile cranes and earthmoving fleets on 18-to-36-month project timelines.
- NOM-085-SEMARNAT-2011 Compliance Mandates:Federal procurement rules now restrict public works contracts to emission-certified equipment, redirecting contractor spend toward compliant rental pools rather than aging owned assets.
- Telematics-Enabled Utilization Optimization:Real-time fleet tracking systems are compressing equipment idle time and enabling dynamic pricing models that improve rental house margins on excavator and crane categories.
Market Restraints
- Diesel Engine Supply Concentration:Tier 4 Final powertrain sourcing depends on a consolidated supplier base concentrated in the United States and Japan, exposing Mexican rental fleets to import tariff volatility and extended lead times.
- Capital Intensity of Fleet Modernization:The cost differential between compliant and non-compliant hydraulic excavators exceeds prior replacement cycles, straining balance sheets of mid-tier rental operators serving state-level contractors.
- Skilled Operator Scarcity:ASME B30 crane certification requirements and PROFECO-mandated training documentation are extending equipment deployment timelines, constraining effective fleet capacity during peak construction windows.
Strategic Opportunities
- Baja California Industrial Corridor:Aerospace and medical device manufacturing expansion in Tijuana and Mexicali is creating underpenetrated demand for specialized material handling and aerial work platforms.
- Hybrid-Electric Equipment Convergence:Battery-assisted hydraulic systems and grid-connected charging infrastructure at rental depots are opening premium rate categories for zero-emission zones in Mexico City and Monterrey metropolitan areas.
- PROFECO-Certified Service Bundling:Integrated maintenance and operator training packages are emerging as a differentiated channel strategy, capturing contractor preferences for risk transfer and compliance outsourcing.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems at established rental houses require substantial reconfiguration to absorb real-time data feeds from mixed-vendor equipment pools, delaying ROI realization on digital investments.
- ASME B30 Inspection Backlogs:Certified crane inspector capacity constraints are extending pre-rental certification timelines, compressing effective utilization rates during high-demand construction seasons in central Mexico.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Heavy Construction Equipment Rental Market |
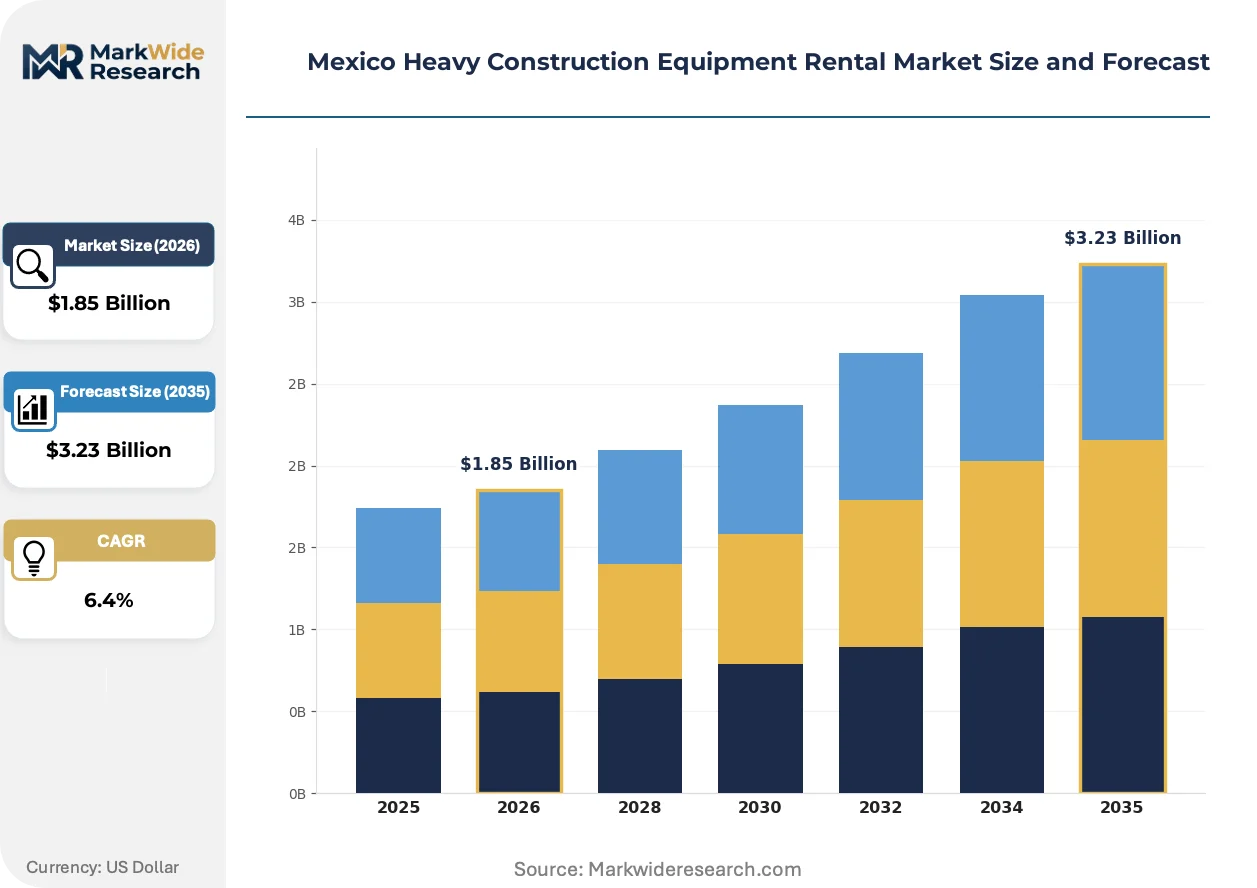
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Excavators, Bulldozers, Cranes, Loaders Service Type: Short-Term Rental, Long-Term Rental, Maintenance, Delivery End User: Construction Companies, Contractors, Government Agencies, Industrial Firms Deployment: On-Site Rental, Off-Site Rental, Auction Based, Direct Sales |
| Companies Covered | Ascendum Mexico, Ibergruas, TRACSA Group, United Rentals, Inc., Herc Rentals Inc., Maqro, Intertorito, Ashtead Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Heavy Construction Equipment Rental Market Trends and Innovations
Digital fleet management architectures are collapsing traditional asset ownership models across Mexican construction markets, with data-driven utilization platforms now determining competitive position more than fleet scale alone.
Machine learning-based predictive maintenance is collapsing unplanned downtime intervals for hydraulic excavators and crawler cranes. Mid-tier contractors operating on T-MEC-linked industrial timelines are adopting these systems fastest, prioritizing uptime guarantees over capital ownership. Equipment availability contracts are compressing traditional day-rate structures into performance-based fee arrangements that transfer mechanical risk to rental providers.
SEMARNAT enforcement protocols under NOM-085-SEMARNAT-2011 are tightening diesel particulate thresholds for machinery operating on federal infrastructure contracts. Rental houses serving Pemex and CFE programs face equipment disqualification without Tier 4 Final certification, accelerating scrap-and-replace cycles for excavators above 15 metric tons. Compliance documentation requirements are reshaping procurement evaluation criteria toward emission certification over unit age or brand.
Contractor procurement patterns are fragmenting across project-specific rental durations rather than annual fleet leases. Short-term arrangements of 30-to-90 days are displacing traditional six-month contracts among regional builders responding to volatile industrial construction pipelines. This behavioral shift concentrates most visibly in Querétaro and Guanajuato manufacturing zones where nearshoring project starts remain unpredictable.
Mexico Heavy Construction Equipment Rental Market Segmentation
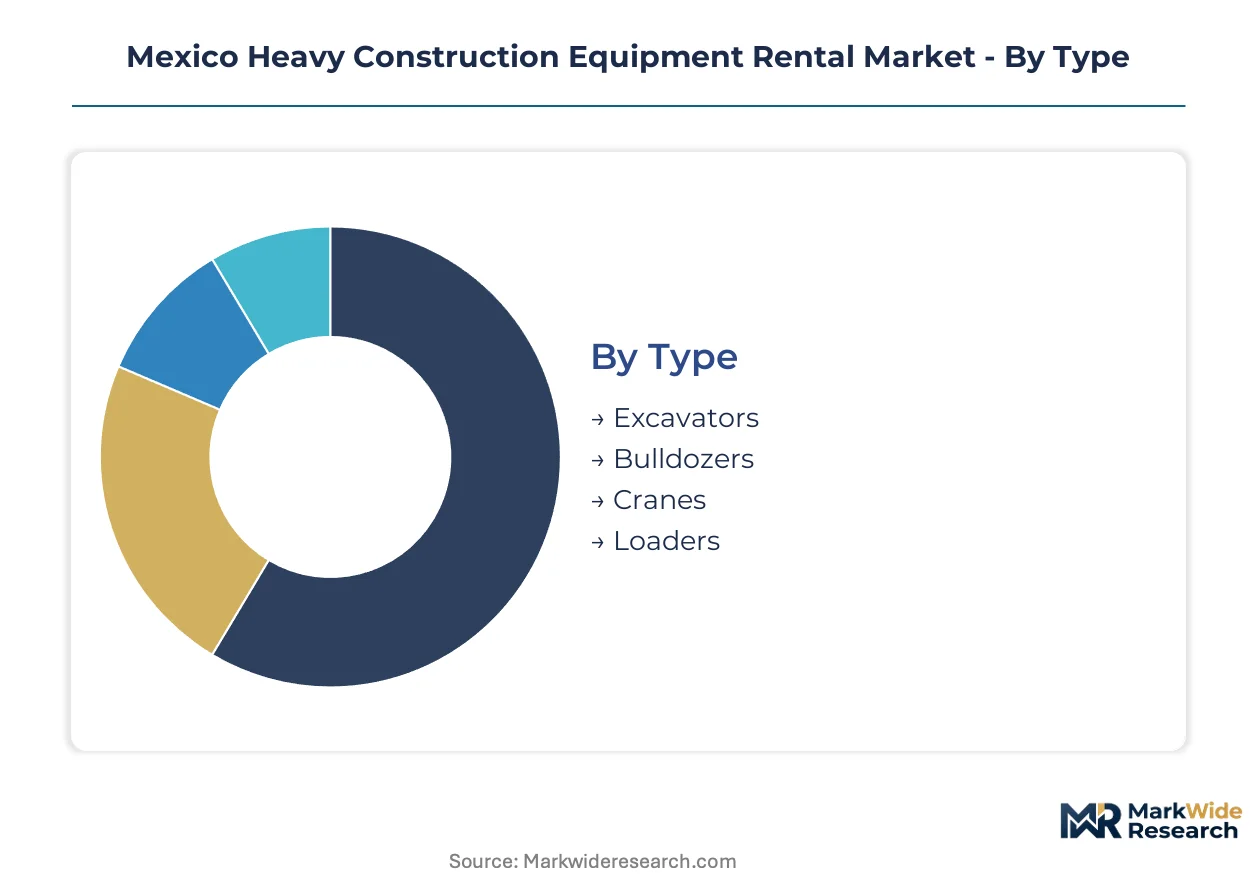
Rental fleet composition in Mexico reflects divergent capital deployment cycles across equipment categories. Service duration preferences fragment procurement patterns between project-based contractors and institutional infrastructure programs. Understanding these segment boundaries clarifies where rental houses concentrate modernization investments versus defensive maintenance.
Type:
Excavators and cranes command the shortest replacement cycles due to SEMARNAT emission mandates, while bulldozers and loaders face extended utilization timelines in secondary applications.
- Excavators:Hydraulic machines with bucket capacities from 0.5 to 5 cubic meters absorb the largest share of rental days across civil earthworks and building foundation phases. Demand concentrates most acutely in Mexico City and the T-MEC corridor industrial zones where nearshoring-driven manufacturing facilities require rapid site preparation.
- Cranes:All-terrain and crawler varieties with load-moment ratings above 100 tonne-meters serve vertical construction and heavy industrial installation. Monterrey metropolitan area generates premium rate demand for ASME B30-certified units in petrochemical and aerospace facility construction.
- Bulldozers:Tracked earthmoving equipment supports grading and landfill operations with longer deployment tenures per project. Pemex pipeline maintenance programs in Veracruz sustain steady utilization for medium-duty dozer fleets.
- Loaders:Wheel and track loaders handle material handling across quarry and aggregate processing applications. Baja California mining operations extend rental durations for high-capacity loader categories beyond typical construction cycles.
Excavators dominate installed base. Cranes are where expansion concentrates.
Service Type:
Margin structures vary sharply between transactional short-term arrangements and integrated long-term contracts that bundle compliance documentation.
- Short-Term Rental:Arrangements spanning 30-to-90 days are displacing traditional six-month contracts among regional builders responding to volatile T-MEC-linked industrial timelines. Querétaro and Guanajuato manufacturing zones show the fastest behavioral shift toward project-specific procurement.
- Long-Term Rental:Contracts exceeding 12 months retain margin concentration among established fleet operators serving Pemex and CFE infrastructure programs. These agreements typically incorporate Tier 4 Final equipment guarantees and PROFECO-certified maintenance documentation.
- Maintenance:Service bundling emerges as a differentiated channel strategy capturing contractor preferences for risk transfer. Integrated packages absorb SEMARNAT compliance costs and ASME B30 inspection scheduling from end-user responsibility.
- Delivery:Logistics coordination for equipment positioning and retrieval commands premium pricing in remote project locations. Baja California and Sonora industrial corridors generate specialized transport demand due to distance from central Mexico depot networks.
Long-term rental locks in revenue predictability. Short-term rental is climbing the fastest.
End User:
Procurement sophistication separates institutional buyers with mandated emission compliance from mid-tier contractors optimizing capital flexibility.
- Construction Companies:Large integrated builders maintain hybrid fleet strategies combining owned core assets with rental surge capacity. These firms prioritize telematics-enabled utilization optimization across multi-project portfolios.
- Contractors:Mid-tier specialty operators drive fastest adoption of predictive maintenance systems and uptime guarantee contracts. T-MEC-linked manufacturing construction timelines compress their procurement decisions toward availability-based fee structures.
- Government Agencies:Federal procurement rules under NOM-085-SEMARNAT-2011 restrict public works contracts to emission-certified equipment. Pemex and CFE programs redirect spend toward compliant rental pools rather than aging owned assets.
- Industrial Firms:Manufacturing and energy sector end-users demand specialized material handling and aerial work platforms. Aerospace expansion in Tijuana and medical device manufacturing in Mexicali create underpenetrated demand for premium equipment categories.
Government agencies anchor compliance-driven procurement. Contractors represent the steepest expansion trajectory.
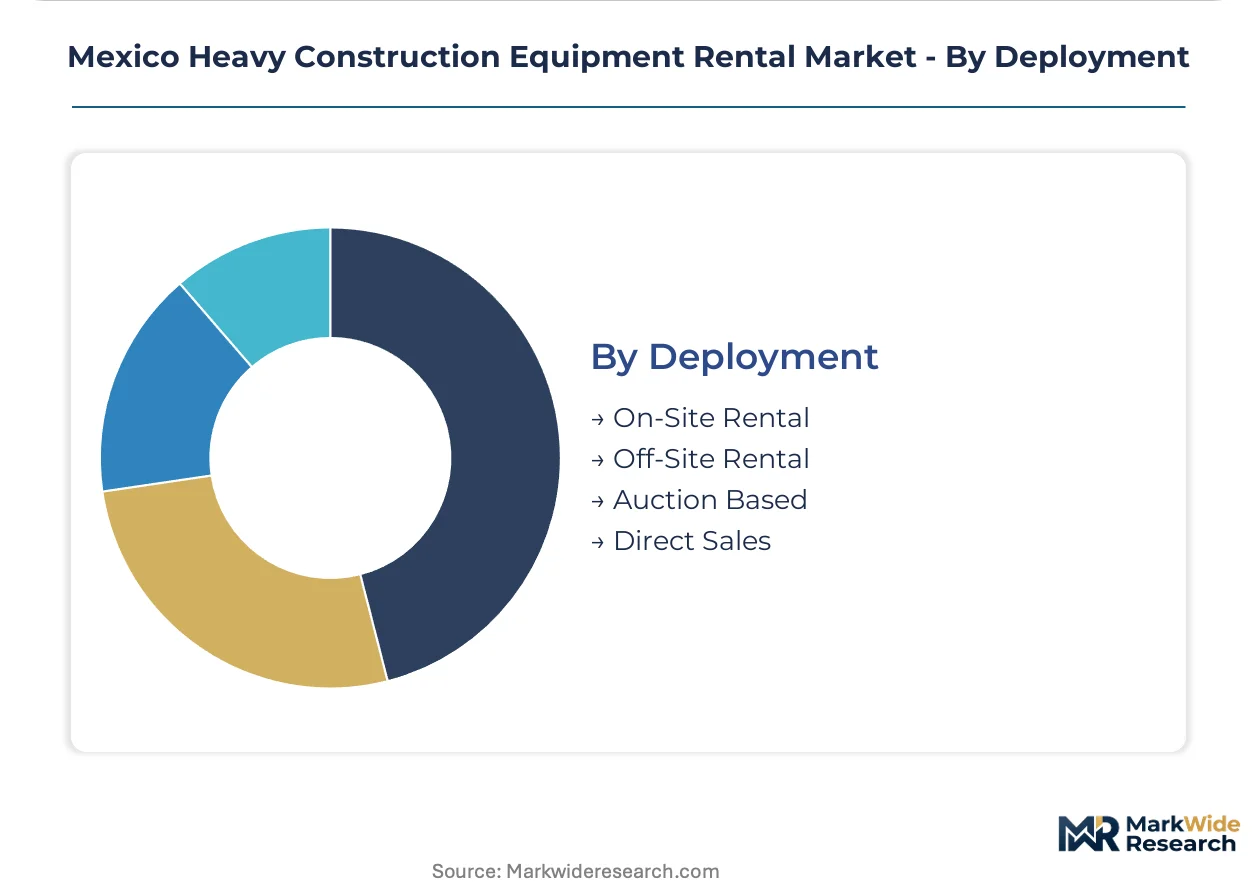
Deployment:
Channel configuration determines asset velocity and residual value exposure for rental providers.
- On-Site Rental:Equipment positioned directly at project locations maximizes utilization rates and minimizes transport dead time. Mexico City metropolitan congestion makes on-site deployment essential for meeting compressed construction windows.
- Off-Site Rental:Depot-based availability requires robust logistics coordination but enables fleet pooling across multiple concurrent projects. Central Mexico service center density supports this model for established Caterpillar dealership networks.
- Auction Based:Secondary market disposition channels absorb retired Tier 3 and pre-Tier 4 equipment facing SEMARNAT disqualification. These transactions accelerate capital recovery for fleet modernization programs.
- Direct Sales:Lease-to-own arrangements and outright purchase options serve contractors with predictable long-term equipment needs. State-level infrastructure contractors in Nuevo León and Jalisco favor this path for core excavator fleets.
On-site rental dominates effective fleet utilization. Auction-based channels are gaining share fastest as emission compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The T-MEC corridor channels Mexican heavy construction equipment rental demand northward toward United States and Canadian manufacturing investment, with cross-border industrial construction timelines compressing procurement cycles across central and northern states.
Mexico City Metropolitan Area
Vertical construction and metro expansion projects absorb the highest density of hydraulic excavator and crane rentals. SEMARNAT enforcement of NOM-085-SEMARNAT-2011 disqualifies pre-Tier 4 equipment from federal contracts, redirecting contractor spend toward compliant rental pools. The Santa Fe and Vallejo districts concentrate demand for ASME B30-certified aerial platforms in high-rise development.
Nuevo León
Monterrey anchors petrochemical and aerospace facility construction generating premium-rate crane demand. The state's proximity to Texas manufacturing supply chains accelerates nearshoring-driven earthmoving equipment deployment. García and Apodaca industrial parks sustain 18-to-36-month rental timelines for mobile crane fleets.
Jalisco
Guadalajara's electronics manufacturing expansion creates specialized material handling requirements. PROFECO-certified service bundling captures contractor preferences for risk transfer in this mid-tier market. El Salto and Tlajomulco industrial corridors show fastest adoption of predictive maintenance contracts.
Bajío Region
Querétaro and Guanajuato automotive supplier parks drive volatile short-term rental patterns. Unpredictable project starts compress procurement decisions toward 30-to-90-day arrangements rather than annual leases. San José Iturbide and Apaseo el Alto manufacturing zones generate surge demand for telematics-enabled utilization optimization.
Northern Border States
Tijuana and Mexicali aerospace and medical device manufacturing creates underpenetrated demand for specialized aerial work platforms. Distance from central Mexico depot networks commands premium logistics pricing for equipment positioning. Mexicali's solar energy projects extend crawler crane rental durations beyond typical construction cycles.
Mexico Heavy Construction Equipment Rental Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates among established fleet operators with dense service center coverage. United Rentals and TRACSA Group anchor the upper tier through North American platform extension and Caterpillar dealership exclusivity respectively. Mid-tier regional operators survive through specialized equipment segments and localized logistics coordination. Dominant competitive moves include telematics-enabled fleet modernization and PROFECO-certified service bundling that transfers compliance risk to rental providers.
Among North American platform extenders, United Rentals, Inc. and Herc Rentals Inc. occupy positions emphasizing digital fleet tracking and specialized aerial work platform segments. TRACSA Group anchors the dealership-anchored archetype through Caterpillar exclusivity and central Mexico service density. These three exemplify divergent strategic vectors: technology-led utilization optimization, premium segment specialization, and manufacturer-tied distribution control.
| Leading Market Players |
|---|
| Ascendum Mexico |
| Ibergruas |
| TRACSA Group |
| United Rentals, Inc. |
| Herc Rentals Inc. |
| Maqro |
| Intertorito |
| Ashtead Group plc |
| Others |
Pricing and Supply Chain Analysis
The Laredo-Nuevo Laredo freight corridor's diesel transport cost dynamics compress margins for Tier 4 Final equipment deliveries while amplifying price differentiation between emission-certified and legacy rental fleets across central Mexico depot networks.
Pricing Analysis
Tier 4 Final hydraulic excavators command 15-25% day-rate premiums over Tier 3 equivalents, while battery-assisted hybrid units in pilot deployment fetch additional surcharges in Mexico City zero-emission zones. Three-tier pricing structure across premium certified, standard compliant, and economy legacy levels stratifies around SEMARNAT documentation completeness and ASME B30 inspection currency. Cost compression in economy-tier diesel fleets is intensifying because accelerated scrap-and-replace cycles collapse residual value recovery timelines. Mid-tier contractors operating on volatile T-MEC project timelines exhibit highest price sensitivity, whereas Pemex and CFE infrastructure programs prioritize uptime guarantees over rate negotiation.
Supply Chain Analysis
Diesel engine powertrain manufacturing concentrates in the United States, Japan, and Germany, with Cummins, Isuzu, and Deutz supplying the Mexican rental market's Tier 4 Final retrofit requirements. Steel plate fabrication, hydraulic system components, and telematics hardware draw from Chinese, South Korean, and domestic maquiladora assembly operations. Single-source vulnerability around EPA-certified engine control modules exposes fleet operators to 6-9 month lead time extensions during supply crunches. Distribution runs through Caterpillar dealership networks anchored by TRACSA Group in central Mexico, supplemented by United Rentals' direct depot model in northern industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME B30-certified crane inspector capacity constraints and telematics integration expertise gaps concentrate competitive advantage among operators who can guarantee equipment availability with compliance documentation bundled.
For Market Incumbents: Insulate core revenue streams by securing exclusive Caterpillar or Komatsu dealership territories before emission deadlines disqualify non-compliant competitors from federal procurement. Backward integration into captive maintenance facilities in Querétaro and Guanajuato absorbs PROFECO-certified service bundling margins that would otherwise leak to third-party providers. Accelerated fleet telemetry deployment locks in contractor switching costs through utilization optimization platforms that mid-tier operators cannot replicate internally. For New Entrants and Emerging Players: Establish a beachhead in Baja California's aerospace and medical device manufacturing zones where specialized aerial work platform demand outruns established depot coverage from central Mexico incumbents. Mexicali and Tijuana project pipelines remain underpenetrated by ASME B30-certified crane fleets, creating 18-24 month windows for premium rate capture before national operators extend northward. A telematics-first go-to-market angle differentiates against legacy fleet managers whose digital retrofit cycles lag 12-18 months behind equipment replacement timelines. For Investors and Strategic Acquirers: Regional rental operators with dense service center footprints in Nuevo León and Jalisco but sub-scale telematics infrastructure represent consolidation targets for North American platform extenders seeking geographic density. Long-term viability in this market hinges on emission compliance transition completion before NOM-085-SEMARNAT-2011 enforcement tightens further. Watch SEMARNAT inspection queue backlogs as the inflection indicator—extended certification timelines signal effective fleet capacity constraints that compress utilization rates and trigger rate inflation.| Strategic Initiative | Industry Significance |
|---|---|
| Tier 4 Final Fleet Modernization | SEMARNAT compliance deadlines disqualify legacy assets from Pemex and CFE contracts, redirecting procurement toward certified rental pools. |
| Telematics Platform Deployment | Real-time utilization tracking enables dynamic pricing models that improve excavator and crane category margins for early adopters. |
| ASME B30 Certification Investment | Certified inspector capacity constraints extend pre-rental timelines, creating competitive advantage for operators with in-house compliance teams. |
| Service Center Network Densification | Proximity to T-MEC corridor industrial zones reduces transport dead time and captures surge demand from nearshoring manufacturing construction. |
| Hybrid-Electric Equipment Pilot Programs | Battery-assisted hydraulic systems open premium rate categories in Mexico City and Monterrey metropolitan zero-emission zones. |
Research Methodology
A standing panel of fleet operations directors, maintenance service managers, contractor procurement leads, and SEMARNAT compliance officers provided ongoing calibration across the primary research phase. Secondary validation drew from Mexican customs import records for diesel powertrain components, SEC filings of North American rental platform parents, ASME B30 inspector certification databases, and PROFECO consumer protection enforcement notices. Bottom-up equipment unit economics triangulated against top-down construction spending forecasts from federal infrastructure budget disclosures.
Scenario bracketing around T-MEC manufacturing investment velocity, SEMARNAT enforcement intensity, and diesel engine supply availability established high-low bounds across the projection horizon. Segmentation modeling incorporated equipment type, service duration, end-user sophistication tier, and deployment channel configuration. CAGRs derived from logistic curve fitting to historical rental day trajectories, cross-referenced against Pemex and CFE capital program announcements and nearshoring facility ground-breaking timelines.
Stress conditions across diesel powertrain import tariff volatility, ASME B30 inspector capacity bottlenecks, and T-MEC project cancellation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding emission standard phase-in schedules and federal infrastructure spending continuity. Cross-checking against Mexican construction industry association equipment utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
Trenchers Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Part Feeder Market