
 Rail Welding Equipment Market | 2026-2036
Rail Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Welding Equipment Market Insights
Modular service bundling is broadening buyer choice across the rail welding equipment landscape. Lincoln Electric leverages its electrode supply chain to anchor turnkey welding system contracts in North American freight corridors. ESAB competes through specialized flux-cored wire portfolios tailored to thermite welding applications in European track maintenance. Schlatter Group dominates flash butt welding machinery for high-speed rail joints, sustaining engineering-intensive relationships with Chinese and German infrastructure providers.
Rail welding equipment encompasses portable and stationary systems that generate metallurgically continuous rail joints through thermal or electrical energy input, typically achieving tensile strengths exceeding 880 MPa in flash butt configurations. These systems eliminate bolted connections to reduce track vibration, lower maintenance cycles, and support train speeds above 300 km/h on welded continuous rail. Flash butt welding commands the largest installed base among product types due to its prevalence in high-speed rail construction, while thermite welding retains entrenched demand in freight line maintenance where field portability outweighs cycle time. Automatic control systems within the technology dimension are capturing margin pools as infrastructure providers mandate real-time parameter logging and infrared inspection integration for warranty compliance.
The US Federal Railroad Administration enforces welded rail inspection protocols under Track Safety Standards, compelling end users to specify equipment with embedded ultrasonic testing capabilities. China's NMPA-aligned rail equipment certification and the EU's CE marking under the Machinery Directive jointly shape product access barriers and R&D allocation across manufacturing footprints. Stakeholders must monitor how evolving carbon-accounting rules under the EU Green Deal redirect procurement criteria toward lower-emission welding processes without compromising joint fatigue performance.
Market Dynamics
Automated flash butt welding systems are concentrating procurement power among state-funded high-speed rail corridors, compressing vendor margins while elevating technical compliance thresholds for joint fatigue performance and real-time parameter logging.
Growth Catalysts
- China's dual carbon goals:State-backed electrification mandates in eastern coastal provinces are accelerating replacement of gas-powered welding units with grid-tied flash butt systems in metro and intercity builds.
- Thermite process refinement:Low-emission aluminothermic formulations are capturing maintenance contracts on European freight corridors where REACH and F-Gas Regulation restrict conventional flux compositions.
- Infrared inspection integration:Automatic control systems with embedded thermal monitoring are becoming warranty prerequisites for high-speed rail joints exceeding 300 km/h operational speeds.
Market Restraints
- Specialized electrode supply concentration:Premium alloy consumables for flash butt welding concentrate among a limited supplier base in Germany and Japan, exposing buyers to input cost volatility and extended lead times.
- CE marking complexity under Machinery Directive:European equipment certification timelines stretch 14-18 months for flash butt systems with integrated ultrasonic testing, delaying revenue recognition for manufacturers.
- Field-portable thermite limitations:Cycle times for aluminothermic welding remain 3-4 times longer than flash butt methods, restricting adoption on high-frequency maintenance schedules where track possession windows contract.
Strategic Opportunities
- India's PLI scheme for rail infrastructure:Domestic manufacturing incentives are creating white space for localized welding system assembly serving Dedicated Freight Corridor expansion and Mumbai-Ahmedabad high-speed line procurement.
- Service unbundling:Equipment vendors are separating hardware sales from predictive maintenance subscriptions, opening recurring revenue streams among North American Class I railroads with aging track infrastructure.
- Hybrid welding convergence:Integration of induction preheating with conventional flash butt cycles is reducing energy consumption profiles, aligning with EU Green Deal carbon-accounting criteria for public tender eligibility.
Industry Challenges
- Certified welder scarcity:Flash butt operation requires specialized metallurgical training that outpaces vocational pipeline output in China's interior provinces and India's northern states.
- Legacy system integration friction:Retrofitting automatic control systems onto 1990s-era stationary welding plants demands custom mechanical interfaces that extend commissioning timelines and inflate project risk.
- Ultrasonic testing calibration complexity:Embedded NDT modules require traceable reference standards that differ across China's NMPA-aligned certification, US FRA Track Safety Standards, and EU CE marking frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Welding Equipment Market |
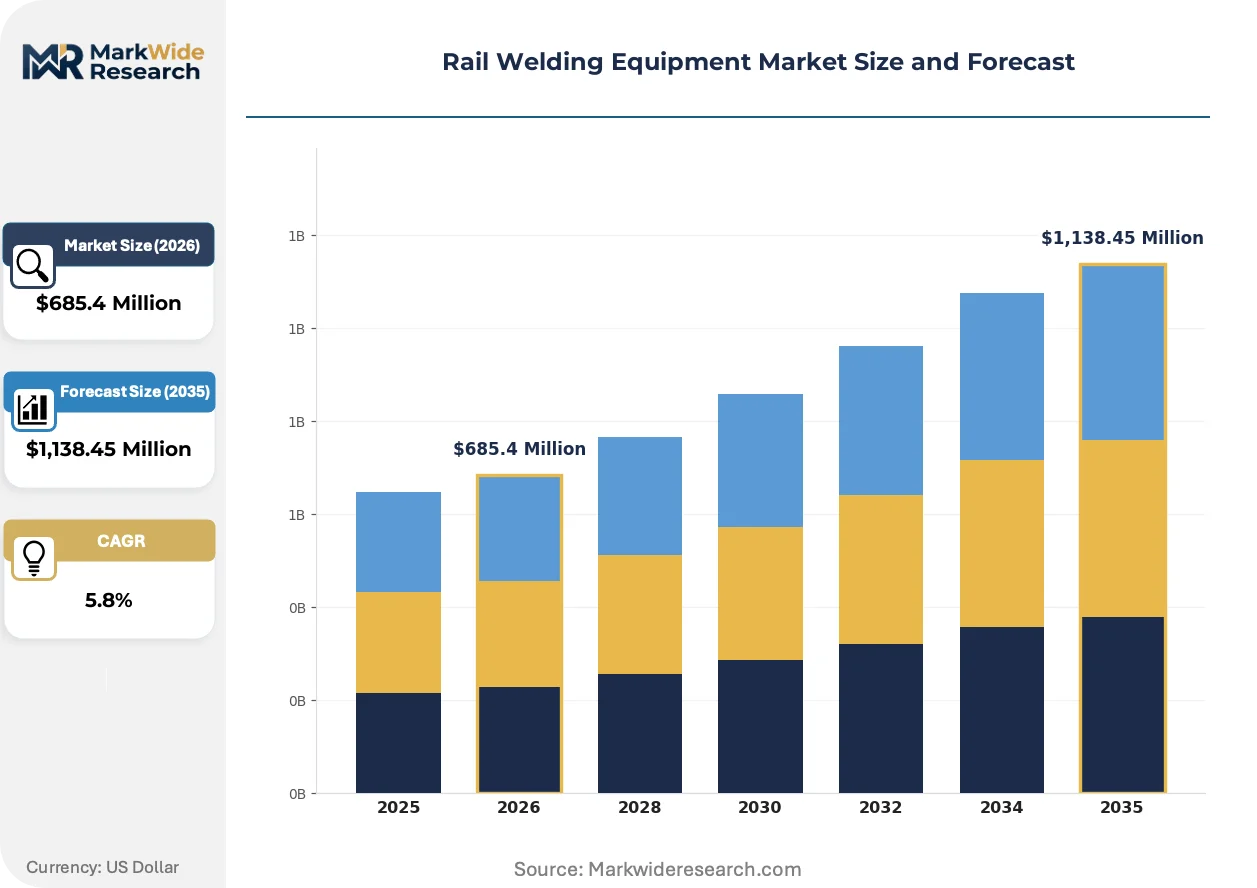
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Butt Welding, Thermite Welding, Electric Arc Welding, Gas Welding, Ultrasonic Welding Technology: Automatic Control Systems, Manual Operation, Semi-Automatic Operation, Remote Monitoring, Infrared Inspection Application: High-Speed Rail Construction, Tramway Installation, Freight Line Maintenance, Urban Transit Expansion End User: Rail Infrastructure Providers, Track Maintenance Contractors, Railway Equipment Manufacturers, Government Transport Bodies |
| Companies Covered | Lincoln Electric, Miller Electric, ESAB, Schlatter Group, Plasser & Theurer, Progress Rail, Geismar, Holland, KZESO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Welding Equipment Market Trends and Innovations
Digital thread architectures are threading through rail welding equipment specification, compressing the gap between design-phase simulation and field joint validation while elevating data sovereignty as a procurement criterion.
Laser-assisted flash butt preheating is rewriting energy input protocols for high-carbon rail grades. Chinese and German infrastructure providers are piloting fiber-delivered beam systems that reduce thermal distortion in 880 MPa tensile strength joints. The technology is compressing heat-affected zone widths and enabling single-pass welding of premium rail alloys previously requiring multi-cycle treatment.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cooling systems out of portable welding equipment. Manufacturers serving European maintenance contractors are pivoting to thermoelectric and liquid-cooled architectures that eliminate fluorinated gas compliance exposure. Freight line operators in Germany and France are specifying these alternatives in framework agreements to preempt regulatory retrofit costs.
After-sales contracting is fragmenting from bundled turnkey packages toward discrete component subscriptions. North American freight corridors are unbundling electrode supply, control software licenses, and field service into separate annual agreements. This pattern concentrates most acutely among Class I railroads with centralized procurement functions seeking usage-based cost allocation across multiple maintenance districts.
Rail Welding Equipment Market Segmentation
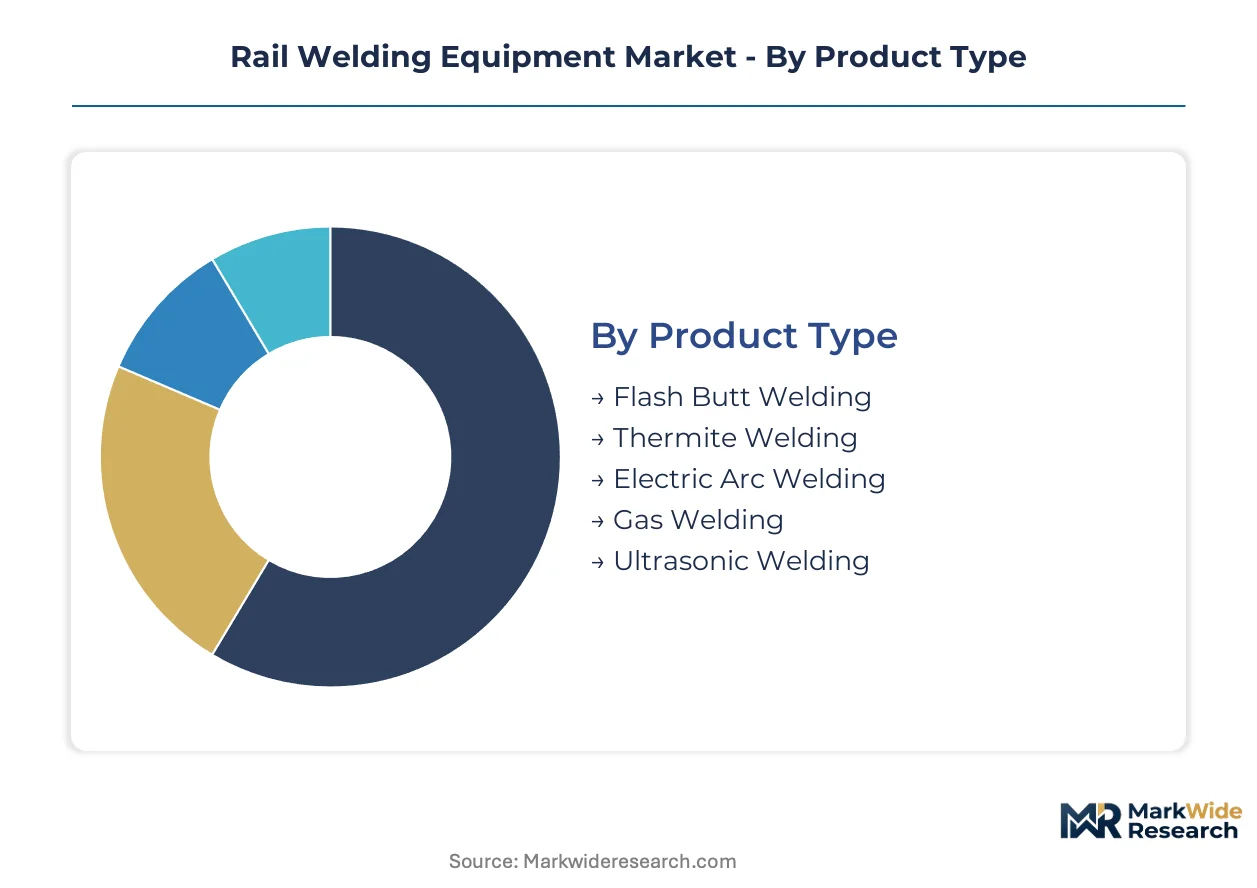
Rail welding equipment segmentation reveals how procurement power concentrates around high-speed rail construction while maintenance applications sustain parallel technology streams. Equipment specification diverges sharply between factory-grade flash butt systems and field-portable thermite kits, with control technology becoming the decisive margin battleground.
Product Type:
Flash butt systems command premium pricing through precision engineering, while thermite equipment spreads across volume maintenance contracts.
- Flash Butt Welding:Delivers metallurgically continuous joints through electrical resistance heating and upset forging, achieving tensile strengths exceeding 880 MPa. Chinese state-funded high-speed rail corridors in eastern coastal provinces anchor procurement volume, driven by mandatory real-time parameter logging for warranty compliance on lines operating above 300 km/h.
- Thermite Welding:Employs exothermic aluminothermic reactions to fuse rail ends without external power sources, prioritizing field portability over cycle speed. European freight line maintenance contractors specify low-emission formulations to satisfy REACH and F-Gas Regulation constraints on conventional flux compositions.
- Electric Arc Welding:Deploys consumable electrodes for localized repair applications where full rail replacement is impractical.
- Gas Welding:Retains niche utility in legacy track networks with limited electrical infrastructure access.
- Ultrasonic Welding:Emerging for specialized joining of rail accessories and signaling component housings.
Today's leader: Flash Butt Welding. Tomorrow's challenger: Thermite Welding.
Technology:
Control sophistication separates price tiers, with embedded inspection modules becoming non-negotiable for high-speed rail qualification.
- Automatic Control Systems:Integrate closed-loop parameter regulation with infrared thermal monitoring and ultrasonic testing modules. Infrastructure providers in Germany and China mandate these configurations for joint warranty coverage on premium rail grades.
- Infrared Inspection:Embeds non-contact temperature profiling directly into welding cycles, enabling real-time heat-affected zone validation. EU Green Deal carbon-accounting rules favor these systems for public tender eligibility through energy consumption optimization.
- Manual Operation:Persists in emerging markets where certified technician scarcity limits automated system deployment.
- Semi-Automatic Operation:Bridges cost and capability gaps for mid-tier maintenance contractors.
- Remote Monitoring:Enables centralized oversight of distributed welding operations across North American Class I railroad maintenance districts.
Automatic Control Systems capture the steepest expansion trajectory as regulatory compliance tightens.
Application:
Construction intensity versus maintenance frequency shapes equipment lifecycle economics and service contract structures.
- High-Speed Rail Construction:Demands stationary flash butt systems with integrated NDT capabilities for continuous welded rail production. India's Dedicated Freight Corridor and Mumbai-Ahmedabad high-speed line procurement under PLI scheme incentives are concentrating near-term demand.
- Freight Line Maintenance:Relies on portable thermite equipment for field joint repair where track possession windows constrain cycle time. German and French operators are specifying F-Gas-compliant cooling architectures in framework agreements.
- Tramway Installation:Requires compact welding systems for urban right-of-way constraints.
- Urban Transit Expansion:Metro builds in China's interior provinces drive automated system adoption despite certified welder scarcity.
High-Speed Rail Construction dominates capital deployment. Freight Line Maintenance sustains recurring consumables demand.
End User:
Procurement centralization varies sharply between state infrastructure monopolies and fragmented maintenance contracting.
- Rail Infrastructure Providers:State-backed entities in China and India wield concentrated purchasing power for turnkey system procurement, compressing vendor margins while elevating technical compliance thresholds.
- Track Maintenance Contractors:European and North American operators are unbundling equipment from service contracts, creating discrete revenue streams for predictive maintenance subscriptions.
- Railway Equipment Manufacturers:Source welding systems for in-house rail component fabrication and quality validation.
- Government Transport Bodies:Shape specification standards through safety regulation and tender design.
Rail Infrastructure Providers dictate volume terms. Track Maintenance Contractors are fragmenting supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flash butt welding technology originated in German engineering workshops during the early 20th century before scaling through Chinese state rail expansion. Manufacturing footprints now cluster around high-speed rail construction corridors and legacy maintenance networks across five major economies.
China
Eastern coastal provinces anchor procurement volume for automated flash butt systems serving concurrent metro and intercity builds. NMPA-aligned rail equipment certification mandates real-time parameter logging for warranty compliance on lines exceeding 300 km/h. The Yangtze River Delta concentration includes Shanghai-Nanjing corridor upgrades where networked infrastructure deployment compresses vendor delivery schedules.
Germany
Engineering-intensive relationships with infrastructure providers sustain premium flash butt machinery production for export markets. EU F-Gas Regulation and REACH compliance frameworks redirect R&D toward thermite-based alternatives with lower emissions profiles. The Baden-Württemberg industrial corridor houses specialized electrode supply concentration that exposes buyers to input cost volatility.
United States
North American freight corridors drive demand for predictive maintenance subscriptions and unbundled service contracts among Class I railroads. FRA Track Safety Standards enforce welded rail inspection protocols compelling ultrasonic testing capability specifications. The Midwest rail maintenance cluster spanning Illinois and Ohio concentrates track possession operations requiring portable thermite equipment.
India
PLI scheme incentives for rail infrastructure create white space for localized welding system assembly serving Dedicated Freight Corridor expansion. CDSCO-aligned equipment standards and BIS certification timelines shape market access for foreign manufacturers. The Mumbai-Ahmedabad high-speed line procurement concentrates demand in Maharashtra and Gujarat states.
France
Freight line maintenance contractors specify F-Gas-compliant cooling architectures in framework agreements to preempt regulatory retrofit costs. ANSM and national environmental regulators enforce emissions constraints on conventional flux compositions. The Île-de-France region anchors thermite welding demand for dense suburban rail networks with constrained track access windows.
Rail Welding Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with automatic control systems separating price tiers. The vendor base concentrates among diversified industrial conglomerates with captive welding consumables supply and specialized machinery builders focused on rail-specific joint formation. Three archetypes dominate: electrode-anchored system integrators, flash butt precision engineers, and portable thermite specialists. Competitive moves center on service unbundling for recurring revenue capture and hybrid welding convergence for EU Green Deal tender eligibility.
Among diversified industrial conglomerates, Lincoln Electric and ESAB occupy positions spanning electrode supply chains through turnkey system architecture. Schlatter Group exemplifies the precision engineering archetype for high-speed rail joint applications. These three anchors represent distinct competitive vectors: consumables-integrated contracting, specialized flux-cored portfolios, and flash butt machinery dominance respectively.
| Leading Market Players |
|---|
| Lincoln Electric |
| Miller Electric |
| ESAB |
| Schlatter Group |
| Plasser & Theurer |
| Progress Rail |
| Geismar |
| Holland |
| KZESO |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between CE-marked flash butt systems and field-portable thermite kits manifests in both pricing power and supply chain configuration. Premium automatic control systems with embedded NDT modules command substantial markups through German and Chinese engineering-intensive relationships, while commodity thermite consumables flow through fragmented electrode distributors across European maintenance networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement dynamics. Price differentiation rests on CE marking tier and infrared inspection integration density. Cost compression in standard-tier flash butt equipment is intensifying because Chinese state-funded corridors compress vendor margins through consolidated tender volumes. Track maintenance contractors exhibit acute price sensitivity compared to rail infrastructure providers with centralized procurement functions.
Supply Chain Analysis
Remanufacturing flows for 1990s-era stationary welding plants create secondary parts markets extending equipment lifecycles. Premium alloy consumables concentrate in Germany and Japan, while complete system assembly clusters in China and India under PLI scheme incentives. Single-source vulnerability around specialized electrodes exposes buyers to input cost volatility. Distribution runs through turnkey system integrators for high-speed rail construction and consumables distributors for maintenance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through divergent certification timelines: European CE marking stretches 14-18 months while India's BIS pathways create faster market access for localized assembly.
For Market Incumbents: Lock in electrode supply chain dominance through captive production of premium alloy consumables in Baden-Württemberg. Defend against emerging Chinese automation vendors by deepening automatic control system integration with real-time parameter logging. Prioritize certification investment in India's CDSCO-aligned standards ahead of Dedicated Freight Corridor expansion. For New Entrants and Emerging Players: Mid-tier maintenance contractors in North American Class I railroads represent an underserved buyer archetype seeking unbundled predictive maintenance subscriptions. Penetrate through service-only contracts without hardware sales. Target India's Maharashtra and Gujarat states for localized flash butt system assembly serving Mumbai-Ahmedabad high-speed procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermite formulation developers holding REACH-compliant low-emission portfolios. Five-to-ten-year viability favors vendors with hybrid welding convergence capabilities aligning with EU Green Deal tender criteria. Monitor F-Gas Regulation phase-down schedules as inflection signal for cooling architecture substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Supply | Lincoln Electric's captive consumables production anchors turnkey contract pricing power across North American freight corridors. |
| Hybrid Welding Convergence | Induction preheating integration with flash butt cycles reduces energy consumption for EU Green Deal public tender eligibility. |
| Service Unbundling | Separating hardware sales from predictive maintenance subscriptions opens recurring revenue among aging North American track infrastructure. |
| Localized Assembly Under PLI Incentives | Domestic manufacturing in India serves Dedicated Freight Corridor expansion with reduced BIS certification friction. |
| Low-Emission Formulation Development | REACH-compliant thermite alternatives capture European freight maintenance contracts under F-Gas Regulation constraints. |
Research Methodology
Direct dialogue with rail infrastructure procurement directors, track maintenance contractors, welding equipment plant managers, and aftermarket service heads grounded qualitative findings. Secondary validation drew from FRA Track Safety Standards filings, EU Machinery Directive certification databases, Chinese NMPA equipment registries, and Indian BIS conformity records. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis provided triangulation.
Segment-level value outputs across the analysis window reflect modeled deployment of flash butt versus thermite systems by application intensity. Technology tier, end-user procurement centralization, and regional regulatory cluster shaped segmentation dimensions. CAGRs derived from infrastructure pipeline tracking and equipment replacement cycle analysis, with energy transition policy velocity and certified welder pipeline output as key forecast inputs.
Underlying measurement precision varies by segment; high-speed rail construction carries tighter precision than fragmented maintenance contracting. Forecasts reflect assumptions around state funding continuity and regulatory phase-down schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Truck Crane Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Global Welding Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Winch Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market