
 Coil Fed Punching and Cutting Machines Market | 2026-2036
Coil Fed Punching and Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Coil Fed Punching and Cutting Machines Market Analysis
China's Jiangsu and Zhejiang provinces are adding significant coil processing capacity for electric vehicle battery tray manufacturing, which is reshaping procurement patterns across Asia. DIMECO leverages its Italian engineering heritage to dominate high-precision combination machines for European appliance makers. Dallan S.p.A. anchors its competitive position through deep specialization in roll-forming-integrated punching lines for solar racking and construction profiles. DANOBAT GROUP sustains technology leadership via advanced servo-electric architectures that reduce energy consumption in heavy-gauge metalworking applications.
Coil fed punching and cutting machines process continuous metal strips through synchronized decoilers, straighteners, and press stations to produce blanked, pierced, or formed components without manual sheet handling, typically operating at feed rates exceeding 100 meters per minute and positioning accuracies within ±0.1 millimeter for high-volume automotive and electronics production. The technology dimension shows servo-electric systems capturing premium positioning as manufacturers phase out hydraulic equipment to meet factory energy targets, while combination machines that merge punching with shearing or forming operations represent the fastest-expanding product category by installed base growth. Application demand in electronics fabrication concentrates on thin-gauge copper and aluminum processing for thermal management components, whereas automotive manufacturing maintains the largest absolute volume share due to structural part programs across multiple vehicle platforms.
EU machinery directives and CE marking requirements enforce safety interlock standards and noise emission limits that elevate engineering costs for equipment sold across European manufacturing facilities. China's GB standards and MIIT industrial upgrading guidelines promote domestic substitution in precision press automation, creating certification complexity for imported systems. OSHA lockout-tagout regulations and EPA metalworking fluid discharge rules in the United States shape maintenance protocols and coolant system designs. Stakeholders must evaluate how regional decarbonization timelines will alter powertrain metal content and thus reprogram capacity planning for coil processing lines across their geographic footprints.
Market Dynamics
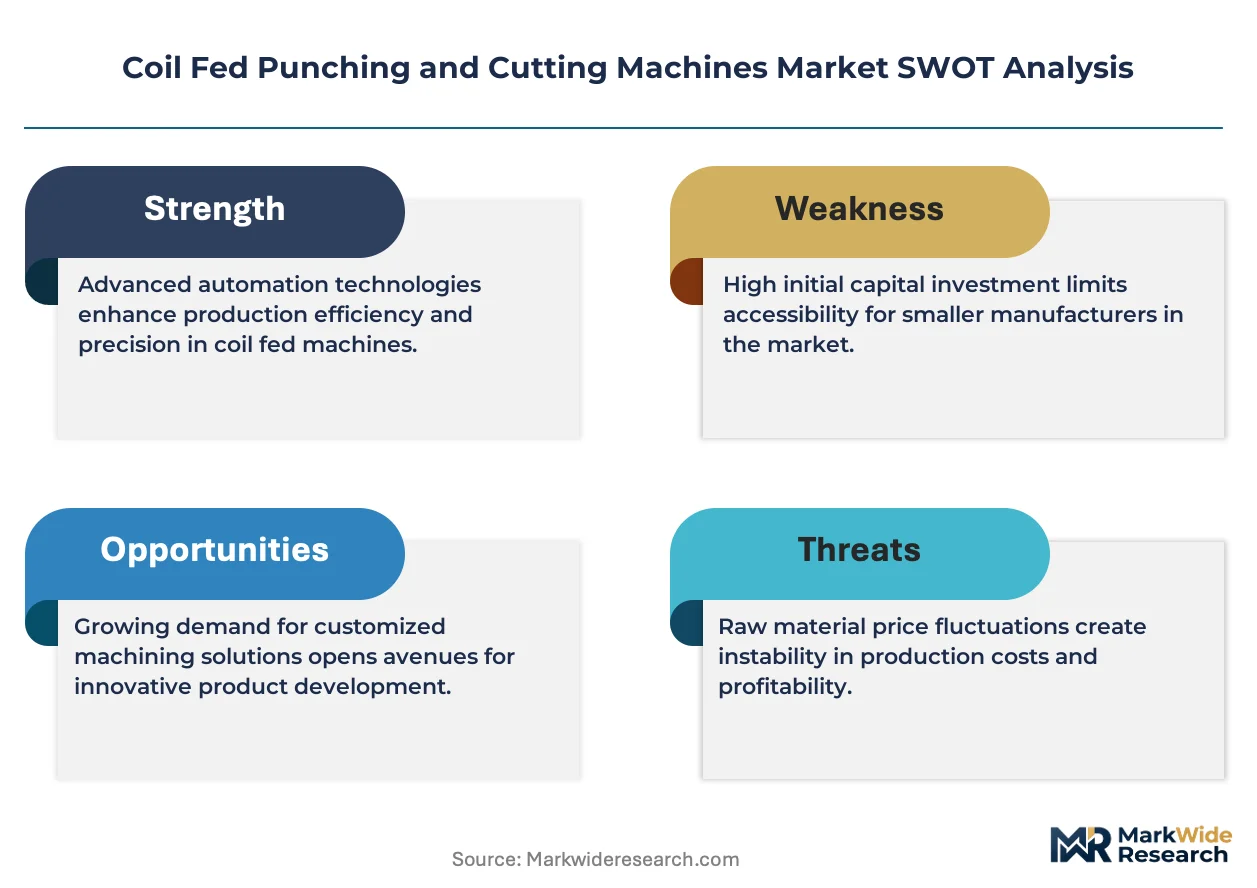
Servo-electric architectures are compressing the competitive window for hydraulic equipment as energy efficiency mandates harden across manufacturing jurisdictions, forcing capital allocation toward electromechanical press systems that slash factory power consumption.
Growth Catalysts
- EU CO2 regulations:Automotive OEMs in Germany must achieve fleet emission reductions, driving investment in lightweighting production lines that rely on high-speed coil-fed blanking for aluminum-intensive vehicle structures.
- EV battery enclosure fabrication:China's Yangtze River Delta corridor is scaling precision metalworking capacity for thermal management component production, creating concentrated demand for thin-gauge copper and aluminum processing systems.
- Japan's METI energy efficiency standards:Industrial facility upgrades must demonstrate measurable kilowatt-hour reductions, accelerating replacement cycles for legacy hydraulic punching equipment with servo-electric alternatives.
Market Restraints
- Specialized alloy supply concentration:High-strength automotive-grade aluminum coil availability clusters with a limited set of rolling mill operators, exposing equipment utilization rates to raw material allocation disruptions.
- CE marking compliance costs:EU machinery directives mandate safety interlock engineering and noise emission containment that elevate non-recurring engineering expenses for equipment destined for European facilities.
- Laser blanking substitution:Fiber laser cutting systems achieve comparable feed rates on thinner gauges with reduced tooling wear, capturing share in electronics thermal management applications where punch-die maintenance intervals deter adoption.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Domestic production-linked incentives for electric vehicle and component assembly are attracting greenfield press shop investments that require coil processing line deployment.
- Solar racking roll-forming integration:Photovoltaic mounting system producers seek combination machines that merge punching with continuous forming operations, reducing handling steps in long-profile production.
- GB standards domestic substitution:China's MIIT industrial upgrading guidelines promote certified local equipment procurement, creating certification pathways for domestic manufacturers to displace imported servo-electric systems.
Industry Challenges
- Servo-electric maintenance specialization:Electromechanical press diagnostics require control systems expertise that outstrips the hydraulic troubleshooting capabilities prevalent in incumbent maintenance workforces.
- Legacy SCADA integration complexity:Brownfield facilities operate proprietary data architectures that resist seamless connectivity with modern coil line automation, extending commissioning timelines and acceptance testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coil Fed Punching and Cutting Machines Market |
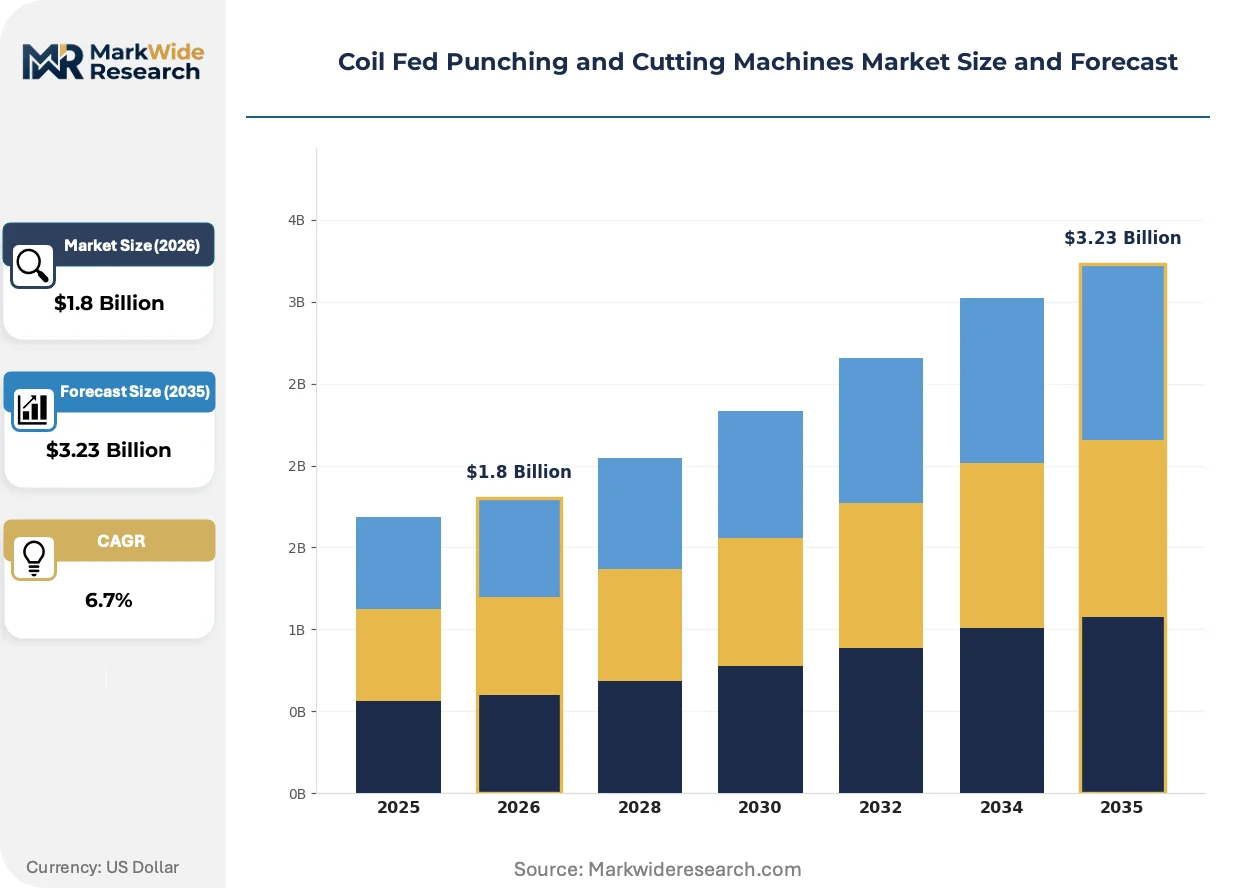
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Punching Machines, Shearing Machines, Combination Machines, Specialty Machines Application: Automotive Manufacturing, Electronics Fabrication, Metalworking, Appliance Production End User: OEMs, Tier-1 Suppliers, Manufacturing Facilities, Contract Manufacturers Technology: Hydraulic, Mechanical, Servo, Pneumatic |
| Companies Covered | DIMECO, Dallan S.p.A., DANOBAT GROUP, HACO, Pivatic Oy, Produtech s.r.l., Wuxi Qingyuan Laser Technology Co., Ltd, Dalcos, SMD Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coil Fed Punching and Cutting Machines Market Emerging Trajectories
Digital twin technology is compressing commissioning cycles and enabling predictive maintenance models that alter service revenue structures for equipment vendors. Three developments are restructuring competitive positioning.
Digital twin simulation is virtualizing press line configuration and die tryout processes before physical installation. Tier-one automotive suppliers in Germany and Japan deploy these virtual environments to reduce startup scrap rates and accelerate production ramp schedules. The technology is virtualizing traditional equipment acceptance protocols, compressing the window between delivery and full-rate production.
REACH substance restrictions and evolving RoHS scope definitions are forcing coolant formulation changes that affect lubrication system designs in coil processing equipment. Metalworking fluid chemistry adjustments to eliminate restricted additives require press manufacturers to revalidate spray nozzle configurations and filtration specifications. European appliance and electronics metal fabricators face the steepest compliance recertification burdens as they adapt to substance phase-out timelines.
Service contract unbundling is fragmenting the traditional bundled maintenance model that dominated coil line procurement. Automotive OEM procurement teams in China's Jiangsu province now separate preventive maintenance subscriptions from equipment capital purchases, pressuring vendor margins while creating openings for specialized third-party service providers. This purchasing pattern shift is most pronounced in high-volume battery tray manufacturing facilities where uptime guarantees outweigh brand loyalty in vendor selection criteria.
Coil Fed Punching and Cutting Machines Market Segmentation
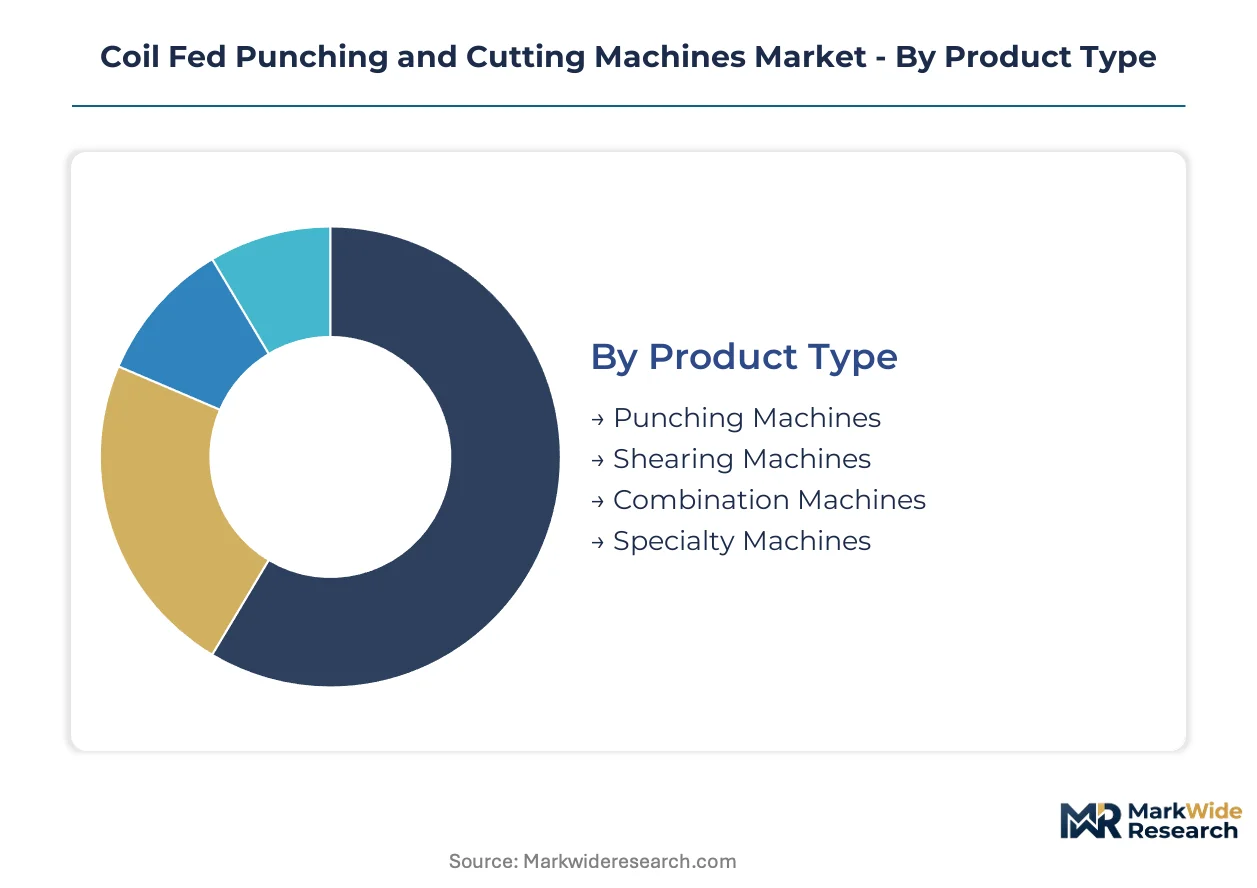
Coil-fed processing equipment serves distinct operational profiles across metalworking industries, with technology choices and application requirements driving procurement specifications. Segmentation reveals how servo-electric architectures are displacing legacy hydraulic systems in precision-demanding environments while combination machines capture share in multi-process operations.
Product Type:
Mature punching and shearing configurations dominate installed bases, while emerging combination architectures reshape competitive dynamics through process consolidation.
- Combination Machines:These systems integrate punching, shearing, and forming stations within a single coil line, eliminating material handling between operations. Automotive OEMs in Germany deploy these configurations for aluminum-intensive vehicle structures to compress cycle times and reduce work-in-process inventory.
- Punching Machines:Dedicated piercing stations achieve positioning accuracies within ±0.1 millimeter at feed rates exceeding 100 meters per minute. China's Yangtze River Delta corridor concentrates demand for high-speed servo-electric punching systems serving EV battery enclosure fabrication.
- Shearing Machines:Continuous blanking systems cut coil stock to precise lengths for subsequent press operations.
- Specialty Machines:Custom-configured lines address niche applications including perforated metal production and decorative pattern cutting.
Combination machines handle the majority of throughput in new automotive lightweighting investments; punching machines are expanding most quickly on share in electronics thermal management applications.
Application:
Cost-tier differentiation separates high-volume automotive programs from precision electronics work, with metalworking and appliance production occupying intermediate positions on capital intensity.
- Automotive Manufacturing:Structural part programs across multiple vehicle platforms sustain the largest absolute volume share, with EU CO2 regulations mandating fleet emission reductions that drive aluminum processing line investments. German OEMs expand coil-fed blanking capacity to meet lightweighting targets.
- Electronics Fabrication:Thin-gauge copper and aluminum processing for thermal management components demands servo-electric precision at reduced tonnage. Japan's METI energy efficiency standards accelerate replacement of hydraulic equipment in these facilities.
- Metalworking:General fabrication applications span construction profiles and industrial components with moderate precision requirements.
- Appliance Production:High-volume steel processing for refrigerator cabinets and washing machine drums emphasizes throughput over positioning accuracy.
Automotive manufacturing absorbs the greatest capital deployment; electronics fabrication shows the steepest expansion trajectory as battery and semiconductor thermal management requirements intensify.
End User:
Customer-type segmentation distinguishes captive production from outsourced fabrication, with tier-1 suppliers occupying a pivotal position between OEM specification and manufacturing execution.
- OEMs:Original equipment manufacturers operate proprietary coil processing lines for structural components where design integration and quality control justify captive production. These facilities prioritize uptime guarantees and direct vendor relationships over initial capital cost.
- Tier-1 Suppliers:Contracted component producers serve multiple OEM platforms from shared press shops, creating demand for flexible reconfigurable coil lines. India's PLI scheme for automotive manufacturing attracts greenfield investments from these suppliers seeking domestic production qualification.
- Manufacturing Facilities:Independent metal processors serve fragmented regional demand across construction and industrial applications.
- Contract Manufacturers:Job-shop operators purchase coil-fed equipment for project-specific capacity expansion rather than long-term platform commitments.
Tier-1 suppliers represent the fastest mover on share as OEMs outsource non-core metal fabrication; OEMs retain the highest absolute throughput in structural and safety-critical components.
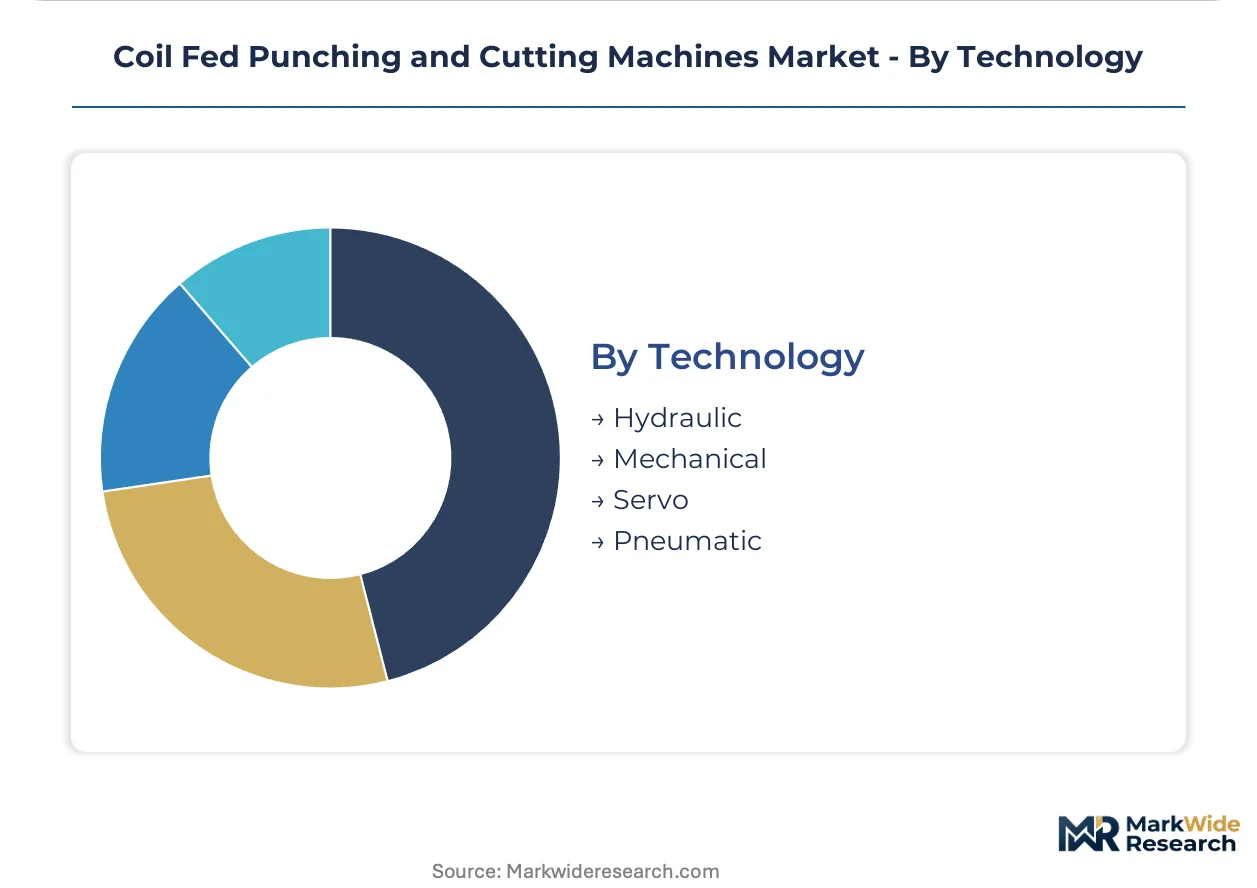
Technology:
Supply concentration in servo-electric drive systems is accelerating displacement of hydraulic architectures as factory energy targets harden across manufacturing jurisdictions.
- Servo:Electromechanical press systems slash factory power consumption through regenerative braking and demand-responsive motor control. These architectures capture premium positioning as Japan's METI standards and EU machinery directives elevate energy efficiency requirements.
- Hydraulic:Legacy fluid-power systems retain installed base presence in heavy-gauge metalworking where high tonnage at moderate speeds satisfies structural steel applications. Maintenance workforces with hydraulic troubleshooting expertise extend replacement cycles in brownfield facilities.
- Mechanical:Crank-driven presses serve cost-sensitive high-volume applications with fixed stroke profiles.
- Pneumatic:Air-powered systems occupy niche positions in light-gauge piercing operations with minimal force requirements.
Servo technology handles the majority of new capital allocation; mechanical systems are gaining share fastest in emerging market cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German facilities prioritize servo-electric precision for aluminum lightweighting, while Chinese producers emphasize throughput volume for battery enclosure fabrication, and Japanese operators optimize for energy efficiency compliance.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are expanding coil-fed blanking capacity to meet EU CO2 fleet emission mandates. The KBA enforces strict manufacturing facility standards that elevate equipment certification costs. Stuttgart's precision metalworking corridor concentrates demand for combination machines that integrate punching with continuous forming operations.
China
EV battery tray manufacturers in Jiangsu and Zhejiang provinces are scaling thin-gauge aluminum processing lines at unprecedented rates. MIIT industrial upgrading guidelines promote domestic equipment substitution through GB standards certification. The Yangtze River Delta cluster has become the world's densest concentration of high-speed servo-electric punching systems for thermal management components.
Japan
Electronics fabricators in the Chubu and Kansai regions are replacing legacy hydraulic equipment to satisfy METI energy efficiency standards. JIS certification requirements shape procurement specifications for precision press automation. Osaka's industrial belt leads adoption of regenerative braking systems in electromechanical coil processing lines.
United States
Tier-1 automotive suppliers in Michigan and Ohio are retooling for electric vehicle platform metal content shifts. OSHA lockout-tagout regulations and EPA metalworking fluid discharge rules constrain coolant system designs. The Southeast manufacturing corridor attracts greenfield press shop investments seeking proximity to battery assembly plants.
India
Automotive component producers in Maharashtra and Tamil Nadu are deploying coil processing lines to qualify for PLI scheme domestic production incentives. BIS certification requirements create compliance complexity for imported servo-electric systems. The Chennai-Bengaluru industrial belt concentrates new capacity for EV structural part fabrication.
Coil Fed Punching and Cutting Machines Market Vendor Landscape
Capability concentration sits with Italian and Spanish engineering specialists; scale advantage sits with diversified industrial machinery conglomerates. The vendor base separates into three tiers: heritage European precision engineers, Asian cost-optimized fabricators, and integrated automation providers. Strategic moves center on geographic expansion into India's PLI-attracted investments and technology licensing for servo-electric architectures.
Among Italian heritage engineers, DIMECO and Dallan S.p.A. occupy positions emphasizing deep specialization in combination machine configurations. DANOBAT GROUP exemplifies the integrated automation tier with its Spanish engineering base. These three represent distinct competitive archetypes: DIMECO anchors high-precision appliance manufacturing applications, Dallan S.p.A. exemplifies roll-forming-integrated system design, and DANOBAT GROUP sits within the heavy-gauge metalworking technology leadership segment.
| Leading Market Players |
|---|
| DIMECO |
| Dallan S.p.A. |
| DANOBAT GROUP |
| HACO |
| Pivatic Oy |
| Produtech s.r.l. |
| Wuxi Qingyuan Laser Technology Co., Ltd |
| Dalcos |
| SMD Machinery |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's EV battery tray manufacturing cluster commands downstream pricing leverage through concentrated demand for high-speed servo-electric punching systems. OEM procurement teams in this corridor unbundle service contracts from capital purchases, compressing vendor margins while amplifying buyer negotiation power across Asia-Pacific procurement patterns.
Pricing Analysis
Italian-engineered combination machines command 25-40% premiums over Asian-fabricated alternatives in European appliance and automotive applications. Pricing stratifies across premium servo-electric architectures, standard hydraulic configurations, and economy mechanical systems based on energy efficiency certification tiers and after-sales service bundling. Cost compression in the standard tier intensifies as Chinese domestic manufacturers achieve GB standards certification for local substitution. Tier-1 automotive suppliers demonstrate lowest price sensitivity, prioritizing uptime guarantees and direct vendor relationships over initial capital expenditure.
Supply Chain Analysis
Export control regimes on high-precision linear motor drives and motion control systems limit technology flows from Japan and Germany to emerging manufacturing jurisdictions. Manufacturing concentration rests in Italy, Spain, and China for complete machine builds, with critical dependencies on German-built servo drives, Japanese precision bearings, and Chinese steel coil feedstock. Single-source vulnerability concentrates in specialized high-strength aluminum coil supply from limited rolling mill operators. Distribution runs through direct OEM sales channels for large automotive accounts and regional distributor networks for mid-tier metalworking facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-electric displacement of hydraulic architectures constitutes a high-growth disruption as factory energy mandates harden across manufacturing jurisdictions. EU CO2 regulations and Japan's METI standards have created irreversible replacement cycles that restructure competitive positioning.
For Market Incumbents: Build switching-cost moats through digital twin integration and predictive maintenance service contracts that embed control system expertise. Defend against laser blanking substitution by emphasizing thick-gauge capability and combination machine process consolidation. Deepen backward integration into servo drive calibration and motion control software to capture margin from electromechanical architecture transitions. For New Entrants and Emerging Players: India's PLI-attracted automotive manufacturing investments represent the most penetrable geography for greenfield coil processing line deployment. Target contract manufacturers in the Chennai-Bengaluru industrial belt seeking qualification for domestic production incentives. Establish technology licensing partnerships with European precision engineering specialists to bypass JIS and CE certification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a capital-goods cyclical play because automotive lightweighting mandates and EV battery enclosure demand create sustained replacement cycles across multiple regulatory jurisdictions. Acquisition targets should concentrate on Italian and Spanish heritage engineers with installed base presence in combination machine configurations. Monitor fiber laser blanking feed rate improvements on sub-3mm gauges as the critical substitution threat indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Architecture Transition | Reduces factory power consumption to meet EU machinery directive energy efficiency thresholds. |
| Digital Twin Commissioning Integration | Compresses startup timelines for German Tier-1 automotive supplier press line deployments. |
| GB Standards Certification Pathway | Enables Chinese domestic manufacturers to displace imported systems in MIIT-promoted upgrading programs. |
| Roll-Forming Combination Machine Development | Captures solar racking demand for continuous profile production with reduced handling steps. |
| Service Contract Unbundling Response | Addresses Jiangsu province procurement patterns separating maintenance subscriptions from capital purchases. |
Methodological Framework
Desk research of trade association technical publications, customs shipment records, and machinery directive compliance databases preceded structured interviews with plant engineers, OEM procurement teams, aftermarket service directors, and automation integration specialists. Primary fieldwork across Germany's Baden-Württemberg precision metalworking corridor, China's Yangtze River Delta battery manufacturing cluster, and Japan's Chubu electronics fabrication belt was validated against secondary sources including KBA facility standards filings, METI energy efficiency audit reports, and MIIT industrial upgrading guidelines. Bottom-up equipment shipment analysis and top-down manufacturing capacity estimates were triangulated to establish market sizing.
Forecast assumptions held EU CO2 fleet emission reduction mandates, Japan's METI kilowatt-hour reduction standards, and China's dual carbon goals as fixed regulatory drivers across the projection horizon. Segmentation modeling incorporated technology type, application end-use, and regional production cluster dimensions. CAGRs were derived from installed base growth rates, replacement cycle acceleration factors, and penetration curve analysis for servo-electric architectures. Industry-specific inputs included automotive aluminum content per vehicle trajectories and EV battery enclosure fabrication capacity buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified industrial machinery conglomerates would shift outcomes. Material shifts in fiber laser cutting feed rate capabilities on thin-gauge aluminum or sudden relaxation of EU machinery directive safety interlock requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Portable Grinders Market
Tools
Cordless Power Drill Market
Tools
Hand Saw Market
Tools
Chainsaw Market
Tools
Belt File Sander Market
Tools
Multi Spindle Machines Market
Tools
Europe Machine Tools Market
Tools
Tile Cutter Market
Tools
Grinding Discs Market
Tools
Edge Banders Market
Tools
Global Table Saws Market
Tools
Screw Fastener Market
Tools
Fastening Power Tools Market
Tools
Pneumatic Marking Machines Market
Tools
Edge Bending Machine Market
Tools
Global Cordless Power Tools Market