
 Gear Shaping Machine Market | 2026-2036
Gear Shaping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Shaping Machine Market Analytics
The EU Green Deal's carbon border adjustment mechanism is consolidating demand for energy-efficient gear production equipment across European manufacturing bases. Gleason Corp. leverages its vertical integration into cutting tool supply to control lifecycle costs for automotive tier-one suppliers. Liebherr anchors high-precision aerospace gear shaping through specialized platforms that meet tight tolerances for turbine transmission systems. Klingelnberg differentiates via measurement-integrated shaping cells that close quality loops in single setups.
A gear shaping machine is a metal-cutting machine tool that uses a reciprocating cutter to generate involute gear profiles through precise indexing motions, typically achieving DIN 4-7 accuracy grades depending on machine class and tooling condition. The equipment serves primarily to produce internal and external spur gears, helical gears, and special tooth forms where hobbing remains impractical due to access constraints or blank geometry. CNC gear shapers now dominate capital procurement budgets as programmable axes eliminate mechanical change gears and reduce setup intervals from hours to minutes. Horizontal gear shapers retain position in heavy-vehicle and marine applications where large-diameter workpieces require rigid overarm support structures. Precision gears for electric vehicle reduction drives represent the fastest-growing application segment as torque density requirements intensify tooling performance demands.
The EPA enforces metalworking fluid discharge standards that shape coolant system designs and waste handling configurations on machines sold into US manufacturing facilities. REACH chemical restrictions in Europe limit certain extreme-pressure additives in cutting oils, pushing suppliers toward synthetic and vegetable-based formulations that maintain tool life under aggressive cutting parameters. ISO 6336 and AGMA 2001 gear rating standards determine the dimensional and surface finish specifications that shaping equipment must repeatably achieve. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's tightening benchmarks redirect capital allocation toward platforms with documented energy consumption and carbon footprint credentials.
Market Dynamics
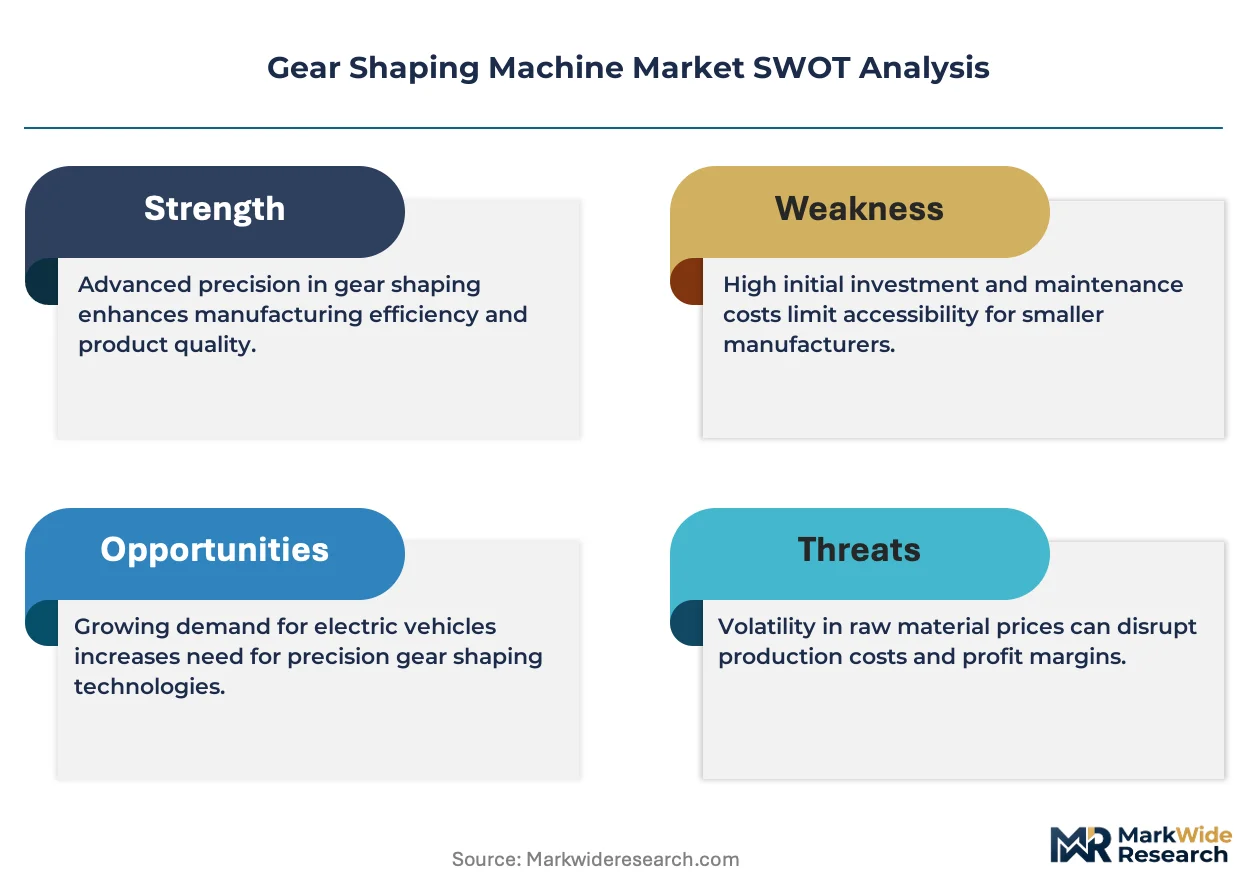
The EU Green Deal's carbon border adjustment mechanism is consolidating demand for energy-efficient gear production equipment across European manufacturing bases. Automotive manufacturers in Germany and Japan are expanding precision gear production capacity to support electric drivetrain transitions, reshaping capital allocation patterns for CNC shaping platforms.
Growth Catalysts
- Electric vehicle reduction drives:Torque density requirements for EV powertrains are intensifying demand for precision gears that shaping machines produce with DIN 4-7 accuracy grades.
- REACH chemical restrictions:European regulations limiting extreme-pressure additives in cutting oils are pushing suppliers toward synthetic formulations that maintain tool life under aggressive parameters.
- Yangtze River Delta concentration:China's machine tool cluster co-locates domestic suppliers and multinational service centers, accelerating technology transfer and localized support capabilities.
Market Restraints
- Tungsten carbide supply volatility:Cutting tool material costs fluctuate with concentrated mining operations in specific geographies, pressuring tooling lifecycle economics.
- Horizontal shaper platform limitations:Heavy-vehicle and marine applications require rigid overarm structures that constrain feed rates and throughput compared to vertical configurations.
- EPA discharge compliance:Metalworking fluid standards in US facilities add capital burden to coolant system designs and waste handling configurations.
Strategic Opportunities
- Measurement-integrated shaping cells:Quality-loop closure in single setups reduces inspection bottlenecks and work-in-process inventory for aerospace gear producers.
- Dual carbon goals in China:Beijing's industrial emissions benchmarks are redirecting state-backed capital toward documented energy consumption credentials for equipment procurement.
- Helical gear specialization:Internal gear applications where hobbing remains impractical offer protected niches for shaping technology against competing processes.
Industry Challenges
- CNC programming expertise gaps:Programmable axes eliminate mechanical change gears but require operators capable of parametric setup optimization, compressing effective labor pools.
- ISO 6336 certification timelines:Gear rating standard compliance for dimensional and surface finish specifications extends validation cycles for new machine installations.
- Legacy mechanical change gear integration:Hybrid retrofits of existing installed base with modern control architectures create commissioning complexity and downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Shaping Machine Market |
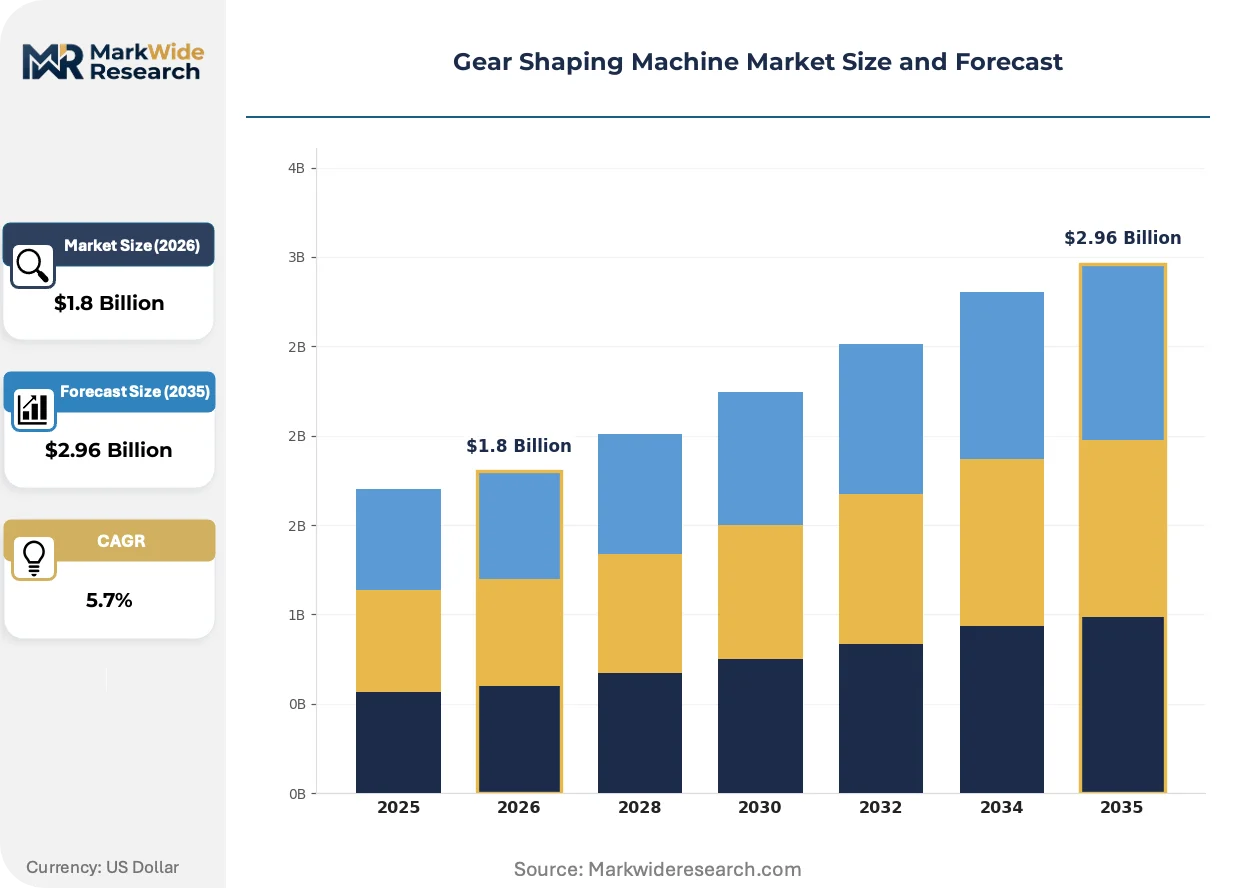
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Gear Shapers, Horizontal Gear Shapers, CNC Gear Shapers, Manual Gear Shapers Technology: Hobbing, Broaching, Shaving, Finishing End User: Aerospace, Automotive, Marine, Industrial Machinery Application: Precision Gears, Spiral Gears, Bevel Gears, Worm Gears |
| Companies Covered | Liebherr, Gleason Corp., Klingelnberg, Bourn & Koch, EMAG GmbH, DMG MORI Co. Ltd., Mitsubishi Heavy Industries, HAMAI Company, Reishauer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Shaping Machine Market Evolving Landscape
Software-defined motion control architectures are displacing mechanical indexing systems across precision gear production. The convergence of programmable servo axes with real-time process monitoring is compressing setup intervals from hours to minutes.
Direct-drive rotary tables with integrated torque motors are modularizing workpiece positioning subsystems in next-generation shapers. Automotive tier-one suppliers in Stuttgart and Nagoya are adopting these configurations to eliminate backlash and improve indexing repeatability for high-volume EV gear production. The technology is modularizing machine architectures into swappable axis modules that reduce field service complexity and spare parts proliferation.
REACH chemical restrictions in Europe are limiting certain extreme-pressure additives in cutting oils, pushing suppliers toward synthetic and vegetable-based formulations. Machine builders must redesign coolant delivery systems to maintain thermal stability and chip evacuation under these alternative chemistries. German and Swiss equipment manufacturers are responding fastest, embedding closed-loop filtration and temperature control as standard rather than optional configurations.
Buyer consolidation among automotive OEMs is concentrating procurement authority at fewer engineering centers. Tier-one suppliers now face consolidated technical specifications and volume commitments that favor vendors with global service networks over regional specialists. This pattern is most visible in China's Yangtze River Delta, where multinational service centers co-locate with domestic suppliers to capture concentrated demand from BYD, NIO, and Geely powertrain divisions.
Gear Shaping Machine Market Segmentation
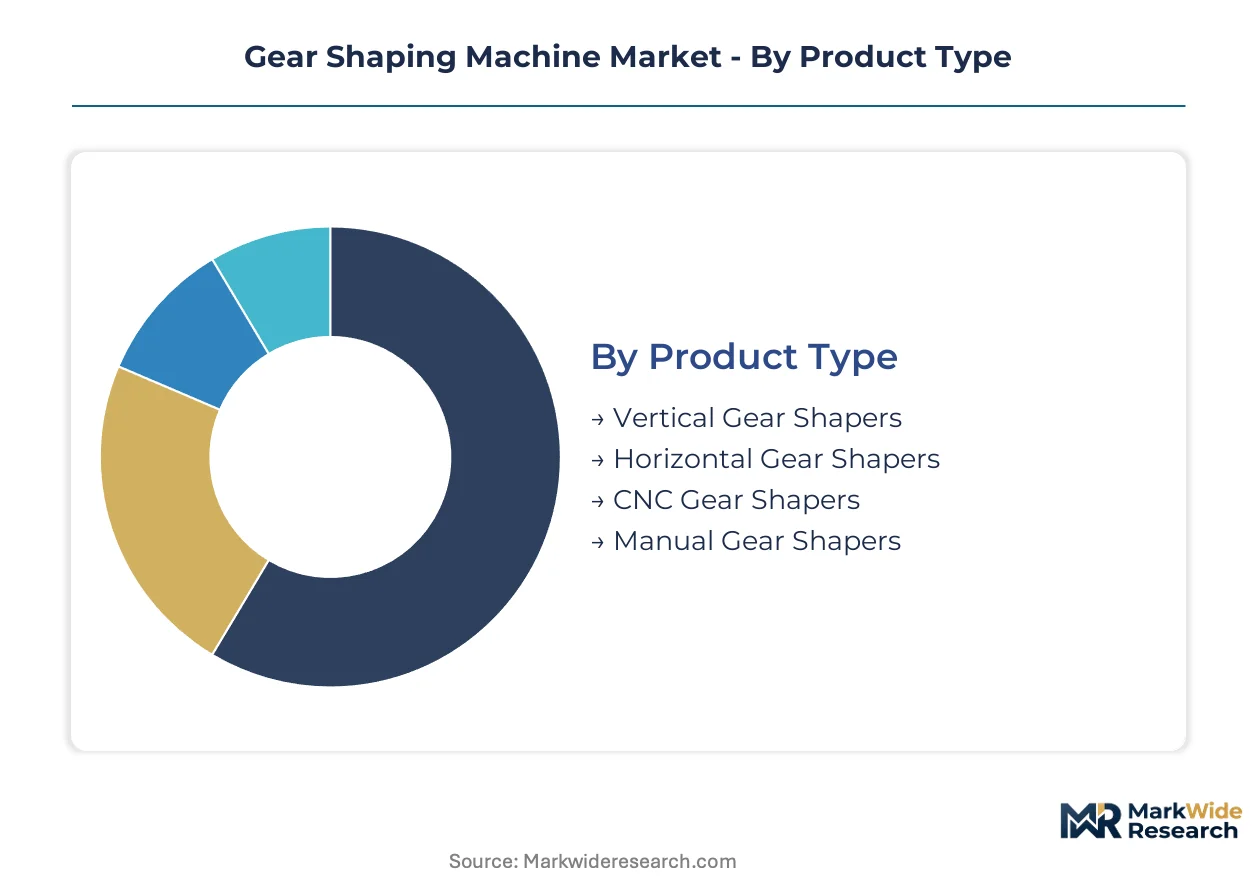
Gear shaping machine procurement patterns diverge sharply across product configurations, with certification requirements from ISO 6336 and AGMA 2001 determining which equipment classes qualify for aerospace versus automotive contracts. End-use specifications for DIN 4-7 accuracy grades reshape technology selection and capital allocation priorities across manufacturing bases.
Product Type:
ISO 6336 gear rating compliance and AGMA 2001 dimensional specifications impose distinct certification burdens across shaper configurations, with CNC platforms facing extended validation timelines compared to mechanical alternatives.
- CNC Gear Shapers:Programmable servo axes eliminate mechanical change gears and compress setup intervals from hours to minutes. Demand concentrates in Germany and Japan where automotive manufacturers expand precision gear capacity for electric drivetrain transitions, driven by torque density requirements for EV reduction drives.
- Vertical Gear Shapers:Dominant configuration for general-purpose gear production with rigid column structures supporting high-speed reciprocation. China's Yangtze River Delta machine tool cluster drives procurement volume as domestic suppliers and multinational service centers co-locate to capture EV powertrain demand.
- Horizontal Gear Shapers:Retain position in heavy-vehicle and marine applications requiring rigid overarm support for large-diameter workpieces.
- Manual Gear Shapers:Survive in maintenance operations and developing manufacturing bases where mechanical simplicity outweighs throughput requirements.
CNC Gear Shapers sit at the top of the volume ranking, with Vertical Gear Shapers climbing the fastest.
Technology:
Cost tier differentiation separates high-capital automated systems from entry-level mechanical platforms, with tooling lifecycle economics determining total cost of ownership across process categories.
- Shaving:Final tooth profile refinement process achieving surface finishes required for DIN 4-5 precision grades. Stuttgart automotive tier-one suppliers deploy shaving cells for EV reduction gear production where noise and efficiency specifications are most demanding.
- Finishing:Encompasses grinding and honing operations for post-shaping dimensional correction. Japanese aerospace gear producers in Nagoya favor finishing-integrated cells for turbine transmission components requiring tight tolerances.
- Hobbing:Competing continuous-generation process displacing shaping in external gear applications with fewer access constraints.
- Broaching:Specialized for internal splines and keyways where shaping cutter geometry proves impractical.
Shaving commands the premium pricing tier, with Finishing gaining share fastest in aerospace-qualified installations.
End User:
Application-specific margin structures vary dramatically, with aerospace contracts supporting equipment amortization over longer production runs compared to high-volume automotive programs.
- Automotive:Largest demand concentration for gear shaping equipment, driven by electric vehicle reduction drive requirements. Germany's automotive OEMs specify DIN 4-6 accuracy grades for powertrain gears, with procurement authority consolidating at fewer engineering centers.
- Aerospace:Liebherr and specialized suppliers anchor demand for turbine transmission gears requiring tight tolerances. EU Green Deal emissions benchmarks push gear producers toward energy-efficient CNC platforms with documented carbon credentials.
- Marine:Heavy-gear applications favor horizontal shaper configurations with rigid overarm structures for large-diameter propulsion components.
- Industrial Machinery:General-purpose gear demand spans construction equipment, mining machinery, and material handling systems with moderate precision requirements.
Automotive generates the highest absolute equipment demand, with Aerospace expanding most quickly on a percentage basis.
Application:
Customer type segmentation separates OEM captive production from contract gear manufacturers, with volume commitments and technical specifications diverging across procurement channels.
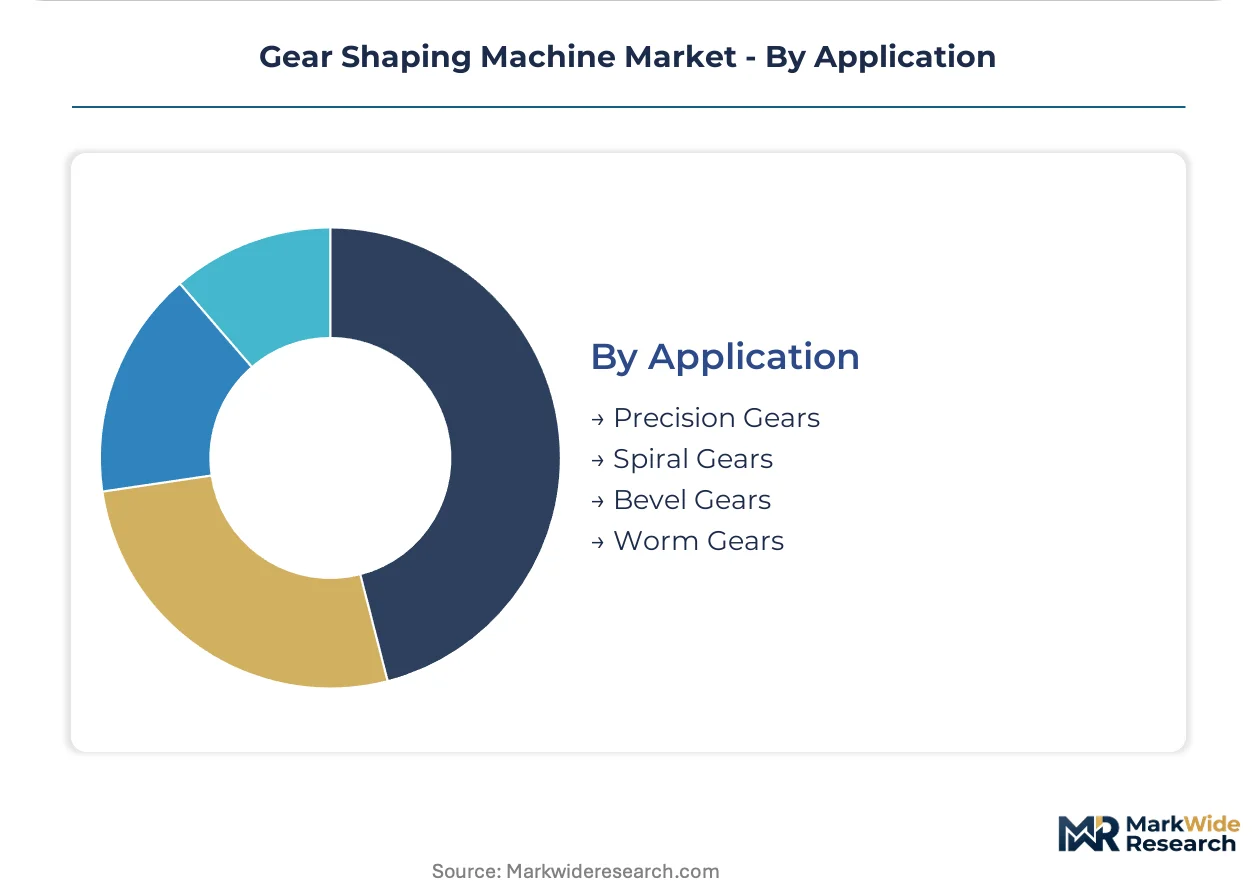
- Precision Gears:DIN 4-7 accuracy grade components for power transmission systems requiring controlled backlash and noise characteristics. Electric vehicle reduction drives represent the steepest expansion trajectory as torque density intensifies tooling performance demands.
- Spiral Gears:Helical tooth forms where hobbing access constraints protect shaping technology market position. China's BYD, NIO, and Geely powertrain divisions concentrate demand in the Yangtze River Delta cluster.
- Bevel Gears:Conical gear forms typically produced on specialized generating equipment rather than conventional shapers.
- Worm Gears:Screw-type drives for high-reduction applications where shaping cutter geometry accommodates worm wheel production.
Precision Gears dominate installed capacity utilization, with Spiral Gears gaining fastest among EV-qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern gear shaping technology through Stuttgart and Munich machine tool clusters established in the early twentieth century. Japanese manufacturers scaled precision production for automotive applications during the post-war industrial expansion. These historical foundations continue shaping contemporary demand patterns and technology transfer flows.
Germany
Automotive OEMs in Stuttgart and Munich specify DIN 4-6 accuracy grades for EV reduction drives, consolidating procurement authority at fewer engineering centers. The EU Green Deal's carbon border adjustment mechanism redirects capital toward CNC platforms with documented energy credentials. Bavaria's machine tool cluster anchors high-precision aerospace gear production for turbine transmission systems.
Japan
Nagoya-based aerospace gear producers favor measurement-integrated shaping cells requiring tight tolerances for turbine components. METI's industrial emissions benchmarks push equipment procurement toward energy-efficient platforms. The Chubu region concentrates precision gear manufacturing capacity serving Toyota and Honda powertrain divisions.
China
BYD, NIO, and Geely powertrain divisions concentrate demand in the Yangtze River Delta machine tool cluster. Beijing's dual carbon goals redirect state-backed capital toward equipment with verified energy consumption documentation. Domestic suppliers co-locate with multinational service centers in Shanghai and Suzhou to capture EV-qualified supplier contracts.
United States
EPA metalworking fluid discharge standards shape coolant system designs for machines sold into Michigan and Ohio automotive manufacturing facilities. The Inflation Reduction Act's clean vehicle tax credits accelerate EV powertrain investment across Midwest industrial corridors. Detroit-area tier-one suppliers expand precision gear capacity to support domestic electric drivetrain production.
Switzerland
Swiss gear producers serving medical and precision instrument markets demand DIN 4-5 accuracy grades that justify premium equipment configurations. REACH chemical restrictions limit extreme-pressure additives in cutting oils, pushing toward synthetic formulations. The Zurich-Geneva industrial corridor hosts specialized measurement-integrated shaping cell installations.
Gear Shaping Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-complexity dimensions. The vendor base organizes into three tiers: multinational platform specialists with global service networks, regional fabricators serving captive automotive supply chains, and emerging Chinese suppliers capturing domestic EV demand. Consolidation pressures intensify as automotive OEM procurement authority concentrates at fewer engineering centers. Dominant competitive moves include backward integration into cutting tool supply and geographic co-location with high-volume demand clusters.
Among German-based platform specialists, Liebherr and Klingelnberg occupy positions exemplifying premium-tier positioning through aerospace-qualified installations. Gleason Corp. represents the archetype of upstream control over tooling supply chains. These three companies anchor the competitive structure through differentiated specializations: precision aerospace applications, measurement-integrated quality systems, and captive cutting tool economics.
| Leading Market Players |
|---|
| Liebherr |
| Gleason Corp. |
| Klingelnberg |
| Bourn & Koch |
| EMAG GmbH |
| DMG MORI Co. Ltd. |
| Mitsubishi Heavy Industries |
| HAMAI Company |
| Reishauer AG |
| Others |
Value Network & Pricing Analysis
Tungsten carbide powder indices cascade through gear shaping machine supply chains into three distinct pricing tiers anchored by certification grade, tooling lifecycle economics, and after-sales service bundling. Buyers in automotive and aerospace segments face divergent cost structures as raw material volatility concentrates pricing power among cutting tool suppliers with captive carbide sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by DIN accuracy certification and measurement integration capabilities. Premium tiers command substantial markups for aerospace-qualified DIN 4-5 systems with closed-loop quality cells, while standard configurations serve high-volume automotive with DIN 6-7 grades. Cost compression in economy tiers intensifies as Chinese domestic suppliers scale CNC platform production for the Yangtze River Delta cluster. Automotive tier-one suppliers exhibit highest price sensitivity due to consolidated procurement authority, whereas aerospace contractors prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate qualified supplier lists spanning Germany, Japan, and China for critical motion control subsystems. Machine builders draw from concentrated tungsten carbide supplies in China and cobalt processing facilities in the Democratic Republic of Congo for cutting tool fabrication. Single-source vulnerability in high-precision linear motion components from Swiss and German specialists creates bottleneck exposure for lead screw and torque motor procurement. Distribution runs through manufacturer-direct channels for large aerospace contracts, while regional service centers in Stuttgart, Nagoya, and Suzhou handle automotive volume deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gear shaping machine market functions as a stable compounder, underpinned by irreversible capital commitments from automotive OEMs electrifying powertrain architectures across multiple manufacturing bases.
For Market Incumbents: Acquire cutting tool manufacturing assets to secure carbide supply continuity against mining concentration risk. Deepen captive production of torque motors and direct-drive rotary tables to insulate margins from precision component shortages. Prioritize certification pre-qualification for EU Green Deal energy efficiency benchmarks ahead of carbon border adjustment mechanism enforcement.
For New Entrants and Emerging Players: Launch via regional service center partnerships in China's Yangtze River Delta to bypass capital-intensive manufacturing scale requirements. Target manual gear shaper replacement cycles in Southeast Asian and Indian maintenance operations where mechanical simplicity still dominates procurement criteria. Emphasize software-defined motion control architectures as retrofit solutions for legacy installed base modernization.
For Investors and Strategic Acquirers: Asymmetric upside sits with measurement-integrated shaping cell specialists serving aerospace turbine transmission demand. Long-term viability across the analysis window rests on durable aftermarket service revenue streams rather than equipment replacement cycles alone. Monitor EV reduction drive torque density specifications as the signal indicating acceleration or deceleration in precision gear capital expenditure intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutting Tool Supply | Gleason Corp.'s captive carbide sourcing controls lifecycle costs for automotive tier-one contracts. |
| Measurement-Integrated Shaping Cell Deployment | Klingelnberg's quality-loop closure reduces inspection bottlenecks for Nagoya aerospace producers. |
| Regional Service Center Co-location | Multinational centers in Suzhou capture concentrated BYD and NIO powertrain procurement authority. |
| Synthetic Cutting Fluid System Redesign | German builders embed closed-loop filtration responding to REACH chemical restrictions on extreme-pressure additives. |
| Software-Defined Motion Control Migration | Programmable servo axes displace mechanical indexing, compressing setup intervals for Stuttgart EV gear production. |
Research Methodology
Coverage spans Germany, Japan, China, and the United States, with primary inputs from each manufacturing cluster. The analysis combines structured interviews with plant engineers at automotive tier-one suppliers, procurement leads at aerospace gear producers, and aftermarket service heads at multinational machine tool distributors. Secondary validation draws from customs trade data for machine tool imports, SEC filings of listed equipment manufacturers, and ISO certification registries. Bottom-up equipment shipment tallies triangulate against top-down capital expenditure surveys from metalworking industry associations.
Rate-of-change decomposition separates volume drivers from price mix effects across the projection horizon. The analytical framework models segmentation by product configuration, end-use industry, technology tier, and regional production cluster. CAGRs derive from equipment replacement cycle analysis, capacity expansion announcements, and regulatory compliance timelines. Industry-specific forecast inputs include EV powertrain penetration assumptions and aerospace engine platform development schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tungsten carbide supply disruption or accelerated hobbing technology substitution. Deviation in Chinese dual carbon goal enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Truck Crane Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Snow Removal Market