
 Core Drill Automatic Feeding Machine Market | 2026-2036
Core Drill Automatic Feeding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Core Drill Automatic Feeding Machine Market Outlook
OSHA silica exposure limits is pivoting capital allocation toward dust-contained automatic feeding systems. Hilti Corporation leverages its vertical integration into diamond tooling to sustain premium positioning in North American infrastructure contracts. Epiroc AB anchors its underground mining portfolio with pneumatic feeding architectures that dominate Australian and Scandinavian tunnelling projects.
A core drill automatic feeding machine is a mechanized drilling apparatus engineered to advance diamond-impregnated or carbide-tipped core bits through reinforced concrete, rock formations, or composite substrates at controlled feed rates, typically achieving rotational speeds between 300 and 1,500 RPM depending on material density. The system eliminates manual pressure application, ensuring consistent penetration depth and operator safety in continuous-duty commercial and industrial environments. Vertical drill configurations command the dominant share in high-rise construction and geotechnical surveying, while pneumatic technology leads in underground mining where explosive atmosphere compliance is mandatory. Electric systems are gaining fastest in European research labs and controlled indoor construction sites where emissions restrictions limit combustion or compressed air alternatives.
The US Department of Labor's Mine Safety and Health Administration enforces continuous miner automation standards that directly mandate automatic feed mechanisms in coal and hard-rock operations. The EU Machinery Directive, implemented through CE marking requirements, mandates emergency stop integration and two-hand control architectures that reshape product design for European market access. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content rules that threaten to fragment procurement strategies across Atlantic and Asia-Pacific supply corridors.
Market Dynamics
OSHA silica exposure mandates are compressing replacement cycles for dust-contained automatic feeding systems across North American infrastructure and mining operations, forcing capital reallocation toward compliant architectures.
Growth Catalysts
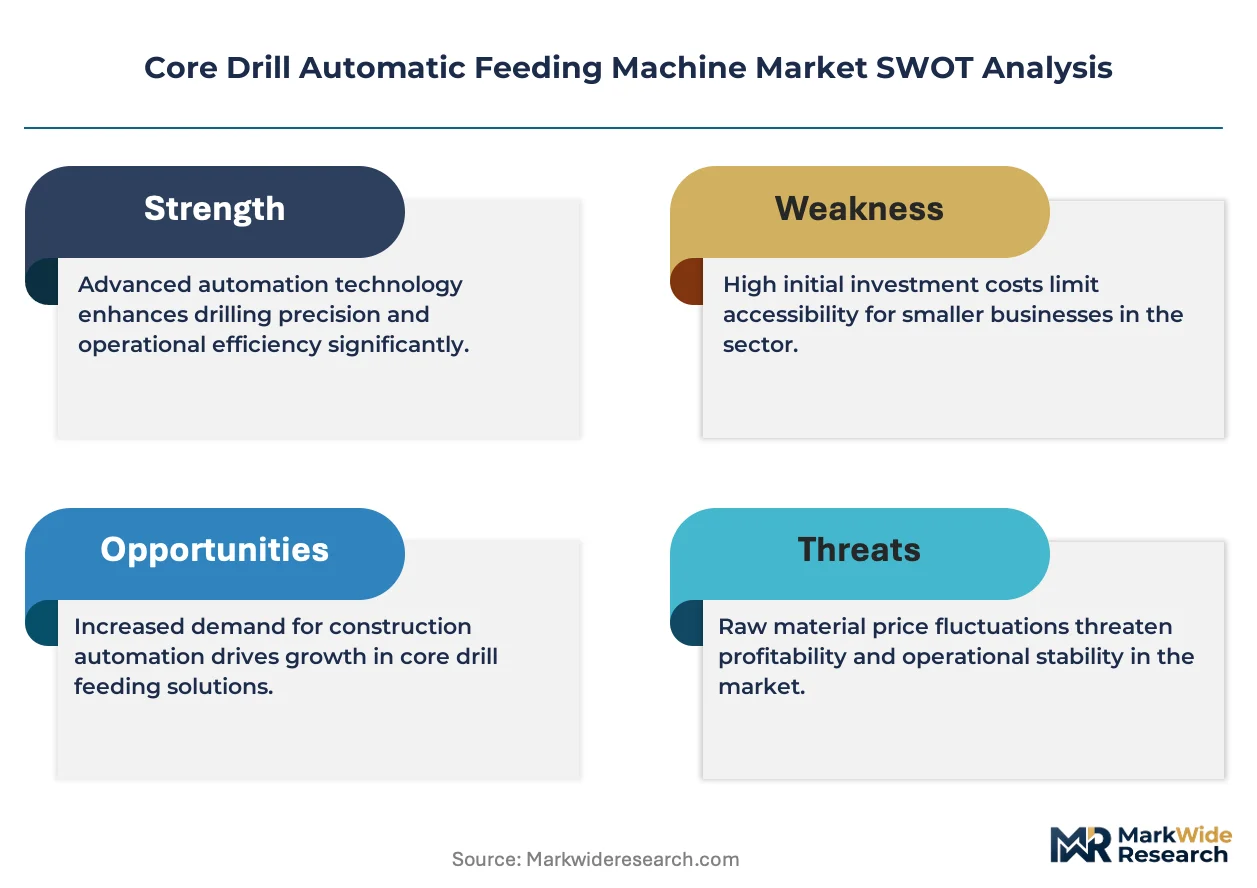
- Underground Mining Automation:MSHA continuous miner standards in the United States mandate automatic feed mechanisms in coal and hard-rock extraction, accelerating equipment turnover.
- EU Machinery Directive:CE marking requirements for emergency stop integration and two-hand control architectures are reshaping product design for European market access.
- Pneumatic Technology Leadership:Explosive atmosphere compliance in Australian and Scandinavian tunnelling projects drives specification of pneumatic feeding architectures over electric alternatives.
Market Restraints
- Carbon Border Adjustment Mechanisms:Emerging EU carbon border taxes threaten to fragment procurement strategies across Atlantic supply corridors, raising landed costs for non-EU manufacturers.
- Diamond Tooling Input Concentration:Synthetic diamond supply concentrates in limited production clusters, exposing margins to raw material volatility and geopolitical friction.
- Compressed Air Infrastructure Dependency:Pneumatic system adoption requires captive compressor capacity, creating capital barriers for smaller contractors and rental fleet operators.
Strategic Opportunities
- European Research Laboratory Expansion:Electric automatic feeding systems face expanding specification in controlled indoor construction sites and materials science facilities where emissions restrictions exclude combustion or compressed air alternatives.
- Local Content Rule Arbitrage:Evolving domestic procurement mandates in resource-rich economies create white space for assembly partnerships that satisfy regional content thresholds.
- Sensor-Drill Convergence:Integration of real-time penetration analytics with automatic feed control enables predictive maintenance contracts and performance-guaranteed service models.
Industry Challenges
- Certification Timeline Compression:CE marking and MSHA approval processes for modified control architectures extend product launch windows, delaying revenue recognition on redesigned platforms.
- Legacy Fleet Integration Friction:Retrofit of automatic feeding mechanisms onto existing drill rigs demands custom mechanical interfaces, fragmenting engineering resources and extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Core Drill Automatic Feeding Machine Market |
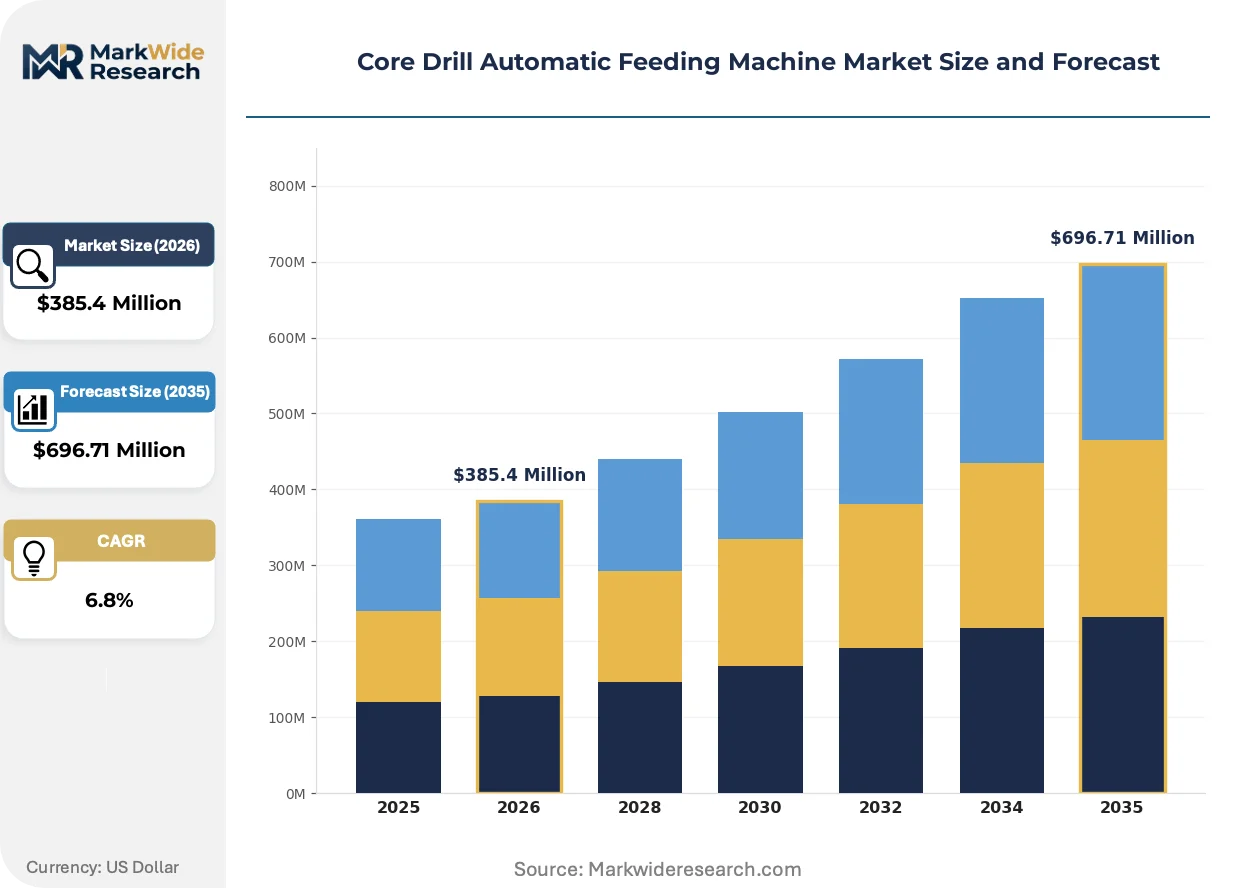
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Drill, Horizontal Drill, Handheld Drill, Specialty Drill Technology: Pneumatic, Hydraulic, Electric, Manual End User: Construction, Mining, Oil & Gas, Research Labs Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Hilti Corporation, Atlas Copco, Husqvarna Group, Robert Bosch Tool Corporation, CS Unitec, BAIER, Golz, Scientific Drilling International, Epiroc AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Core Drill Automatic Feeding Machine Market Strategic Shifts
Feed rate optimization algorithms and closed-loop penetration control are displacing open-loop hydraulic architectures across precision drilling applications, compressing the performance gap between manual and automatic systems.
Brushless DC motor drives with integrated torque feedback are absorbing market share from traditional hydraulic feed systems in high-rise construction and geotechnical surveying. European equipment rental fleets are specifying these architectures for indoor demolition and core sampling contracts where noise and emissions restrictions apply. The technology is absorbing service contract value previously captured by hydraulic maintenance providers, reshaping aftermarket revenue pools.
REACH substance restrictions and F-Gas Regulation phase-down schedules in the European Union are eliminating certain hydraulic fluid formulations from certified equipment supply chains. Manufacturers serving German precision manufacturing corridors are reformulating lubrication systems to maintain CE marking compliance. Underground mining specialists with pneumatic portfolios face limited direct impact but monitor for downstream pressure on sealed component specifications.
Rental channel expansion is fragmenting traditional direct-sales relationships in commercial construction verticals. Equipment-as-a-service models with bundled maintenance and consumable provisioning are displacing capital purchase decisions for mid-tier contractors in Australian mining services and US infrastructure rehabilitation markets. The shift is most visible in urban core drilling contracts where project duration uncertainty favors operational expense treatment over balance sheet commitment.
Core Drill Automatic Feeding Machine Market Segmentation
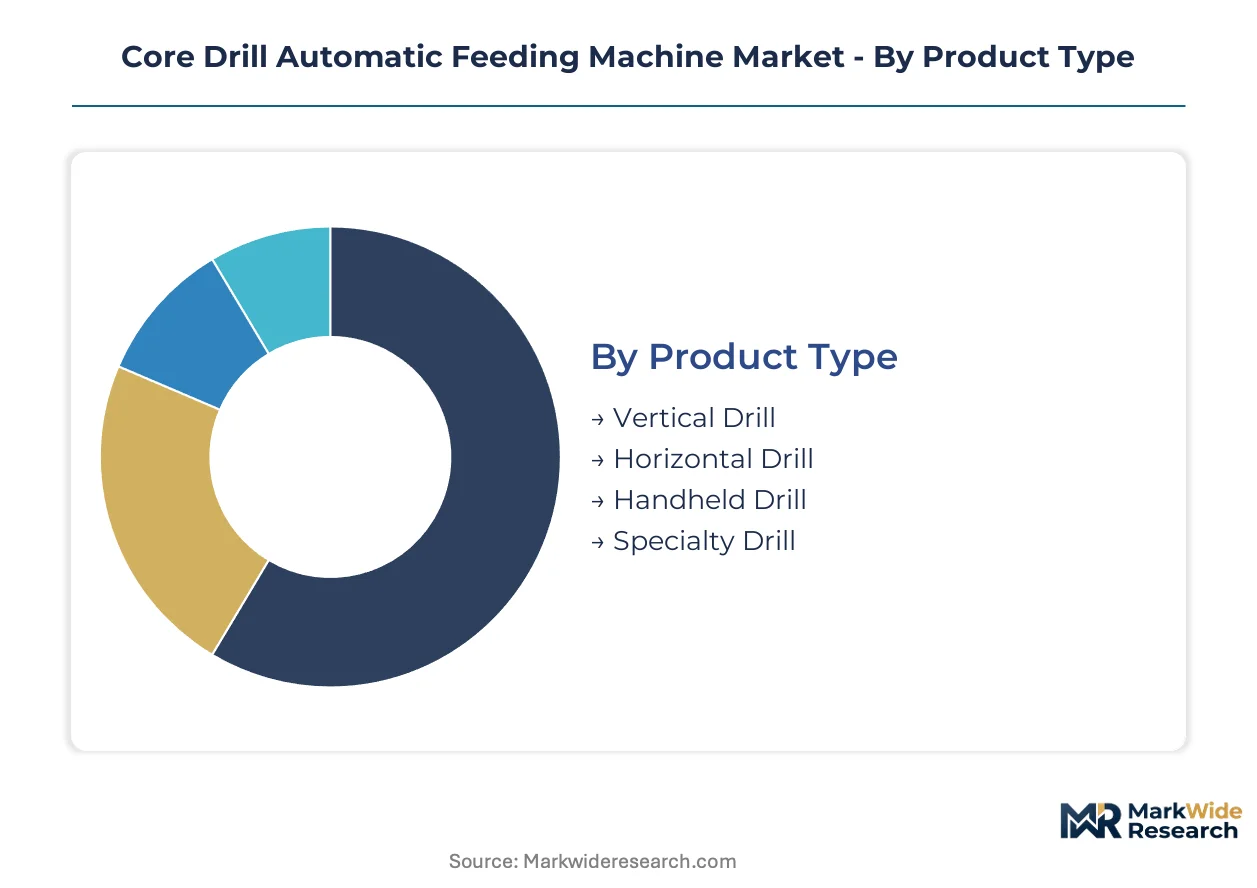
Segmentation in core drill automatic feeding machines reveals how automation depth varies by mounting configuration, power source, and procurement pathway. Equipment specification differs sharply between integrated mining systems and standalone rental fleet deployments.
Product Type:
Standalone vertical configurations dominate high-rise construction, while embedded horizontal systems integrate into continuous mining platforms.
- Vertical Drill:Column-mounted rigs achieve penetration depths exceeding 600mm in reinforced concrete. Demand concentrates in German precision manufacturing corridors and UAE high-rise developments where OSHA silica containment mandates force dust-integrated architectures.
- Horizontal Drill:Bridge-mounted or track-based systems drill parallel to substrate surfaces. Australian underground mining operations specify these for tunnel boring pre-drilling where MSHA continuous miner standards mandate automatic feed integration.
- Handheld Drill:Portable units with automatic feed attachments serve renovation contractors in controlled indoor environments.
- Specialty Drill:Custom-configured rigs address nuclear decommissioning and offshore platform maintenance with explosion-proof specifications.
Vertical drill configurations lead volumes today; horizontal drill systems are gaining share fastest in mining automation retrofits.
Technology:
Cost tier separation runs from capital-intensive pneumatic infrastructure to low-entry electric alternatives.
- Pneumatic:Compressed-air systems deliver intrinsic safety in explosive atmospheres without electrical ignition risk. Australian and Scandinavian tunnelling projects specify these exclusively where methane accumulation hazards exist.
- Electric:Brushless DC architectures with integrated torque feedback capture indoor demolition contracts in European cities where REACH substance restrictions and F-Gas Regulation phase-downs eliminate hydraulic alternatives.
- Hydraulic:Open-loop systems persist in legacy mining fleets and heavy infrastructure rehabilitation.
- Manual:Non-automated feed mechanisms survive only in developing market rental tiers and emergency backup specifications.
Pneumatic technology leads volumes today; electric systems are expanding most quickly in emissions-restricted urban construction.
End User:
Application maturity separates established mining automation from emerging research laboratory specifications.
- Construction:Commercial and infrastructure contractors deploy vertical and handheld configurations for core sampling, anchor installation, and structural assessment. German equipment rental fleets specify electric automatic feeding systems for indoor demolition where noise ordinances apply.
- Mining:Underground hard-rock and coal operations mandate automatic feed mechanisms under MSHA continuous miner standards. Australian replacement cycles drive equipment turnover as surface deposits deplete.
- Oil & Gas:Offshore platform maintenance and pipeline construction require explosion-proof pneumatic or hydraulic architectures.
- Research Labs:Materials science and geotechnical facilities specify precision electric systems with closed-loop penetration control for repeatable sample extraction.
Mining leads volumes today; research labs are climbing the fastest as materials science funding expands.
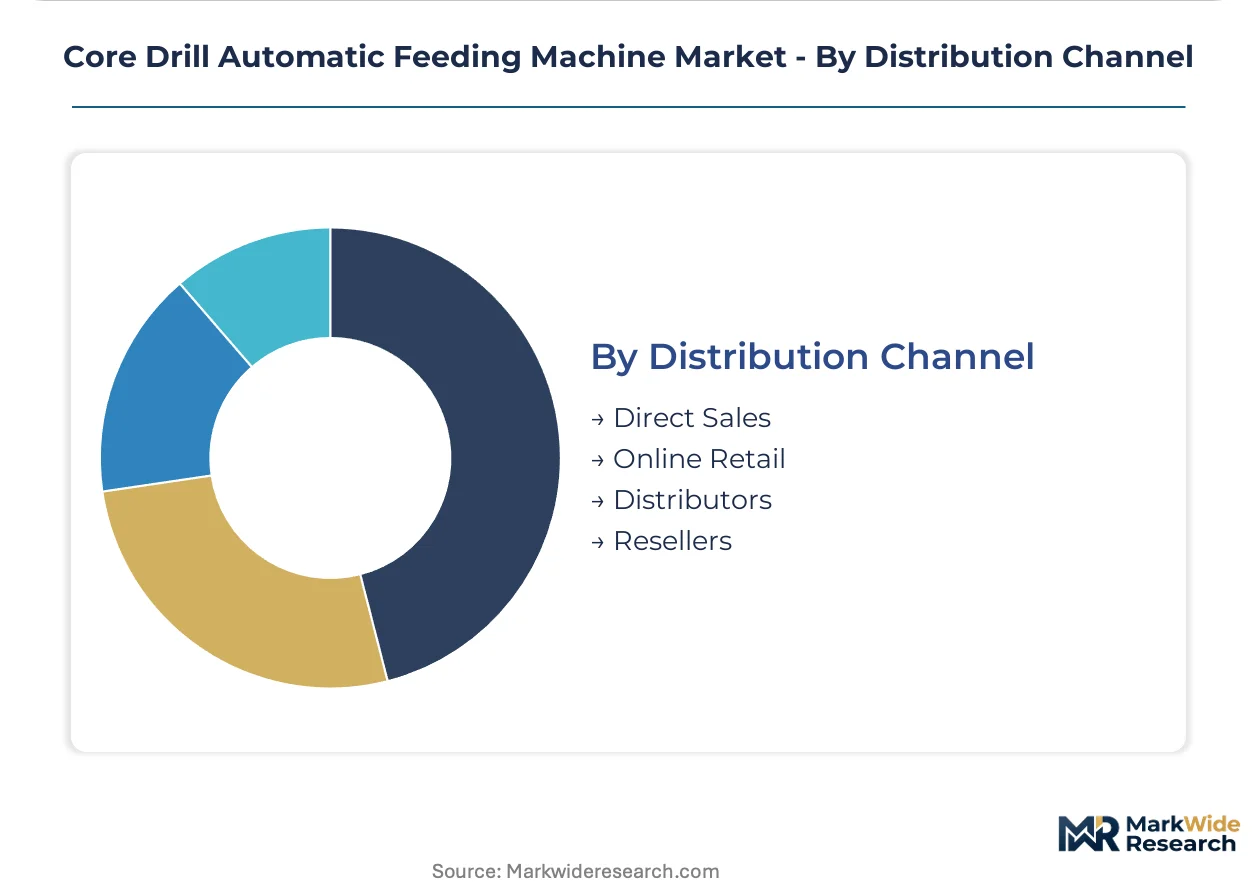
Distribution Channel:
Customer type fragmentation separates capital-purchase mining operators from operational-expense construction contractors.
- Direct Sales:OEM relationships serve large mining houses and infrastructure contractors with customized specifications and captive service contracts. Hilti Corporation leverages this channel for North American infrastructure contracts with bundled diamond tooling provisioning.
- Distributors:Regional equipment houses stock standardized configurations for mid-tier construction and rental fleet operators. Australian mining services procurement flows heavily through this channel for rapid replacement parts access.
- Online Retail:E-commerce platforms capture small contractor and maintenance department purchases for consumables and portable units.
- Resellers:Secondary market channels move refurbished equipment into price-sensitive developing markets.
Direct sales leads volumes today; distributor channels are gaining share fastest as rental fleet expansion fragments procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mining engineers and geotechnical specialists concentrate in Australia, Germany, and the United States, anchoring demand for precision drilling automation. Equipment specification varies sharply by regulatory environment and substrate conditions.
United States
MSHA continuous miner standards mandate automatic feed mechanisms in coal and hard-rock extraction, accelerating replacement cycles in Appalachian and Powder River Basin operations. OSHA silica exposure limits compress procurement timelines for dust-contained architectures. Houston and Denver house the largest mining services procurement clusters.
Germany
Precision manufacturing corridors in Baden-Württemberg and Bavaria specify electric automatic feeding systems for indoor demolition and core sampling contracts. REACH substance restrictions and F-Gas Regulation phase-downs eliminate hydraulic alternatives from certified supply chains. Stuttgart-based equipment rental fleets drive specification of brushless DC architectures.
Australia
Underground hard-rock operations in Western Australia and Queensland specify pneumatic feeding architectures for methane compliance in tunnelling projects. Surface deposit depletion forces deeper extraction, extending drill duty cycles. Perth anchors the largest mining equipment procurement and maintenance services cluster.
China
Infrastructure rehabilitation and high-rise construction in Yangtze River Delta and Pearl River Delta metros absorb vertical drill configurations for reinforced concrete penetration. GB standards and local emissions enforcement favor electric systems in urban cores. Shenzhen and Shanghai equipment distributors stock automatic feeding architectures for mid-tier contractors.
Sweden
Scandinavian tunnelling projects specify pneumatic systems for explosive atmosphere compliance in Stockholm and Oslo metro extensions. Mining automation R&D concentrates in Kiruna and Luleå, testing sensor-drill convergence architectures. CE marking requirements for emergency stop integration shape product design for Nordic market access.
Core Drill Automatic Feeding Machine Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive distribution networks. Tier separation runs from premium-positioned integrated solution providers to price-competitive component fabricators. Three archetypes dominate: diamond tooling specialists with backward integration into equipment, pneumatic system architects with mining captive relationships, and electric drive innovators with rental fleet specifications. Capacity expansion and sensor-drill convergence partnerships represent the dominant competitive moves.
Among European diversified industrial groups, Hilti Corporation and Atlas Copco exemplify the premium-tier archetype with integrated tooling and equipment portfolios. Epiroc AB anchors the pneumatic-specialist position within underground mining automation. These three occupy positions that reflect divergent technology bets: electric urban construction, compressed-air explosive atmosphere compliance, and sensor-integrated predictive service models.
| Leading Market Players |
|---|
| Hilti Corporation |
| Atlas Copco |
| Husqvarna Group |
| Robert Bosch Tool Corporation |
| CS Unitec |
| BAIER |
| Golz |
| Scientific Drilling International |
| Epiroc AB |
| Others |
Value Chain & Pricing Dynamics
EU REACH substance restrictions and F-Gas Regulation phase-down schedules gate qualified supply for hydraulic fluid formulations, reserving premium-tier pricing access to manufacturers with reformulated lubrication systems and CE marking compliance. This environmental mandate compresses margins for non-compliant fabricators while rewarding integrated players with captive chemistry capabilities and certified component sourcing.
Pricing Analysis
Bundled equipment-as-a-service contracts with maintenance and consumable provisioning are displacing unbundled capital purchases across Australian mining services and US infrastructure rehabilitation markets. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated predictive service models from basic pneumatic architectures and rental fleet specifications. Cost compression in economy tiers is intensifying because distributor channel expansion fragments procurement relationships and pressures aftermarket revenue pools. Mid-tier contractors exhibit highest price sensitivity due to project duration uncertainty, while large mining houses with captive service contracts demonstrate lowest sensitivity to upfront equipment costs.
Supply Chain Analysis
Regional distribution centers in Perth, Houston, and Stuttgart anchor hub-and-spoke patterns that position finished equipment and replacement parts within rapid-response distance of mining and construction clusters. Manufacturing concentration centers on Germany, Sweden, and the United States for precision electric drives and control architectures, while pneumatic component fabrication concentrates in Australia and Scandinavia for explosive atmosphere compliance. Synthetic diamond supply for core bit production draws from limited production clusters, exposing margins to raw material volatility and geopolitical friction. Single-source vulnerability in sealed component specifications for pneumatic systems threatens fleet availability during supply disruptions. Distribution runs through OEM direct relationships for large mining houses and specialized distributors for mid-tier rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification for dust-contained automatic feeding systems with integrated silica containment is shifting procurement toward premium-tier electric and pneumatic architectures with certified compliance documentation.
For Market Incumbents: To counter rental channel expansion fragmenting traditional direct-sales relationships, Hilti Corporation and Epiroc AB should deepen backward integration into diamond tooling and pneumatic component supply respectively, while accelerating sensor-drill convergence partnerships that enable predictive maintenance contracts with performance-guaranteed service models. Certification investment in CE marking and MSHA approval processes for modified control architectures defends market access against regulatory timeline compression. For New Entrants and Emerging Players: Capture white space in European research laboratory expansion for precision electric systems with closed-loop penetration control, where materials science funding growth outpaces established supplier focus. Local content rule arbitrage in resource-rich economies offers assembly partnership opportunities that satisfy regional procurement thresholds without full manufacturing footprint commitment. Equipment-as-a-service models with bundled maintenance provisioning provide the most penetrable go-to-market angle for mid-tier contractors favoring operational expense treatment. For Investors and Strategic Acquirers: Valuations sit cheapest among component fabricators without captive distribution networks or certified regulatory compliance, particularly those serving price-sensitive developing market rental tiers. Long-term viability over the projection horizon favors diversified industrial conglomerates with integrated tooling and equipment portfolios capable of absorbing sensor-drill convergence architectures. The signal to monitor is MSHA and EU Machinery Directive enforcement intensity accelerating replacement cycles beyond natural equipment depreciation schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Drill Convergence Partnerships | Integration of real-time penetration analytics with automatic feed control enables predictive maintenance contracts in Australian mining operations. |
| Backward Integration into Diamond Tooling | Hilti Corporation's captive supply of diamond-impregnated core bits sustains premium positioning in North American infrastructure contracts. |
| CE Marking Compliance Investment | Emergency stop integration and two-hand control architectures secure European market access against Machinery Directive enforcement. |
| Equipment-as-a-Service Model Expansion | Bundled maintenance and consumable provisioning captures mid-tier contractors shifting from capital purchase to operational expense treatment. |
| Local Content Assembly Partnerships | Regional assembly satisfies domestic procurement mandates in resource-rich economies without full manufacturing footprint commitment. |
Study Parameters
Multiple input streams — technical specification databases, regulatory filing repositories, and equipment procurement records — were reconciled through structured primary interviews with maintenance directors at mining operations, plant engineers at construction contractors, OEM procurement teams, and aftermarket service heads, combined with secondary validation against customs and trade data, SEC filings, and MSHA enforcement documentation. Bottom-up segment sizing and top-down market triangulation were cross-checked for consistency across vertical drill, horizontal drill, and handheld configurations.
Data-stream reconciliation anchored volume and value outputs across the analysis window through modeling of technology type, end-use application, mounting configuration, and distribution channel dimensions. CAGRs were derived from regression analysis of replacement cycle compression, regulatory mandate timelines, and automation penetration curves specific to underground mining and precision construction verticals. Pneumatic system adoption rates in Australian tunnelling projects and electric system specification in German indoor demolition contracts served as industry-specific forecast calibration inputs.
Regulatory enforcement delays, raw material supply disruptions, and carbon border adjustment mechanism implementation scope are the dominant revision risks that could compress or extend projected replacement cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Jackhammer Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
CNC Router Market