
 Barn Door Hardware Market | 2026-2036
Barn Door Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Barn Door Hardware Market Analysis
Aftermarket service revenue from track maintenance and component replacement is narrowing as manufacturers shift toward bundled hardware-plus-installation offerings. ASSA ABLOY leverages its architectural access control portfolio to cross-sell sliding systems into commercial fit-outs. Häfele anchors European distribution through specialized cabinetry and interior hardware channels. P C Henderson competes on heritage engineering credibility in heavy-duty industrial track applications.
Barn door hardware comprises the mechanical assemblies—rollers, hangers, tracks, floor guides, and stopping mechanisms—that enable horizontal sliding operation of panel doors weighing from fifty to over five hundred pounds, typically fabricated from cold-rolled steel or extruded aluminum with powder-coated or plated finishes for corrosion resistance. Sliding track systems command the dominant share of product type revenue as architects specify concealed top-mount profiles for minimalist interiors. Steel material grades retain preference in commercial and industrial specifications where deflection tolerances are tightest. Residential application volumes lead absolute consumption though commercial spaces generate higher per-project values through custom solutions and fire-rated assemblies.
ASTM International publishes load-test protocols for sliding door hardware while ANSI/BHMA standards grade cycle-life performance for residential and commercial grades. The EPA regulates volatile organic compound emissions from powder-coating and plating processes, pushing finishers toward water-based alternatives. Stakeholders must monitor evolving building code adoptions of ADA-compliant low-force operation requirements as jurisdictions update accessibility mandates.
Market Dynamics
Residential renovation cycles in the United States are compressing procurement timelines for barn door hardware, forcing distributors to carry deeper inventories of concealed track systems and soft-close mechanisms to capture same-day contractor demand.
Growth Catalysts
- ASTM Load-Test Certification:Architects in commercial fit-outs increasingly specify ASTM-certified hardware for liability protection, pulling premium-grade steel track systems into multi-family housing specifications.
- Powder-Coating Water-Based Transition:EPA volatile organic compound regulations are accelerating capital investment in water-based finishing lines, enabling domestic manufacturers to bypass import tariffs on plated components.
- Texas and California Housing Permits:Single-family permit velocity in these states concentrates demand for barn door kits in new construction, with developers standardizing sliding systems to maximize usable floor area.
Market Restraints
- Cold-Rolled Steel Input Volatility:Mill pricing fluctuations for 1018 and 1045 steel grades compress hardware fabricator margins, particularly for small-batch custom track producers.
- Concentrated Roller Bearing Supply:Precision bearing sourcing from East Asian suppliers creates lead-time vulnerability for North American hardware assemblers during ocean freight disruptions.
- Fire-Rated Assembly Certification Cost:UL 10C testing requirements for commercial sliding door hardware impose five-figure certification barriers that exclude regional fabricators from institutional projects.
Strategic Opportunities
- ADA-Compliant Low-Force Hardware:Jurisdictions adopting updated accessibility mandates create specification pull for reduced-operating-force roller systems in public buildings.
- Smart Home Integration:Motorized barn door actuators with Wi-Fi connectivity represent unpenetrated white space in residential automation, with early adoption concentrated in California luxury retrofits.
- Bundled Installation Services:Hardware manufacturers capturing installation labor revenue can disintermediate independent contractors and improve project margin capture.
Industry Challenges
- Powder-Coating Technician Shortage:Water-based finishing line operation requires specialized training that vocational programs have not scaled to match EPA compliance timelines.
- Legacy Track Compatibility:Retrofit projects demand hardware that interfaces with non-standard door panel weights and thicknesses, complicating inventory planning for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barn Door Hardware Market |
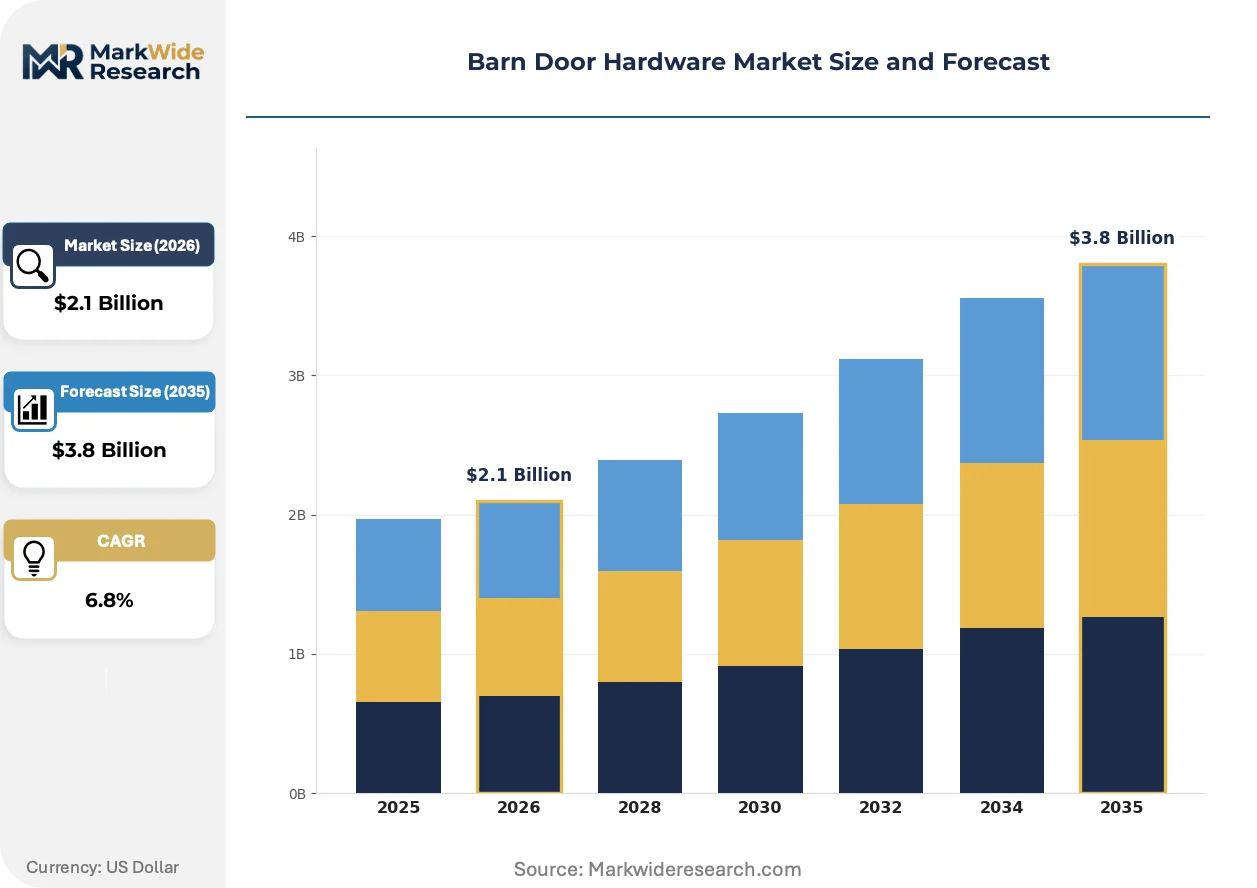
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Track Systems, Barn Door Kits, Accessories, Hardware Components Material: Steel, Aluminum, Wood, Composite Application: Residential, Commercial Spaces, Industrial Settings, Renovations Installation Type: Wall-Mounted, Ceiling-Mounted, Freestanding, Custom Solutions |
| Companies Covered | ASSA ABLOY, P C Henderson, Häfele, Homacer, Richelieu Hardware, Dormakaba, GEZE, Johnson Hardware, Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barn Door Hardware Market Emerging Trajectories
Concealed mounting systems and soft-close damping technologies are compressing the visual profile of barn door hardware, enabling architects to specify sliding panels in minimalist interiors where exposed industrial tracks would violate aesthetic constraints.
Extruded aluminum top-mount track profiles are collapsing the weight differential between residential and commercial-grade systems. High-end residential developers in California now specify 150-pound-capacity aluminum tracks previously reserved for light commercial use. The material shift enables longer unsupported spans without ceiling reinforcement, reducing installation labor by approximately one-third on typical room-divider applications.
EPA enforcement of volatile organic compound limits on powder-coating operations is forcing finishers toward water-based polyester alternatives. Small-batch hardware fabricators in Texas report 18-month compliance timelines to revalidate corrosion resistance under salt-spray protocols. The regulatory compression favors capitalized manufacturers with in-house coating lines over job-shop assemblers dependent on outsourced finishing.
Architects are unbundling hardware specification from general contractor procurement, creating direct relationships with specialty distributors for fire-rated and accessibility-compliant assemblies. This channel disintermediation concentrates in commercial office renovations in California, where liability exposure drives specification control upstream to design firms. Distributors responding with dedicated architectural specification support capture project-level margin premiums unavailable through traditional two-step distribution.
Barn Door Hardware Market Segmentation
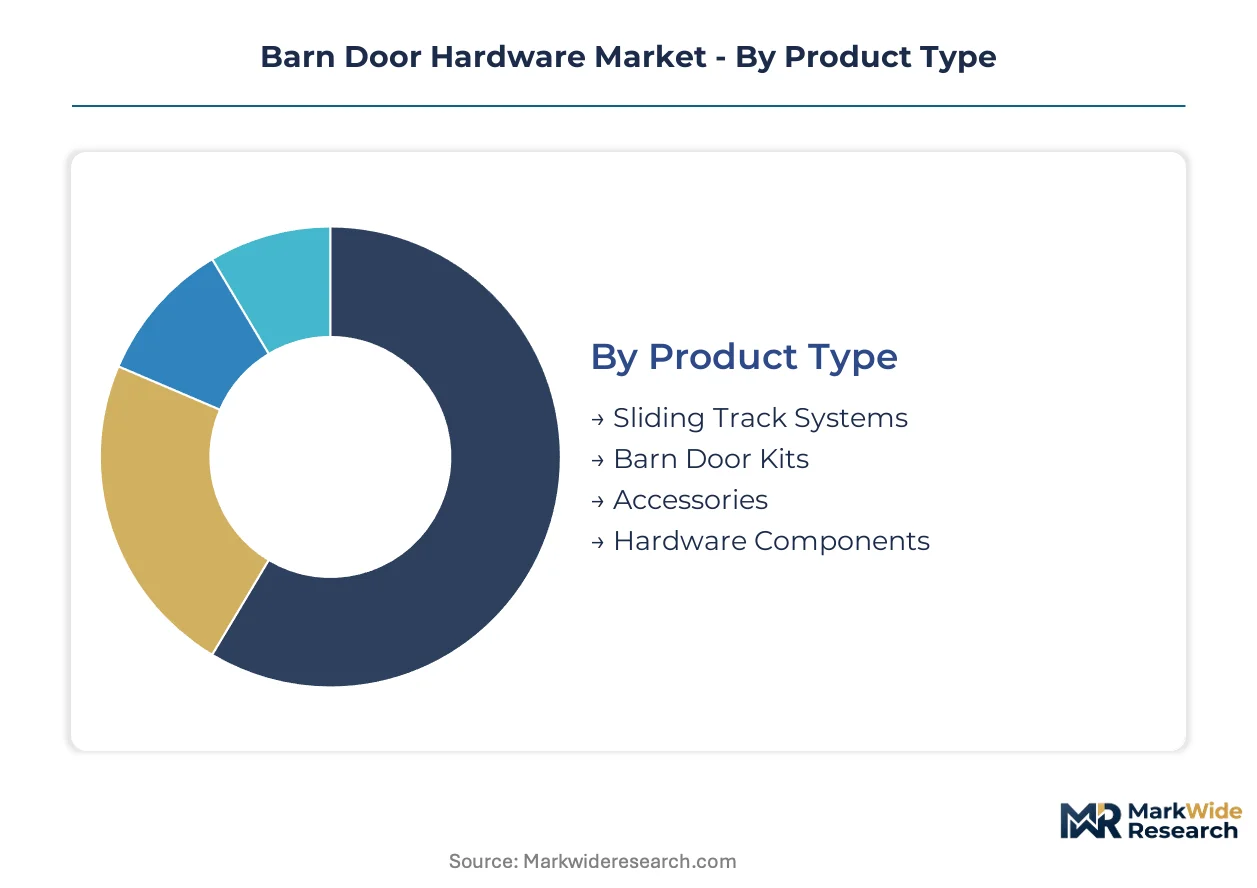
Barn door hardware segmentation reveals stark contrasts in procurement velocity: commercial fit-outs cycle hardware specifications over multi-year renovation timelines while residential renovation projects compress decision windows to days. Understanding these rhythm differences shapes inventory positioning and specification support investments.
Product Type:
Sliding track systems turn inventory fastest through distributor channels, while custom hardware components sit longest awaiting project-specific fabrication. Barn door kits and accessories occupy intermediate velocity tiers depending on finish standardization.
- Sliding Track Systems:Concealed top-mount aluminum and steel profiles enable horizontal panel movement across residential room dividers and commercial office partitions. Texas and California housing markets specify these systems in volume for space-maximizing new construction where square footage premiums drive sliding over swing-door alternatives.
- Barn Door Kits:Pre-assembled roller, hanger, and track combinations reduce contractor field time through standardized component matching. Residential renovation contractors in concentrated metropolitan markets procure these for same-day installation completion, compressing distributor order-to-delivery expectations.
- Accessories:Floor guides, soft-close dampers, and stopping mechanisms complete functional assemblies.
- Hardware Components:Individual rollers, hangers, and brackets for custom fabrication or replacement.
Sliding track systems anchor the volume base while barn door kits gain share at the steepest rate.
Material:
Cost tier stratification runs from commodity-grade aluminum through premium alloy steel specifications, with finish durability separating price bands more than base material expense.
- Steel:Cold-rolled 1018 and 1045 grades deliver deflection resistance for commercial and industrial load-bearing specifications. ASTM load-test certification requirements pull premium steel into multi-family housing where architect liability protection drives grade specification above residential minimums.
- Aluminum:Extruded top-mount profiles collapse weight differentials between residential and light-commercial applications. California luxury residential developers now specify 150-pound-capacity aluminum tracks previously reserved for commercial use, enabling longer unsupported spans without ceiling reinforcement.
- Wood:Decorative fascia and traditional aesthetic applications.
- Composite:Corrosion-resistant alternatives for humid environments.
Steel retains the revenue base while aluminum climbs the fastest across specification volumes.
Application:
Customer type segmentation separates high-volume, low-margin residential procurement from project-based commercial specification with extended sales cycles and custom engineering requirements.
- Residential:Single-family and multi-family housing installations dominate absolute consumption volumes. Texas and California permit velocity concentrates demand for barn door hardware in new construction, with developers standardizing sliding systems to maximize usable floor area per unit.
- Commercial Spaces:Office fit-outs, hospitality, and retail generate higher per-project values through fire-rated assemblies and ADA-compliant low-force operation specifications. California commercial office renovations drive direct architect-to-distributor relationships for liability-controlled specification.
- Industrial Settings:Heavy-duty track applications for warehouse and manufacturing facilities.
- Renovations:Retrofit projects demanding legacy compatibility with non-standard panel weights and thicknesses.
Residential anchors absolute consumption while commercial spaces expand most quickly in value per project.
Installation Type:
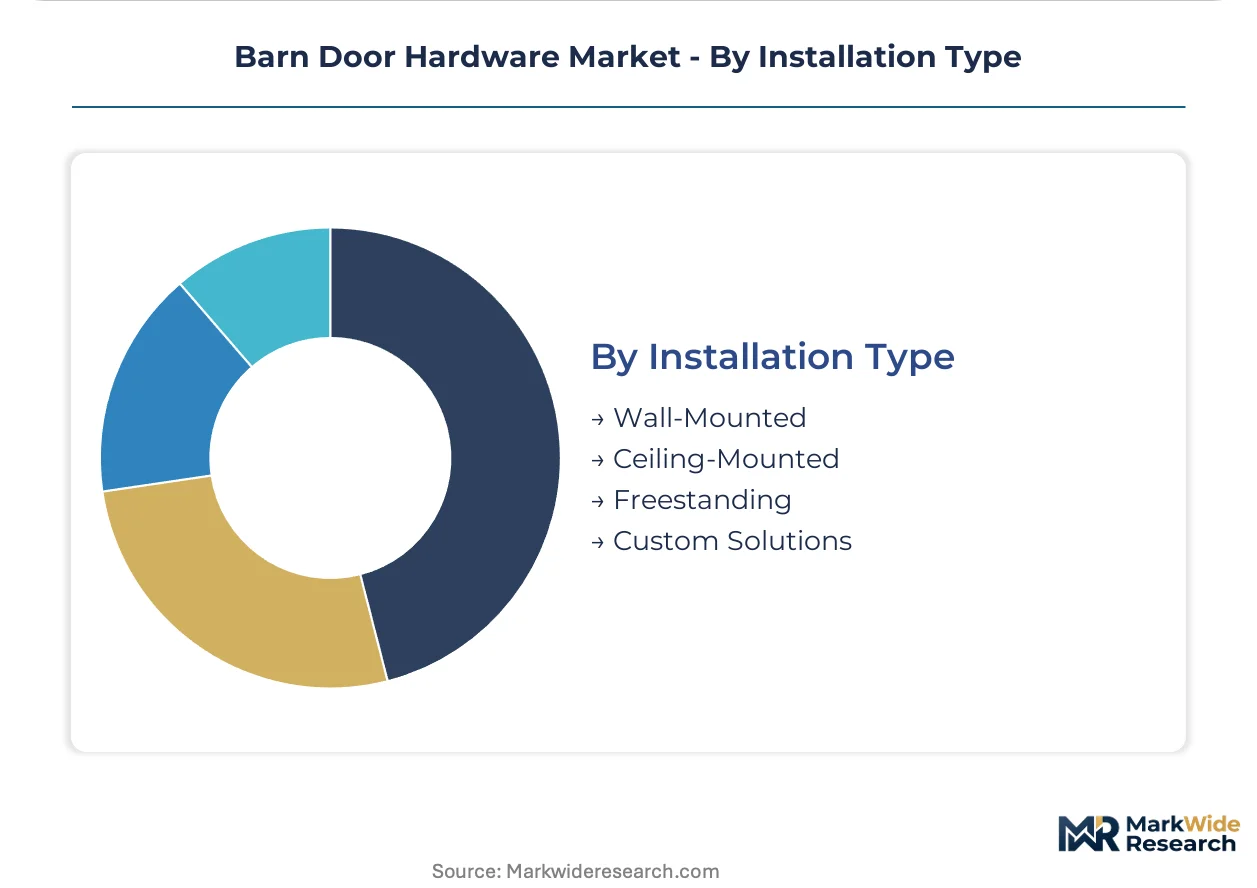
Supply concentration clusters around wall-mounted standardization, with ceiling-mounted and custom solutions requiring specialized engineering support and elongated procurement timelines.
- Wall-Mounted:Standard bracket-to-stud attachment dominates residential contractor preference for installation speed and structural predictability. Distributors carry deeper inventories of wall-mounted concealed track systems to capture compressed renovation procurement timelines.
- Ceiling-Mounted:Top-hung configurations eliminate floor track requirements for minimalist aesthetics and accessibility compliance. Aluminum material shift enables longer unsupported spans, reducing installation labor by approximately one-third on typical room-divider applications.
- Freestanding:Self-supporting frame systems for non-structural wall applications.
- Custom Solutions:Project-specific engineering for non-standard openings, curved tracks, or integrated automation.
Wall-mounted systems anchor the installation base while ceiling-mounted configurations gain specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in North American and European industrial corridors where cold-rolled steel supply chains and powder-coating infrastructure overlap. Housing permit velocity and commercial renovation cycles dictate regional demand rhythms, with regulatory enforcement of VOC emissions and accessibility standards reshaping competitive positioning.
United States
Texas and California housing markets concentrate new construction demand for space-maximizing sliding systems in multi-family units. EPA enforcement of volatile organic compound limits on powder-coating operations pushes finishers toward water-based alternatives, compressing compliance timelines for small-batch fabricators. Dallas-Fort Worth and Houston industrial corridors host steel fabrication clusters serving regional distributor networks.
Germany
Commercial fit-out specifications in Berlin and Munich pull premium-grade track systems for office renovation projects. REACH regulations govern chemical composition in plated finishes, driving domestic manufacturers toward compliant coating technologies. The Ruhr industrial region anchors steel processing and hardware assembly operations serving Central European distribution channels.
China
Precision bearing supply chains in Zhejiang and Jiangsu provinces feed global hardware assembly operations, though ocean freight disruptions create lead-time vulnerability for North American customers. GB standards for sliding door load-bearing capacity apply to domestic market products. Guangdong Province extrusion facilities produce aluminum track profiles for export markets.
United Kingdom
Herage engineering credibility commands premium positioning in London commercial restoration projects specifying heavy-duty industrial track applications. Building regulations mandate accessibility compliance for public building renovations, creating specification pull for low-force operation hardware. Midlands manufacturing clusters supply fabricated components to national distributor networks.
Canada
Residential renovation contractors in Toronto and Vancouver metropolitan areas procure concealed track systems for same-day installation completion. Health Canada regulations align with EPA VOC emission frameworks for imported finished hardware. Quebec distribution hubs serve cross-border procurement from US manufacturer networks.
Barn Door Hardware Market Vendor Landscape
Diversified architectural access conglomerates and specialized hardware fabricators split the market along specification depth and channel control vectors. Tiered competitive positioning separates capitalized manufacturers with in-house finishing lines from job-shop assemblers dependent on outsourced coating. Two dominant archetypes emerge: full-line building product suppliers leveraging cross-selling infrastructure, and focused track-system specialists competing on engineering credibility. Geographic expansion through distributor partnerships and backward integration into captive steel processing represent the primary competitive moves reshaping margin structures.
Within the diversified conglomerate tier, ASSA ABLOY and Stanley Black & Decker exemplify scale-driven players anchoring specification influence through architectural access control portfolios. Among specialized fabricators, P C Henderson occupies a position tied to heritage engineering credibility in heavy-duty industrial applications, while Häfele represents European distribution-focused specialists penetrating cabinetry and interior hardware channels. Johnson Hardware and Homacer sit within the mid-market fabrication segment serving residential renovation contractors through standardized kit offerings.
| Leading Market Players |
|---|
| ASSA ABLOY |
| P C Henderson |
| Häfele |
| Homacer |
| Richelieu Hardware |
| Dormakaba |
| GEZE |
| Johnson Hardware |
| Stanley Black & Decker |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Zhejiang Province extrusion facilities is compressing aluminum track pricing globally, forcing North American distributors to absorb freight volatility while domestic steel fabricators exploit localized supply security premiums. This utilization imbalance creates divergent margin trajectories across material tiers and reshapes procurement bargaining power.
Pricing Analysis
Aftermarket parts and maintenance service revenue drives lifetime value capture as manufacturers bundle installation labor into hardware offerings. Three-tier pricing structure across premium ASTM-certified steel, standard aluminum residential kits, and economy-grade imported components stratifies the market. Cost compression in cold-rolled steel grades intensifies because mill pricing volatility squeezes small-batch custom fabricator margins. Residential renovation contractors exhibit highest price sensitivity, while commercial architects specifying fire-rated assemblies demonstrate lowest sensitivity due to liability-driven quality mandates.
Supply Chain Analysis
Export-control restrictions on precision bearing technology from East Asian suppliers create sourcing friction for North American hardware assemblers. Production concentrates in China for aluminum extrusions and precision components, in Germany for engineered steel systems, and in the United States for powder-coated finished goods. Supply chains draw from cold-rolled steel mills, extruded aluminum profiles, and precision roller bearings as core inputs. Single-source vulnerability in ocean freight lanes connecting Zhejiang to Long Beach generates lead-time risk during port congestion. Distribution runs through two-step wholesale networks serving contractor and architectural specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as architect specification control disintermediates general contractors, creating niche entry points for specialized distributors with fire-rated and ADA-compliant assembly expertise.
For Market Incumbents: Entrench specification influence by deepening architectural specification support teams in California commercial renovation corridors. Capture installation labor revenue through bundled hardware-plus-service offerings to disintermediate independent contractors. Cold-rolled steel input volatility threatens margin stability; backward integration into captive steel processing secures supply predictability.
For New Entrants and Emerging Players: Pursue motorized barn door actuators with Wi-Fi connectivity as unpenetrated white space in California luxury residential retrofits. Target ADA-compliant low-force roller systems in public building renovations as jurisdictions update accessibility mandates. Go-to-market through direct architect relationships bypasses traditional two-step distribution concentration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based finishing line transitions as EPA compliance timelines compress. Long-term viability favors capitalized manufacturers with in-house coating infrastructure over job-shop assemblers dependent on outsourced finishing. Acquisition targets include regional fabricators with established UL 10C fire-rated certifications. Signal to watch: Texas and California housing permit velocity as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Transition | EPA VOC compliance enables domestic manufacturers to bypass import tariffs on plated components. |
| Architectural Specification Support Investment | Direct designer relationships capture project-level margin premiums in California commercial fit-outs. |
| Installation Service Bundling | Hardware-plus-labor offerings disintermediate contractors and improve margin capture per project. |
| ADA-Compliant Product Development | Low-force roller systems address updated accessibility mandates in public building renovations. |
| Smart Home Integration Partnership | Motorized actuator development penetrates California luxury residential automation retrofit demand. |
Methodological Framework
Initial hypotheses were tested against primary input from hardware fabricator operations directors, architectural specification consultants, distributor procurement managers, and residential renovation contractors and refined through secondary validation. Primary fieldwork combined structured interviews with channel stakeholders and facility observations across Texas and California production clusters. Secondary sources included ASTM International certification databases, EPA enforcement records for VOC compliance, housing permit filings from Texas and California state agencies, and customs trade data for bearing and aluminum profile imports. Bottom-up demand modeling triangulated against top-down market sizing.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, application category, and installation configuration. CAGRs derived from trajectory analysis of housing permit cycles, commercial renovation spend patterns, and regulatory adoption curves for accessibility standards. Industry-specific inputs incorporated powder-coating capacity utilization rates and cold-rolled steel mill pricing indices.
Macroeconomic conditions sit as an overlay; deviation in residential construction spend and ocean freight rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding EPA compliance timelines and ASTM certification adoption rates. Material shifts in fire-rated assembly certification requirements or concentrated bearing supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Floor Screeds Market